
 Mobile Payment Security Market | 2026-2036
Mobile Payment Security Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Payment Security Market Outlook
Retail banking is hardening its defenses against real-time fraud as contactless transaction volumes surge across merchant networks. Visa leverages its tokenization infrastructure to anchor security standards across issuer-processor relationships. Mastercard competes through biometric authentication investments that extend its fraud-prevention reach into emerging markets. Square (Block Inc.) specializes in point-to-end encryption for small-business payment flows, occupying a distinct niche between enterprise-grade and consumer-facing security layers.
Mobile payment security encompasses the cryptographic protocols, authentication frameworks, and threat-detection systems that protect financial transactions initiated from smartphones, tablets, and wearable devices. These systems typically employ AES-256 encryption, token vaults, and behavioral biometrics to verify payer identity while masking primary account numbers from merchants and intermediaries. Tokenization now leads technology adoption as issuers replace static card numbers with dynamic credentials, while cloud-based deployment grows fastest among mid-tier fintechs seeking elastic fraud-scoring capacity without capital-intensive infrastructure. Biometric authentication captures concentrated margin pools as hardware-software integration costs sustain premium pricing for liveness-detection and multimodal verification engines.
PCI DSS mandates from the payment card industry, GDPR data-protection requirements in Europe, and PSD2 strong-customer-authentication rules enforced by EU national regulators collectively shape product roadmaps and market-access thresholds for security vendors. The US Federal Trade Commission and state-level attorneys general add enforcement layers through data-breach notification statutes that accelerate enterprise procurement cycles. Stakeholders must monitor regulatory divergence between EMVCo token specifications and emerging central-bank digital currency security frameworks as these standards determine interoperability investments and geographic expansion feasibility.
Market Dynamics
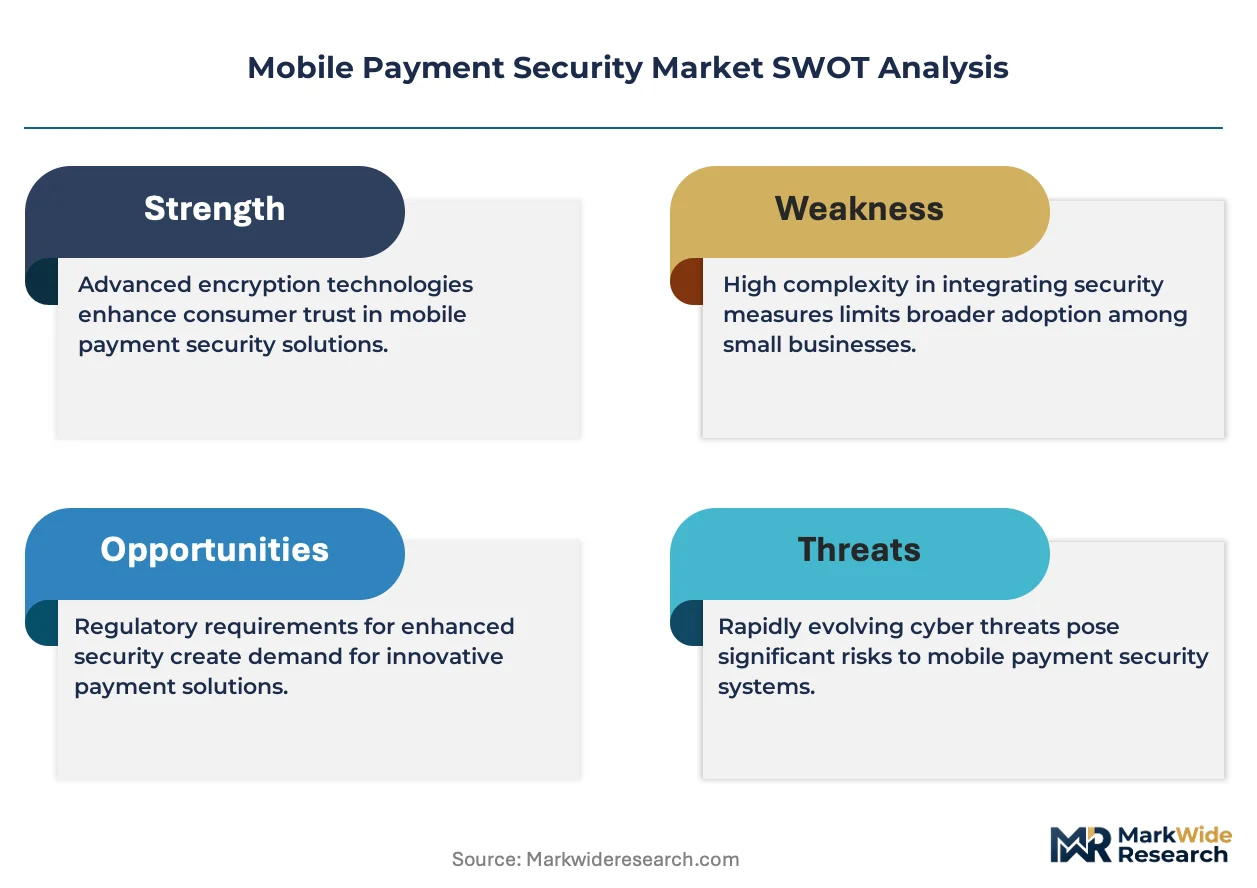
Tokenization infrastructure investments are restructuring procurement priorities across issuer-processor relationships as PCI DSS 4.0 mandates force hardware refresh cycles. Banks and fintechs now prioritize dynamic credential vaults over static encryption, compressing vendor selection timelines and consolidating procurement around integrated platform providers.
Growth Catalysts
- PCI DSS 4.0 Mandates:The payment card industry's updated data security standards require enhanced encryption protocols, forcing merchant acquirers and issuers to upgrade tokenization infrastructure before audit deadlines.
- Contactless Transaction Surge:Transit authorities and quick-service restaurant chains are deploying tap-to-pay at scale, expanding the attack surface that security vendors must protect.
- Behavioral Biometrics:Keystroke dynamics and gait analysis are integrating with mobile SDKs to reduce false-decline rates without adding friction to checkout flows.
Market Restraints
- Semiconductor Supply Concentration:Secure element manufacturing concentrates in Taiwan and South Korea, creating vulnerability for hardware-backed authentication vendors during geopolitical disruptions.
- EMVCo Specification Fragmentation:Divergent token vault architectures between US and EU implementations force vendors to maintain dual certification tracks, inflating R&D overhead.
- Legacy POS Integration Costs:Small merchants face prohibitive capex to retrofit countertop terminals with point-to-point encryption, slowing security standard adoption at the long tail.
Strategic Opportunities
- India UPI Security Layer:The National Payments Corporation of India's real-time settlement protocol lacks built-in tokenization, creating white space for third-party vault providers to anchor issuer partnerships.
- Central Bank Digital Currency Convergence:China's e-CNY and Brazil's Drex pilots require hardware-software security stacks that bridge existing mobile wallet infrastructure with sovereign currency protocols.
- Embedded Insurance Bundling:Cyber coverage for transaction fraud is attaching to merchant acquiring contracts as a value-add, opening recurring revenue streams for security platform vendors.
Industry Challenges
- Post-Quantum Cryptography Talent Scarcity:Lattice-based algorithm implementation requires specialized cryptographers that incumbent vendors struggle to recruit against fintech compensation packages.
- Cross-Border Certification Timelines:EMVCo, PCI SSC, and national regulators operate non-harmonized approval processes that delay product launches by 8-14 months in key markets.
- SDK Fragmentation Across OEMs:Samsung Knox, Apple Secure Enclave, and Google Titan M require distinct integration paths, multiplying QA overhead for biometric authentication vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Payment Security Market |
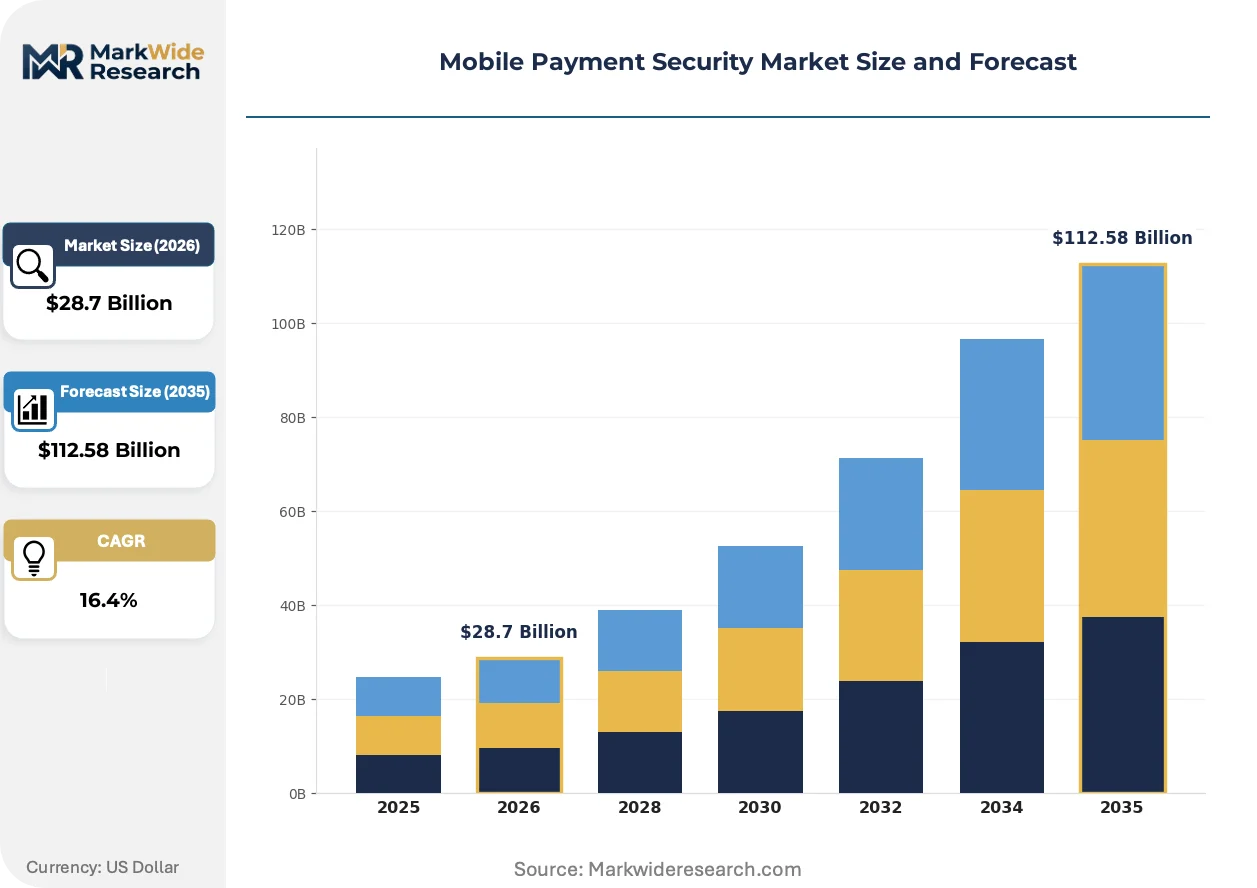
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tokenization, Encryption, Biometric Authentication, Two-Factor Authentication End User: Retailers, Financial Institutions, E-Commerce Platforms, Service Providers Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Solution: Software Solutions, Hardware Solutions, Integrated Solutions, Managed Services |
| Companies Covered | Stripe, Square (Block Inc.), Visa, Ripple, Fiserv, Mastercard, PayPal, Konsentus, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Payment Security Market Strategic Shifts
Security architecture is converging around cloud-native fraud scoring that decouples detection from transaction processing. Vendors are racing to embed machine learning at the network edge while regulators tighten authentication mandates.
Token vault technology is consolidating issuer-processor relationships around a smaller set of certified providers. Mid-tier banks are abandoning in-house credential management for hosted vault services to accelerate PCI DSS compliance. This shift is compressing the vendor landscape and elevating platform-scale players that can absorb audit liability.
GDPR Article 32 enforcement is mandating encryption-at-rest for biometric templates stored on EU servers. Payment service providers must now segregate fingerprint and facial recognition data within jurisdictional boundaries. German and French regulators are conducting sector-wide audits that accelerate procurement of localized tokenization infrastructure.
Merchant acquiring contracts are unbundling fraud liability from processing fees as risk-aware pricing penetrates the mid-market. ISOs and payment facilitators now offer tiered security packages that shift chargeback exposure to the vendor. This model is spreading fastest among US e-commerce platforms serving high-risk verticals.
Mobile Payment Security Market Segmentation
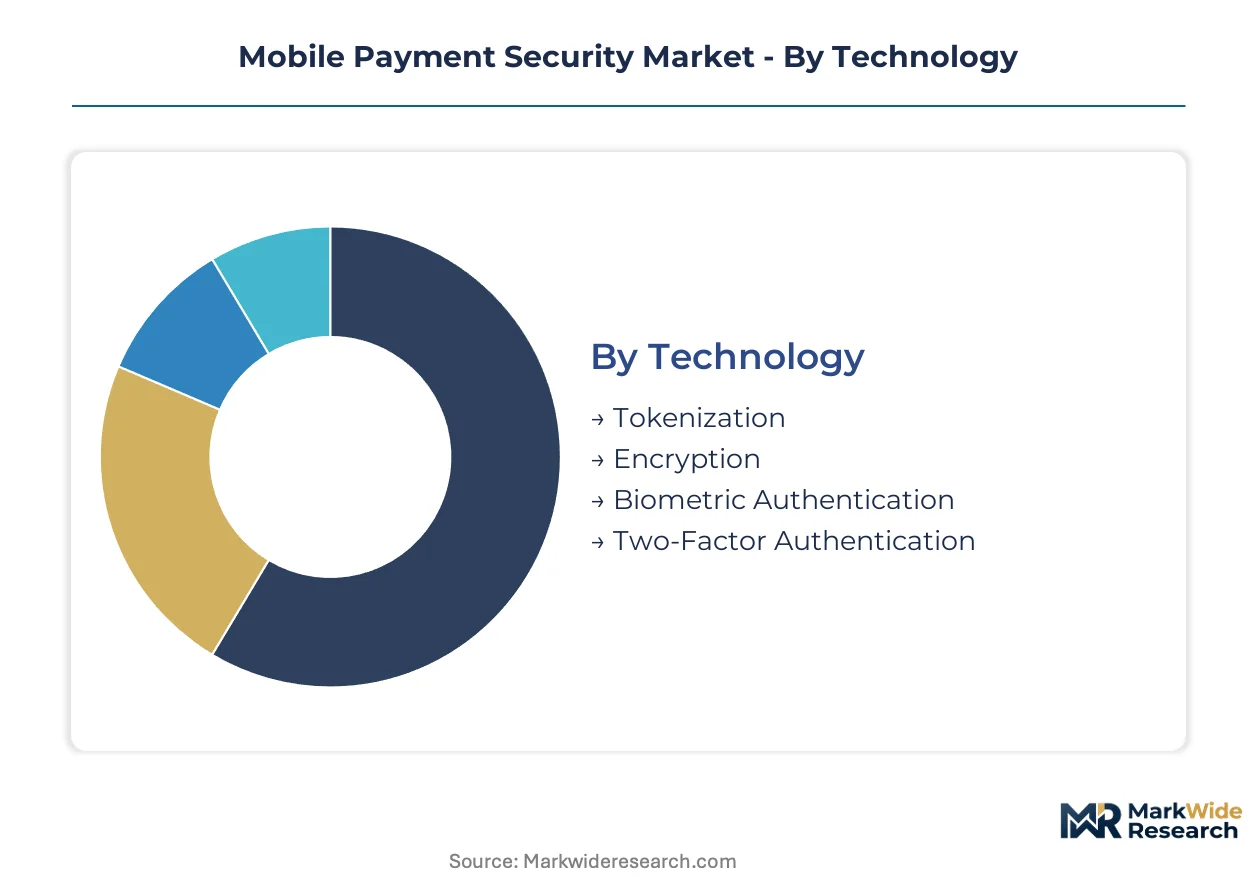
Security procurement in mobile payments diverges sharply by technical architecture and operational maturity. Buyers prioritize tokenization for PCI DSS alignment, cloud deployment for elasticity, and integrated platforms to consolidate vendor relationships.
Technology:
Technology selection hinges on compliance deadlines and fraud-loss exposure, with tokenization commanding premium budgets from tier-one issuers.
- Tokenization:Dynamic credential vaults replace static primary account numbers with single-use tokens. Financial institutions in the United States and India are consolidating procurement around EMVCo-certified providers to meet audit timelines.
- Encryption:AES-256 protocols protect data in transit and at rest. E-commerce platforms facing GDPR Article 32 enforcement are mandating end-to-end encryption for EU customer databases.
- Biometric Authentication:Fingerprint, facial recognition, and liveness detection reduce false-decline rates. Transit authorities in China are deploying multimodal verification for contactless fare collection.
- Two-Factor Authentication:SMS and app-based one-time passwords provide baseline protection. Small merchants adopt this tier for cost containment before upgrading to biometric layers.
Tokenization leads on scale; biometric authentication leads on momentum.
End User:
End-user segmentation reflects liability allocation and transaction velocity, with financial institutions absorbing the largest fraud-scoring infrastructure investments.
- Financial Institutions:Banks and card issuers deploy multi-layered security stacks spanning token vaults, behavioral analytics, and real-time authorization engines. Regulatory pressure from the FTC and state attorneys general accelerates refresh cycles.
- Retailers:Merchant acquirers integrate point-to-point encryption with POS terminals. Quick-service restaurant chains are retrofitting countertop hardware to support tap-to-pay surges.
- E-Commerce Platforms:Online merchants prioritize SDK-based fraud detection that embeds into checkout flows without redirect friction. High-risk verticals are unbundling cyber coverage from processing contracts.
- Service Providers:Payment facilitators and ISOs offer tiered security packages to downstream merchants. These intermediaries assume chargeback exposure to differentiate against commoditized processing rates.
Financial institutions dominate absolute spend; e-commerce platforms are expanding most quickly.
Deployment:
Deployment architecture determines capital efficiency and jurisdictional data sovereignty, with cloud models capturing mid-tier fintech procurement.
- Cloud-Based:Elastic fraud-scoring capacity scales with transaction volumes without hardware capex. German and French regulators are mandating localized EU data residency for biometric template storage.
- Hybrid:Sensitive credential operations remain on-premises while analytics shift to cloud. This model satisfies RBI data-localization requirements for Indian payment processors.
- On-Premises:Legacy vault infrastructure persists among tier-one issuers with dedicated security operations centers. These deployments carry higher audit liability but offer direct control over encryption key management.
- Multi-Cloud:Redundancy across AWS, Azure, and regional providers mitigates concentration risk. Brazil's Drex pilot programs are evaluating sovereign cloud integration for CBDC security layers.
Cloud-based deployment leads on scale; multi-cloud configurations are gaining share fastest.
Solution:
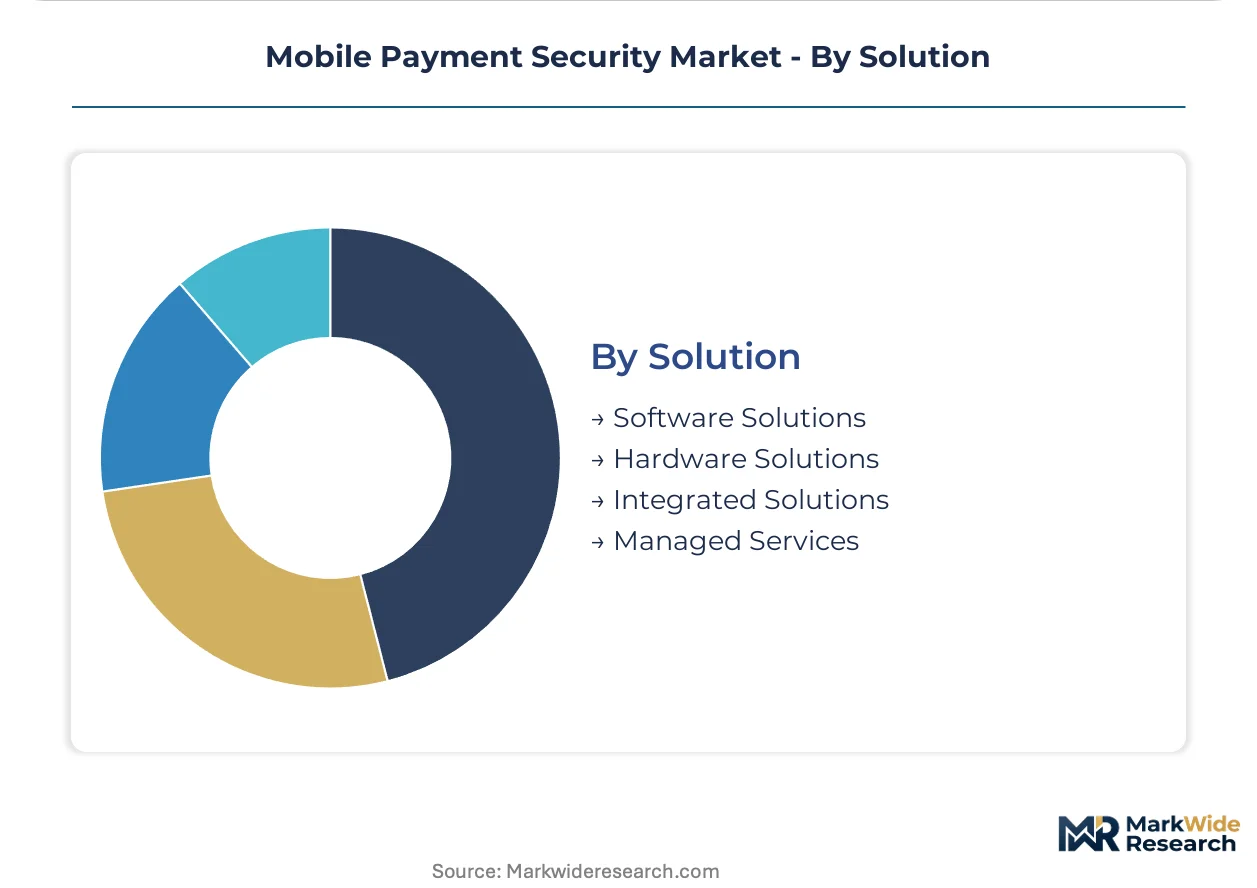
Solution packaging reflects buyer sophistication and internal security team capacity, with integrated platforms consolidating fragmented point products.
- Integrated Solutions:Unified platforms combine tokenization, encryption, and biometric modules under single vendor accountability. Mid-tier banks are abandoning in-house credential management for these hosted services.
- Managed Services:Outsourced security operations center monitoring shifts fraud-detection labor to vendors. This model penetrates fastest among US e-commerce platforms lacking dedicated infosec teams.
- Software Solutions:SDKs and APIs embed authentication into merchant applications without hardware dependencies. Transit authorities favor lightweight software for rapid mobile wallet integration.
- Hardware Solutions:Secure elements and dedicated cryptographic processors provide tamper-resistant key storage. Manufacturing concentration in Taiwan and South Korea creates supply vulnerability during geopolitical disruptions.
Integrated solutions lead on scale; managed services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting security infrastructure investment toward jurisdictions with clearer compliance pathways and lower certification friction. Vendors are relocating tokenization operations to exploit gaps between EMVCo audit timelines and national data-localization mandates.
United States
Contactless transaction volumes at quick-service restaurants and transit authorities are driving hardware refresh cycles for point-to-point encryption. The FTC enforces data-breach notification statutes that compress enterprise procurement timelines. New York and San Francisco anchor fintech security clusters where token vault providers concentrate engineering talent.
China
Digital yuan pilots require hardware-software security stacks bridging mobile wallet infrastructure with sovereign currency protocols. The People's Bank of China mandates localized cryptographic certification for CBDC transaction processing. Shenzhen and Hangzhou host concentrated development centers for secure element integration with transit payment systems.
India
UPI real-time settlement volumes are surging without built-in tokenization, creating procurement openings for third-party vault providers. The Reserve Bank of India enforces strict data-localization requirements for payment processor operations. Mumbai and Bangalore dominate fintech security partnerships as issuers seek hosted credential management.
Germany
GDPR Article 32 enforcement is mandating encryption-at-rest for biometric templates stored on EU servers. The Federal Financial Supervisory Authority conducts sector-wide audits that accelerate localized tokenization procurement. Frankfurt and Munich concentrate issuer-processor relationships around EMVCo-certified platform providers.
Singapore
Cross-border remittance corridors are demanding interoperable security frameworks for ASEAN digital wallet convergence. The Monetary Authority of Singapore coordinates regional standards alignment for biometric authentication in transit payments. The city-state hosts regional headquarters for vendors serving Southeast Asian merchant acquiring networks.
Mobile Payment Security Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to bridge token vault certification with cloud-native fraud-scoring capabilities. The market structures around three tiers: integrated platform providers absorbing audit liability, specialized biometric authentication vendors, and merchant-facing point-to-point encryption specialists. Technology licensing agreements between hardware secure element manufacturers and cloud infrastructure providers represent the primary consolidation mechanism. Geographic expansion into CBDC pilot jurisdictions and portfolio diversification into embedded cyber insurance products constitute the two prevailing competitive moves.
Among payment network operators, Visa and Mastercard exemplify the integrated platform archetype through their respective tokenization and biometric authentication infrastructures. Square (Block Inc.) occupies a distinct specialist position focused on small-business payment flows with point-to-end encryption offerings. Stripe represents the cloud-native tier with elastic fraud-scoring capacity targeting mid-market fintechs.
| Leading Market Players |
|---|
| Stripe |
| Square (Block Inc.) |
| Visa |
| Ripple |
| Fiserv |
| Mastercard |
| PayPal |
| Konsentus |
| Adyen |
| Others |
Value Chain & Pricing Dynamics
PCI DSS 4.0 audit deadlines are compressing procurement timelines for tier-one issuers, forcing accelerated vendor consolidation around EMVCo-certified platform providers and elevating pricing power for integrated token vault operators that can absorb compliance liability.
Pricing Analysis
Distributor margins for hardware-backed authentication modules typically run 15-25 percent before value-added integration services. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and transaction volume scale, with premium tiers commanding multiples for EMVCo-certified vaults with biometric liveness detection. Cost compression in the small-merchant segment intensifies because legacy POS retrofit capex remains prohibitive, while large financial institutions show lowest price sensitivity due to fraud-loss exposure and regulatory penalty risk.
Supply Chain Analysis
Dual-sourcing requirements for secure element chips now mandate qualified suppliers in both Taiwan and South Korea after geopolitical disruptions exposed single-source vulnerability. Manufacturing draws from concentrated semiconductor fabrication in Taiwan, South Korea, and Japan, with raw material dependencies spanning silicon wafers, cryptographic co-processors, and tamper-resistant packaging substrates. Tariff exposure on hardware imports into India and Brazil creates margin pressure for authentication vendors. Distribution runs through certified value-added resellers that handle EMVCo compliance documentation and localized certification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward premium specifications as PCI DSS 4.0 mandates eliminate budget-tier alternatives for tier-one issuers.
For Market Incumbents: Extend token vault certification coverage into CBDC pilot jurisdictions before specification divergence hardens. Deepen backward integration into secure element design to reduce Taiwan-South Korea supply concentration exposure. Anchor issuer relationships through managed services contracts that shift audit liability from banks to platform vendors.
For New Entrants and Emerging Players: Capture white space in India UPI third-party vault provision where built-in tokenization remains absent from the national real-time settlement protocol. Target mid-tier fintechs in Germany and France facing GDPR Article 32 enforcement deadlines for localized biometric template storage. Lead with cloud-native SDK deployment that bypasses hardware manufacturing dependencies.
For Investors and Strategic Acquirers: Asymmetric upside sits with biometric authentication specialists possessing hardware-software integration capabilities and EMVCo certification track records. Five-to-ten year viability hinges on post-quantum cryptography readiness as lattice-based algorithm standards mature. Watch EMVCo specification harmonization progress between US and EU token vault architectures as the inflection signal for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Expansion | Dual-track US-EU vault certification reduces R&D overhead for multinational issuers. |
| Post-Quantum Cryptography Investment | Lattice-based algorithm development attracts scarce cryptographer talent before standardization. |
| CBDC Security Stack Integration | China e-CNY and Brazil Drex pilots require bridging mobile wallet infrastructure with sovereign protocols. |
| Embedded Cyber Insurance Bundling | Fraud liability unbundling from processing fees creates recurring revenue for platform vendors. |
| Localized Data Residency Deployment | German and French GDPR enforcement mandates EU-server encryption-at-rest for biometric templates. |
Study Parameters
Coverage spans the United States, China, India, Germany, and Singapore, with primary inputs from each market combining interviews with fraud operations executives at tier-one issuers, payment processor procurement leads, EMVCo certification consultants, fintech CTOs, and merchant acquiring risk officers alongside secondary validation from PCI SSC disclosure filings, EMVCo specification documents, RBI and Bundesbank regulatory circulars, and hyperscaler cloud security capex disclosures. Bottom-up transaction volume modeling triangulates against top-down security software market sizing.
Rate-of-change decomposition separates volume growth from value-per-transaction evolution across the projection horizon. Segmentation dimensions modeled span technology architecture, deployment mode, end-user liability tier, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to PCI DSS compliance deadline impacts, contactless transaction velocity trajectories, and cloud-native fraud-scoring adoption patterns among mid-tier fintechs.
Regulatory timeline slippage, secure element supply disruption, and post-quantum cryptography standardization delays are the dominant revision risks to modeled forecasts. Deviation in EMVCo specification harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Czech Republic POS Terminals Market
Payments
Asia Pacific POS Terminal Market
Payments
M Commerce Payment Market
Payments
Subscription Billing Management Market
Payments
Digital Payment in Healthcare Market
Payments
Payment Service Provider Market
Payments
Online Charging System (OCS) Market
Payments
Payment Orchestration Platform Market
Payments
P2P Payment Market
Payments
Luxembourg POS Terminals Market
Payments
Digital Debit Market
Payments
Global Accounts Payable Automation Market
Payments
Japan Real Time Payment Market
Payments
Global Telecom Billing Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Face-Swiping Payment Market