
 China Lubricants Market | 2026-2036
China Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
China Lubricants Market Analysis
China's dual carbon goals is shifting lubricant procurement toward lower-viscosity, extended-drain formulations across state-owned transport fleets. PetroChina Company Limited leverages its captive refining base to dominate mineral oil supply chains in northern industrial zones. Sinopec anchors national distribution through 30,000-plus branded service stations. Shell plc competes on synthetic product credentials, positioning its technology leadership around wind turbine and electric vehicle thermal management fluids.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically spanning ISO VG 32 to 680 for industrial applications and SAE 0W-16 to 20W-50 for automotive engines. Their primary purpose is extending equipment life and optimizing energy efficiency in combustion engines, transmissions, hydraulic systems, and precision manufacturing equipment. Engine Oil occupies the largest value pool due to China's massive passenger and commercial vehicle parc, while Synthetic Oil commands premium positioning as OEMs specify longer service intervals and severe-duty performance. Industrial application demand tracks fixed-asset investment cycles, with hydraulic fluids seeing concentrated uptake in construction machinery and steel rolling mills.
MIIT fuel economy standards and GB national standards for lubricant specifications are tightening additive chemistry and base oil refining requirements, directly shaping product reformulation timelines and import substitution dynamics. NMPA-equivalent oversight of food-grade and pharmaceutical-process lubricants, alongside provincial environmental bureaus' enforcement of MEE wastewater discharge rules, is forcing blenders to relocate capacity or upgrade solvent recovery systems. Stakeholders must monitor how China's carbon border adjustment preparations and evolving new-energy vehicle thermal fluid specifications reshape product portfolio priorities.
Market Dynamics
MIIT fuel economy standards and China's dual carbon goals are compressing formulation timelines, forcing blenders to abandon mineral oil portfolios faster than equipment replacement cycles would naturally allow.
Growth Catalysts
- Dual carbon policy framework:State-owned transport fleets face mandatory emissions benchmarks that reward extended-drain synthetic formulations. Procurement officers now specify ISO VG 46 and 68 grades with 50,000-kilometer service intervals.
- Yangtze River Delta manufacturing density:Automotive OEMs and precision machinery plants cluster in Jiangsu and Zhejiang provinces, creating concentrated demand for high-performance hydraulic fluids and metalworking lubricants.
- Wind turbine installation surge:Gearbox manufacturers specify PAO-based lubricants for offshore units, opening a premium segment insulated from passenger vehicle electrification risks.
Market Restraints
- Base oil supply concentration:Group II and III base stock production concentrates in state-controlled refineries, limiting independent blenders' feedstock flexibility and pricing leverage.
- MEE wastewater enforcement:Provincial environmental bureaus' discharge rules force solvent recovery system upgrades that add 15-20% to blending facility capex.
- Electric vehicle thermal fluid substitution:Battery electric vehicle powertrains eliminate engine oil demand entirely, threatening the largest value pool in the lubricant portfolio.
Strategic Opportunities
- Food-grade lubricant white space:NMPA-equivalent oversight of pharmaceutical-process lubricants remains underdeveloped, allowing early movers to establish certification benchmarks before mandatory standards arrive.
- Guangdong-Hong Kong-Macao Greater Bay Area:Advanced manufacturing investments in Shenzhen and Dongguan create demand for cleanroom-compatible synthetic lubricants in semiconductor fabrication equipment.
- Carbon border adjustment preparation:Export-oriented machinery manufacturers seek lubricants with verified carbon intensity documentation to preserve EU market access once CBAM phases in.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise in zinc-free anti-wear packages and friction modifier synergies concentrates at a handful of research institutes, constraining new product development velocity.
- GB standard compliance timelines:National standards for lubricant specifications update on irregular cycles, forcing blenders to maintain parallel inventory for domestic and export-certified variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Lubricants Market |
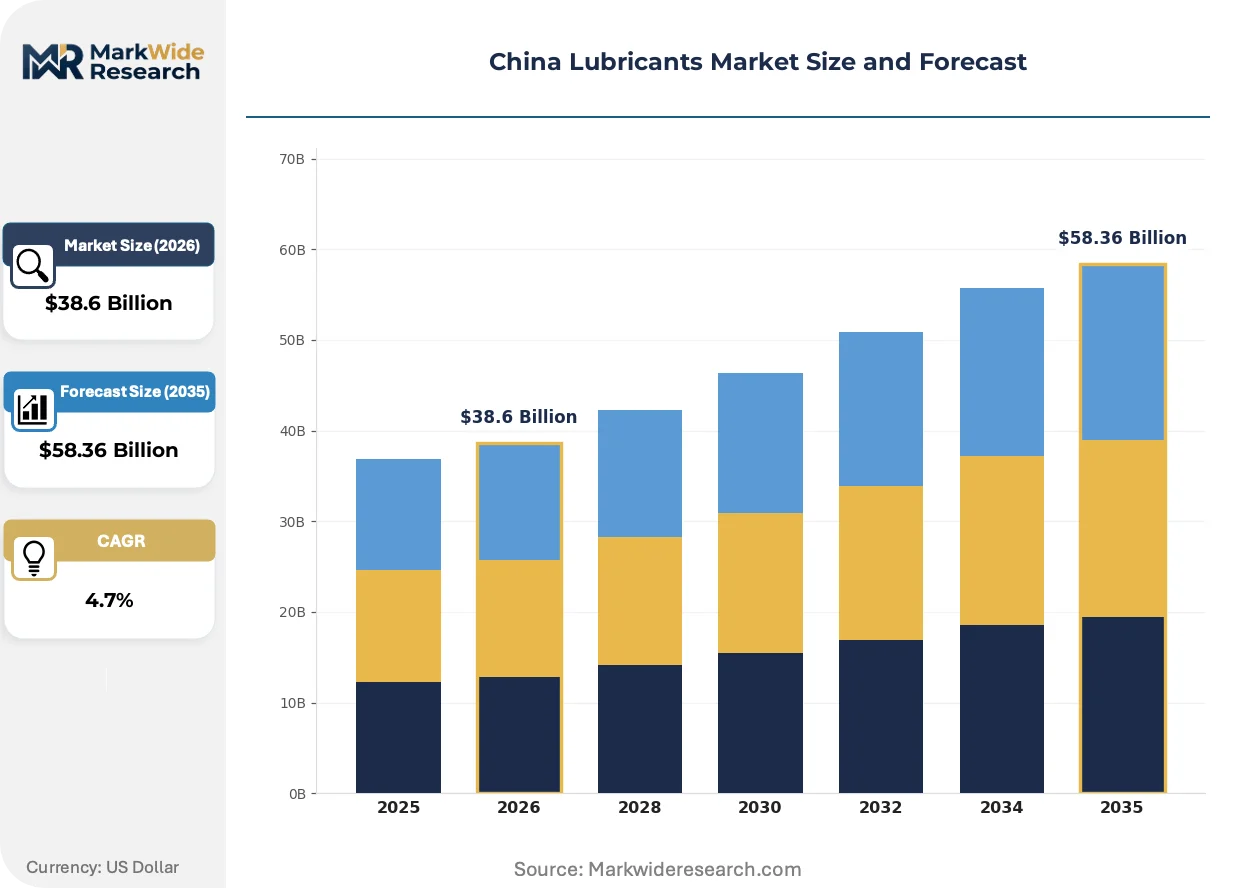
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Engine Oil, Gear Oil, Hydraulic Oil, Process Oil Application: Automotive, Industrial, Marine, Aerospace Base Oil: Mineral Oil, Synthetic Oil, Bio-Based Oil, Recycled Oil End User: Manufacturers, Workshops, Retailers, OEMs |
| Companies Covered | Shell plc, Jiangsu Dete Chemical Trade Co., Ltd., PetroChina Company Limited, Shanghai Songze Trading Co., Ltd., Hebei Yingye New Energy Technology Co., Ltd., Sinopec (China Petrochemical Corporation), ExxonMobil Corporation, Xipeng Technology (Luoyang) Co., Ltd., Zhongtian Petrochemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Lubricants Market Emerging Trajectories
Reformulation priorities are diverging sharply between thermal management fluids for electrified powertrains and legacy combustion engine oils, splitting R&D budgets across incompatible technical pathways.
Polyalkylene glycol synthetic base stocks are expanding into electric vehicle battery thermal management systems. Ningbo and Changzhou battery pack assemblers specify these fluids for their dielectric properties and temperature stability across -40°C to 150°C operating windows. The technology is expanding into a segment that previously consumed no lubricants at all, creating net new volume despite powertrain simplification.
MIIT's tightened fuel economy standards now mandate 4.0L/100km fleet averages for passenger vehicles by 2025. Lubricant viscosity grades are compressing toward SAE 0W-8 and 0W-12 specifications that reduce hydrodynamic friction losses. Domestic OEMs in the Shanghai and Beijing design centers reformulate factory-fill specifications quarterly to protect corporate average fuel economy credits.
Fleet operators in the logistics sector now unbundle lubricant procurement from maintenance contracts, conducting reverse auctions for bulk synthetic deliveries. Third-party maintenance chains in Chengdu and Wuhan capture this disintermediated volume, displacing traditional service-station attachment sales. The pattern concentrates where independent fleet management platforms have achieved critical mass in long-haul trucking networks.
China Lubricants Market Segmentation
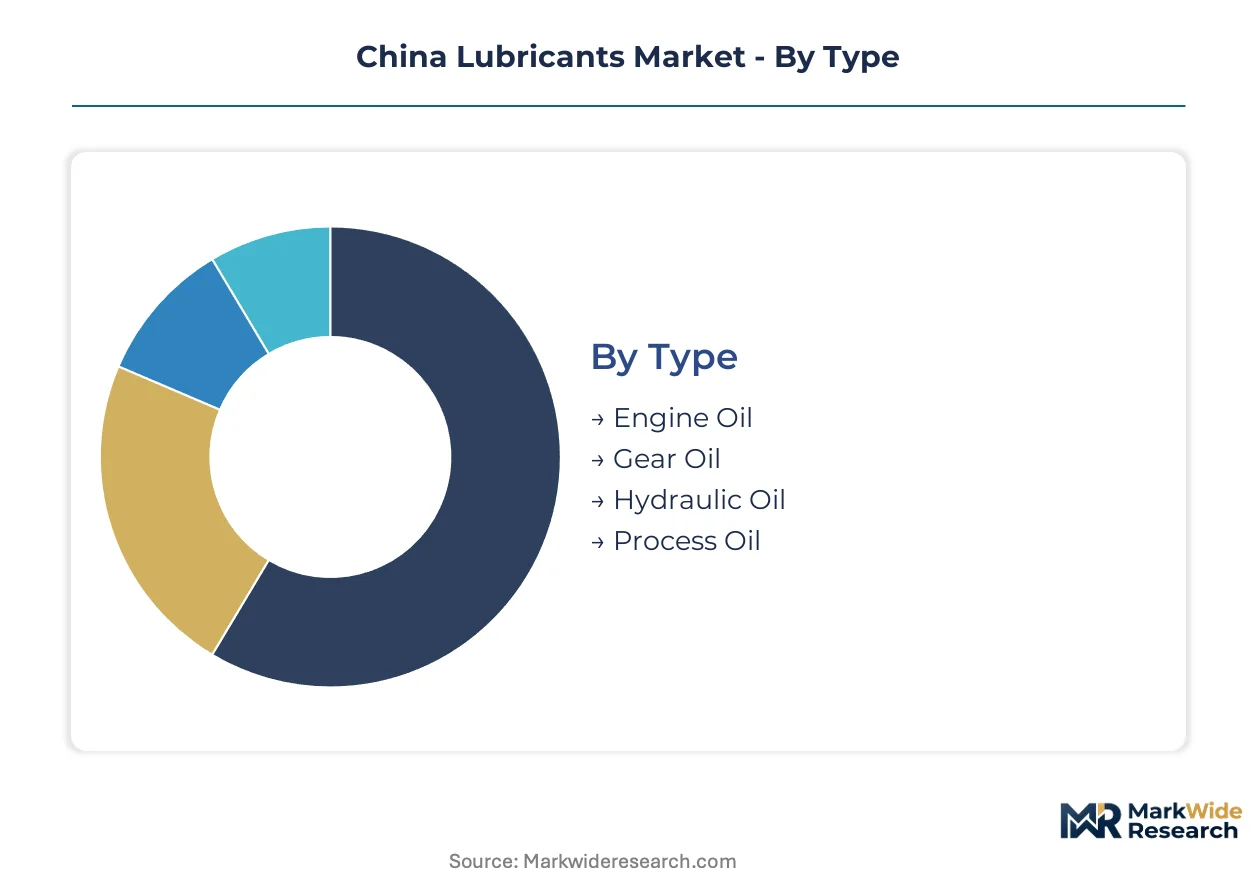
Segmentation in China's lubricants market reveals how MIIT fuel economy standards and dual carbon goals are fragmenting demand across incompatible technical specifications. Procurement patterns now diverge sharply between state-owned fleet tenders and private industrial accounts, forcing blenders to maintain parallel product architectures.
Type:
Buyers prioritize viscosity grade and drain interval specifications that directly impact total cost of ownership calculations in fleet procurement.
- Engine Oil:Formulations span SAE 0W-16 to 20W-50 grades with additive packages tuned for gasoline direct injection and turbocharged compression ignition. Demand concentrates in the Yangtze River Delta where automotive OEMs specify factory-fill synthetic blends to protect corporate average fuel economy credits under MIIT mandates.
- Hydraulic Oil:ISO VG 32 to 68 grades dominate construction machinery and steel rolling mill applications. Procurement officers in Jiangsu and Zhejiang provinces specify zinc-free anti-wear packages to meet MEE wastewater discharge rules for metalworking operations.
- Gear Oil:Extreme-pressure formulations serve wind turbine gearboxes and heavy-duty transmissions. PAO-based synthetics capture premium positioning in offshore wind installations where service access costs dwarf lubricant price premiums.
- Process Oil:Rubber extender and textile auxiliary grades follow polymer manufacturing location patterns. Demand tracks synthetic rubber capacity expansion in Shandong and petrochemical integration projects along the Bohai Rim.
Engine Oil leads on scale; Hydraulic Oil leads on momentum as industrial fixed-asset investment cycles recover in eastern manufacturing corridors.
Application:
Volume distribution reflects the divergence between electrification-threatened automotive demand and infrastructure-driven industrial uptake.
- Automotive:Passenger and commercial vehicle parc maintenance generates the largest absolute volume pool. Workshop chains in Chengdu and Wuhan capture disintermediated procurement through reverse auction platforms that unbundle lubricant supply from maintenance contracts.
- Industrial:Precision machinery, metalworking, and hydraulic equipment applications concentrate in the Pearl River Delta semiconductor fabrication ecosystem. Cleanroom-compatible synthetic formulations command 40-60% price premiums over standard industrial grades.
- Marine:Two-stroke crosshead engine oils and stern tube lubricants serve coastal shipping and fishing fleet operators. Port authorities in Ningbo and Qingdao enforce sulfur content regulations that reshape cylinder oil additive chemistry.
- Aerospace:Military and civil aviation specifications demand ester-based synthetics with thermal stability to 200°C. Domestic certification lags behind imported alternatives, constraining local blender participation.
Automotive dominates current volume; Industrial offers the steepest expansion trajectory as advanced manufacturing investments accelerate in Guangdong and Jiangsu.
Base Oil:
Feedstock selection determines regulatory compliance positioning and carbon intensity documentation for export-oriented machinery manufacturers.
- Mineral Oil:Group I and II base stocks from state-controlled refineries anchor economy-tier positioning. PetroChina's captive northern refining base limits independent blender pricing leverage through supply concentration.
- Synthetic Oil:PAO, ester, and polyalkylene glycol chemistries serve severe-duty and thermal management applications. Ningbo battery pack assemblers specify PAG dielectric fluids for electric vehicle thermal management systems operating across -40°C to 150°C windows.
- Bio-Based Oil:Vegetable oil derivatives and synthetic esters from renewable feedstocks target food-grade and environmentally sensitive applications. NMPA-equivalent oversight remains underdeveloped, delaying mandatory certification benchmarks.
- Recycled Oil:Re-refined base stocks from used lubricant recovery face quality perception barriers despite GB standard recognition. MEE wastewater enforcement is forcing solvent recovery system upgrades that improve re-refining economics.
Mineral Oil retains volume leadership; Synthetic Oil gains share fastest as OEM factory-fill specifications tighten and electric vehicle thermal fluids create net new demand.
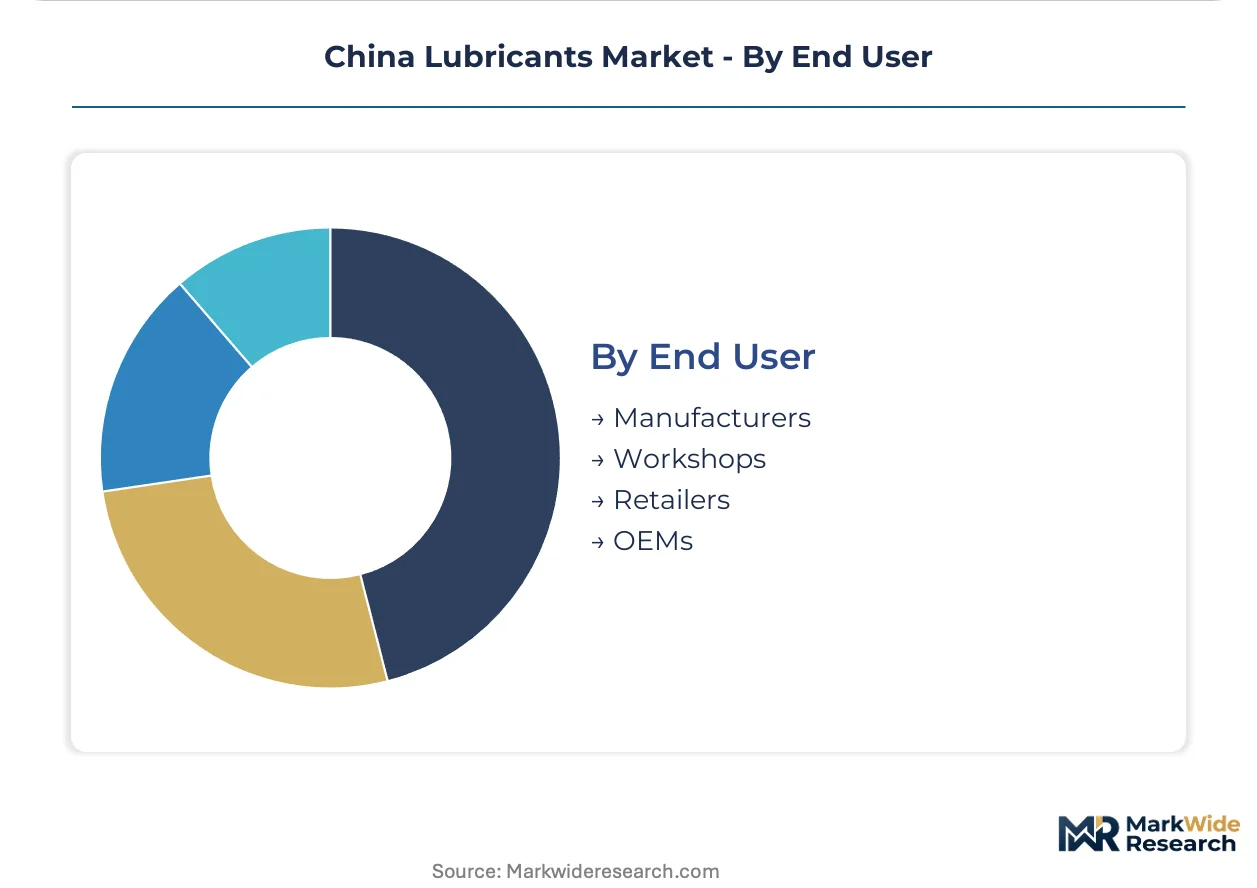
End User:
Channel structure determines pricing realization and technical service intensity requirements across divergent procurement modalities.
- OEMs:Factory-fill specifications and approved aftermarket programs lock in multi-year supply agreements. Shanghai and Beijing design centers reformulate quarterly to protect fuel economy credits, accelerating specification turnover.
- Manufacturers:In-house maintenance departments at steel, cement, and chemical plants specify industrial lubricants directly. Procurement centralization in state-owned enterprises favors bulk synthetic tenders with extended drain interval guarantees.
- Workshops:Independent and franchised service outlets capture the aftermarket replacement cycle. Third-party maintenance chains displace traditional service-station attachment sales where fleet management platforms achieve critical mass.
- Retailers:Branded service stations and e-commerce channels serve the fragmented passenger vehicle DIY segment. Sinopec's 30,000-plus network anchors national distribution density that independent blenders cannot replicate.
OEMs command the highest margin pool; Workshops represent the fastest volume shift as procurement disintermediation accelerates in logistics fleet networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and additive package engineers concentrate in eastern China's petrochemical corridors, anchoring regional competitive advantage.
Yangtze River Delta
Automotive OEMs and precision machinery plants cluster across Jiangsu and Zhejiang provinces, generating concentrated demand for high-performance hydraulic fluids. MIIT fuel economy standards mandate 4.0L/100km fleet averages, forcing Shanghai design centers to reformulate factory-fill specifications quarterly. Ningbo battery pack assemblers specify polyalkylene glycol dielectric fluids for electric vehicle thermal management systems.
Pearl River Delta
Advanced manufacturing investments in Shenzhen and Dongguan create demand for cleanroom-compatible synthetic lubricants in semiconductor fabrication equipment. Provincial environmental bureaus enforce MEE wastewater discharge rules that force solvent recovery system upgrades across blending facilities. Third-party maintenance chains in Guangzhou capture disintermediated procurement volume through reverse auction platforms.
Beijing-Tianjin-Hebei
State-owned transport fleets face mandatory emissions benchmarks under China's dual carbon goals, rewarding extended-drain synthetic formulations. Procurement officers specify ISO VG 46 and 68 grades with 50,000-kilometer service intervals for heavy-duty logistics operations. Sinopec's branded service station network anchors national distribution density that independent blenders cannot replicate.
Shandong Peninsula
Synthetic rubber capacity expansion and petrochemical integration projects drive process oil demand for rubber extender and textile auxiliary grades. PetroChina's captive northern refining base limits independent blender pricing leverage through Group II and III base stock supply concentration. Local blenders serve economy-tier positioning in industrial maintenance accounts.
Sichuan-Chongqing
Western industrial development and infrastructure investment cycles sustain hydraulic fluid demand for construction machinery applications. Fleet management platforms achieve critical mass in long-haul trucking networks, accelerating procurement disintermediation. Workshop chains in Chengdu capture aftermarket replacement volume outside traditional service-station channels.
China Lubricants Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent feedstock and formulation strategies. State-controlled refineries dominate mineral oil supply chains through captive Group II and III base stock production, while independent blenders rely on strategic sourcing relationships. Three archetypes define competitive positioning: integrated state oil majors, multinational synthetic specialists, and regional independent blenders. Capacity expansion and portfolio diversification toward thermal management fluids represent the dominant competitive moves as electrification reshapes product architectures.
Within the integrated state oil major tier, PetroChina Company Limited and Sinopec occupy positions anchored by refining scale and distribution infrastructure. Shell plc exemplifies the multinational synthetic specialist archetype, competing on technology credentials in severe-duty applications. Among regional independent blenders, Jiangsu Dete Chemical Trade Co., Ltd. and Shanghai Songze Trading Co., Ltd. represent asset-light models focused on formulation flexibility and localized service relationships.
| Leading Market Players |
|---|
| Shell plc |
| Jiangsu Dete Chemical Trade Co., Ltd. |
| PetroChina Company Limited |
| Shanghai Songze Trading Co., Ltd. |
| Hebei Yingye New Energy Technology Co., Ltd. |
| Sinopec (China Petrochemical Corporation) |
| ExxonMobil Corporation |
| Xipeng Technology (Luoyang) Co., Ltd. |
| Zhongtian Petrochemical |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers anchor supply discipline through captive refining infrastructure that compresses pricing flexibility for independent blenders. PetroChina's northern refining base and Sinopec's branded service network create dual leverage over mineral oil feedstock costs and downstream realization, while procurement disintermediation in logistics fleets fragments pricing power across third-party maintenance chains.
Pricing Analysis
The bundled-vs-unbundled service split now defines pricing architecture across China's lubricants landscape. Three-tier pricing structure across premium synthetics, standard mineral blends, and economy re-refined grades separates OEM factory-fill contracts from aftermarket workshop sales and bulk fleet tenders. Pricing pressure stems from reverse auction platforms that unbundle lubricant supply from maintenance contracts in Chengdu and Wuhan logistics networks. State-owned transport fleets exhibit lowest price sensitivity due to extended-drain interval guarantees, while independent workshops face margin compression from procurement centralization.
Supply Chain Analysis
Reverse-logistics flows for used lubricant re-refining are expanding as MEE wastewater enforcement upgrades solvent recovery economics. Base oil production concentrates in China through state-controlled Group II and III refining capacity, with supplementary Group I supply from regional Asian exporters. Feedstock sourcing rests on crude slate flexibility at northern refineries and additive package imports from specialty chemical producers. Single-source vulnerability concentrates in state refinery supply agreements that limit independent blender feedstock optionality. Distribution runs through Sinopec's 30,000-plus branded service station network alongside disintermediated third-party maintenance chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's lubricants market functions as a regulatory compounder where MIIT fuel economy standards and dual carbon goals continuously reset formulation requirements and procurement specifications.
For Market Incumbents: Anchor defensive positioning through backward integration into captive additive blending capacity and certification pre-positioning for NMPA-equivalent food-grade standards. Electrification of passenger vehicle powertrains threatens the engine oil value pool, requiring accelerated thermal management fluid development for battery pack assemblers in Ningbo and Changzhou. For New Entrants and Emerging Players: Capture white-space opportunity in Guangdong-Hong Kong-Macao Greater Bay Area semiconductor fabrication lubricants, where cleanroom-compatible synthetics command substantial premiums over standard industrial grades. Food-grade lubricant certification remains underdeveloped, allowing early movers to establish benchmarks before mandatory standards arrive through direct technical service relationships with Shenzhen precision manufacturers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional independent blenders with formulation flexibility and localized service density in eastern manufacturing corridors. Long-term viability hinges on electric vehicle thermal fluid portfolio development and carbon intensity documentation capabilities for export-oriented machinery manufacturers. Monitor NMPA-equivalent regulatory timeline acceleration as the inflection signal for food-grade certification value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Captive additive production reduces feedstock cost volatility for independent blenders serving Jiangsu precision machinery accounts. |
| Thermal Management Fluid Development | PAG-based dielectric formulations for Ningbo battery pack assemblers create net new volume outside threatened engine oil segments. |
| Carbon Intensity Documentation Investment | Verified lifecycle carbon data preserves EU market access for export-oriented machinery manufacturers under CBAM preparation. |
| Food-Grade Certification Pre-Positioning | Early NMPA-equivalent compliance establishes benchmark status before mandatory pharmaceutical-process lubricant standards arrive. |
| Reverse Logistics Infrastructure Buildout | Re-refining capacity expansion improves economy-tier positioning as MEE wastewater rules upgrade solvent recovery economics. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement pattern shifts and formulation specification changes. Primary discussions with lubricant procurement officers at state-owned transport fleets, technical directors at Yangtze River Delta automotive OEMs, plant engineers at Jiangsu precision machinery facilities, and blending operations managers at independent facilities informed demand segmentation. Secondary validation drew from MIIT fuel economy standard filings, GB lubricant specification updates, MEE wastewater discharge enforcement records, and customs trade data for base oil and additive imports. Bottom-up volume builds across end-use applications triangulated against top-down macroeconomic indicators.
Segment-weighting approaches distributed value and volume across engine oil, hydraulic oil, gear oil, and process oil categories, with further disaggregation by base oil type and end-user channel. The projection horizon incorporates fixed-asset investment cycles in eastern manufacturing corridors, wind turbine installation trajectories for offshore gearbox lubricants, and electric vehicle thermal fluid penetration in battery pack assembly. CAGRs derive from elasticity modeling against industrial production indices and automotive parc maintenance patterns. MIIT regulatory compliance timelines and dual carbon policy implementation intensity serve as scenario variables.
Policy implementation delays, base oil supply disruptions at state refineries, and faster-than-expected electric vehicle powertrain penetration are the dominant revision risks to the outlook. Forecasts embed assumptions regarding NMPA-equivalent regulatory development pace and CBAM phase-in stringency for export-oriented machinery. Practitioners should monitor MIIT factory-fill specification update frequency and independent fleet management platform penetration in long-haul trucking networks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Indonesia Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
South Korea Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Europe Metalworking Fluids Market