
 Industrial Lubricants Market | 2026-2036
Industrial Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lubricants Market Intelligence
Base oil refining capacity in the Middle East is consolidating as national oil companies expand Group II and III output for export-oriented lubricant blending. ExxonMobil Corporation leverages its integrated upstream-to-blending infrastructure across Singapore and Rotterdam to sustain cost advantages in marine lubricant supply. Shell plc anchors its position through backward integration into gas-to-liquids base stocks, while Fuchs Petrolub SE differentiates via specialization in high-performance greases for wind turbine main bearings.
Industrial lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems operating under boundary, mixed, or hydrodynamic regimes; typical formulations contain 70-95% base oil with viscosity indices exceeding 95 for multi-grade hydraulic fluids. Their primary commercial purpose is extending equipment life and energy efficiency in capital-intensive machinery. Hydraulic fluids dominate product type value pools due to ubiquity in construction and factory automation, while metalworking fluids represent the fastest-growing category as precision machining intensifies in aerospace component manufacturing. Among end users, OEMs command premium pricing through specification lock-in, whereas aftermarket service providers compete on inventory breadth and technical service density.
EPA regulations under the Vessel General Permit mandate biodegradable lubricants in U.S. commercial marine applications, while REACH restrictions on zinc-based anti-wear additives are forcing reformulation across European supply chains. China's GB standards on industrial lubricant performance classes are tightening import access for non-certified suppliers. Stakeholders must monitor evolving OEM factory-fill specifications for electric vehicle gearboxes and thermal management systems as powertrain electrification redefines lubricant functional requirements.
Market Dynamics
Powertrain electrification is fragmenting traditional lubricant demand pools as electric vehicle thermal management systems require dielectric fluids with entirely different viscosity and conductivity profiles than internal combustion engine oils.
Growth Catalysts
- REACH biodegradability mandates:European formulators are accelerating synthetic ester adoption in hydraulic systems to preempt ECHA restrictions on mineral oil aquatic toxicity.
- Wind turbine OEM factory-fill specifications:Turbine manufacturers in Germany and Denmark are specifying high-performance greases for main bearings operating under 20-year service intervals.
- Precision machining intensification:Aerospace component manufacturers in Japan are consuming advanced metalworking fluids for titanium and nickel superalloy operations.
Market Restraints
- Group II/III base oil supply concentration:Middle Eastern national oil companies control expanding export-oriented refining capacity, creating single-source dependency for blenders.
- Technical limitation of dielectric fluids:Current polyalphaolefin formulations exhibit insufficient thermal conductivity for 800V electric vehicle architectures.
- REACH zinc additive restrictions:ECHA limitations on zinc dialkyldithiophosphate anti-wear chemistry are forcing costly reformulation across European gear oil supply chains.
Strategic Opportunities
- Underpenetrated Indian manufacturing:BIS certification requirements for industrial lubricant performance classes are tightening, creating entry barriers for uncertified imports and opening space for compliant domestic blenders.
- Marine biodegradable mandates:EPA Vessel General Permit requirements for U.S. commercial marine applications are generating specification-locked demand for environmentally acceptable lubricants.
- Gas-to-liquids base stock convergence:Integration of Fischer-Tropsch synthesis with additive package engineering enables ultra-high viscosity index formulations for arctic offshore equipment.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tribology and additive synergy modeling is concentrating at legacy European and U.S. research centers, constraining regional expansion.
- OEM specification volatility:Rapidly evolving electric vehicle gearbox and thermal management factory-fill requirements are compressing product development cycles and straining testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lubricants Market |
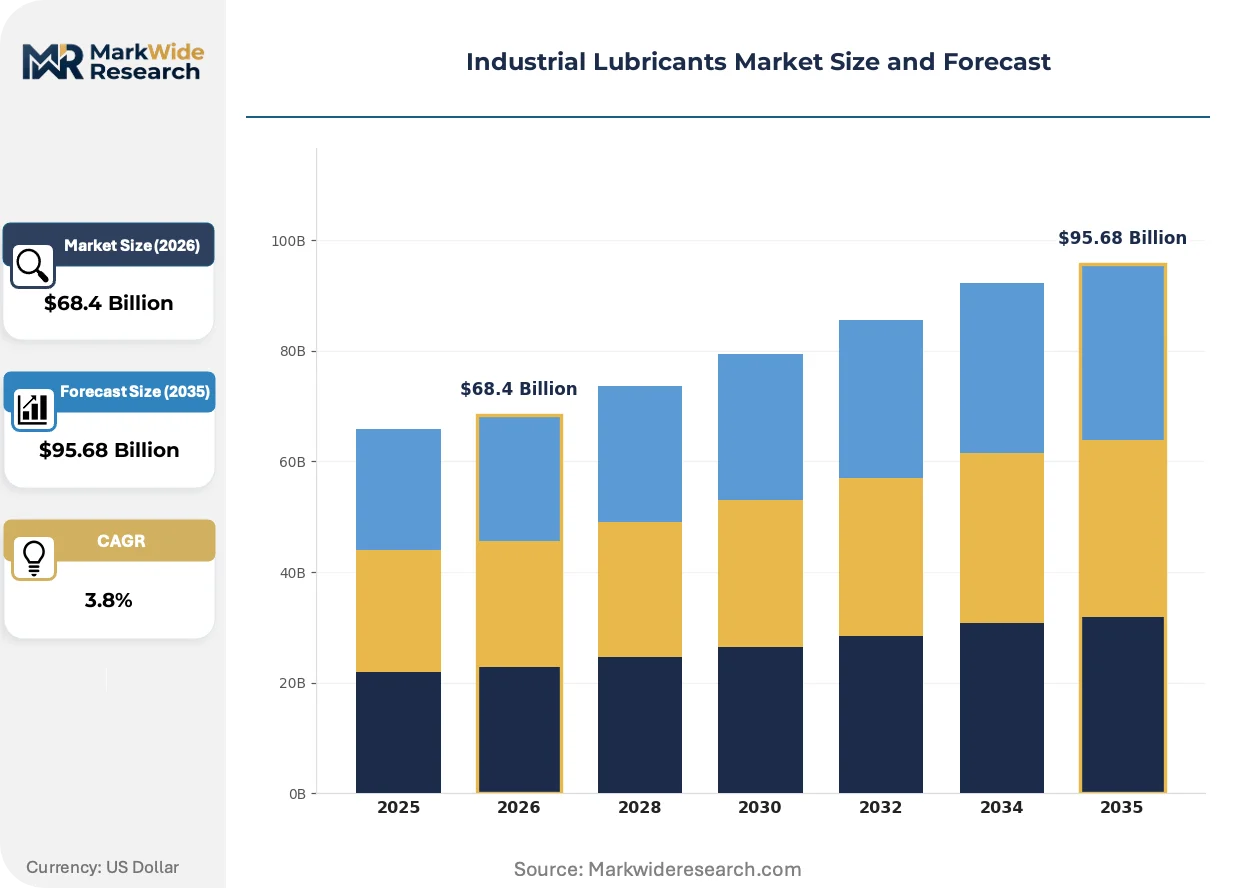
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $95.68 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Greases, Motor Oils, Metalworking Fluids Application: Manufacturing Equipment, Automotive Industry, Marine Applications, Mining Equipment End User: OEMs, Aftermarket Service Providers, Industrial Manufacturers, Maintenance Service Providers Distribution Channel: Direct Sales, Distributors, Online Retail, Retail Outlets |
| Companies Covered | TotalEnergies SE, BP plc, ExxonMobil Corporation, The Lubrizol Corporation, Phillips 66 Company, Shell plc, Fuchs Petrolub SE, Klüber Lubrication, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lubricants Market Strategic Shifts & Innovations
Synthetic base stock technology is restructuring competitive advantage as formulators race to meet electrification-driven thermal management requirements and tightening environmental compliance thresholds.
Polyalkylene glycol synthetic hydraulic fluids are consolidating technical preference among German and Japanese manufacturing equipment operators. These formulations deliver superior oxidation stability and biodegradability profiles compared to mineral oil predecessors. Factory automation OEMs in Bavaria and Aichi Prefecture are specifying PAG fluids for servo-hydraulic systems, compressing demand for conventional hydraulic oil categories.
EPA regulations under the Vessel General Permit mandate biodegradable lubricants in U.S. commercial marine applications including stern tubes, thrusters, and controllable pitch propellers. This policy is diverting blending capacity toward ester-based formulations and away from mineral oil marine products. Gulf Coast supply chains are reconfiguring around environmentally acceptable lubricant certification requirements.
Specification-driven procurement is compressing supplier lists as electric vehicle powertrain OEMs consolidate factory-fill approvals around fewer qualified lubricant partners. Tier-1 automotive suppliers in Stuttgart and Detroit are demanding dedicated technical service teams and co-development agreements rather than spot purchasing. This behavioral shift is visible most acutely in thermal management fluid categories where dielectric properties must be validated against proprietary battery pack designs.
Industrial Lubricants Market Segmentation
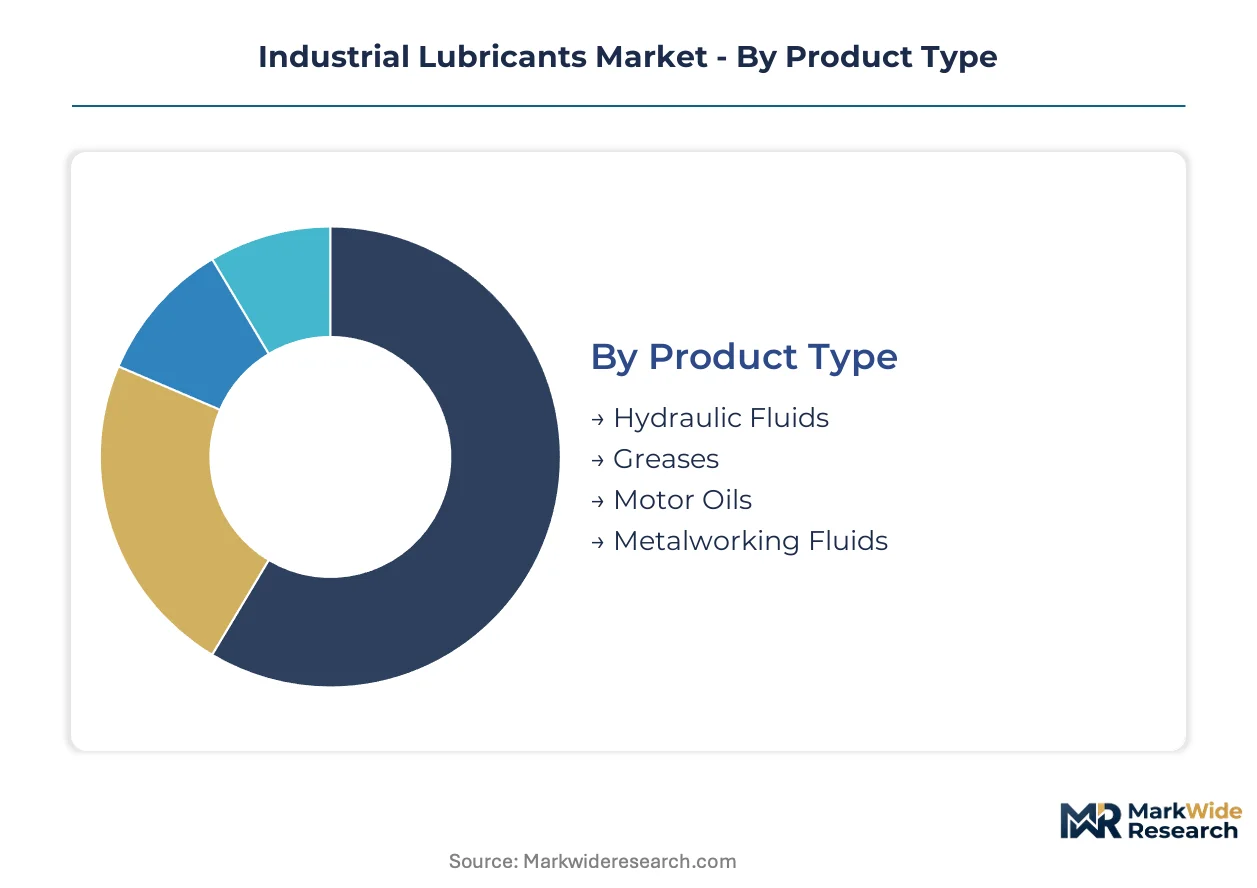
Segmentation in industrial lubricants reveals how specification power, procurement authority, and channel economics fragment value capture. Buyers prioritize formulation performance for capital-intensive machinery, while regulatory compliance reshapes product mix across end-use verticals.
Product Type:
Equipment operators select formulations based on operating regime severity, environmental exposure, and OEM warranty requirements rather than price alone.
- Hydraulic Fluids:Formulations contain 70-95% base oil with viscosity indices exceeding 95 for multi-grade performance. German and Japanese manufacturing equipment operators are expanding synthetic hydraulic fluid consumption amid tightening EPA and REACH mandates on mineral oil biodegradability. Demand concentrates in construction and factory automation where system reliability dictates specification.
- Metalworking Fluids:Advanced formulations for precision machining operations deliver cooling and lubrication under extreme pressure. Aerospace component manufacturers in Japan consume these fluids intensively for titanium and nickel superalloy operations, making this category the steepest expansion trajectory as precision machining intensifies.
- Greases:High-performance thickeners with synthetic base stocks serve wind turbine main bearings and heavy-load industrial equipment.
- Motor Oils:Traditional internal combustion engine lubricants face demand pressure from powertrain electrification and thermal management fluid substitution.
Volume sits with hydraulic fluids; growth tilts toward metalworking fluids.
Application:
Application selection tracks capital expenditure cycles, regulatory exposure, and equipment utilization intensity across industrial verticals.
- Manufacturing Equipment:Servo-hydraulic systems and precision machine tools require oxidation-stable formulations. Factory automation OEMs in Bavaria and Aichi Prefecture specify polyalkylene glycol fluids, compressing demand for conventional mineral oil categories in high-value production environments.
- Automotive Industry:Electric vehicle powertrain redesigns require novel thermal management chemistries with dielectric properties validated against proprietary battery pack designs. OEMs in Stuttgart and Detroit consolidate factory-fill approvals around fewer qualified lubricant partners.
- Marine Applications:EPA Vessel General Permit mandates biodegradable lubricants in U.S. commercial marine applications including stern tubes and controllable pitch propellers. Gulf Coast supply chains reconfigure around environmentally acceptable lubricant certification requirements.
- Mining Equipment:Extreme-load machinery operating in abrasive environments demands high-viscosity formulations with enhanced anti-wear additive packages.
Revenue concentrates in manufacturing equipment; specification intensity peaks in automotive applications.
End User:
Procurement authority splits between specification-locked OEM relationships and service-driven aftermarket channels.
- OEMs:Factory-fill specifications command premium pricing through technical validation and co-development agreements. Turbine manufacturers in Germany and Denmark specify high-performance greases for main bearings operating under 20-year service intervals, locking in supplier relationships.
- Aftermarket Service Providers:Inventory breadth and technical service density drive competitive positioning. These competitors compete on response time and formulation availability rather than specification control.
- Industrial Manufacturers:Direct procurement for in-house maintenance operations emphasizes total cost of ownership over unit price.
- Maintenance Service Providers:Contract-based lubrication management services bundle fluid supply with condition monitoring and equipment reliability programs.
Margin capture favors OEMs; volume flows through aftermarket channels.
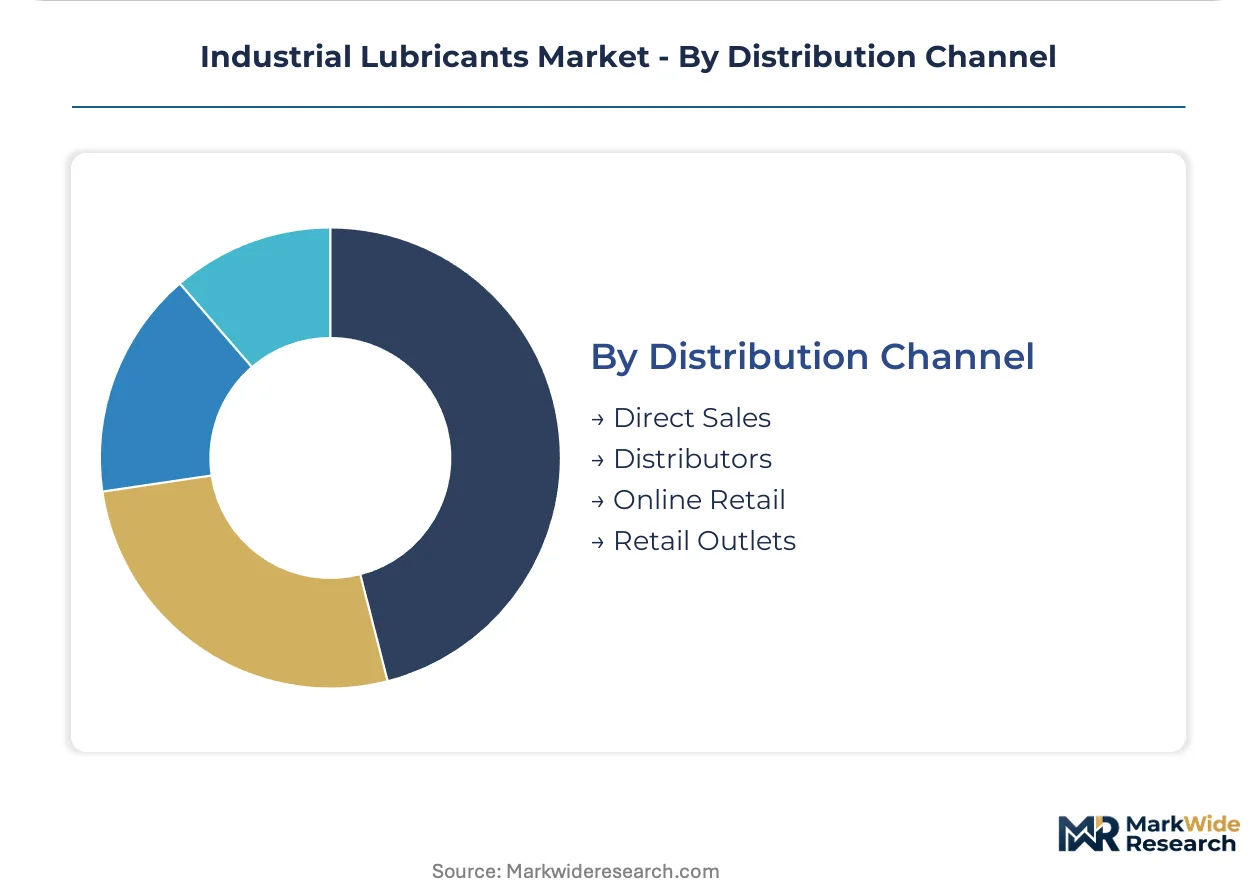
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic coverage needs.
- Direct Sales:Large-volume accounts with technical service requirements bypass intermediaries. Integrated suppliers leverage upstream-to-blending infrastructure across Singapore and Rotterdam to sustain cost advantages in marine lubricant supply.
- Distributors:Regional inventory positioning serves mid-scale industrial accounts with fragmented geographic footprints. Middle Eastern national oil companies control expanding export-oriented refining capacity, creating single-source dependency for blenders sourcing through distribution.
- Online Retail:Standardized product categories with defined specifications enable digital procurement for small and medium enterprises.
- Retail Outlets:Consumer-grade and light industrial lubricants reach maintenance shops and small equipment operators through physical storefront networks.
Technical complexity drives direct engagement; commoditized products flow through distributors and retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Group II and III base oil refining capacity in the Middle East anchors export-oriented supply chains serving lubricant blenders across manufacturing belts worldwide.
United States
Construction equipment operators and factory automation OEMs in the Midwest and Southeast drive hydraulic fluid consumption. EPA Vessel General Permit mandates for biodegradable marine lubricants reconfigure Gulf Coast blending capacity toward ester-based formulations. Houston and Port Arthur host concentrated marine lubricant supply infrastructure.
Germany
Wind turbine OEMs in northern Germany and automotive powertrain manufacturers in Stuttgart specify high-performance greases and thermal management fluids. REACH restrictions on zinc-based anti-wear additives force reformulation across gear oil supply chains. Bavarian factory automation clusters specify polyalkylene glycol hydraulic fluids for servo systems.
China
Industrial machinery production in Jiangsu and Zhejiang provinces sustains metalworking fluid demand for precision component manufacturing. GB standards on industrial lubricant performance classes tighten import access for non-certified suppliers. Shanghai and Ningbo concentrate domestic blending capacity serving export-oriented manufacturing.
Japan
Aerospace component manufacturers in Aichi Prefecture consume advanced metalworking fluids for titanium and nickel superalloy machining operations. METI efficiency standards accelerate synthetic lubricant adoption in capital-intensive production environments. Nagoya and Toyota City anchor precision manufacturing lubricant demand.
India
BIS certification requirements for industrial lubricant performance classes create entry barriers for uncertified imports across Maharashtra and Gujarat manufacturing corridors. Domestic blenders expand capacity to serve automotive OEMs and textile machinery operators. Mumbai and Pune concentrate formulation and distribution infrastructure.
Industrial Lubricants Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty synthetic formulations and regional certification compliance. The market structures around three tiers: integrated oil majors with captive base stock supply, independent blenders with formulation specialization, and regional distributors with technical service density. Strategic archetypes include backward-integrated upstream players, additive technology specialists, and application-focused grease formulators. Dominant competitive moves encompass Fischer-Tropsch base stock integration and co-development agreements with electric vehicle powertrain OEMs.
Among Europe-based lubricant specialists, Fuchs Petrolub SE and Klüber Lubrication exemplify the high-performance grease archetype serving wind turbine and precision machinery applications. ExxonMobil Corporation anchors the integrated major tier with upstream-to-blending infrastructure. Shell plc represents gas-to-liquids base stock convergence, while TotalEnergies SE and BP plc occupy positions within the diversified energy major segment. The Lubrizol Corporation exemplifies additive technology specialization upstream of finished lubricant formulation.
| Leading Market Players |
|---|
| TotalEnergies SE |
| BP plc |
| ExxonMobil Corporation |
| The Lubrizol Corporation |
| Phillips 66 Company |
| Shell plc |
| Fuchs Petrolub SE |
| Klüber Lubrication |
| Chevron Corporation |
| Others |
Cost & Logistics Intelligence
Backward integration into Fischer-Tropsch base stock production anchors Shell's supply position and pricing power in high-viscosity index formulations, while ExxonMobil's Singapore-Rotterdam infrastructure locks in marine lubricant cost advantages against spot-market blenders.
Pricing Analysis
Warranty-bundled technical service separates OEM factory-fill contracts from unbundled aftermarket spot purchases. Three-tier pricing structure across premium synthetic, standard Group II/III, and economy mineral oil grades tracks certification tier and volume commitment. Cost compression in conventional hydraulic fluids intensifies as German and Japanese operators accelerate PAG adoption. Aftermarket service providers exhibit highest price sensitivity; OEM specification-locked buyers accept premium positioning.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns serving blending operations worldwide. Base oil supply concentrates in Saudi Arabia, Kuwait, and the United Arab Emirates as national oil companies expand Group II/III export capacity. Finished lubricant formulation draws from polyalphaolefin, synthetic ester, and additive package inputs. Single-source dependency on Middle Eastern base stock creates vulnerability to export quota shifts. Distribution runs through direct sales for large OEM accounts and regional distributors for fragmented industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH biodegradability mandates in Europe erect compliance moats that synthetic ester specialists exploit while mineral oil-dependent blenders absorb reformulation costs or exit.
For Market Incumbents: Deepen additive package engineering capabilities to preempt ECHA restrictions on zinc dialkyldithiophosphate chemistry. Secure captive Fischer-Tropsch base stock supply through long-term offtake agreements with gas-to-liquids operators. Electric vehicle thermal management fluid specifications fragment demand pools and compress product development cycles. For New Entrants and Emerging Players: BIS certification requirements in India open a window for compliant domestic blenders to capture share from uncertified import suppliers. Target Maharashtra and Gujarat manufacturing corridors with automotive OEM factory-fill programs. Pursue co-development agreements with wind turbine OEMs specifying 20-year service interval greases. For Investors and Strategic Acquirers: Exit pathways concentrate in additive technology specialists and regional certification-compliant blenders. Five-to-ten year viability favors formulators with backward-integrated base stock positions or proprietary dielectric fluid validation against 800V architectures. Watch EPA Vessel General Permit enforcement intensity as inflection indicator for environmentally acceptable lubricant demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas-to-Liquids Base Stocks | Shell's Fischer-Tropsch synthesis enables ultra-high viscosity index formulations for arctic offshore equipment. |
| Co-Development Agreements with EV Powertrain OEMs | Tier-1 suppliers in Stuttgart and Detroit demand dedicated technical service teams for thermal management validation. |
| REACH-Compliant Synthetic Ester Capacity Expansion | European formulators accelerate hydraulic fluid reformulation to preempt ECHA aquatic toxicity restrictions. |
| BIS Certification Investment for Indian Market Entry | Domestic blenders in Mumbai and Pune capture share as import barriers tighten for non-certified suppliers. |
| Marine Biodegradable Lubricant Blending Capacity | Gulf Coast supply chains reconfigure around EPA Vessel General Permit ester-based formulation requirements. |
Research Approach
Trade statistics from customs authorities, additive technology patent filings, and SEC 10-K disclosures from integrated oil majors formed the secondary backbone. Primary interviews with lubricant formulation chemists, procurement leads at German automotive OEMs, marine equipment operators, and wind turbine maintenance directors validated demand assumptions. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of base oil refining capacity additions and synthetic lubricant adoption rates informed projection parameters. The model segmented by product type, application vertical, end-user procurement authority, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating electric vehicle powertrain penetration and REACH compliance cost pass-through. Forecast inputs included Group II/III capacity expansion timelines and OEM factory-fill specification volatility.
The model assumes a particular technology adoption path; alternative pathways for polyalphaolefin dielectric fluids in 800V architectures would alter the outlook. Forecasts reflect assumptions around regulatory enforcement intensity and base oil supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Hydro Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
Global Finished Lubricant Market