
 Hydropower Lubricants Market | 2026-2036
Hydropower Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Hydropower Lubricants Market Outlook
Synthetic ester base stocks are pivoting toward wider use in high-head turbine applications as operators seek longer drain intervals and reduced environmental contamination risk. ExxonMobil Corporation leverages its integrated polyalphaolefin supply chain to serve OEM factory-fill programs across North America and Asia. Shell plc anchors its position through specialized hydraulic fluid portfolios certified for Francis and Kaplan turbine designs. FUCHS Petrolub SE differentiates via regional blending networks that reduce lead times for maintenance providers in alpine hydropower corridors.
Hydropower lubricants are formulated lubricating fluids and greases engineered to reduce friction, dissipate heat, and prevent corrosion in water turbine machinery operating under high load, variable temperature, and intermittent water exposure conditions; typical specifications include ISO VG 32-68 viscosity grades, zinc-free anti-wear additive packages, and biodegradability thresholds exceeding 60% per OECD 301B. Their primary purpose is to extend machinery life and maintain efficiency in generating equipment that operates for decades with minimal downtime. Hydraulic oils dominate volume demand due to pervasive use in turbine governor systems and wicket gate actuators across installed fleets. Bio-based formulations represent the fastest-expanding segment as European utilities face mandatory environmental compliance for installations in protected watersheds. Synthetic gear oils command premium positioning in pumped-storage facilities where frequent start-stop cycles accelerate thermal degradation of mineral alternatives.
The EPA administers spill prevention regulations under the Clean Water Act that mandate contingency planning for lubricant releases at federally licensed hydropower facilities. REACH and the EU F-Gas Regulation indirectly shape formulation roadmaps by restricting certain additive chemistries and pressurizing operators to document chemical safety across supply chains. China's MEE enforces water quality standards that affect lubricant disposal practices near the Three Gorges and other major cascade systems. Stakeholders must monitor evolving biodegradability certification requirements as watershed protection policies tighten across jurisdictions with large installed hydropower bases.
Market Dynamics
The hydropower lubricants sector faces a structural pivot as watershed protection mandates force operators to abandon mineral oil formulations in favor of bio-based and synthetic alternatives that satisfy stringent biodegradability thresholds.
Growth Catalysts
- EU Green Deal implementation:European utilities must replace conventional lubricants in protected river systems, creating mandatory demand for OECD 301B-certified formulations that exceed 60% biodegradability.
- China's Yangtze infrastructure modernization:State-owned operators are retrofitting aging turbine fleets across cascade systems, expanding procurement of high-performance hydraulic fluids for governor and wicket gate systems.
- Synthetic ester technology maturation:Extended drain intervals and thermal stability advantages are accelerating adoption in pumped-storage facilities with frequent start-stop cycling patterns.
Market Restraints
- Base stock supply concentration:Polyalphaolefin and synthetic ester feedstocks concentrate among specialty chemical producers in Germany and the United States, exposing formulators to input volatility.
- REACH additive restrictions:ECHA scrutiny of zinc-based anti-wear packages forces costly reformulation of legacy turbine lubricants without performance degradation.
- Technical compatibility barriers:Bio-based formulations exhibit seal swelling tendencies with older nitrile rubber components in vintage Francis turbine installations.
Strategic Opportunities
- Alpine corridor service networks:Switzerland, Austria, and Norway host concentrated hydropower assets where regional blending capabilities reduce maintenance provider lead times.
- Pumped-storage expansion:Grid stabilization investments in China and the United States create demand for thermal-stress-resistant synthetic gear oils.
- Digital fluid monitoring integration:IoT sensor deployment enables predictive drain interval optimization, opening subscription-based lubricant management contracts.
Industry Challenges
- Tribology specialist scarcity:Formulation chemists with combined expertise in hydro turbine mechanics and biodegradable additive chemistry remain concentrated at a handful of European technical institutes.
- Multi-jurisdiction certification timelines:Simultaneous OECD 301B, Blue Angel, and EU Ecolabel approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydropower Lubricants Market |
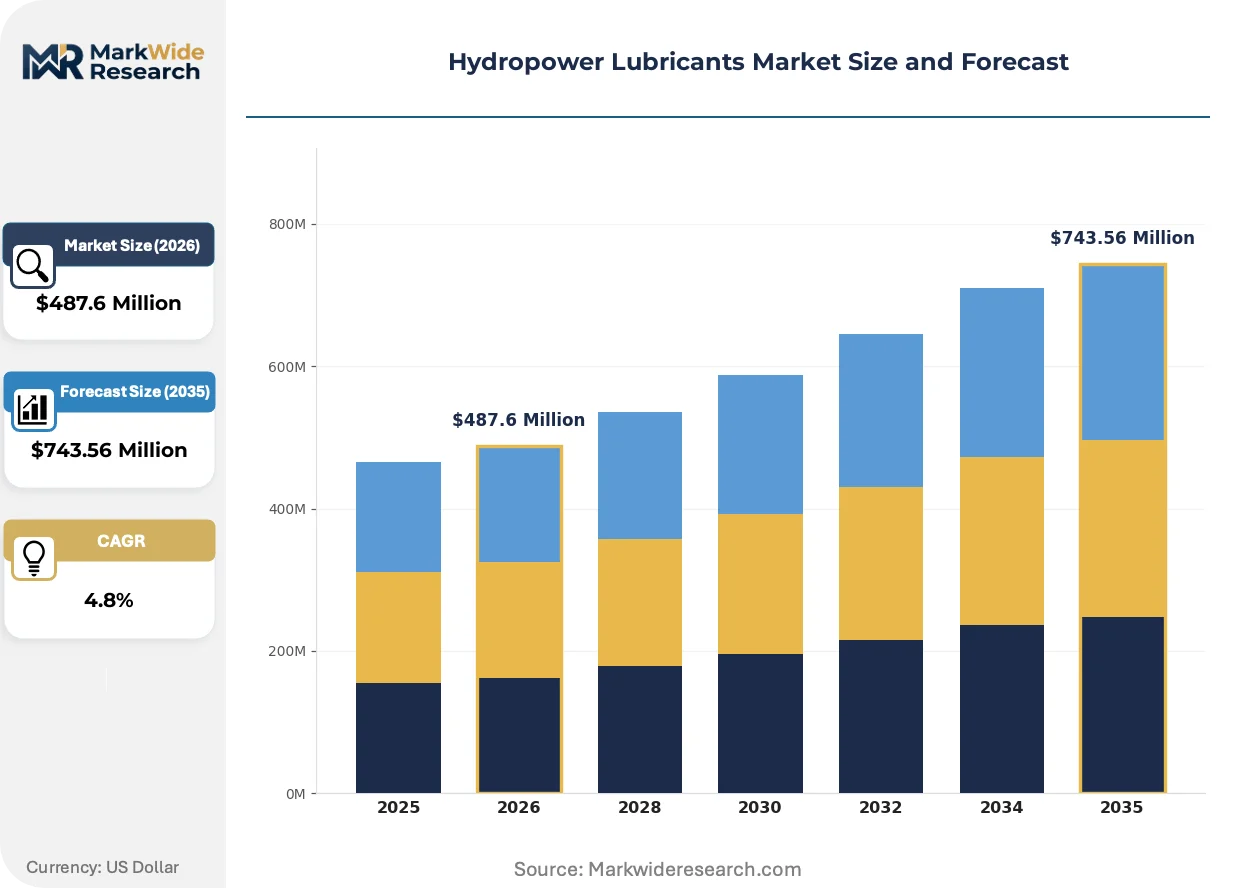
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Oils, Gear Oils, Greases, Compressor Oils Application: Turbines, Generators, Pumps, Conveyors Formulation: Synthetic, Mineral, Bio-based, Semi-synthetic End User: Utilities, OEMs, Maintenance Providers, Contractors |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, TotalEnergies SE, BP plc, FUCHS Petrolub SE, Idemitsu Kosan Co. Ltd., Sinopec Corporation, Kluber Lubrication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydropower Lubricants Market Strategic Shifts
Formulation science and regulatory compliance frameworks are converging to redefine product specifications, with biodegradability certification emerging as the primary axis of competitive differentiation.
Advanced condition monitoring systems are decentralizing maintenance planning across distributed hydropower fleets. Operators in Norway and Canada deploy real-time particle counters and moisture sensors to extend drain intervals based on actual fluid degradation rather than fixed schedules. This shift compresses the addressable market for routine bulk lubricant sales while expanding demand for analytical services and rapid-response regional distribution networks.
REACH authorization requirements are reshaping additive chemistry roadmaps across European manufacturing. ECHA's escalating scrutiny of boron and zinc compounds forces formulators to develop ashless anti-wear packages that maintain extreme-pressure performance in high-load turbine bearings. German and Swiss lubricant producers are accelerating partnerships with additive houses to secure proprietary chemistries ahead of sunset dates for legacy substances.
Utility procurement departments are consolidating supplier relationships around full-fluid-management contracts. Nordic and Alpine operators now bundle lubricant supply, waste collection, and re-refining services into single-source agreements that transfer environmental liability to vendors. This model displaces spot purchasing through industrial distributors and favors integrated suppliers with certified waste handling capabilities.
Hydropower Lubricants Market Segmentation
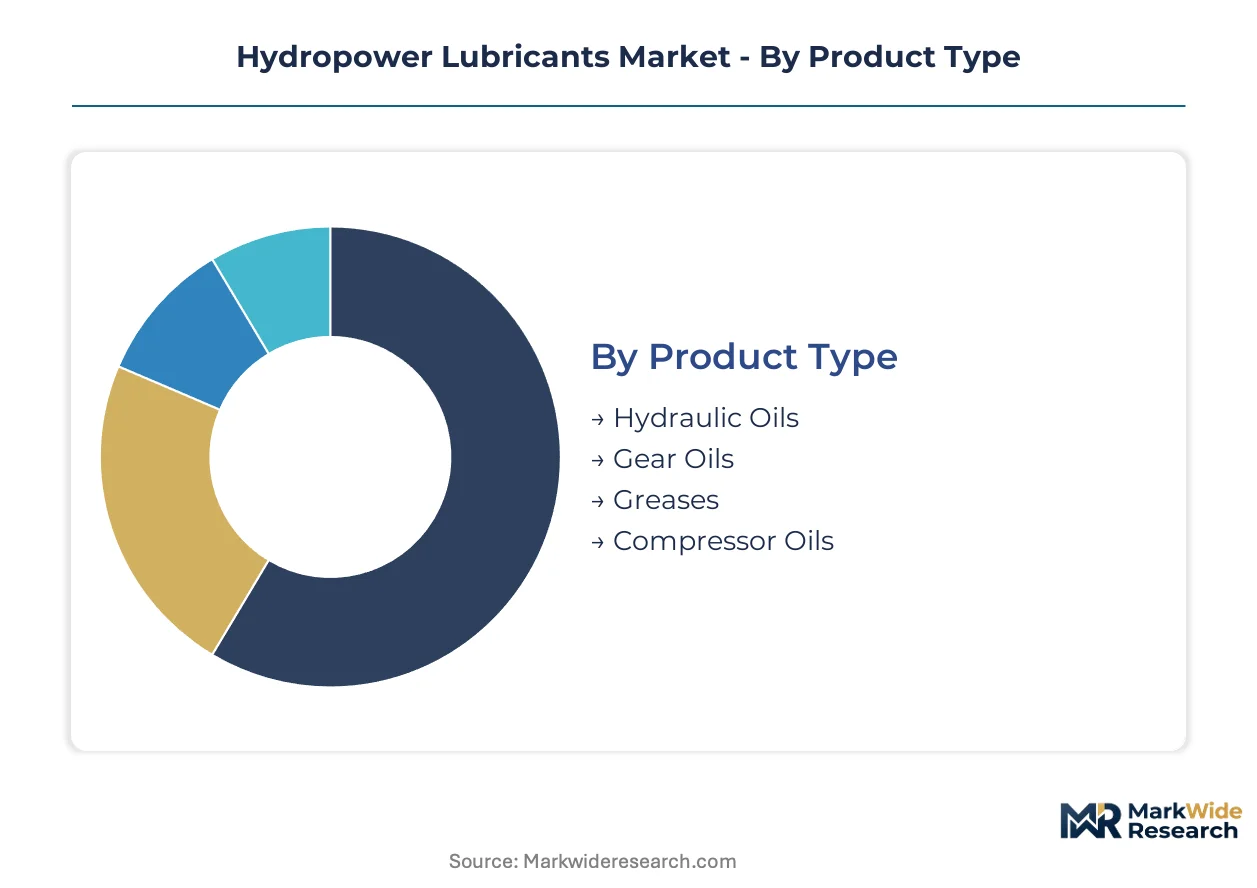
Segmentation in hydropower lubricants reveals distinct procurement patterns across fluid types, machinery applications, and environmental compliance tiers. Understanding these divisions enables suppliers to align formulation investments with specific operational stresses and regulatory thresholds.
Product Type:
Integration depth varies sharply: hydraulic oils operate as standalone circulating systems, while greases embed permanently within sealed bearing housings requiring infrequent replenishment.
- Hydraulic Oils:Formulated to ISO VG 32-68 specifications with zinc-free anti-wear packages for governor and wicket gate actuator systems. Demand concentrates across China's Yangtze basin modernization programs where state-owned operators prioritize extended drain intervals.
- Gear Oils:Synthetic ester and polyalphaolefin base stocks deliver thermal stability for high-load reduction gearboxes in pumped-storage facilities. Alpine corridor utilities in Switzerland and Austria specify these for frequent start-stop cycling regimes.
- Greases:Calcium sulfonate and lithium complex thickeners provide water resistance for turbine guide bearing applications.
- Compressor Oils:Rotary screw and reciprocating compressor formulations serve auxiliary air systems in powerhouse facilities.
Volume placements concentrate in Hydraulic Oils; the faster expansion belongs to Gear Oils.
Application:
Cost tier differentiation separates premium formulations for continuous-duty turbines from standard grades for intermittent auxiliary equipment.
- Turbines:Francis, Kaplan, and Pelton turbine designs require customized viscosity profiles and ashless additive chemistry to prevent valve sticking and bearing corrosion. European installations under EU Green Deal mandates drive specification shifts toward biodegradable formulations.
- Generators:Thrust and guide bearing lubrication demands high film strength oils with oxidation resistance for decades-long service intervals. China's Three Gorges and other cascade systems represent concentrated procurement for large-unit generator bearings.
- Pumps:Cooling water and drainage pump systems utilize standard hydraulic fluid specifications with shorter change intervals.
- Conveyors:Material handling equipment in powerhouse facilities operates on general industrial lubricant grades.
Procurement scale peaks with Turbine applications; Generator lubricant specifications are climbing fastest as aging infrastructure retrofits accelerate.
Formulation:
Customer type alignment maps synthetic and bio-based grades to utility direct procurement, while mineral oils persist through contractor spot purchasing.
- Synthetic:Polyalphaolefin and synthetic ester base stocks deliver extended drain intervals and thermal stability for high-head and pumped-storage applications. REACH compliance pressures in Europe accelerate displacement of mineral alternatives.
- Bio-based:Vegetable oil and synthetic ester formulations exceeding 60% OECD 301B biodegradability serve protected watershed installations. Nordic operators bundle these into full-fluid-management contracts transferring environmental liability to suppliers.
- Mineral:Conventional Group I and II base stocks retain cost advantage in non-sensitive installations.
- Semi-synthetic:Blended formulations balance performance and cost for mid-tier maintenance providers.
Volume concentrates in Mineral formulations; Bio-based specifications are expanding most quickly under watershed protection mandates.
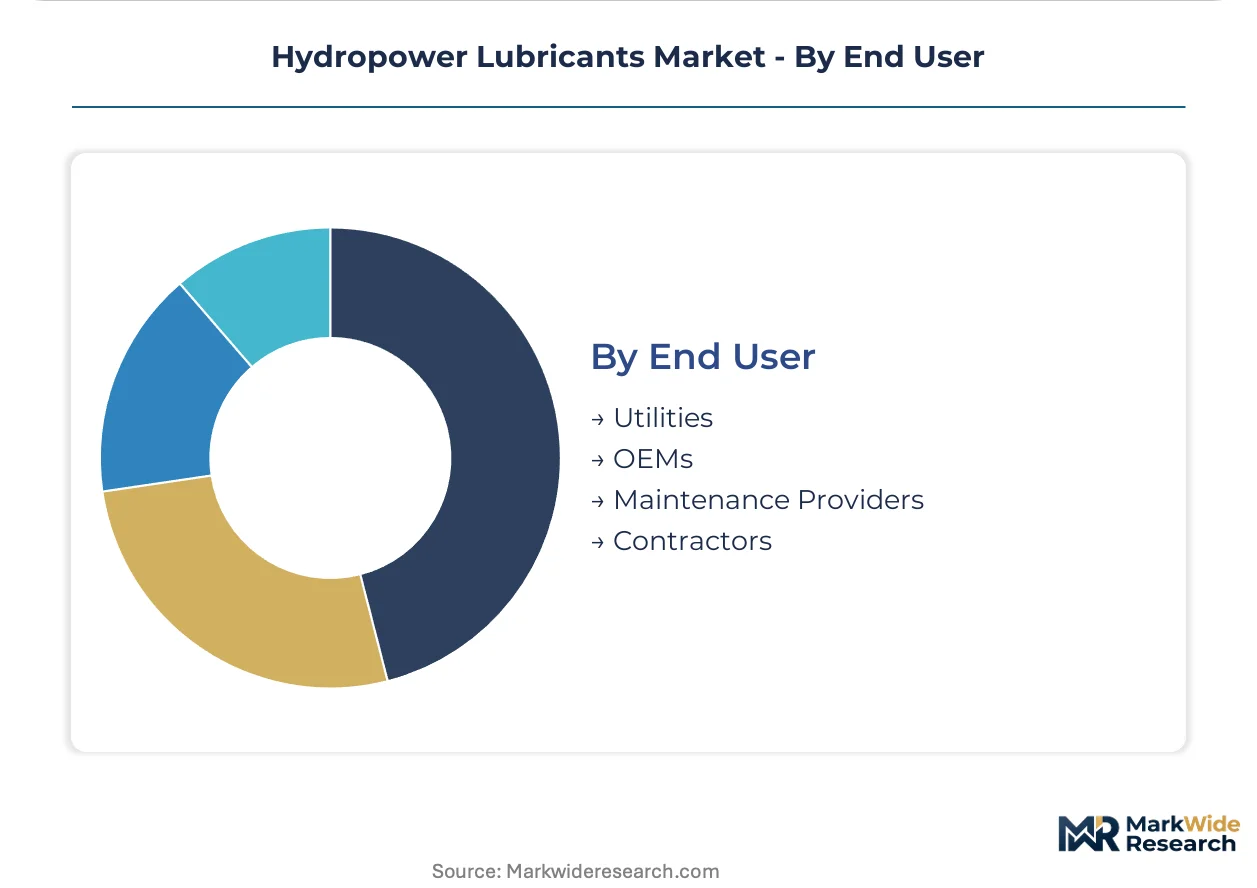
End User:
Supply concentration patterns favor integrated formulators serving OEM factory-fill programs, while regional blenders capture maintenance provider spot demand.
- Utilities:State-owned and investor-owned power generators specify premium synthetic and bio-based grades through multi-year supply agreements. China's state grid operators drive systematic specification upgrades across cascade system fleets.
- OEMs:Turbine manufacturers factory-fill new units with certified lubricants and mandate compatible maintenance fluids. Factory-fill programs in North America and Asia concentrate procurement with integrated polyalphaolefin suppliers.
- Maintenance Providers:Independent service contractors purchase through regional distribution networks with shorter lead time requirements.
- Contractors:Construction and commissioning teams utilize standard grades for temporary installations.
Contract volume aggregates with Utilities; OEM factory-fill specifications are gaining share fastest as new turbine installations accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hydropower lubricants concentrates in river basin systems with aging infrastructure and strict watershed protection mandates. State-owned operators in China drive systematic procurement upgrades across cascade networks. European utilities face compulsory formulation shifts under environmental compliance deadlines.
China
State Grid Corporation and China Three Gorges Corporation are retrofitting turbine fleets across the Yangtze River basin. MEE water quality standards govern lubricant disposal practices near major cascade installations. Sichuan and Yunnan provinces host concentrated procurement activity for high-performance hydraulic fluids in governor systems.
United States
FERC-licensed facilities face spill prevention mandates under Clean Water Act provisions. The EPA administers contingency planning requirements for lubricant releases at federally regulated hydropower sites. Pacific Northwest utilities in Washington and Oregon specify synthetic ester formulations for salmon-protected watersheds.
Switzerland
Alpine hydropower operators bundle lubricant supply into full-fluid-management contracts transferring environmental liability. REACH compliance pressures accelerate displacement of mineral oil bases in protected river corridors. The Gotthard and Grimsel regions concentrate maintenance provider networks serving high-head pumped-storage facilities.
Norway
Statkraft and other state-owned generators deploy real-time fluid monitoring to extend drain intervals in fjord-adjacent installations. The country's watershed protection framework mandates OECD 301B-certified formulations exceeding 60% biodegradability. Western Norway hydropower clusters drive demand for regional blending capabilities.
Brazil
Itaipu Binacional and regional utilities modernize Francis turbine fleets across the Paraná River basin. ANVISA and environmental agency regulations shape additive chemistry roadmaps for Amazon watershed installations. São Paulo and Minas Gerais states concentrate procurement for generator bearing lubrication in large-unit facilities.
Hydropower Lubricants Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. Integrated oil majors dominate factory-fill programs through captive base stock supply chains. Regional blenders capture maintenance provider demand via shorter lead times in alpine corridors. Strategic archetypes include polyalphaolefin-integrated majors, synthetic ester specialists, and regional service-network operators. Competitive moves concentrate on formulation partnerships with additive houses and geographic expansion of blending assets.
Among the integrated majors, ExxonMobil Corporation and Shell plc anchor the factory-fill tier through polyalphaolefin supply chain control. FUCHS Petrolub SE occupies a position within the regional service-network archetype, exemplifying proximity-based strategies in European alpine markets. These three entities represent distinct competitive vectors: upstream-integrated supply security, specialized hydraulic fluid certification, and decentralized blending responsiveness.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| TotalEnergies SE |
| BP plc |
| FUCHS Petrolub SE |
| Idemitsu Kosan Co. Ltd. |
| Sinopec Corporation |
| Kluber Lubrication |
| Others |
Value Chain & Pricing Dynamics
Tribology formulation chemists concentrate in German and Swiss technical institutes, creating labor-cost differentials that widen pricing spreads between premium synthetic ester formulations and standard mineral oil alternatives.
Pricing Analysis
Volume concentrates in mineral oil hydraulic fluids for routine maintenance, while margins accrue to synthetic ester and bio-based grades certified for protected watersheds. Price differentiation hinges on OECD 301B biodegradability certification and REACH compliance tier, with Nordic utilities paying premiums for full-fluid-management contracts. Cost compression in mid-tier semi-synthetic formulations is intensifying as Chinese state-owned operators consolidate procurement. Maintenance providers remain most price-sensitive, while OEM factory-fill programs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Polyalphaolefin and synthetic ester base stocks rest on specialty chemical producers in Germany and the United States, creating concentrated input dependencies for formulators. Key dependencies include Group III+ base oils, ashless anti-wear additive packages, and biodegradable thickener systems. Single-source vulnerability persists for zinc-free additive chemistry following ECHA sunset timelines. Distribution runs through regional blending networks in alpine corridors, with integrated majors controlling factory-fill channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydropower lubricants sector sits in a formulation-transition phase, as bio-based and synthetic ester technologies displace mineral oil bases under tightening watershed protection mandates.
For Market Incumbents: Lock in additive house partnerships to secure proprietary ashless anti-wear chemistries ahead of REACH authorization deadlines. Extend regional blending footprints in China's Yangtze basin to capture retrofit procurement from state-owned operators modernizing aging turbine fleets. Prioritize certification investment in OECD 301B and Blue Angel tiers to defend premium positioning as European utilities consolidate supplier relationships. For New Entrants and Emerging Players: Digital fluid monitoring platforms offer a technology-first wedge into predictive maintenance contracts currently underserved by traditional formulators. Target pumped-storage expansion projects in the United States and China for thermal-stress-resistant synthetic gear oil procurement. Pursue white-label regional blending partnerships in Norway and western Canada to bypass captive supply chains. For Investors and Strategic Acquirers: Re-rating potential sits with regional service-network operators given accelerating utility demand for full-fluid-management contracts transferring environmental liability. Long-term viability favors blenders with certified waste handling and re-refining capabilities over pure-play formulators. Watch ECHA additive authorization timelines as inflection indicators for consolidation pressure on legacy mineral oil-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Captive polyalphaolefin supply secures margin control for OEM factory-fill programs. |
| Regional Blending Network Expansion | Alpine corridor assets reduce lead times for maintenance providers serving high-head installations. |
| Biodegradability Certification Investment | OECD 301B and EU Ecolabel approvals unlock mandatory procurement from European utilities. |
| Digital Fluid Monitoring Integration | IoT sensor deployment enables subscription-based predictive maintenance contracts. |
| Waste Handling and Re-refining Capability | Certified environmental liability transfer attracts Nordic full-fluid-management bundling. |
Study Parameters
Document review covered trade association technical standards, ECHA authorization databases, and utility procurement records, complemented by interviews with lubricant formulation chemists, hydropower maintenance directors, and OEM procurement specialists. Secondary sources included customs data on base stock imports, SEC filings of integrated oil majors, and MEE water quality enforcement reports. Bottom-up volume estimates from turbine fleet counts and top-down value triangulation from utility spending disclosures were cross-validated.
Segment-level outputs across the projection horizon reflect modeled interactions between formulation type, application stress, and regulatory compliance tier. The analytical framework incorporated synthetic ester technology adoption curves, REACH-driven additive substitution timelines, and pumped-storage capacity expansion patterns. CAGRs were derived from elasticity-adjusted demand functions rather than extrapolated historical trends.
Several conditions sit outside the modeled scope, including unannounced additive chemistry bans, abrupt shifts in crude oil price differentials affecting base stock economics, and geopolitical disruptions to German specialty chemical supply. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology maturation curves. A small set of named triggers warrants ongoing watch: ECHA sunset date accelerations, China's MEE disposal standard tightening, and Nordic utility consolidation of supplier panels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Kingdom Lubricants Market
Lubricants
China Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Anti-Static Oil Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Offshore Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Bangladesh Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Lubrication Equipment Market