
 Poland Data Center Storage Market | 2026-2036
Poland Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Data Center Storage Market Insights
The EU Green Deal is hardening carbon efficiency mandates for Polish data center operators, pushing facility owners toward lower-power storage architectures and renewable power sourcing. Dell Technologies leverages its direct sales channel and local assembly footprint to compete for enterprise refresh cycles. Huawei Technologies anchors its position through aggressive pricing on all-flash arrays and established relationships with Polish telecom carriers. NetApp specializes in cloud-adjacent storage software, differentiating through data management tools that bridge on-premises and colocation environments.
Poland data center storage encompasses solid-state, hard disk, hybrid, and tape systems engineered for enterprise-grade durability, with SSD arrays typically rated for millions of write cycles and HDD platforms optimized for sequential throughput in petabyte-scale deployments. These systems serve cloud storage, backup, analytics, and virtualization workloads across IT, financial services, healthcare, and retail verticals. SSD configurations command premium positioning for latency-sensitive applications, while hybrid deployments are gaining traction among mid-market adopters seeking cost-performance balance. Tape retains niche dominance in long-term archival use cases where air-gapped compliance and extreme cost-per-gigabyte economics outweigh access speed requirements.
Polish data center development falls under the Energy Regulatory Office for power allocation and the General Inspectorate of Environmental Protection for emissions compliance, while CE marking and EU F-Gas Regulation govern equipment import and cooling system standards. National broadband expansion programs and EU cohesion funds are channeling infrastructure investment toward secondary cities, altering the geographic distribution of storage demand. Stakeholders must monitor Warsaw's power grid saturation and emerging cable landing points on the Baltic coast as determinants of future capacity deployment.
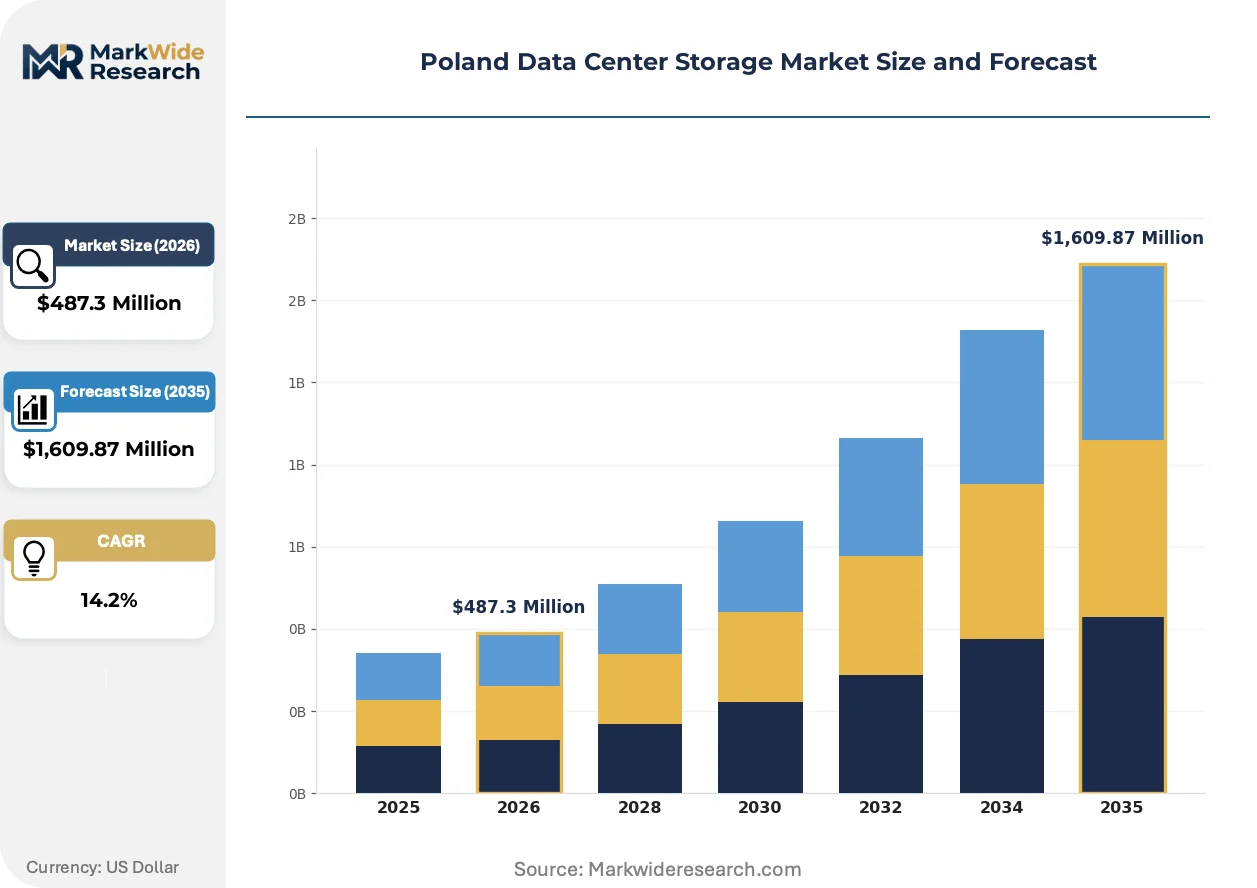
Market Dynamics
EU Green Deal carbon efficiency mandates are compressing Polish data center operator margins while simultaneously accelerating storage architecture refreshes toward lower-power solid-state and renewable-powered deployments.
Growth Catalysts
- EU F-Gas Regulation:Cooling system phase-downs are forcing facility retrofits that bundle storage infrastructure upgrades, creating replacement pull through Warsaw's hyperscaler corridor.
- Financial Services Data Retention:Polish banks and insurers are expanding petabyte-scale archival capacity to satisfy EU-wide supervisory mandates on transaction record longevity.
- NVMe-over-Fabrics:Latency-sensitive analytics workloads in Warsaw's fintech cluster are driving all-flash array penetration above hybrid alternatives.
Market Restraints
- Power Grid Saturation:Warsaw metropolitan substations face allocation bottlenecks that delay storage-rich facility commissioning by 18-24 months.
- NAND Flash Supply Concentration:Polish buyers remain exposed to Asian foundry output volatility and shipping lane disruptions through the Suez corridor.
- CE Marking Complexity:Equipment import certification timelines for electromagnetic compatibility testing extend vendor lead times unpredictably.
Strategic Opportunities
- Baltic Cable Landing Points:Emerging fiber interchanges near Gdańsk and Szczecin offer greenfield data center sites with direct submarine connectivity to Nordic and Western European hubs.
- Healthcare Imaging Archives:Polish hospital digitization mandates are opening petabyte-scale tape and cold storage demand for radiological record retention.
- EU Cohesion Funds:Infrastructure grants are channeling secondary city broadband investment toward Kraków, Wrocław, and Łódź, redistributing storage demand geographically.
Industry Challenges
- Legacy Tape Migration:Long-tenured archival systems in public sector data centers resist seamless cloud-tier integration, forcing costly bridge infrastructure.
- Specialized Technician Scarcity:NVMe fabric administration and liquid cooling maintenance skills concentrate in Warsaw, constraining facility expansion to provincial markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Data Center Storage Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: SSD, HDD, Hybrid, Tape Application: Cloud Storage, Data Backup, Big Data Analytics, Virtualization End User: IT & Telecom, BFSI, Healthcare, Retail Deployment Model: On-Premises, Colocation, Managed Services, Hybrid Cloud |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Huawei Technologies, NetApp, IBM Corporation, Cisco Systems, Hitachi Vantara, Lenovo Group, Comarch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Data Center Storage Market Trends and Innovations
Storage-class memory convergence and regulatory carbon accounting are restructuring procurement priorities across Polish enterprise and colocation buyers. Three developments are compressing traditional technology refresh cycles.
Computational storage drives are unifying processing and persistence at the device level, reducing data movement overhead for analytics-intensive workloads. Warsaw-based financial services operators are piloting these architectures for real-time risk calculation. The technology is unifying previously separate server and storage procurement decisions into single-vendor negotiations.
EU Green Deal sustainability disclosure requirements are mandating granular carbon reporting for data center operators. Polish facilities must now document embodied emissions in storage hardware and renewable power sourcing for cooling loads. CE marking extensions now cover circularity documentation, affecting import timelines for Asian-origin solid-state arrays.
Consumption-based financing is displacing capital purchase models for mid-market Polish enterprises. Colocation providers are bundling storage-as-a-service offerings that transfer hardware obsolescence risk to facility operators. Healthcare and retail verticals in Kraków and Wrocław are adopting these arrangements most aggressively, compressing traditional three-year depreciation cycles.
Poland Data Center Storage Market Segmentation
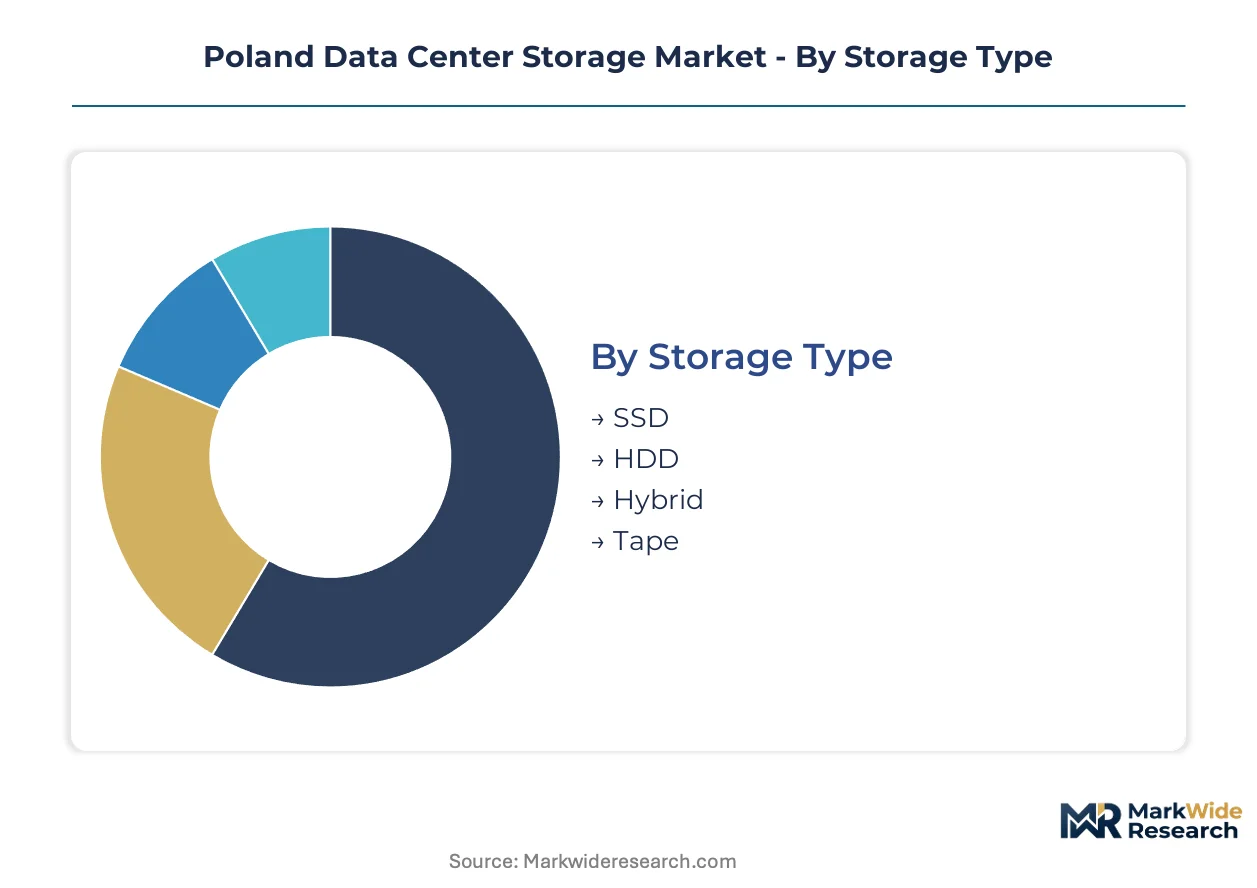
Storage procurement patterns in Poland diverge sharply across workload profiles and regulatory exposure. CE marking requirements and EU F-Gas Regulation compliance create divergent certification burdens that reshape vendor selection and deployment timelines for each segment category.
Storage Type:
CE marking mandates electromagnetic compatibility testing for all solid-state and magnetic media imports, with cooling-integrated arrays facing additional EU F-Gas Regulation scrutiny for refrigerant-based thermal management systems.
- SSD:Non-volatile NAND flash configurations deliver sub-millisecond latency for transactional databases. Warsaw fintech operators are standardizing on NVMe-over-Fabrics SSD arrays to satisfy real-time risk calculation requirements under Polish Financial Supervision Authority data availability mandates.
- HDD:Shingled magnetic recording and conventional perpendicular drives optimize sequential throughput for petabyte-scale warm storage. Kraków and Wrocław enterprise buyers favor HDD for backup repositories where access frequency stays below weekly patterns.
- Hybrid:Tiered architectures combine flash caching with magnetic capacity for cost-performance balance. Mid-market adopters in Łódź manufacturing clusters deploy hybrid systems to bridge budget constraints and latency requirements.
- Tape:Linear Tape-Open and enterprise tape formats provide air-gapped archival for compliance retention. Polish insurers maintain petabyte-scale tape libraries to satisfy EU supervisory mandates on multi-decade transaction record preservation.
HDD sits at the top of the volume ranking, with SSD climbing the fastest.
Application:
Workload-specific performance requirements drive divergent infrastructure investments across Polish verticals, with latency tolerance and data gravity determining whether deployments anchor in Warsaw hyperscaler facilities or distribute to secondary cities.
- Cloud Storage:Object and file services delivered from colocation facilities. Warsaw hyperscaler corridors concentrate cloud storage demand near fiber interchanges with direct Nordic connectivity.
- Data Backup:Immutable snapshot and disaster recovery repositories. Polish banks facing KNF mandates are expanding backup capacity with ransomware-resistant air-gapped architectures.
- Big Data Analytics:High-throughput storage for machine learning and business intelligence pipelines. Gdańsk emerging cable landing points are attracting analytics workloads requiring submarine bandwidth to Western European data lakes.
- Virtualization:Shared storage for VMware and Hyper-V server consolidation. Healthcare providers in Poznań deploy virtualization storage to support electronic health record systems under national digitization directives.
Cloud Storage commands the largest installed base, with Big Data Analytics expanding most quickly.
End User:
Vertical-specific retention rules and availability requirements fragment procurement patterns, with financial services and healthcare facing the most stringent supervisory oversight.
- IT & Telecom:Carrier-neutral facilities and enterprise IT infrastructure. Polish telecom operators anchor storage demand through 5G core network data retention and subscriber analytics platforms.
- BFSI:Banking, financial services, and insurance compliance archives. EU-wide supervisory mandates on transaction longevity are forcing petabyte-scale expansion across Warsaw-based institutions.
- Healthcare:Imaging archives and electronic health record systems. Polish hospital digitization programs are opening cold storage demand for radiological retention under national healthcare IT modernization.
- Retail:Customer analytics and supply chain optimization. E-commerce operators in Kraków and Wrocław deploy flash storage for real-time personalization engines.
BFSI dominates current capacity deployment, with Healthcare gaining share fastest.
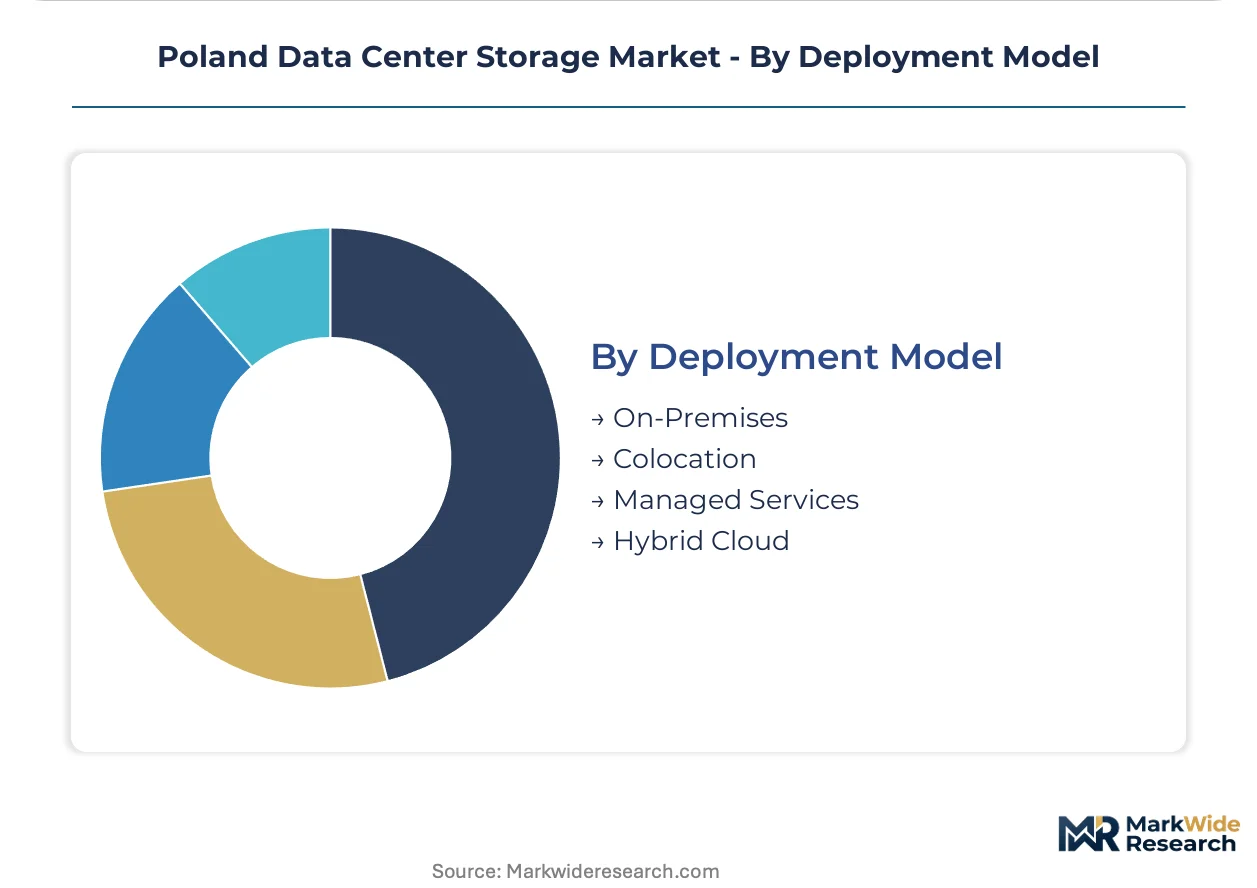
Deployment Model:
Capital availability and technical staffing constraints determine whether Polish enterprises own infrastructure or transfer operational burden to facility operators and managed service providers.
- On-Premises:Customer-owned data centers with direct hardware control. Large Warsaw enterprises retain on-premises storage for workloads with sovereignty requirements or sub-millisecond latency demands.
- Colocation:Leased space in multi-tenant facilities with self-managed hardware. Mid-market buyers are shifting toward colocation to bypass Warsaw power grid allocation bottlenecks.
- Managed Services:Fully outsourced storage operations with SLA-guaranteed availability. Healthcare and retail verticals adopt managed services most aggressively to address specialized technician scarcity outside Warsaw.
- Hybrid Cloud:Coordinated on-premises and public cloud storage tiers. Financial services operators deploy hybrid models to balance regulatory data residency with burst capacity for stress testing.
On-Premises maintains the largest footprint, with Hybrid Cloud showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's data center storage sector traces its modern lineage to the post-2004 EU accession period, when telecommunications liberalization and banking sector modernization created the first enterprise-grade storage demand clusters around Warsaw and Kraków.
Warsaw Metropolitan Area
Hyperscaler facility construction and fintech data retention mandates dominate storage procurement in the capital region. The Energy Regulatory Office allocates power through constrained metropolitan substations, creating 18-24 month commissioning delays for new storage-rich deployments. Warsaw's fiber interchange density attracts Dell Technologies and Huawei Technologies demonstration facilities near the city's carrier-neutral zones.
Kraków
Healthcare digitization and shared service center expansion drive mid-market hybrid storage adoption in Poland's second city. EU cohesion funds channel broadband infrastructure investment toward Kraków's hospital networks, opening petabyte-scale imaging archive demand. Local colocation providers bundle consumption-based storage offerings for healthcare and retail verticals.
Wrocław
Manufacturing automation and logistics platform development anchor HDD and hybrid array procurement in Lower Silesia's industrial corridor. The General Inspectorate of Environmental Protection enforces emissions compliance for facility expansions near the Oder River basin. Wrocław's technical university pipeline supplies NVMe fabric administration skills scarce elsewhere outside Warsaw.
Gdańsk and Baltic Coast
Emerging submarine cable landing points position Pomerania as Poland's alternative data center geography with direct Nordic and Western European connectivity. Greenfield facility development bypasses Warsaw's power grid saturation while serving latency-tolerant analytics workloads. The region's offshore wind expansion aligns with EU Green Deal renewable sourcing mandates for storage facility cooling loads.
Łódź
Textile-to-technology industrial transition and central logistics hub status concentrate mid-market enterprise storage demand in this historic manufacturing center. National broadband programs extend fiber connectivity to Łódź's revitalized industrial zones, redistributing storage demand from the capital. Local managed service providers address technician scarcity through remote Warsaw-based administration contracts.
Poland Data Center Storage Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the NVMe fabric and software-defined storage dimension, while HDD array specialists compete on petabyte-scale cost efficiency. The vendor base stratifies into three tiers: integrated infrastructure conglomerates with direct Polish assembly footprints, Asian-origin flash specialists leveraging carrier relationships, and pure-play software vendors bridging on-premises and colocation environments. Dominant competitive moves include strategic partnerships with Warsaw telecom operators and portfolio diversification into consumption-based financing models.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions anchored by local assembly capabilities and enterprise direct sales channels. Huawei Technologies exemplifies the Asian-origin flash specialist archetype through established Polish telecom carrier relationships. NetApp represents the cloud-adjacent software tier with data management tools spanning on-premises and colocation deployments. IBM Corporation and Hitachi Vantara sit within the legacy enterprise refresh segment serving long-tenured Polish banking and public sector accounts.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| NetApp |
| IBM Corporation |
| Cisco Systems |
| Hitachi Vantara |
| Lenovo Group |
| Comarch |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler-backed facility operators and private-equity-rolled-up colocation providers anchor procurement decisions in Poland, compressing vendor margins through consolidated buying power while simultaneously demanding extended financing terms that reshape supplier cash flow cycles across the Warsaw metropolitan corridor.
Pricing Analysis
Consumption-based financing models now dominate enterprise procurement, displacing capital purchase arrangements across mid-market healthcare and retail buyers in Kraków and Wrocław. Price differentiation hinges on CE marking certification tiers and renewable power sourcing documentation under EU Green Deal disclosure rules. Cost compression in all-flash arrays is intensifying because NAND flash supply concentration exposes Polish buyers to Asian foundry volatility. Mid-market manufacturing clusters in Łódź exhibit the highest price sensitivity, while Warsaw fintech operators prioritize latency performance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by Polish financial institutions and telecom carriers compel vendors to qualify secondary component suppliers beyond primary Asian foundry relationships. NAND flash controllers and enterprise HDD substrates draw from Taiwan, South Korea, and China, while precision cooling components and power distribution units rest on German and Dutch manufacturing bases. Single-source vulnerability in Baltic Sea shipping lanes exposes delivery schedules to Suez corridor disruption risks. Distribution runs through Warsaw-based value-added resellers with direct assembly partnerships for Dell Technologies and local Huawei Technologies integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland data center storage operates as a regulatory compounder where EU F-Gas Regulation cooling system phase-downs and Green Deal carbon disclosure mandates accelerate infrastructure replacement cycles beyond natural technology obsolescence.
For Market Incumbents: Anticipate margin compression from Chinese-origin flash specialists leveraging carrier relationships to undercut premium positioning. Defend wallet share by deepening backward integration into liquid cooling system assembly within Polish free economic zones. Prioritize CE marking pre-certification investments to compress import timelines for solid-state arrays facing electromagnetic compatibility testing bottlenecks. For New Entrants and Emerging Players: EU Cohesion Funds in Poland open a window for secondary city colocation development bypassing Warsaw power grid saturation. Target Gdańsk cable landing point adjacencies for latency-tolerant analytics workloads and Łódź manufacturing corridor hybrid storage demand. Differentiate through managed services bundling that transfers hardware obsolescence risk to facility operators addressing technician scarcity outside the capital. For Investors and Strategic Acquirers: Valuations sit cheapest among regional managed service providers with established healthcare vertical relationships and consumption-based contract backlogs. Long-term viability centers on facilities with secured renewable power offtake and Baltic coast geographic diversification. Watch Warsaw metropolitan substation allocation announcements as the inflection signal for capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-over-Fabrics Deployment | Warsaw fintech operators satisfy Polish Financial Supervision Authority real-time availability mandates through sub-millisecond latency architectures. |
| Renewable Power Sourcing | Gdańsk offshore wind expansion aligns facility cooling loads with EU Green Deal carbon disclosure requirements for storage hardware. |
| Consumption-Based Financing | Kraków healthcare providers transfer capital risk to colocation operators while compressing traditional three-year depreciation cycles. |
| Tape-to-Cloud Migration | Polish insurers bridge legacy archival systems toward cloud-tier integration under EU supervisory data retention mandates. |
| Baltic Cable Landing Expansion | Pomeranian greenfield sites bypass Warsaw grid constraints while serving Nordic-connected analytics workloads. |
Research Methodology
Multiple input streams — hyperscaler facility operators, enterprise IT procurement directors, colocation sales executives, and systems integration specialists — were reconciled against Polish Energy Regulatory Office power allocation records, CE marking certification databases, and EU cohesion fund disbursement filings. Secondary validation drew from General Inspectorate of Environmental Protection emissions compliance reports, hyperscaler capital expenditure disclosures, and Baltic submarine cable development announcements. Bottom-up storage capacity deployment estimates were triangulated against top-down infrastructure investment flow analysis.
Historical capacity commissioning patterns were cross-referenced against expert panel assessments of Warsaw grid saturation timelines and regional broadband expansion trajectories. Segmentation modeling incorporated storage type, deployment model, end-user vertical, and application workload dimensions across the projection horizon. CAGRs were derived from fitted growth curves calibrated to EU regulatory milestone schedules and Polish national healthcare digitization program phases. Forecast inputs included NAND flash supply elasticity assumptions and F-Gas Regulation refrigerant phase-down compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended Warsaw power grid allocation delays or Baltic shipping corridor disruptions. Deviation in EU Green Deal carbon pricing implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Cloud Storage Market