
 Indonesia Data Center Construction Market | 2026-2036
Indonesia Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Construction Market Insights
Multi-source engineering procurement is repositioning how hyperscale clients contract construction services in Indonesia. PT AECOM Indonesia leverages its integrated design-build portfolio to capture turnkey mandates from international cloud operators. Jacobs Engineering Group Inc. sustains competitive advantage through deep specialization in mission-critical cooling and power redundancy systems. Arup Group anchors its presence with advanced seismic engineering capabilities suited to Indonesia's tectonic risk profile.
Indonesia data center construction encompasses the planning, engineering, physical build-out, and commissioning of facilities housing servers, storage, and networking equipment, typically requiring power densities of 5-30 kW per rack and tier-certified uptime architectures. These structures serve as the physical backbone for digital commerce, cloud services, and government data sovereignty. Hyperscale facilities command the largest capital allocation pools as global cloud providers commit to multi-hundred-megawatt campuses across the archipelago. Modular data centers are gaining traction among telecom companies and enterprises seeking rapid deployment with standardized factory-built components. Edge computing centers remain nascent but attract pilot investment from content delivery networks targeting latency-sensitive applications in secondary cities.
Indonesia's Ministry of Communication and Informatics enforces data localization under Government Regulation No. 71 of 2019, compelling foreign platforms to store citizen data within national borders and directly stimulating domestic facility construction. BIS-equivalent electrical and fire safety standards, alongside Jakarta's building code amendments for high-density power infrastructure, shape equipment specifications and contractor qualification requirements. Stakeholders must monitor permitting velocity in Batam and Surabaya special economic zones, where regulatory streamlining could redistribute construction activity away from saturated Greater Jakarta corridors.
Market Dynamics
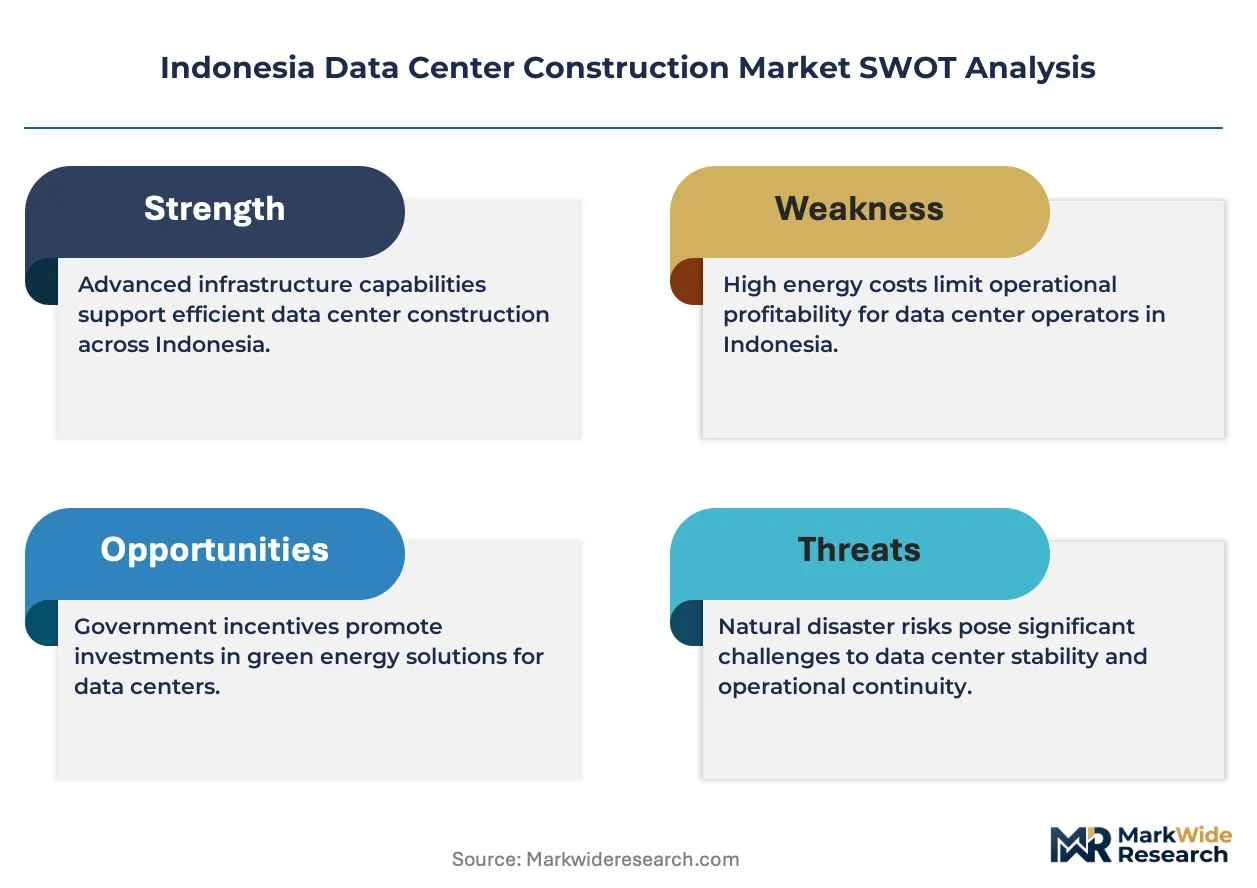
Government Regulation No. 71 of 2019 is the dominant force restructuring Indonesia's data center construction pipeline, compelling foreign cloud operators to build sovereign facilities rather than lease offshore capacity. This localization mandate has triggered a wave of domestic greenfield projects concentrated in Greater Jakarta and Batam.
Growth Catalysts
- Data Localization Mandate:Government Regulation No. 71 of 2019 requires foreign digital platforms to store Indonesian citizen data within national borders, directly stimulating domestic facility construction.
- Submarine Cable Convergence:Batam's position as a landing point for multiple international submarine cables creates natural aggregation points for hyperscale campus development.
- Liquid Cooling Adoption:Rising rack power densities above 30 kW in AI training clusters are accelerating demand for advanced thermal management systems in new builds.
Market Restraints
- Copper and Steel Input Volatility:Electrical busbar and structural steel price fluctuations compress contractor margins on fixed-price turnkey contracts.
- Specialized Contractor Concentration:Seismic engineering and mission-critical cooling expertise remains concentrated among a handful of qualified firms, creating bidding bottlenecks.
- Grid Interconnection Queues:PLN's 150 kV and 500 kV transmission upgrade timelines often lag behind data center commissioning schedules in Greater Jakarta.
Strategic Opportunities
- Surabaya Special Economic Zone:Regulatory streamlining and improved submarine cable connectivity position East Java as an alternative to saturated Jakarta corridors.
- Modular Edge Deployment:Factory-built edge modules offer rapid deployment pathways for content delivery networks targeting latency-sensitive gaming and streaming in secondary cities.
- Renewable Energy Integration:PLN's geothermal and hydroelectric capacity expansion creates pathways for 24/7 carbon-free power matching in new developments.
Industry Challenges
- Mission-Critical Certification Talent:Shortages of Uptime Institute and TIA-942 certified commissioning engineers extend project handover timelines.
- Seismic Design Complexity:Indonesia's tectonic activity demands specialized structural engineering that increases design-cycle duration and contractor qualification thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Construction Market |
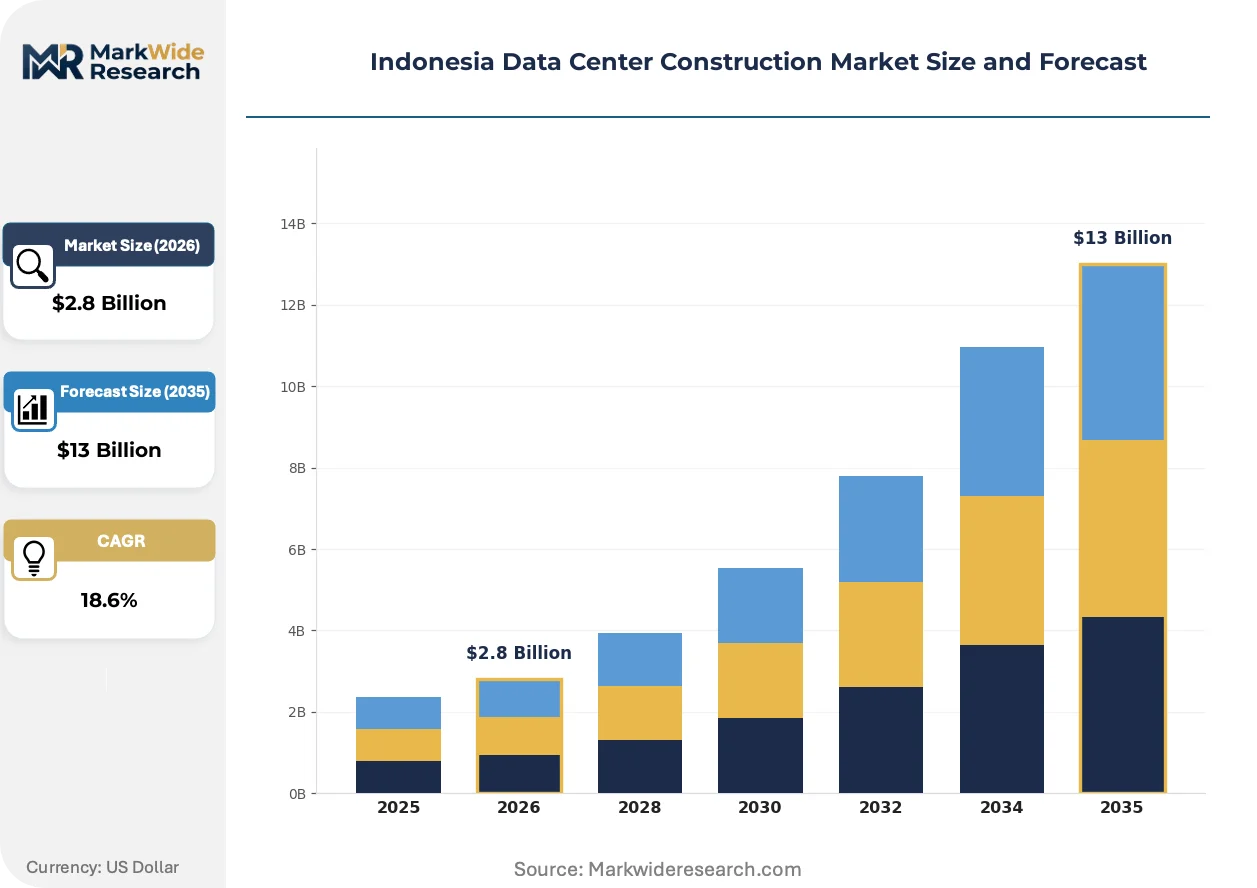
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Traditional Data Centers, Hyperscale Facilities, Edge Computing Centers Technology: Cooling Solutions, Power Distribution Units, Racking Systems, Fire Suppression Systems End User: Cloud Service Providers, Telecom Companies, Enterprises, Government Agencies Delivery Model: Turnkey Solutions, Design-Build Services, Managed Services, Consulting Services |
| Companies Covered | Jacobs Engineering Group Inc., PT Arkonin, Aurecon Group Pty Ltd, Aesler Group International, DSCO Group Pte Ltd, PT AECOM Indonesia, Turner & Townsend, NTT Facilities, Arup Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Construction Market Trends and Innovations
Hyperscale operators are fundamentally reconfiguring how physical infrastructure gets specified, procured, and delivered across the archipelago. Three interconnected shifts are compressing traditional construction timelines while raising technical performance benchmarks.
Direct liquid cooling is rewriting thermal architecture standards for high-density AI training halls. This technology circulates dielectric fluid directly to chip packages, enabling sustained power densities above 50 kW per rack that air-cooled designs cannot match. Cloud operators with GPU-heavy workloads are mandating liquid-ready designs in new RFPs, forcing mechanical contractors to retrain installation crews and source specialized coolant distribution units from limited qualified suppliers.
Indonesia's Ministry of Communication and Informatics continues tightening enforcement of Government Regulation No. 71 of 2019 through periodic compliance audits of foreign platform operators. This regulatory pressure is pushing international cloud providers from lease-back models toward owned-asset strategies with full design control. Financial services and healthcare verticals are most affected, with these sectors now requiring tier-certified facilities with documented Indonesian data residency.
Contracting structures are evolving from discrete design-bid-build phases toward integrated turnkey mandates with performance guarantees. Hyperscale clients now bundle civil, mechanical, electrical, and commissioning scope under single-point accountability contracts that penalize schedule and PUE misses. This consolidation is most visible in Greater Jakarta, where international operators have established preferred contractor panels with pre-negotiated risk allocation frameworks.
Indonesia Data Center Construction Market Segmentation
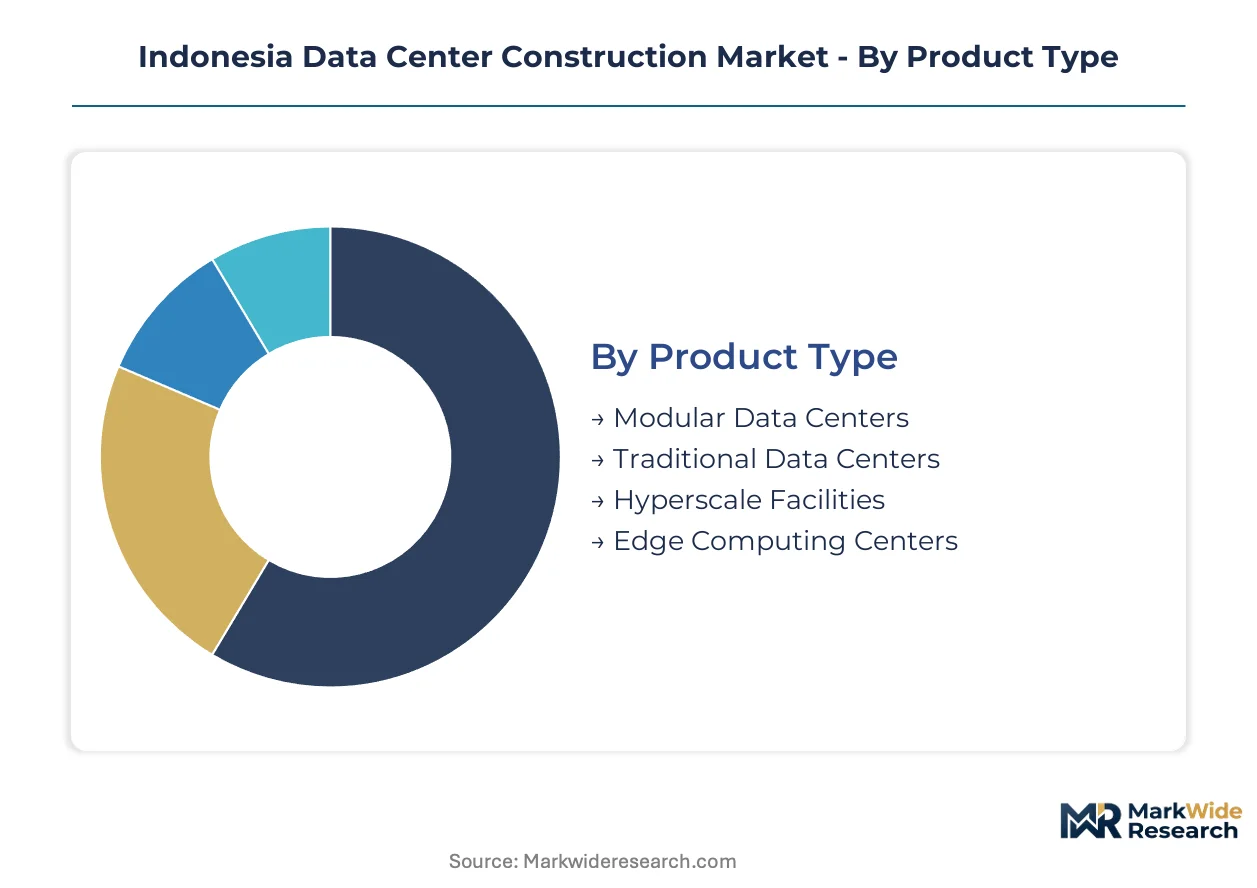
Construction demand in Indonesia fragments sharply across facility scale and technical architecture. Each segment imposes distinct procurement patterns, contractor qualification thresholds, and commissioning protocols that reshape competitive positioning across the archipelago.
Product Type:
Supply concentration among specialized EPC contractors varies dramatically by facility scale, with hyperscale mandates demanding integrated capabilities that modular specialists cannot replicate.
- Hyperscale Facilities:Campus-scale developments exceeding 50 MW of critical IT load require multi-phase civil engineering with dedicated substations and liquid-cooled halls. Demand concentrates in Greater Jakarta and Batam where PLN transmission upgrades and submarine cable landings converge, though grid interconnection queues frequently compress contractor margins.
- Traditional Data Centers:Enterprise-grade facilities with 5-15 MW capacity utilize conventional air-cooled architectures and tier-certified redundancy. State-owned enterprises and financial institutions in Jakarta drive procurement, constrained by BIS-equivalent electrical standards and seismic engineering requirements.
- Modular Data Centers:Factory-built enclosures with standardized power and cooling modules enable rapid deployment for telecom edge expansion. Telkomsel and Indosat Ooredoo Hutchison deploy these across secondary cities where construction labor pools remain shallow.
- Edge Computing Centers:Sub-1 MW micro-facilities target latency-sensitive content delivery in Surabaya, Medan, and Makassar. Content delivery networks pilot these configurations despite limited local commissioning expertise.
Hyperscale facilities absorb the bulk of installed capacity; edge computing centers are expanding most quickly.
Technology:
Technical specification intensity escalates with rack power density, creating tiered supplier ecosystems where advanced thermal management commands premium pricing.
- Cooling Solutions:Direct liquid cooling systems circulate dielectric fluid to chip packages, sustaining densities above 50 kW per rack for AI training clusters. Cloud operators with GPU-heavy workloads mandate liquid-ready designs in new RFPs, forcing mechanical contractors to retrain installation crews.
- Power Distribution Units:Medium-voltage switchgear and intelligent PDUs with outlet-level monitoring support tier-certified uptime architectures. Demand clusters in financial services verticals where Reserve Bank of Indonesia regulations mandate documented power redundancy.
- Racking Systems:Hot-aisle containment and adjustable rail configurations accommodate varying server form factors. Standardized 42U and 48U cabinets dominate enterprise deployments.
- Fire Suppression Systems:Clean agent and early smoke detection apparatus protect high-value IT equipment. BIS-equivalent standards govern specification requirements across all facility tiers.
Cooling solutions capture the dominant share of mechanical capital allocation; direct liquid configurations are climbing the fastest.
End User:
Procurement authority concentrates with cloud operators building sovereign assets under Government Regulation No. 71 of 2019, displacing traditional lease-back arrangements.
- Cloud Service Providers:International operators construct owned facilities with full design control to satisfy data localization mandates. Compliance audits by the Ministry of Communication and Informatics accelerate greenfield commitments across Greater Jakarta and Batam.
- Telecom Companies:Domestic carriers deploy modular and edge configurations to support 5G network densification. Indosat Ooredoo Hutchison and XL Axiata prioritize rapid deployment in secondary cities over tier certification.
- Enterprises:Banking and insurance verticals require tier-certified facilities with documented Indonesian data residency. State-owned Bank Mandiri and Bank Rakyat Indonesia drive captive facility construction.
- Government Agencies:National data center consolidation programs under the Ministry of Communication and Informatics stimulate sovereign cloud infrastructure buildouts.
Cloud service providers command the largest capital allocation pools; government agencies are gaining share fastest on sovereign infrastructure mandates.
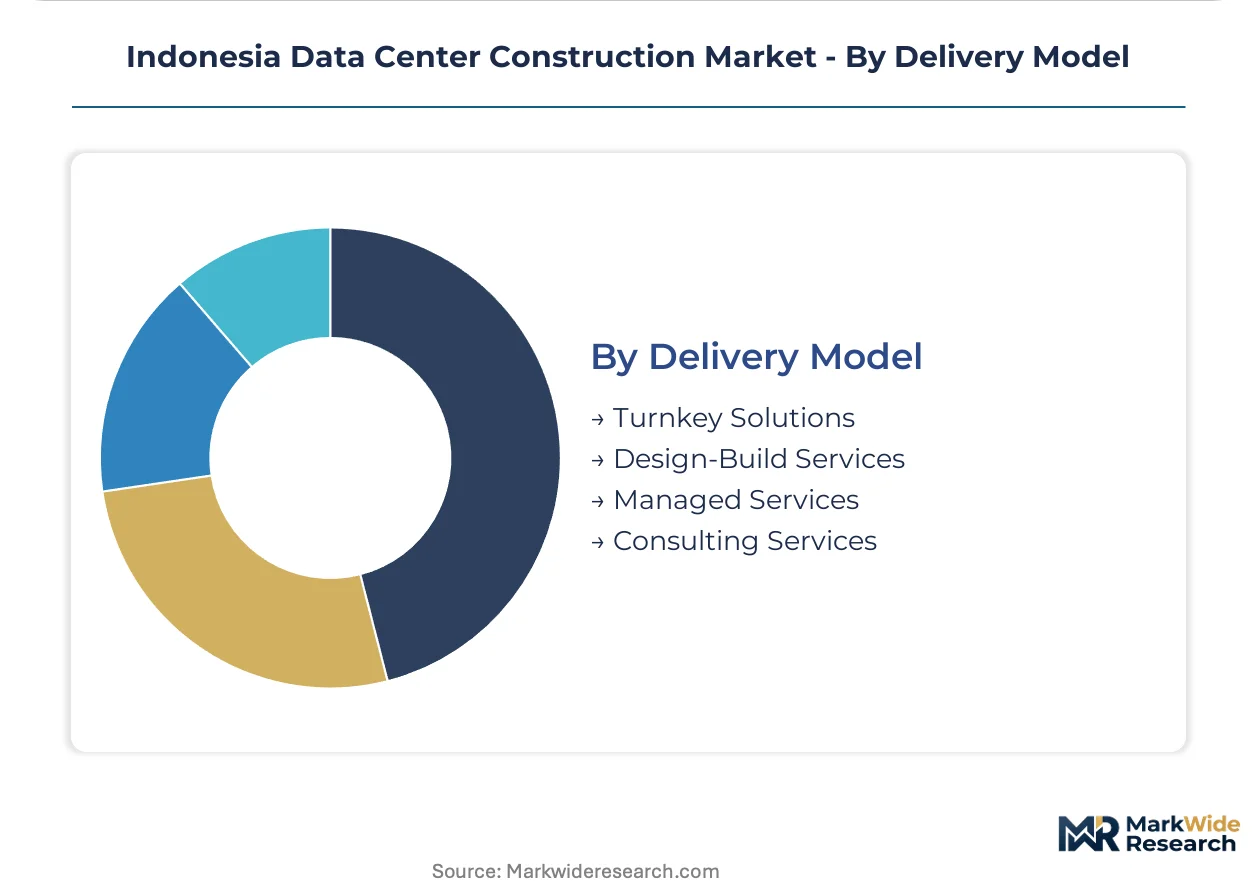
Delivery Model:
Risk allocation frameworks are consolidating scope under single-point accountability contracts that penalize schedule and PUE misses.
- Turnkey Solutions:Single-contractor responsibility for civil, mechanical, electrical, and commissioning scope with performance guarantees. International operators in Greater Jakarta establish preferred contractor panels with pre-negotiated risk frameworks.
- Design-Build Services:Integrated engineering and construction procurement compresses traditional timelines. PT AECOM Indonesia and Jacobs Engineering Group capture these mandates through mission-critical specialization.
- Managed Services:Post-commissioning operational support including remote hands and facility management. Emerging among enterprises lacking internal critical facilities expertise.
- Consulting Services:Advisory scope covering site selection, regulatory navigation, and tier certification preparation. Demand spikes during permitting phases in Batam and Surabaya special economic zones.
Turnkey solutions dominate hyperscale procurement; design-build services are expanding most quickly among mid-scale enterprise developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction demand concentrates in Greater Jakarta and Batam, where submarine cable landings, PLN grid infrastructure, and data localization compliance requirements converge. The Ministry of Communication and Informatics enforces Government Regulation No. 71 of 2019 across all major development corridors. Four sub-regions capture the bulk of investment flows.
Greater Jakarta
Hyperscale campuses exceeding 50 MW dominate capital allocation, driven by international cloud operators seeking sovereign assets. Government Regulation No. 71 of 2019 mandates Indonesian data residency for citizen information. Cikarang and Bogor industrial zones absorb the majority of greenfield builds despite PLN interconnection queues.
Batam
Submarine cable convergence from multiple international systems positions Batam as an alternative to saturated Jakarta corridors. The Batam Free Trade Zone Authority offers streamlined permitting for critical infrastructure investments. Nagoya and Batam Center districts host emerging hyperscale clusters targeting Singapore-adjacent latency requirements.
Surabaya
East Java's special economic zone status attracts mid-scale enterprise facilities from banking and insurance verticals. Regulatory streamlining under the Ministry of Finance's SEZ framework accelerates project timelines. Rungkut and Gresik industrial corridors emerge as secondary hubs with improved cable connectivity.
Bandung
West Java's technology corridor supports edge computing pilots for content delivery networks targeting latency-sensitive applications. Local government incentives under the Creative Economy Agency stimulate digital infrastructure investment. Cimahi and Padalarang sub-districts concentrate modular deployment activity.
Indonesia Data Center Construction Market Competitive Landscape
Integrated turnkey contracting dominates the current landscape as hyperscale clients consolidate civil, mechanical, electrical, and commissioning scope under single-point accountability. The vendor base concentrates among engineering firms with mission-critical specialization and seismic engineering capabilities. Three archetypes occupy distinct positions: integrated design-build specialists, mission-critical cooling and power consultants, and modular construction providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms scale to capture multi-hundred-megawatt mandates.
Within the integrated design-build tier, PT AECOM Indonesia and Jacobs Engineering Group Inc. exemplify firms capturing turnkey mandates through combined engineering and construction capabilities. Arup Group anchors the seismic engineering specialization segment, occupying a position suited to Indonesia's tectonic risk profile. These three entities represent the qualified contractor concentration that creates bidding bottlenecks for complex hyperscale developments.
| Leading Market Players |
|---|
| Jacobs Engineering Group Inc. |
| PT Arkonin |
| Aurecon Group Pty Ltd |
| Aesler Group International |
| DSCO Group Pte Ltd |
| PT AECOM Indonesia |
| Turner & Townsend |
| NTT Facilities |
| Arup Group |
| Others |
Pricing and Supply Chain Analysis
International cloud operators building owned-asset sovereign facilities under Government Regulation No. 71 of 2019 have compressed contractor margins through fixed-price turnkey mandates while concentrating procurement power among a handful of qualified EPC firms. This ownership pattern forces pricing discipline onto construction specialists who must absorb copper busbar volatility and seismic engineering premiums without recourse to cost-plus structures.
Pricing Analysis
Volume concentration among hyperscale campuses exceeding 50 MW has split the market into thin-margin turnkey contracts for international operators and premium-priced niche engagements for tier-certified enterprise facilities. Price differentiation hinges on Uptime Institute certification tier and liquid cooling readiness, with financial services verticals showing least sensitivity due to Reserve Bank of Indonesia redundancy mandates. Cost compression in modular edge deployments is intensifying as telecom carriers standardize factory-built specifications. State-owned enterprises demonstrate highest price sensitivity, delaying commissioning to await PLN transmission upgrade timelines.
Supply Chain Analysis
Uptime Institute and TIA-942 certification requirements gate access to hyperscale procurement panels, concentrating qualified mechanical and electrical contractors among firms with demonstrated mission-critical commissioning records. Critical inputs draw from China for medium-voltage switchgear, Germany for precision cooling components, and domestic Indonesian sources for structural steel and concrete. Single-source vulnerability sits with specialized coolant distribution units for direct liquid cooling systems. Distribution runs through preferred contractor panels pre-qualified by international operators in Greater Jakarta and Batam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Government Regulation No. 71 of 2019 has erected a formidable cost-of-compliance barrier that favors established players with sovereign facility delivery records while screening out speculative entrants lacking certification credentials and local regulatory relationships.
For Market Incumbents: Extend preferred contractor panel relationships into Surabaya and Batam special economic zones before regulatory streamlining attracts new competitors. Deepen seismic engineering capabilities through targeted hiring from Arup Group's talent pool, as tectonic design complexity remains the scarcest technical competency. Lock in multi-year copper and steel supply agreements to insulate margins from commodity volatility on fixed-price mandates. For New Entrants and Emerging Players: Begin with modular edge computing deployments in Bandung and secondary cities where construction labor pools remain shallow and incumbent concentration is lowest. Target content delivery networks piloting latency-sensitive configurations as the most penetrable buyer archetype lacking established contractor relationships. Pursue design-build service contracts for mid-scale enterprise facilities as a credential-building pathway toward hyperscale qualification. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized commissioning firms with Uptime Institute-certified engineer rosters in Greater Jakarta, where talent shortages extend project handovers and create acquisition opportunities. Long-term viability hinges on exposure to sovereign infrastructure buildouts under Ministry of Communication and Informatics programs rather than speculative private cloud leasing. Watch PLN transmission upgrade announcement velocity as the critical signal for construction pipeline inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Capability Investment | Direct liquid cooling mandates from GPU-heavy cloud operators render air-cooled designs obsolete for AI training halls. |
| Surabaya SEZ Market Entry | Regulatory streamlining under Ministry of Finance framework redistributes activity from saturated Jakarta corridors. |
| Seismic Engineering Talent Acquisition | Indonesia's tectonic risk profile demands specialized structural expertise that extends design-cycle duration. |
| Renewable Energy Power Matching | PLN geothermal and hydroelectric expansion creates 24/7 carbon-free pathways for sustainability-mandated developments. |
| Turnkey Performance Guarantee Structuring | Single-point accountability contracts with PUE penalties consolidate procurement authority among qualified EPC firms. |
Research Methodology
Independent corroboration across hyperscale facility developers, mission-critical EPC contractors, and PLN grid planning officers underwrites the qualitative findings in this study. Primary interviews with data center engineering directors, procurement leads at international cloud operators, and commissioning specialists were validated against secondary sources including Ministry of Communication and Informatics regulatory filings, PLN transmission upgrade announcements, and Uptime Institute certification databases. Bottom-up project pipeline aggregation was triangulated against top-down capital expenditure tracking across the analysis window.
Comparable historical buildout patterns from Singapore and Malaysia anchored the projection framework for Indonesian market maturation. The forecast model segmented by facility scale, cooling architecture, delivery model, and end-user vertical across the projection horizon. CAGRs were derived from facility commissioning timelines, PLN interconnection queue progression, and hyperscale operator announced commitments. Key inputs included submarine cable landing schedules, special economic zone regulatory amendments, and liquid cooling adoption curves for AI training workloads.
Permitting velocity shifts in Batam and Surabaya, PLN transmission upgrade delays, and liquid cooling supply bottlenecks are the dominant revision risks to construction volume assumptions. Forecasts reflect documented stakeholder guidance on project timelines and capital allocation priorities. A model refresh is warranted upon material change in Government Regulation No. 71 enforcement intensity or PLN grid expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Mumbai Data Center Market