
 Non-Flammable Hydraulic Fluids Market | 2026-2036
Non-Flammable Hydraulic Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Flammable Hydraulic Fluids Market Outlook
Aftermarket fluid analysis and condition monitoring is reconfiguring margin pools away from commodity bulk sales toward service-contract models. ExxonMobil Corporation leverages its aviation certification portfolio to dominate aerospace supply chains. Shell plc sustains competitive positioning through backward integration into synthetic ester chemistry. Quaker Houghton specializes in metalworking applications where fire-resistant formulations command technical premiums.
Non-flammable hydraulic fluids are formulated with water-glycol emulsions, synthetic esters, or phosphate esters to achieve flash points above standard mineral oils, typically delivering fire resistance measured by Factory Mutual approval ratings and auto-ignition thresholds above standard hydraulic media. These fluids protect personnel and equipment in high-temperature or high-pressure hydraulic circuits where mineral oil ignition would cascade into catastrophic failure. Ester-based fluids lead the fluid type category due to thermal stability and compatibility with legacy seal materials, while bio-based fluids represent the fastest-growing sub-segment as sustainability mandates reshape procurement criteria in European industrial machinery. The certification dimension structures market access, with MIL-H-5606 and ISO 10304 compliance serving as gatekeepers for aviation and defense contracts where margin pools concentrate.
The EPA regulates hydraulic fluid environmental release under spill prevention frameworks, while REACH and the EU F-Gas Regulation constrain formulation chemistry for products sold into European industrial and energy end-uses. Factory Mutual and Underwriters Laboratories fire-resistance testing protocols shape product development roadmaps and insurance-linked procurement decisions across North American manufacturing. Stakeholders must monitor the divergence between bio-based feedstock scalability and aerospace certification timelines, as the gap between sustainability commitments and qualification cycles widens.
Market Dynamics
REACH and the EU Green Deal are compressing formulation flexibility for mineral oil alternatives while simultaneously accelerating qualification timelines for bio-based synthetic esters in German automotive and French aerospace manufacturing clusters.
Growth Catalysts
- Aviation certification mandates:MIL-H-5606 and ISO 10304 compliance requirements for hydraulic systems in commercial and defense aircraft are locking in specialized fluid procurement specifications that exclude conventional mineral oils from tender eligibility.
- Factory Mutual fire-resistance protocols:Insurance-linked procurement decisions across North American manufacturing are elevating fluids with FM approval ratings above standard hydraulic media in high-temperature press applications.
- German industrial machinery density:Automotive and aerospace manufacturing clusters in Baden-Württemberg and Bavaria are concentrating demand for phosphate ester and water-glycol formulations with localized technical service support.
Market Restraints
- Synthetic ester feedstock volatility:Palm oil and rapeseed derivative prices fluctuate with agricultural commodity cycles, compressing margin predictability for bio-based fluid producers.
- Phosphate ester supply concentration:Specialty chemical production for aviation-grade fluids clusters in a limited number of European and US Gulf Coast facilities, creating geographic vulnerability.
- Legacy seal incompatibility:Nitrile rubber degradation in extended contact with certain fire-resistant formulations forces costly retrofitting of existing hydraulic circuits.
Strategic Opportunities
- India automotive manufacturing expansion:BIS standards adoption for fire-resistant fluids in heavy commercial vehicle production lines is opening qualification pathways for ester-based formulations.
- Condition monitoring service contracts:Fluid analysis and predictive maintenance bundling is displacing commodity bulk sales with recurring revenue models in metalworking and steel mill applications.
- EU F-Gas Regulation chemistry constraints:Refrigeration and energy sector fluid specifications are tightening, creating specification pull-through for phosphate ester alternatives in adjacent industrial cooling systems.
Industry Challenges
- Aerospace qualification timeline compression:OEM certification cycles for new bio-based formulations lag sustainability procurement commitments by three to five years, stranding R&D investment.
- Cross-contamination remediation costs:Mineral oil residue in converted hydraulic systems requires extensive flushing protocols that extend downtime and erode total cost of ownership advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Flammable Hydraulic Fluids Market |
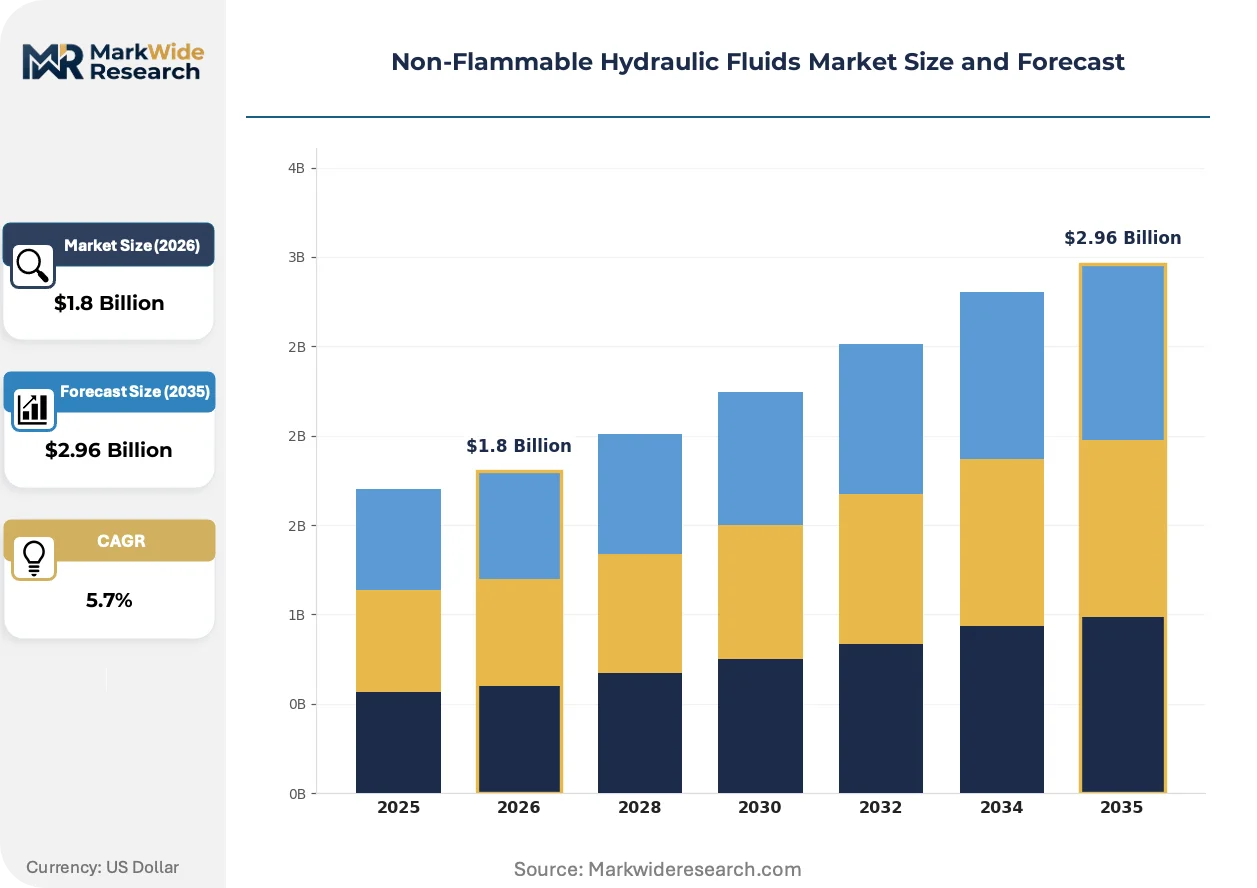
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Water-Based Fluids, Ester-Based Fluids, Glycol-Based Fluids, Bio-Based Fluids End User: Aerospace, Marine, Industrial Machinery, Energy Application: Metalworking, Construction Equipment, Aviation, Hydraulics Certification: ISO 10304, MIL-H-5606, BS ISO 13043, ASTM D7886 |
| Companies Covered | ExxonMobil Corporation, Shell plc, TotalEnergies SE, Quaker Houghton, FUCHS SE, BASF, BP p.l.c., Chevron Corporation, MORESCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Flammable Hydraulic Fluids Market Strategic Shifts
Formulation chemistry and procurement architecture are diverging simultaneously, with sustainability mandates pulling toward bio-based feedstocks while certification requirements anchor performance validation to legacy testing protocols.
Synthetic ester technology is hybridizing fire resistance with biodegradability in single-fluid architectures. Mining equipment operators in Australia and Canada are piloting these formulations in underground hydraulic systems where both ignition risk and environmental release exposure concentrate. The technology is hybridizing previously separate specification categories, enabling suppliers to collapse multiple product SKUs into unified platform chemistries that satisfy both Factory Mutual and OECD biodegradability criteria.
REACH authorization procedures are constraining phosphate ester chemistry in European industrial applications. ECHA substance evaluation timelines are extending reformulation lead times for fluids containing triphenyl phosphate derivatives. Metalworking fluid blenders in Germany and France are responding by accelerating synthetic ester substitution programs ahead of sunset date announcements.
Buyer preference is consolidating around certified-fluid-plus-service bundles rather than standalone product procurement. Steel mills and aluminum smelters are unbundling fluid supply from condition monitoring, then rebundling with predictive analytics vendors. This pattern is most visible in US Great Lakes manufacturing corridors where insurance underwriters incentivize documented fire-resistance compliance through premium adjustments tied to fluid analysis records.
Non-Flammable Hydraulic Fluids Market Segmentation
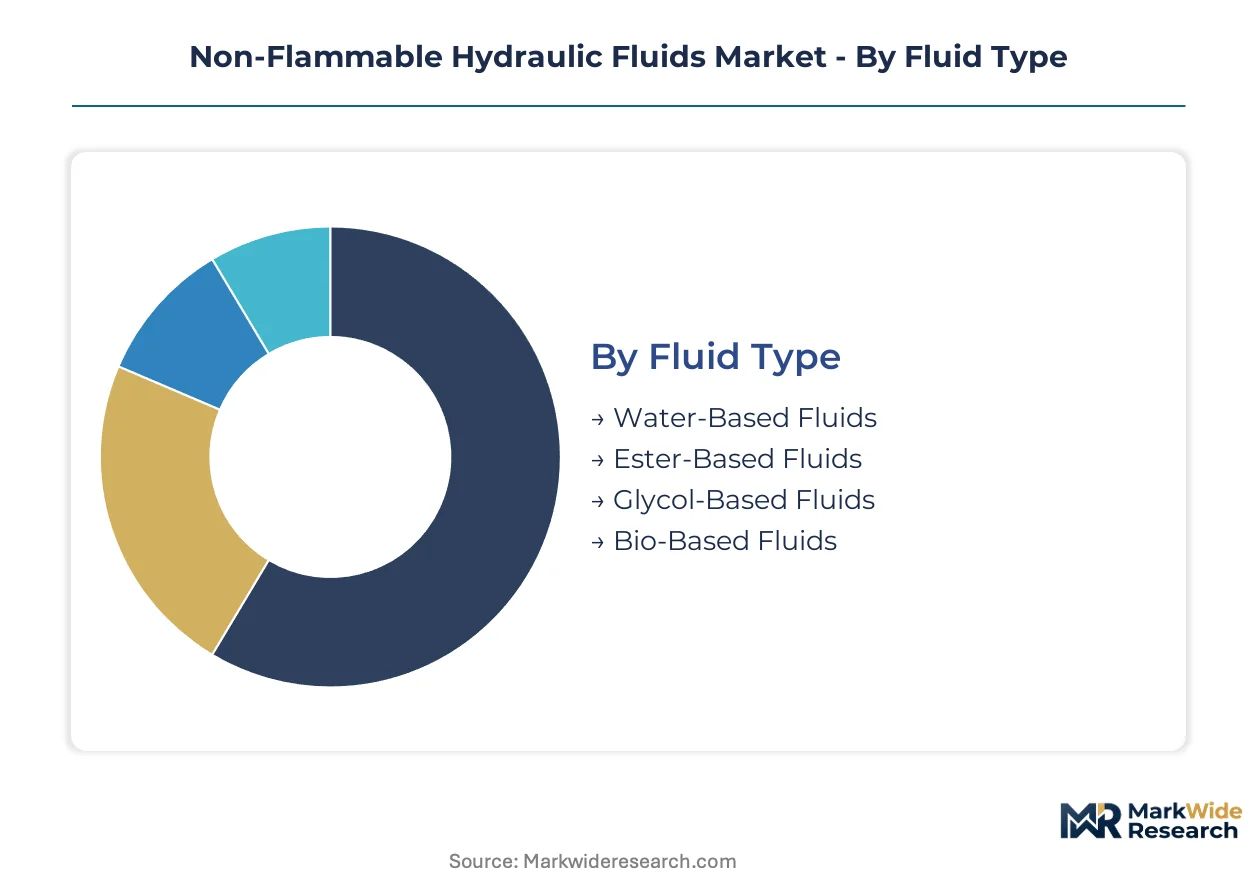
Non-flammable hydraulic fluids demand fragments across incompatible specification regimes. Procurement cycles vary dramatically by end-use, with aerospace qualification timelines stretching years while industrial maintenance turns inventory monthly.
Fluid Type:
Replacement intervals differentiate segment economics, with water-based fluids demanding most frequent changeouts and bio-based formulations commanding extended service life premiums.
- Ester-Based Fluids:Synthetic ester chemistry delivers thermal stability above 150°C and maintains compatibility with legacy nitrile and Viton seal materials. German automotive press lines and French aerospace manufacturing clusters concentrate procurement for phosphate ester alternatives where Factory Mutual ratings govern insurance-linked purchasing.
- Bio-Based Fluids:Rapeseed and palm oil derivatives achieve OECD biodegradability thresholds while meeting fire-resistance protocols. REACH authorization pressures on mineral oil alternatives accelerate substitution programs in European metalworking corridors, though aviation certification timelines lag sustainability procurement commitments by three to five years.
- Water-Based Fluids:Water-glycol emulsions provide lowest-cost fire resistance for steel mills and aluminum smelters with high leakage tolerance.
- Glycol-Based Fluids:Polyalkylene glycol formulations bridge compatibility gaps in mixed-fleet industrial environments requiring intermediate thermal performance.
Ester-based formulations anchor the volume base while bio-based fluids gain share at the steepest rate.
End User:
Margin structures diverge sharply across buyer categories, with certification-intensive segments capturing technical premiums and price-sensitive industrial accounts driving commodity competition.
- Aerospace:MIL-H-5606 and ISO 10304 compliance requirements lock procurement specifications to approved supplier lists. ExxonMobil and Shell dominate through aviation certification portfolios that exclude mineral oils from commercial and defense aircraft tender eligibility.
- Industrial Machinery:Metalworking fluid blenders in Germany and France bundle fire-resistant formulations with condition monitoring services. Predictive maintenance contracts displace bulk commodity sales with recurring revenue models in steel mill and aluminum smelter applications.
- Energy:EU F-Gas Regulation constraints on refrigeration chemistry create specification pull-through for phosphate ester alternatives in industrial cooling and power generation systems.
- Marine:Offshore platform operators prioritize fluids with combined fire resistance and environmental release compliance for subsea hydraulic circuits.
Industrial machinery anchors the volume base while aerospace captures margin concentration through certification barriers.
Application:
Operating environment severity determines formulation selection, with temperature extremes and ignition exposure creating non-substitutable demand pockets.
- Aviation:Hydraulic actuation systems in commercial and defense aircraft require fluids meeting MIL-H-5606 specifications with auto-ignition thresholds above standard mineral oils. OEM qualification cycles structure multi-year procurement relationships with approved suppliers.
- Metalworking:High-temperature press applications in German automotive clusters elevate Factory Mutual-approved fluids above standard hydraulic media through insurance-linked purchasing decisions.
- Construction Equipment:Mining operators in Australia and Canada pilot hybrid formulations combining fire resistance with biodegradability in underground hydraulic systems.
- Hydraulics:General industrial circuits represent price-sensitive volume where water-glycol emulsions compete on total cost of ownership against conversion and flushing expenses.
Hydraulics anchors the volume base while aviation climbs the fastest on certification-driven specification tightening.
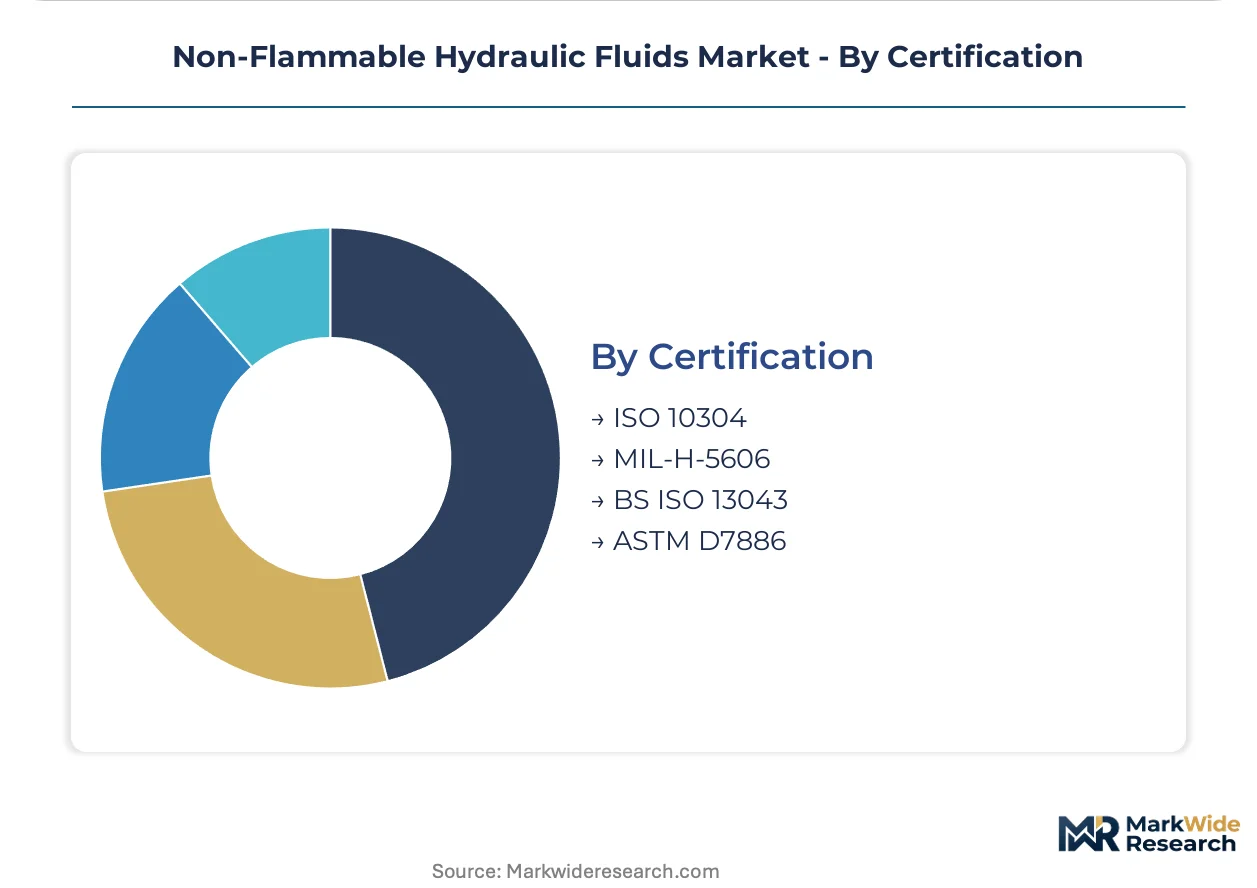
Certification:
Regulatory compliance architecture structures market access, with cross-border recognition gaps fragmenting supplier territories.
- MIL-H-5606:US military specification governs defense aircraft and NATO-aligned procurement, creating captive demand for qualified US and European suppliers.
- ISO 10304:International standard enables commercial aviation market access across multiple jurisdictions, reducing qualification burden for certified blenders.
- BS ISO 13043:British-adopted variant maintains relevance in Commonwealth aerospace supply chains and legacy defense platforms.
- ASTM D7886:US industrial fire-resistance testing protocol shapes Factory Mutual and Underwriters Laboratories approval pathways for North American manufacturing.
ISO 10304 anchors the volume base through broad jurisdictional recognition while MIL-H-5606 maintains steepest expansion in defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation certification requirements pull procurement toward ester-based formulations in France and the United States, while German industrial clusters favor phosphate ester alternatives under Factory Mutual protocols. Water-glycol emulsions dominate price-sensitive steel mill applications in India and Brazil.
United States
MIL-H-5606 defense procurement anchors demand for qualified fluid suppliers serving Boeing and Lockheed Martin production lines. FAA oversight of commercial aviation hydraulic systems reinforces specification rigidity. Houston-Gulf Coast petrochemical corridors concentrate phosphate ester production capacity for both domestic aerospace and export markets.
Germany
Baden-Württemberg automotive press manufacturers specify Factory Mutual-approved fluids under insurance-linked purchasing mandates. REACH authorization pressures on mineral oil alternatives accelerate synthetic ester substitution programs. Bavarian aerospace suppliers cluster around Munich to serve Airbus supply chains with ISO 10304-certified formulations.
France
Toulouse-Blagnac aerospace manufacturing drives qualification-intensive procurement for Airbus hydraulic systems. ECHA substance evaluation timelines extend reformulation lead times for triphenyl phosphate derivatives. Île-de-France metalworking corridors bundle fire-resistant fluids with predictive maintenance service contracts.
India
BIS standards adoption for heavy commercial vehicle production lines opens qualification pathways for ester-based formulations. Automotive manufacturing expansion in Maharashtra and Tamil Nadu concentrates demand for fire-resistant hydraulic media. Pune and Chennai industrial clusters pilot condition monitoring bundling in steel mill applications.
Australia
Mining equipment operators in Western Australia pilot hybrid formulations combining fire resistance with biodegradability in underground hydraulic systems. OECD environmental release standards shape offshore platform procurement specifications. Perth-based resource extraction firms prioritize fluids with combined Factory Mutual ratings and marine discharge compliance.
Non-Flammable Hydraulic Fluids Market Competitive Environment
Capability concentration sits with integrated petrochemical majors holding aviation certification portfolios; scale advantage sits with regional blenders serving industrial maintenance accounts. The market structures around three tiers: global energy majors with backward integration into synthetic ester feedstocks, mid-cap specialists with metalworking application expertise, and regional distributors with localized technical service capabilities. Dominant competitive moves include portfolio diversification into condition monitoring services and geographic expansion through distributor partnerships in emerging manufacturing corridors.
Within the integrated major tier, ExxonMobil Corporation and Shell plc occupy positions defined by aviation certification depth and captive supply of synthetic base stocks. Quaker Houghton exemplifies the application-specialist archetype, anchoring metalworking fluid segments where technical service bundling displaces commodity transactions. These three entities collectively represent the competitive spectrum: certification-driven aerospace supply, feedstock-integrated scale, and service-embedded specialization.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| TotalEnergies SE |
| Quaker Houghton |
| FUCHS SE |
| BASF |
| BP p.l.c. |
| Chevron Corporation |
| MORESCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Phosphate ester supply concentration in US Gulf Coast and European specialty chemical facilities creates geographic vulnerability that widens pricing spreads between aviation-certified formulations and industrial-grade alternatives while compressing margin buffers for regional blenders lacking backward integration into synthetic base stocks.
Pricing Analysis
Long-term offtake agreements anchor procurement for aerospace OEMs, insulating certified suppliers from spot-market volatility while industrial maintenance accounts transact on monthly spot pricing. Certification tier separates MIL-H-5606 qualified fluids from Factory Mutual-approved industrial grades, with aviation specifications commanding technical premiums. Cost compression in water-glycol emulsions intensifies as steel mills prioritize total cost of ownership over performance differentiation. Price sensitivity concentrates in general industrial hydraulics, while aerospace procurement shows inelastic demand tied to qualification timelines.
Supply Chain Analysis
Export-control regimes on phosphate ester chemistry constrain technology transfer for aviation-grade formulations, limiting qualified production to US and European facilities. Synthetic ester feedstock draws from palm oil and rapeseed derivatives concentrated in Southeast Asian and European agricultural processing. Single-source vulnerability sits with triphenyl phosphate intermediates clustered in German and Belgian chemical corridors. Distribution runs through authorized distributor networks for aerospace accounts, while industrial segments source through regional fluid service providers bundling technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-flammable hydraulic fluids market sits at a regulatory inflection where REACH authorization timelines and aviation certification cycles are diverging, creating asymmetric opportunity for suppliers bridging bio-based feedstock scalability with legacy performance validation.
For Market Incumbents: Insulate aerospace certification portfolios from bio-based substitution risk by accelerating synthetic ester qualification programs ahead of ECHA sunset dates. Deepen backward integration into rapeseed derivative supply through offtake agreements with European agricultural processors, reducing exposure to palm oil price volatility. Lock in condition monitoring service contracts at steel mill and aluminum smelter accounts to displace commodity spot purchasing with recurring revenue architectures. For New Entrants and Emerging Players: Indian heavy commercial vehicle production lines represent the most penetrable entry point as BIS standards adoption opens qualification pathways for ester-based formulations without aviation certification barriers. Australian underground mining equipment operators piloting hybrid fire-resistant biodegradable fluids present white-space demand for unified platform chemistries satisfying both Factory Mutual and OECD criteria. Partner with regional fluid analysis laboratories to bundle predictive maintenance capabilities, circumventing capital-intensive certification investments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with metalworking application expertise and embedded technical service capabilities. Long-term viability hinges on differentiation through formulation chemistry rather than scale economies in commodity blending. Watch for ECHA substance evaluation announcements on triphenyl phosphate derivatives as signals of forced reformulation cycles that would revalue synthetic ester technology portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Feedstocks | Captive supply of rapeseed derivatives insulates margin from agricultural commodity cycles. |
| Condition Monitoring Service Contract Bundling | Predictive maintenance partnerships at German automotive press manufacturers displace spot purchasing. |
| Aviation Certification Portfolio Expansion | MIL-H-5606 and ISO 10304 compliance locks out mineral oil competitors from Airbus supply chains. |
| Joint Venture with Bio-Based Feedstock Processors | European oleochemical partnerships accelerate REACH-compliant formulation timelines. |
| Geographic Expansion through Distributor Partnerships | Authorized networks in Maharashtra and Tamil Nadu capture Indian automotive manufacturing growth. |
Study Parameters
Operator-level perspectives from maintenance directors at steel mills, procurement leads at automotive press manufacturers, technical R&D directors at fluid blenders, and aftermarket service heads at aerospace distributors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and ECHA substance evaluation databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across fluid type, end-use industry, and certification tier dimensions.
Scenario-bracketing framed volume and value outputs across the analysis window, with CAGRs derived from regression analysis of historical procurement patterns and forward projection of regulatory compliance timelines. Segmentation dimensions modeled included fluid chemistry architecture, end-use application severity, certification protocol requirements, and regional manufacturing cluster density. Forecast inputs incorporated REACH authorization sunset schedules, aviation OEM qualification pipeline visibility, and industrial insurance underwriting criteria evolution.
Practitioners should monitor ECHA substance evaluation announcements, aviation certification completion rates for bio-based formulations, and agricultural commodity price volatility for early signals of forecast deviation. Forecasts reflect assumptions on regulatory enforcement consistency and certification timeline stability. Material shifts in REACH authorization scope or accelerated aviation sustainability procurement mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Argentina Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Philippines Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market