
 Contact Lubricants Market | 2026-2036
Contact Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Lubricants Market Insights
A shortage of tribology-trained formulation chemists is collapsing development timelines for next-generation contact lubricants. Shell leverages captive base-oil refining to sustain cost advantages across synthetic fluid grades. Dow Corning anchors its position through silicone chemistry specialization for electrical contact applications. Nye Lubricants competes on precision-blended greases tailored to aerospace connector specifications.
Contact lubricants are engineered surface-active formulations, typically comprising synthetic hydrocarbons, perfluoropolyethers, or silicone bases with friction-modifying additives, designed to reduce contact resistance and fretting corrosion in precision electromechanical interfaces. Solid lubrication technology dominates military and space-grade applications where outgassing limits constrain fluid options, while boundary lubrication formulations command premium positions in high-cycle connector systems. Electrical contacts represent the most mature application segment with entrenched supply relationships, whereas renewable energy suppliers are emerging as the fastest-growing end-user channel due to turbine slip-ring maintenance requirements.
EPA toxicity screening protocols and REACH substance authorization lists are forcing reformulation away from certain mineral oil bases and legacy antiwear additives. ECHA candidate list expansions directly impact perfluorinated compound availability for specialty electrical contact greases. F-Gas Regulation phase-down schedules in Europe are redirecting R&D investment toward hydrofluoroether alternatives. Stakeholders must weigh regulatory compliance timelines against qualification cycles for new contact lubricant chemistries in safety-critical applications.
Market Dynamics
Miniaturization in electronics manufacturing is compressing connector tolerances below 50 microns, forcing reformulation of contact lubricants to maintain film integrity at sub-milliwatt contact loads while surviving reflow soldering temperatures.
Growth Catalysts
- RoHS substance restrictions:European electronics assemblers are accelerating procurement of synthetic base-stock lubricants as legacy mineral oil formulations lose authorization under updated hazardous substance lists.
- Renewable energy maintenance:Wind turbine slip-ring servicing is generating recurring demand for high-temperature contact greases capable of surviving 20,000+ rotation cycles in offshore nacelles.
- Shenzhen-Dongguan manufacturing corridor:Connector production concentration in China's southern manufacturing belt is pulling specialty lubricant blending capacity toward regional distribution hubs.
Market Restraints
- Fluoropolyether feedstock concentration:Perfluorinated base oil supply chains concentrate among three specialty chemical producers, exposing formulators to allocation risk during semiconductor-grade material demand surges.
- ECHA candidate list expansion:Authorization timelines for perfluorinated compounds are extending qualification cycles for aerospace-grade contact greases beyond 18 months.
- Silicone outgassing limitations:Vacuum and space applications exclude silicone-based formulations, restricting addressable market for the dominant chemistry platform.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for mobile phone and component manufacturing are attracting connector assembly investment, creating first-mover advantage for lubricant suppliers establishing local blending.
- Hydrofluoroether chemistry convergence:F-Gas Regulation phase-down schedules are redirecting R&D toward low-GWP alternatives that combine vacuum compatibility with electrical contact performance.
- Direct-to-factory digital distribution:Maintenance procurement platforms for industrial automation are disintermediating traditional distributor networks for high-volume MRO lubricant purchasing.
Industry Challenges
- Tribology formulation expertise scarcity:Retirement waves among grease chemists trained in boundary lubrication theory are collapsing new product development timelines at mid-size specialty blenders.
- Cross-industry qualification burden:Aerospace, automotive, and medical device lubricant specifications demand redundant testing protocols, multiplying certification costs for multi-segment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Lubricants Market |
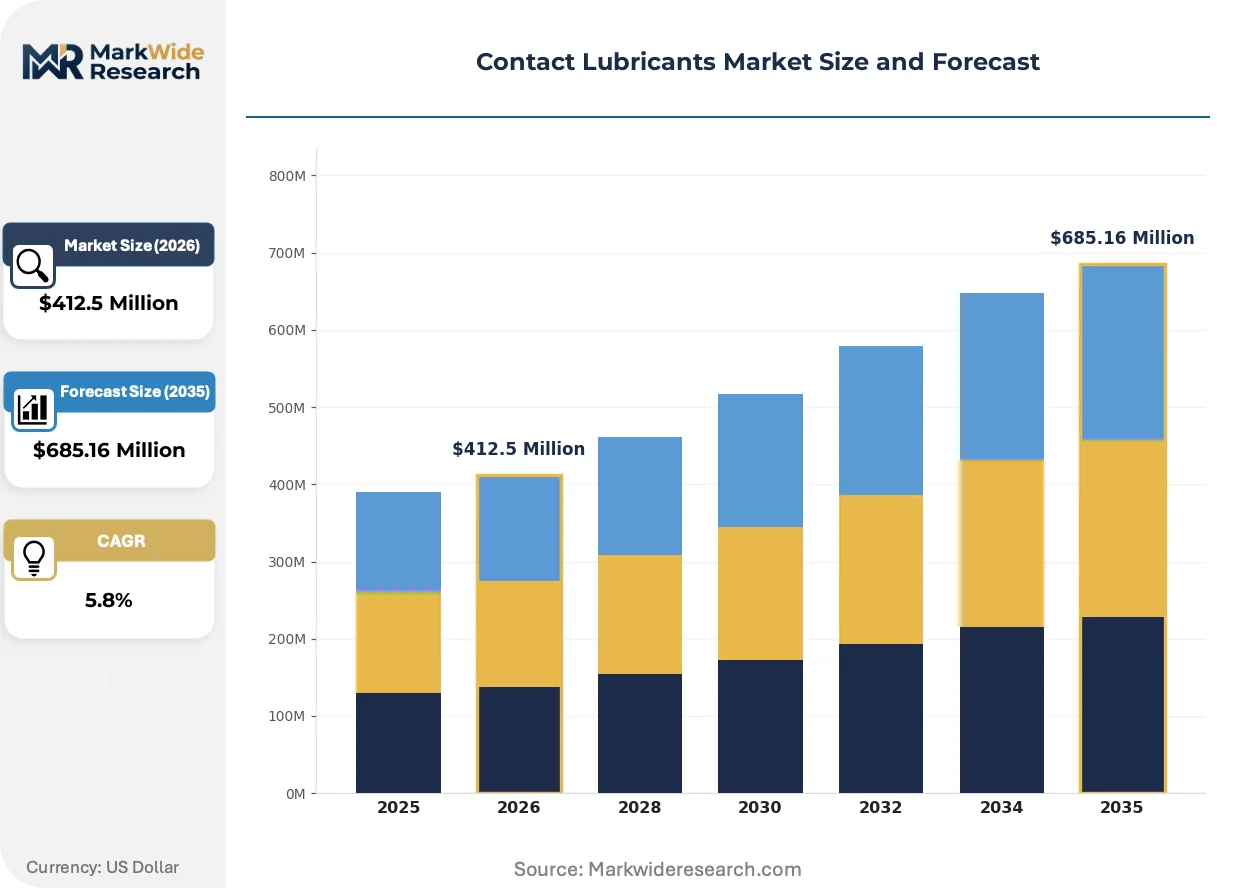
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greases, Oils, Aerosols, Dry Film Lubricants, Synthetic Fluids Technology: Solid Lubrication, Boundary Lubrication, Hydrodynamic Lubrication, Mixed Film Lubrication Application: Electrical Contacts, Mechanical Contacts, Sliding Surfaces, Connectors, Bearings End User Industry: Electronics Manufacturing, Aerospace Assemblers, Renewable Energy Suppliers, Heavy Machinery Producers |
| Companies Covered | Shell, ExxonMobil, Dow Corning, Nye Lubricants, Klüber Lubrication, Fuchs Petrolub, Electrolube, 3M, IKV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Lubricants Market Trends and Innovations
Active reformulation is reshaping competitive positioning as REACH substance restrictions and F-Gas phase-downs simultaneously constrain legacy chemistries while opening substitution windows for novel base stocks.
Solid lubrication technology is fragmenting application segmentation as molybdenum disulfide and tungsten disulfide coatings advance from military-aerospace niches into industrial robotics and medical device connectors. Automotive tier-one suppliers are qualifying solid films for high-voltage charging interfaces where fluid migration risks dominate. The technology is fragmenting procurement patterns as buyers segment specifications by outgassing tolerance rather than traditional load-bearing metrics.
REACH authorization requirements are compressing formulation flexibility as ECHA adds perfluorinated substances to candidate lists with shortened sunset dates. Specialty grease blenders face forced substitution of PTFE-thickened products before alternative rheology modifiers complete qualification. European aerospace connector manufacturers are most affected, accelerating qualification of ceramic-thickened synthetic hydrocarbons to maintain supply continuity.
Buyer concentration among contract electronics manufacturers is consolidating procurement leverage as Foxconn, Jabil, and Flex centralize lubricant specifications across global assembly footprints. Regional purchasing autonomy is contracting as corporate sustainability mandates override site-level formulation preferences. The shift is most visible in Germany's precision engineering corridor, where Tier 1 automotive suppliers now dictate contact lubricant chemistry across their EMS partner networks.
Contact Lubricants Market Segmentation
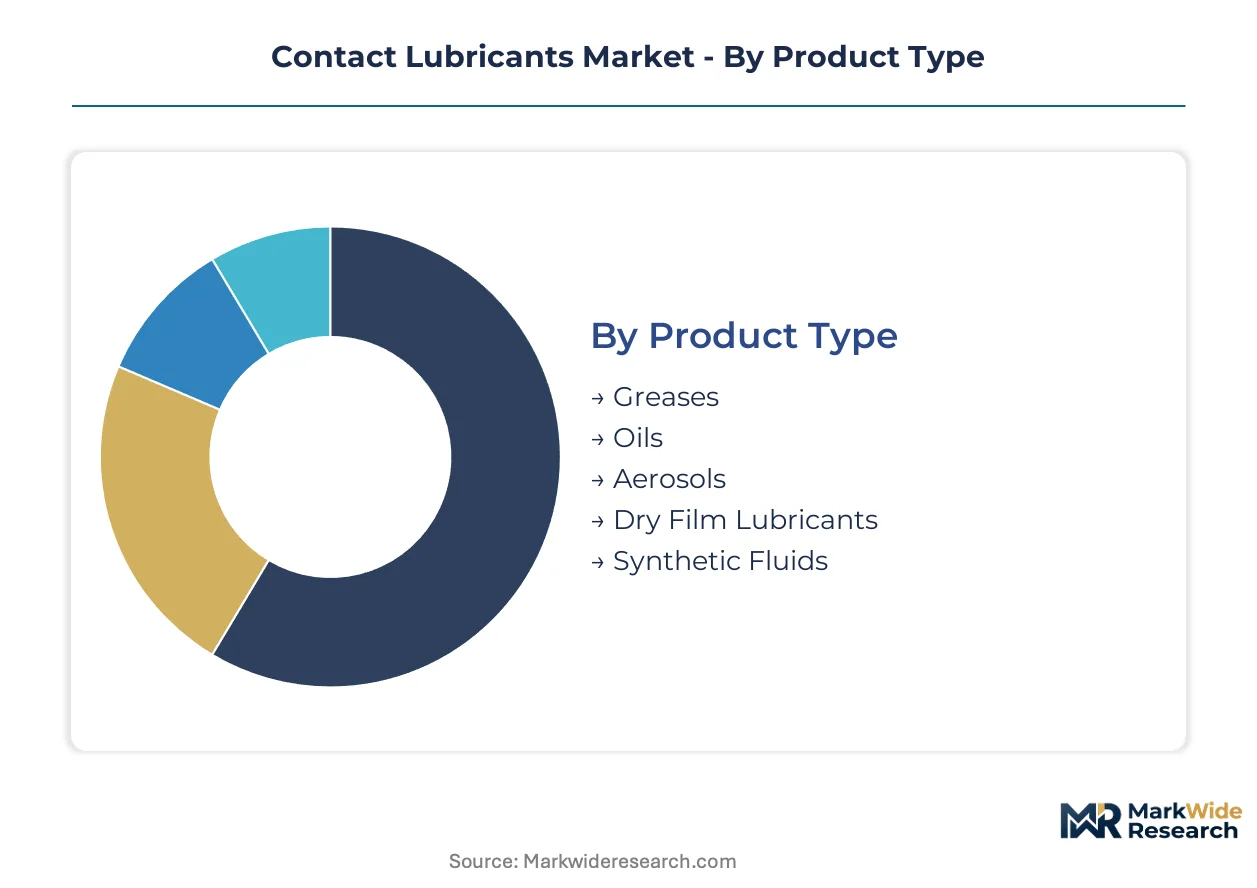
Contact lubricant procurement patterns diverge sharply across product forms and application contexts. Substitution threats from solid film technologies and regulatory-driven chemistry shifts are fragmenting traditional volume concentrations.
Product Type:
Synthetic base stocks face the most acute substitution pressure as REACH substance restrictions accelerate displacement of mineral oil and perfluorinated legacy formulations.
- Greases:Thickened formulations combining synthetic hydrocarbons with PTFE or ceramic rheology modifiers dominate connector maintenance cycles. Demand concentrates in Germany's precision engineering corridor where Tier 1 automotive suppliers now mandate centralized lubricant specifications across EMS partner networks.
- Synthetic Fluids:Perfluoropolyether and hydrofluoroether base stocks deliver vacuum compatibility and thermal stability for aerospace and semiconductor-grade applications. China's southern manufacturing belt is pulling specialty blending capacity toward regional distribution hubs as connector production concentrates in Shenzhen-Dongguan.
- Oils:Low-viscosity synthetic hydrocarbons serve high-speed contact wiping applications with controlled migration characteristics.
- Aerosols:Solvent-dispensed formulations enable precise application in field maintenance of wind turbine slip-rings and industrial automation systems.
- Dry Film Lubricants:Molybdenum disulfide and tungsten disulfide coatings advance from military-aerospace niches into automotive high-voltage charging interfaces where fluid migration risks dominate.
Greases anchor the volume base while synthetic fluids gain share at the steepest rate.
Technology:
Cost tier stratification separates military-qualified solid films from commodity boundary lubrication formulations serving industrial maintenance.
- Solid Lubrication:Molybdenum disulfide and tungsten disulfide coatings deposited through sputtering or burnishing eliminate outgassing risks in vacuum and space applications. Procurement patterns fragment as buyers segment specifications by outgassing tolerance rather than traditional load-bearing metrics.
- Boundary Lubrication:Surface-active additives form protective films under high-load, low-speed conditions in precision electromechanical connectors. Demand concentrates in electronics manufacturing assemblers expanding procurement for reliability amid miniaturization trends compressing tolerances below 50 microns.
- Hydrodynamic Lubrication:Full-film separation mechanisms suit high-speed rotating contacts in turbine slip-ring assemblies.
- Mixed Film Lubrication:Transitional regimes combining boundary and hydrodynamic characteristics serve variable-load industrial bearings.
Boundary lubrication commands the broadest application footprint while solid lubrication expands most quickly into industrial robotics and medical device connectors.
Application:
Customer type concentration among contract electronics manufacturers consolidates procurement leverage across global assembly footprints.
- Electrical Contacts:The most mature application segment with entrenched supply relationships serving printed circuit board connectors, relays, and switches. Foxconn, Jabil, and Flex centralize lubricant specifications across their global footprints, contracting regional purchasing autonomy.
- Connectors:Miniaturization trends force reformulation to maintain film integrity at sub-milliwatt contact loads while surviving reflow soldering temperatures. India's PLI scheme for electronics is attracting connector assembly investment, creating first-mover advantage for lubricant suppliers establishing local blending.
- Mechanical Contacts:Sliding and rolling interfaces in industrial machinery requiring fretting corrosion protection.
- Sliding Surfaces:Linear motion systems and guide rails in automation equipment.
- Bearings:Rotational contacts in motors, generators, and precision spindles.
Electrical contacts generate the largest revenue pool while connector applications show the steepest expansion trajectory.
End User Industry:
Supply concentration among fluoropolyether feedstock producers exposes formulators to allocation risk during semiconductor-grade material demand surges.
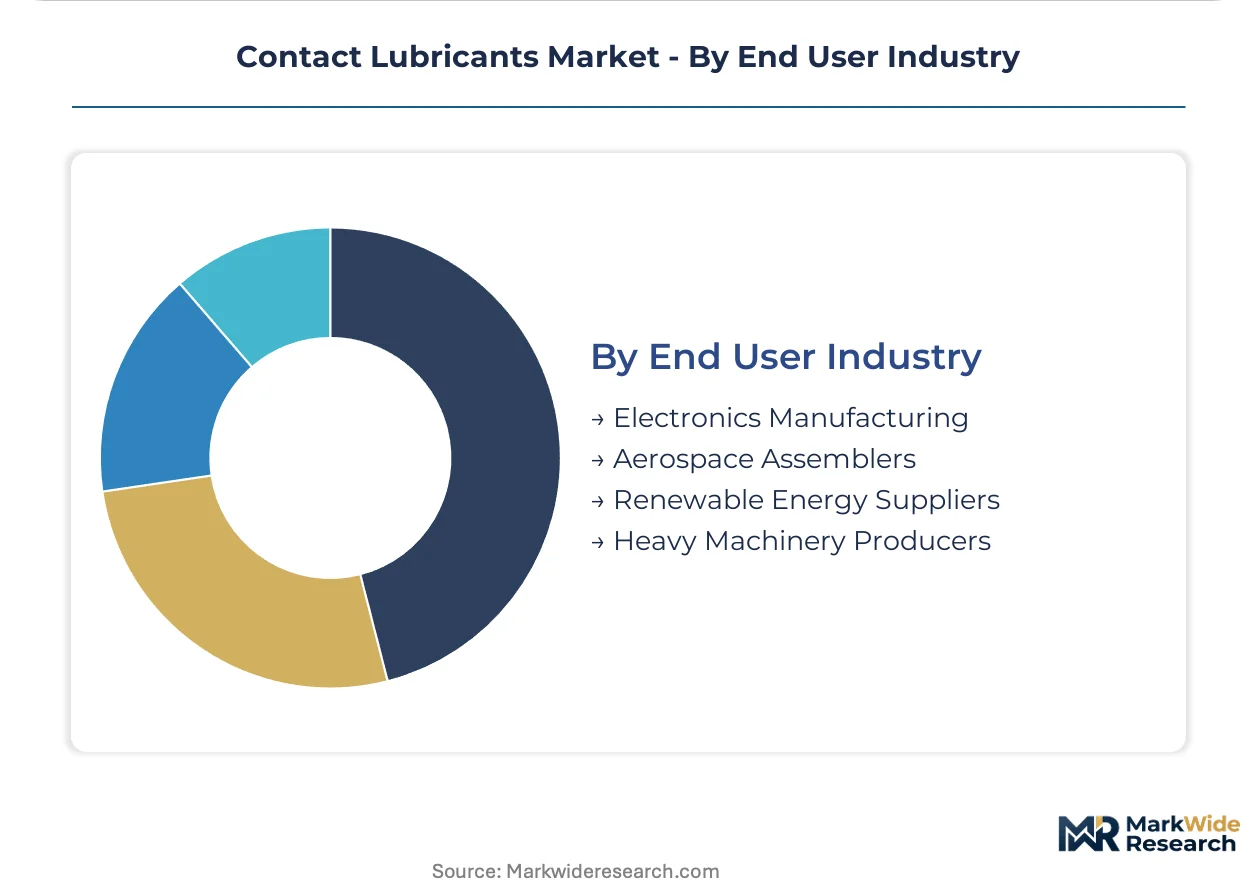
- Electronics Manufacturing:Contract assemblers and OEMs drive specification standardization as corporate sustainability mandates override site-level formulation preferences. RoHS substance restrictions push European electronics assemblers toward synthetic base-stock lubricants as legacy mineral oil formulations lose authorization.
- Renewable Energy Suppliers:Wind turbine slip-ring servicing generates recurring demand for high-temperature contact greases capable of surviving 20,000+ rotation cycles in offshore nacelles. This segment represents the fastest-growing end-user channel.
- Aerospace Assemblers:ECHA candidate list expansions extend qualification cycles for aerospace-grade contact greases beyond 18 months, accelerating substitution of PTFE-thickened products.
- Heavy Machinery Producers:Industrial automation and construction equipment manufacturers with distributed MRO procurement patterns.
Electronics manufacturing anchors the volume base while renewable energy suppliers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contact lubricant consumption patterns diverge sharply across geographies. European aerospace and automotive sectors prioritize REACH-compliant synthetic formulations, while Asian electronics manufacturing drives volume through high-frequency connector assembly. Renewable energy maintenance in offshore wind zones creates specialized demand pockets in Northern Europe and coastal China.
Germany
Precision engineering corridors in Bavaria and Baden-Württemberg anchor European demand for aerospace-grade contact greases. ECHA authorization timelines for perfluorinated compounds now extend qualification cycles beyond 18 months. Stuttgart-based Tier 1 automotive suppliers now mandate centralized lubricant specifications across their EMS partner networks, compressing regional procurement autonomy.
China
Shenzhen-Dongguan manufacturing concentration pulls specialty lubricant blending capacity toward Pearl River Delta distribution hubs. MIIT industrial upgrading guidelines prioritize domestic synthetic base stock production. Offshore wind installations along Jiangsu and Fujian coasts generate recurring demand for high-temperature slip-ring greases surviving 20,000+ rotation cycles.
United States
EPA toxicity screening protocols force reformulation away from certain mineral oil bases and legacy antiwear additives. Defense and space applications in California and Texas sustain solid lubrication procurement despite premium pricing. Pacific Northwest renewable energy clusters are emerging as maintenance demand centers for turbine electrical interfaces.
India
PLI scheme incentives for mobile phone and component manufacturing attract connector assembly investment to Karnataka and Tamil Nadu. BIS standards alignment with RoHS substance restrictions accelerates synthetic base-stock adoption. Delhi-NCR precision component suppliers are establishing qualification partnerships with international grease blenders seeking first-mover positioning.
Japan
METI carbon neutrality roadmaps redirect industrial lubricant procurement toward low-GWP hydrofluoroether alternatives. Kanto and Kansai electronics manufacturing zones maintain stringent outgassing specifications for semiconductor equipment connectors. Nagoya-area automotive electronics suppliers are qualifying ceramic-thickened synthetic hydrocarbons ahead of PTFE substitution deadlines.
Contact Lubricants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in contact lubricant supply. Captive base-oil refining and silicone chemistry specialization separate the upper tier from formulation-dependent competitors. Strategic archetypes include integrated petrochemical majors with backward control over synthetic feedstocks, silicone chemistry specialists leveraging electrical application expertise, and precision blenders serving aerospace qualification requirements. Competitive moves center on regulatory-driven reformulation partnerships and regional blending capacity expansion near electronics manufacturing clusters.
Within the integrated petrochemical tier, Shell and ExxonMobil occupy positions anchored by captive refining infrastructure. Dow Corning exemplifies silicone chemistry specialization for electrical contact applications. Nye Lubricants represents the precision-blending archetype, with formulation expertise concentrated in aerospace connector specifications. These three companies illustrate how feedstock control, chemistry depth, and qualification relationships respectively define competitive positioning in this specification-driven market.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil |
| Dow Corning |
| Nye Lubricants |
| Klüber Lubrication |
| Fuchs Petrolub |
| Electrolube |
| 3M |
| IKV |
| Others |
Pricing and Supply Chain Analysis
Captive base-oil refining capacity among integrated petrochemical majors establishes scale thresholds that price out formulation-dependent competitors while anchoring price floors for synthetic hydrocarbon grades. Shell and ExxonMobil leverage in-house production of synthetic feedstocks to compress margins for specialty blenders purchasing perfluoropolyether base oils on allocation markets, particularly as semiconductor-grade material demand surges strain the three-producer supply concentration.
Pricing Analysis
Contract structures in the contact lubricants market bifurcate between long-term offtake agreements for aerospace and automotive Tier 1 suppliers and spot purchasing patterns for industrial MRO procurement. Price differentiation centers on REACH compliance certification tier and volume scale, with European electronics assemblers absorbing premiums for RoHS-authorized synthetic formulations while contract manufacturers in China's southern manufacturing belt negotiate on geographic delivery cost. Cost compression in mineral oil legacy tiers is intensifying as authorization sunsets approach, with renewable energy maintenance segments proving least price-sensitive due to failure-cost exposure in offshore turbine nacelles.
Supply Chain Analysis
Inventory buffers for perfluorinated base stocks have compressed to eight-week lead times as semiconductor fabrication demand competes for fluoropolyether allocation from the concentrated specialty chemical producer base in Japan, Germany, and the United States. Formulation draws from synthetic hydrocarbon, silicone, and perfluoropolyether feedstocks with ceramic and PTFE rheology modifiers, resting on single-source vulnerability for aerospace-grade perfluorinated compounds. Distribution runs through regional blending hubs co-located with electronics manufacturing clusters in Shenzhen-Dongguan and Germany's precision engineering corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and F-Gas Regulation phase-downs are simultaneously constraining legacy chemistries and opening substitution windows, creating high-growth disruption for suppliers capable of qualifying hydrofluoroether and ceramic-thickened alternatives ahead of sunset deadlines.
For Market Incumbents: Compound qualification partnerships with ECHA-authorized testing laboratories to compress eighteen-month aerospace grease approval cycles before PTFE substitution deadlines hit European supply chains. Anchor backward integration into hydrofluoroether base stock production to escape fluoropolyether allocation risk during semiconductor demand surges, while extending regional blending capacity into India's PLI-subsidized electronics corridors to intercept connector assembly investment migrating from China. For New Entrants and Emerging Players: Certification fast-tracks through BIS-RoHS alignment pathways in India offer lowest barrier-to-entry positioning for synthetic hydrocarbon greases serving Karnataka and Tamil Nadu mobile phone component manufacturers. White-space concentrates in ceramic-thickened formulations for automotive high-voltage charging interfaces where solid lubrication technology fragments procurement patterns, and in direct-to-factory digital distribution platforms disintermediating traditional MRO networks for wind turbine maintenance procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision blenders with locked aerospace qualification relationships over integrated majors facing reformulation lag in specialty electrical contact applications. Long-term viability hinges on tribology formulation expertise scarcity creating defensive moats around Nye Lubricants-type specialists with boundary lubrication theory depth. Watch ECHA candidate list expansion velocity as the inflection signal determining whether hydrofluoroether R&D conversion rates outpace perfluorinated compound authorization delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stocks | Captive hydrofluoroether production escapes fluoropolyether allocation chokepoints during semiconductor demand spikes. |
| Regional Blending Capacity Expansion | Proximity to Shenzhen-Dongguan connector manufacturing compresses logistics cost and qualification cycle friction. |
| Ceramic-Thickener Qualification Partnerships | Substitution readiness ahead of PTFE sunset deadlines locks aerospace connector supply continuity commitments. |
| Direct-to-Factory Digital Distribution | Platform disintermediation captures high-volume MRO procurement shifting from traditional industrial distributor networks. |
| Tribology Expertise Acquisition | Boundary lubrication chemist recruitment collapses new product development timelines at mid-size specialty blenders. |
Research Methodology
A standing panel of formulation chemists at specialty lubricant blenders, procurement directors at contract electronics manufacturers, aerospace connector qualification engineers, and wind turbine maintenance supervisors provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA authorization timelines, REACH substance restriction updates, SEC filings of integrated petrochemical majors, and customs data tracking synthetic base stock trade flows. Bottom-up segment sizing triangulated against top-down petrochemical industry capacity assessments.
Consistency checks validated volume and value outputs against external benchmarks including specialty chemical industry association reports and electronics manufacturing equipment procurement surveys. The analytical framework modeled product type, technology platform, application segment, and end-user industry dimensions across the projection horizon, with CAGRs derived from regression analysis of historical authorization-driven substitution patterns and capacity expansion announcements. Industry-specific inputs included ECHA candidate list sunset date schedules and MIIT industrial upgrading guideline implementation trajectories.
Underlying assumptions cover regulatory authorization timeline adherence, feedstock allocation stability, and electronics manufacturing cluster migration patterns, with deviation risk concentrated in perfluorinated compound supply disruptions and accelerated F-Gas phase-down schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Anti-Static Oil Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Brazil Automotive Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Forestry Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
Spain Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market