
 Point Cloud Processing Software Market | 2026-2036
Point Cloud Processing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Point Cloud Processing Software Market Analysis
Platform licensing revenue is reconfiguring competitive economics as vendors trade perpetual sales for recurring subscriptions. CloudCompare sustains open-source distribution that captures hobbyist and academic users before commercial conversion. Sama specializes in human-in-the-loop annotation services that feed training data into automated extraction pipelines. Pointly anchors its position through browser-native processing that eliminates local compute barriers for mid-sized surveying firms.
Point cloud processing software ingests spatial coordinate sets—typically millions to billions of X,Y,Z measurements—to generate geometrically accurate 3D representations, with output precision often specified to millimeter tolerance for engineering-grade deliverables. The software serves primary commercial purpose in digitizing physical environments for measurement, monitoring, and digital twin construction. Lidar-based processing leads technology revenue given its penetration in autonomous vehicle development and infrastructure inspection, while photogrammetry segments expand fastest in agriculture and heritage documentation where lower hardware costs enable broader deployment. Data analysis modules command premium pricing as engineering firms and government agencies seek automated change detection and volumetric calculation beyond raw visualization.
FAA guidelines on unmanned aerial systems shape how point cloud acquisition platforms operate in controlled airspace, directly affecting software demand tied to drone-mounted sensors. EASA's expanding framework for UAS operations across EU member states creates parallel compliance requirements for cross-border surveying contracts. OSHA workplace safety standards influence how construction and manufacturing end users document as-built conditions and monitor structural deformation. Stakeholders must weigh algorithmic audit readiness against automation speed as regulatory scrutiny of AI-assisted feature extraction intensifies across jurisdictions.
Market Dynamics
Platform licensing revenue is reconfiguring competitive economics as vendors trade perpetual sales for recurring subscriptions, while the EU AI Act and emerging algorithmic transparency requirements in Europe are reshaping how automated feature extraction tools gain commercial deployment clearance.
Growth Catalysts
- EU AI Act compliance pathways:Automated feature extraction tools that document algorithmic audit trails accelerate enterprise procurement cycles in Germany and France.
- Lidar penetration in autonomous vehicle development:Automotive OEMs in Stuttgart, Wolfsburg, and Munich drive enterprise licensing volumes for real-time point cloud processing pipelines.
- Construction digitization mandates:OSHA workplace safety standards and as-built documentation requirements push surveying firms toward millimeter-tolerance deliverables.
Market Restraints
- GPU compute cost volatility:Cloud processing fees for billion-point datasets strain mid-sized surveying firm margins.
- Algorithmic audit complexity:The EU AI Act's risk classification system creates deployment friction for automated classification tools.
- Photogrammetry substitution:Lower hardware costs in agriculture and heritage documentation divert budget from lidar-native platforms.
Strategic Opportunities
- Browser-native processing architectures:WebGL-based pipelines eliminate local workstation barriers for mid-tier engineering consultancies.
- Human-in-the-loop annotation services:Training data pipelines for automated extraction create recurring revenue streams adjacent to software licensing.
- Cross-border UAS compliance tools:EASA's expanding framework for drone operations creates demand for integrated acquisition-to-processing workflows.
Industry Challenges
- Geomatics talent scarcity:Shortage of surveyors proficient in both field acquisition and computational geometry compresses implementation timelines.
- Legacy CAD integration complexity:Point cloud-to-BIM translation errors require manual remediation, eroding automation ROI for construction clients.
- ISO 19650 certification timelines:Information management compliance delays software procurement cycles for government infrastructure contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point Cloud Processing Software Market |
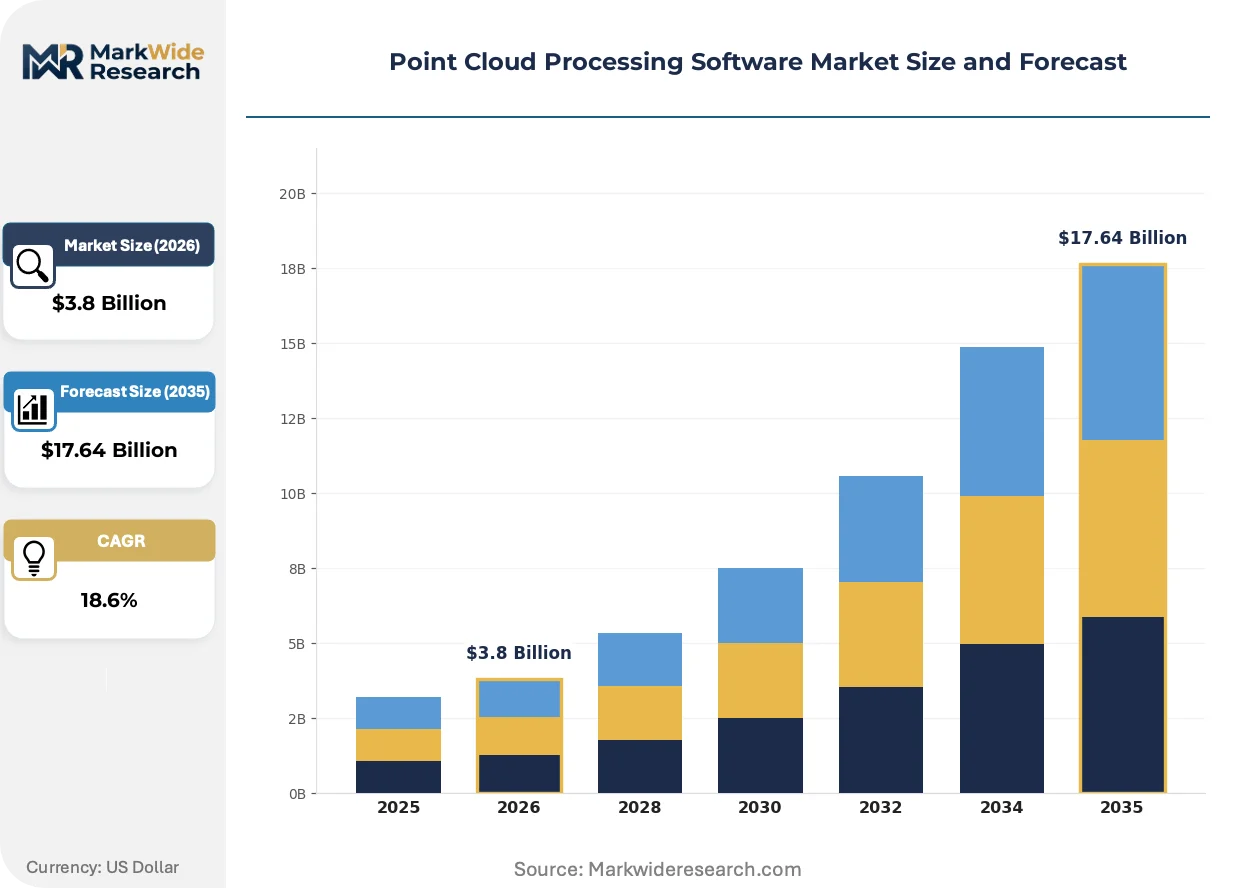
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, Visualization, Simulation, Data Analysis Application: Aerospace, Construction, Surveying, Robotics Technology: Lidar, Photogrammetry, Laser Scanning, Imaging End User: Engineering Firms, Government Agencies, Manufacturing, Academic Institutions |
| Companies Covered | Anolytics, Segments.ai, CloudCompare, Keymakr, AyaData, Carlson Point Cloud, Sama, Pointly, Cogito Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point Cloud Processing Software Market Emerging Trajectories
Neural radiance fields and Gaussian splatting techniques are compressing point cloud storage requirements while preserving geometric fidelity, forcing established vendors to rebuild rendering engines around implicit representations rather than explicit point sets.
Neural radiance fields (NeRF) encode scene geometry through differentiable volumetric rendering, eliminating the need for raw point storage. Automotive perception teams in Detroit and Stuttgart are adopting these representations for simulation environments. This compression architecture is rendering obsolete the traditional octree-based spatial indexing that dominated the previous decade.
The EU AI Act's high-risk system classification applies directly to automated structural defect detection algorithms used in bridge and tunnel inspection. Engineering firms must now maintain technical documentation, human oversight protocols, and post-market monitoring systems. German infrastructure inspectors are responding by hybridizing human verification layers rather than deploying fully automated pipelines.
Subscription unbundling separates visualization modules from analysis engines, allowing surveying firms to license only change-detection or volumetric calculation functions. Channel partners in the UK and Netherlands are assembling à-la-carte bundles that displace traditional all-in-one suites. This pattern is most visible among mid-sized topographic surveyors serving municipal planning departments.
Point Cloud Processing Software Market Segmentation
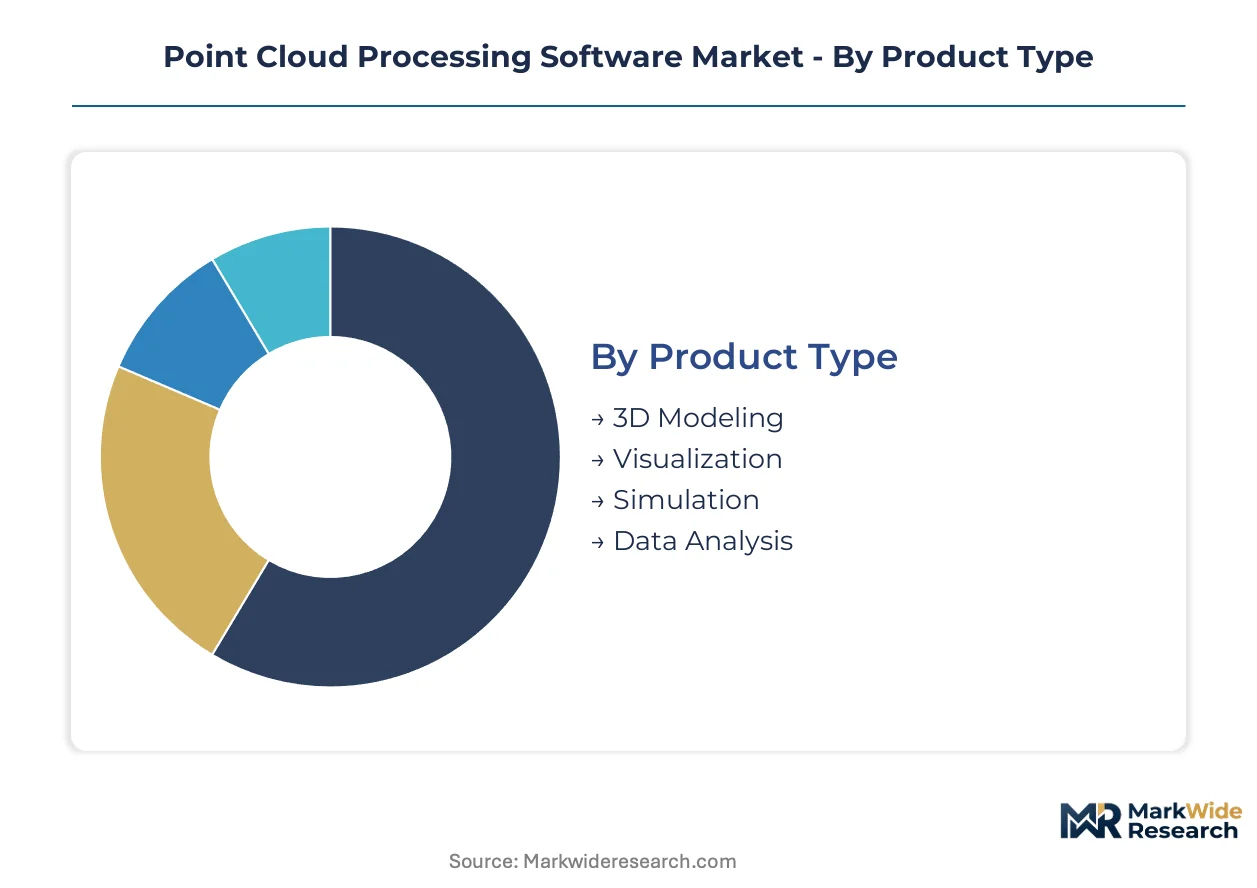
Point cloud processing software vendors configure product architectures around distinct technical workflows and buyer procurement patterns. Segment boundaries determine pricing tiers, sales cycle length, and integration complexity for engineering-grade deployments.
Product Type:
Data analysis modules turn over fastest as engineering firms cycle through automated feature extraction upgrades, while 3D modeling platforms exhibit longer replacement cycles tied to CAD ecosystem lock-in.
- Data Analysis:Automated change detection, volumetric calculation, and defect classification algorithms process billion-point datasets for infrastructure inspection. Engineering firms in Germany and France prioritize these modules for EU AI Act-compliant audit trails. Procurement accelerates where automated extraction replaces manual point classification.
- 3D Modeling:Mesh generation and surface reconstruction tools convert raw point coordinates into engineering-grade solid models. Construction digitization mandates in Germany and OSHA documentation requirements in the US sustain perpetual licensing demand despite subscription migration trends.
- Visualization:Real-time rendering engines for billion-point datasets enable collaborative design review.
- Simulation:Physics-based deformation modeling supports structural integrity assessment workflows.
3D modeling anchors the volume base while data analysis gains share at the steepest rate.
Application:
Procurement patterns diverge sharply: construction applications concentrate in mid-sized surveying firms with compressed evaluation timelines, while aerospace contracts stretch across multi-year qualification cycles.
- Construction:As-built documentation and clash detection workflows dominate commercial deployment. German construction firms drive enterprise licensing for millimeter-tolerance BIM translation. OSHA workplace safety standards mandate regular structural deformation monitoring.
- Aerospace:Airframe inspection and engine component metrology require sub-millimeter precision for regulatory compliance. Stuttgart and Toulouse aerospace clusters sustain premium pricing for certified measurement pipelines.
- Surveying:Topographic mapping and boundary determination serve municipal planning departments.
- Robotics:Simultaneous localization and mapping pipelines support autonomous navigation development.
Construction commands the largest installed base while robotics climbs the fastest as autonomous vehicle programs scale.
Technology:
Hardware cost tiers separate deployment scales: lidar systems demand capital-intensive sensor investments, while photogrammetry enables lower-budget entry for agricultural and heritage documentation.
- Lidar:Time-of-flight and phase-shift measurement systems generate dense point clouds for autonomous vehicle perception and infrastructure inspection. Automotive OEMs in Stuttgart, Wolfsburg, and Munich drive real-time processing pipeline demand. FAA and EASA unmanned aerial system regulations shape acquisition-to-processing workflow design.
- Photogrammetry:Multi-view stereo reconstruction from camera arrays reduces hardware costs for agriculture and cultural heritage applications. French heritage documentation specialists and Dutch agricultural surveyors favor these workflows for budget-constrained deployments.
- Laser Scanning:Terrestrial and mobile scanning platforms serve industrial metrology and forensic documentation.
- Imaging:Structured light and stereo camera systems enable close-range precision measurement.
Lidar underpins the revenue foundation while photogrammetry expands most quickly in cost-sensitive verticals.
End User:
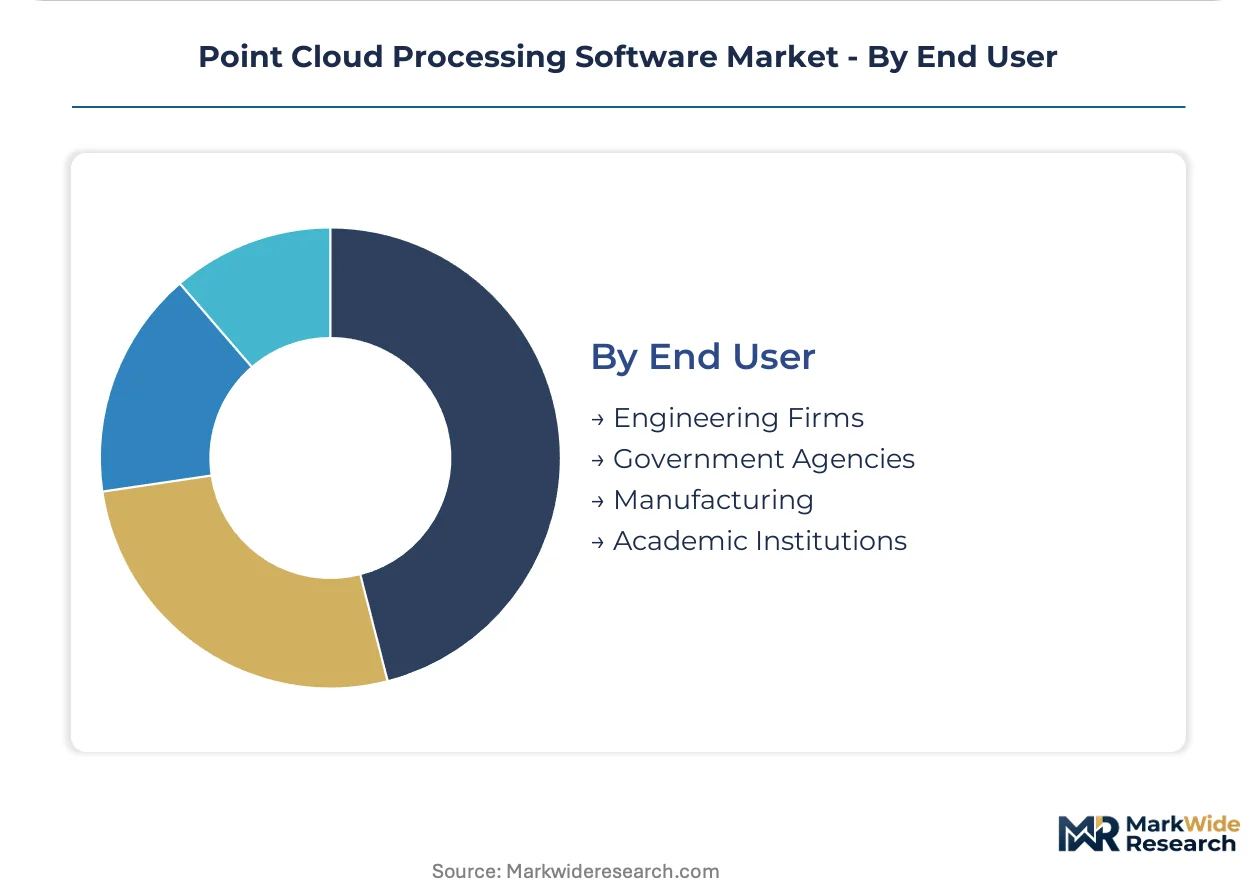
Customer sophistication tiers segment pricing elasticity: government agencies impose extended procurement cycles with ISO 19650 certification requirements, while academic institutions prioritize open-source compatibility over commercial feature depth.
- Engineering Firms:Multidisciplinary consultancies integrate point cloud processing into BIM and CAD workflows for infrastructure and building projects. German engineering consultancies in Munich and Hamburg drive subscription licensing for browser-native processing architectures.
- Government Agencies:National mapping agencies and transportation departments mandate audit trails and technical documentation for automated classification systems. EU AI Act compliance pathways accelerate procurement in France and Germany.
- Manufacturing:Quality control and reverse engineering applications serve automotive and industrial equipment producers.
- Academic Institutions:Research laboratories and geomatics programs train next-generation surveyors on open-source platforms before commercial conversion.
Engineering firms generate the core revenue stream while government agencies represent the steepest expansion trajectory amid infrastructure digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy point cloud pipelines for real-time metrology, while French heritage teams favor photogrammetry for budget-constrained documentation, and US construction firms drive browser-native adoption for OSHA compliance workflows.
Germany
Automotive perception teams in Stuttgart, Wolfsburg, and Munich demand enterprise licensing for lidar-native processing pipelines. The EU AI Act's high-risk system classification for automated defect detection shapes procurement protocols for infrastructure inspectors. Bavarian engineering consultancies hybridize human verification layers rather than deploying fully automated classification.
United States
Construction digitization mandates and OSHA workplace safety standards push surveying firms toward millimeter-tolerance deliverables. FAA guidelines on unmanned aerial systems directly affect software demand tied to drone-mounted sensors. Detroit automotive clusters adopt neural radiance field representations for simulation environments.
France
Heritage documentation specialists favor photogrammetry workflows where lower hardware costs enable broader deployment. EASA's expanding UAS framework creates compliance requirements for cross-border surveying contracts. Toulouse aerospace clusters sustain premium pricing for certified measurement pipelines in airframe inspection.
United Kingdom
Channel partners assemble subscription bundles that separate visualization modules from analysis engines. ISO 19650 certification timelines delay software procurement cycles for government infrastructure contracts. London-based multidisciplinary consultancies integrate point cloud processing into BIM workflows for building projects.
Netherlands
Agricultural surveyors deploy photogrammetry for cost-sensitive topographic mapping of municipal planning zones. EASA drone operation frameworks shape acquisition-to-processing workflow design for cross-border contracts. Dutch engineering firms prioritize browser-native architectures that eliminate local workstation barriers.
Point Cloud Processing Software Market Vendor Landscape
Capability concentration sits with specialized annotation services; scale advantage sits with open-source distribution networks. The vendor base organizes around three strategic archetypes: human-in-the-loop training data pipelines, browser-native processing platforms, and perpetual-license CAD integrators. Competitive moves center on subscription unbundling of analysis modules and cloud processing fee optimization for billion-point datasets.
Within the open-source conversion tier, CloudCompare captures hobbyist and academic users before commercial migration. Sama occupies a position anchoring human-in-the-loop annotation services that feed automated extraction pipelines. Pointly exemplifies browser-native specialists eliminating local compute barriers for mid-sized surveying firms.
| Leading Market Players |
|---|
| Anolytics |
| Segments.ai |
| CloudCompare |
| Keymakr |
| AyaData |
| Carlson Point Cloud |
| Sama |
| Pointly |
| Cogito Tech |
| Others |
Supply Flow & Price Mechanics
GPU undercapacity in cloud regions serving German automotive clusters drives compute-intensive processing vendors toward reserved-instance contracts and hybrid deployment architectures, compressing margins for mid-tier surveying firms while concentrating pricing power with hyperscaler-backed platform providers.
Pricing Analysis
Long-term enterprise licensing contracts dominate German automotive procurement, while project-based fees persist among French heritage documentation specialists and Dutch agricultural surveyors. Three-tier pricing structure across premium certification-grade, standard professional, and economy browser-native levels differentiates by audit-trail depth and EU AI Act compliance documentation. Cost compression in mid-tier SaaS subscriptions intensifies because GPU cloud fees for billion-point datasets scale non-linearly with point density. Government agencies in France and Germany exhibit lowest price sensitivity due to ISO 19650 certification mandates, while academic institutions and hobbyist users gravitate toward open-source alternatives.
Supply Chain Analysis
Upstream GPU and specialized AI accelerator hardware concentrates supply from Taiwan, South Korea, and the United States, with NVIDIA and AMD architectures anchoring neural network training pipelines for automated feature extraction. Software vendors draw from photogrammetry camera arrays manufactured in Japan and China, lidar sensors produced in Germany and the United States, and cloud compute infrastructure operated by hyperscalers across Ireland, Germany, and the Netherlands. Single-source vulnerability in high-end GPU allocation creates procurement bottlenecks for real-time processing vendors serving Stuttgart automotive clusters. Distribution runs through direct enterprise sales teams for automotive OEMs, channel partners for mid-sized European engineering consultancies, and self-serve web platforms for academic and hobbyist segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because switching costs tether construction firms to legacy CAD-integrated workflows, creating sticky revenue streams that resist displacement by browser-native challengers.
For Market Incumbents: Pre-empt photogrammetry substitution by bundling lidar-native processing with automated change detection modules at price points that erase hardware cost advantages. Acquire browser-native specialists in the Netherlands and United Kingdom to neutralize the local-compute-elimination threat before channel partners displace traditional licensing models. Deepen backward integration into human-in-the-loop annotation services to capture training data revenue adjacent to software licensing.
For New Entrants and Emerging Players: Pursue French heritage documentation and Dutch agricultural surveying as the most penetrable segments, where photogrammetry workflows and budget constraints have suppressed incumbent lock-in. Target municipal planning departments in Germany with EU AI Act-compliant audit trail features that incumbent suites lack. Deploy freemium browser-native architectures to bypass capital-intensive local workstation requirements and compress sales cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because the EU AI Act's high-risk system classification creates compliance moats that favor established vendors with technical documentation infrastructure. Acquisition candidates include human-in-the-loop annotation specialists with automotive training data contracts and browser-native platforms with mid-sized surveying firm traction. Watch EASA cross-border UAS framework implementation as the signal indicating accelerated procurement for integrated acquisition-to-processing workflows.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Accelerates German infrastructure inspector procurement by documenting algorithmic audit trails. |
| Browser-Native Architecture Launch | Eliminates local workstation barriers for Dutch and UK mid-tier engineering consultancies. |
| Human-in-the-Loop Service Integration | Captures recurring training data revenue feeding Stuttgart automotive perception pipelines. |
| Photogrammetry Workflow Acquisition | Neutralizes cost-driven substitution threatening lidar-native platform margins in agriculture. |
| Cross-Border UAS Compliance Partnership | Locks in EASA-aligned surveying contracts spanning French-German-Dutch municipal planning zones. |
Methodological Framework
Desk research of SEC software company filings, EASA regulatory guidance documents, and hyperscaler cloud infrastructure disclosures preceded structured interviews with CTOs at German engineering consultancies, procurement officers at French heritage documentation agencies, platform engineers at autonomous vehicle startups, and channel partners in the UK and Netherlands. Primary fieldwork combined with secondary validation against EU AI Act implementation timelines, FAA UAS operational waivers, and ISO 19650 certification databases. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and end-user sophistication tiers.
Assumptions held fixed include EU AI Act enforcement intensity, GPU cloud pricing trajectories, and lidar sensor cost decline curves, while variables tested included photogrammetry substitution rates, browser-native adoption velocity, and cross-border UAS regulatory harmonization. Segmentation dimensions modeled encompass product type, application vertical, underlying technology, and end-user procurement sophistication across the projection horizon. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns in adjacent spatial computing markets, with inputs from automotive OEM lidar deployment schedules and construction digitization mandate compliance timelines.
Sensitivities concentrate around EU AI Act risk classification revisions, GPU supply allocation disruptions affecting billion-point processing economics, and photogrammetry hardware cost declines accelerating substitution in cost-sensitive verticals. Forecasts embed assumptions about regulatory enforcement consistency and cloud infrastructure scaling. Cross-checking against IEA digital infrastructure investment benchmarks and EASA UAS operational authorization growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Development Tools Software Market
Software & Services
Application Platform As a Service Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Artwork Management Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Global Food Traceability Software Market
Software & Services
Auto Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
High Education Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Global Janitorial Software Market