
 Global Development Tools Software Market | 2026-2036
Global Development Tools Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Development Tools Software Market Foresight
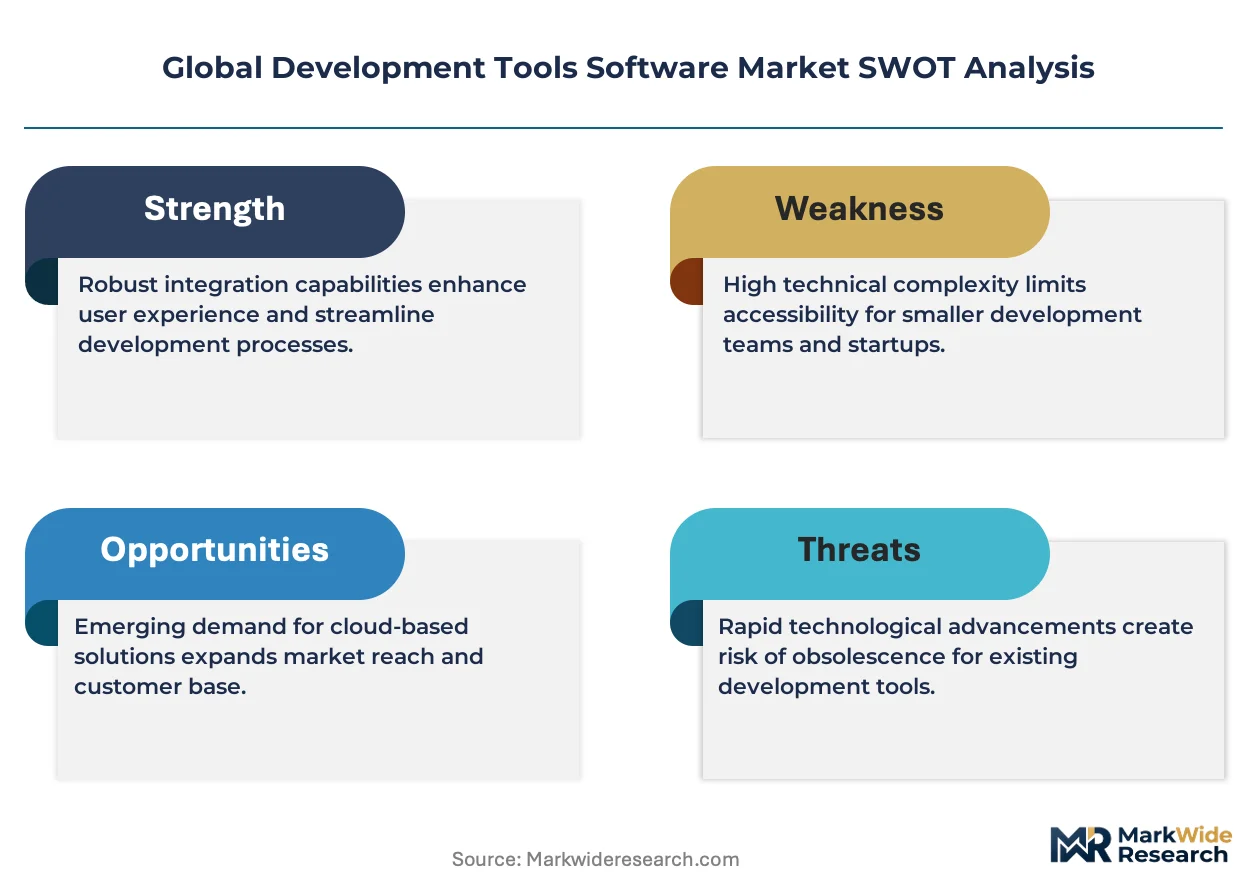
The EU Green Deal is expanding sustainability disclosure requirements across enterprise software supply chains, compelling development tool vendors to embed carbon tracking into CI/CD pipelines. Microsoft Corporation leverages its Azure DevOps ecosystem to anchor cloud-native workflows for regulated industries. JetBrains sustains loyalty among polyglot developers through IDE specialization across Kotlin, Rust, and Go ecosystems. GitLab differentiates by packaging security scanning and compliance dashboards into unified DevSecOps platforms.
Development tools software encompasses integrated programming environments, version control systems, build automation engines, and debugging frameworks that translate human-readable code into executable applications through compilation, interpretation, or transpilation. These tools manage source code integrity, automate testing protocols, and orchestrate deployment across distributed infrastructure. Cloud-based deployment leads solution type demand as enterprises migrate from monolithic on-premise installations to elastic Kubernetes-orchestrated pipelines. Integrated Development Environment offerings capture mature margin pools through subscription retention, while Testing Frameworks represent the fastest-expanding segment amid shift-left quality mandates. Build Automation solutions occupy a structural niche where GitHub Actions and GitLab CI compete for pipeline standardization across multi-cloud estates.
The U.S. SEC climate disclosure rules and the EU CSRD mandate granular reporting on software supply chain emissions, forcing tool vendors to instrument energy consumption metrics directly into compiler and test execution layers. ISO 27001 and SOC 2 Type II certifications now function as market access prerequisites for enterprise procurement committees evaluating development platforms. Stakeholders must monitor whether emerging AI coding assistants trigger new liability frameworks from the U.S. Copyright Office or EDPB guidance on training data provenance before committing to long-term platform contracts.
Market Dynamics
Cloud-native CI/CD pipelines are absorbing development team budgets as enterprises abandon monolithic on-premise toolchains, while the EU AI Act forces automated code generation vendors to re-architect compliance layers around training data provenance and output liability.
Growth Catalysts
- EU AI Act compliance mandates:Automated code generation platforms must embed audit trails and human oversight mechanisms, creating procurement urgency among European financial services and healthcare software teams.
- Kubernetes-orchestrated pipeline adoption:Container-native build automation is displacing legacy Jenkins installations as platform engineering teams standardize on GitOps workflows across multi-cloud estates.
- Bengaluru-Hyderabad engineering cluster expansion:Multinational software vendors are concentrating R&D procurement in these Indian cities, driving localized demand for polyglot IDEs and collaborative debugging infrastructure.
Market Restraints
- Enterprise license cost escalation:Per-seat SaaS pricing for integrated development environments strains mid-market software vendor budgets, particularly when multiplied across contractor and offshore development populations.
- Training data provenance uncertainty:The U.S. Copyright Office has signaled potential liability exposure for AI coding assistants trained on publicly scraped repositories, chilling enterprise adoption timelines.
- Specialized talent scarcity:Platform engineering expertise combining Kubernetes administration with security policy-as-code remains concentrated among a narrow cohort of Silicon Valley and London-based practitioners.
Strategic Opportunities
- Carbon-aware CI/CD instrumentation:The EU Green Deal and CSRD mandate granular emissions disclosure, creating white space for build automation vendors to differentiate through energy consumption analytics and green compute scheduling.
- Embedded security scanning convergence:Shift-left mandates are collapsing separate SAST, DAST, and SCA procurement into unified DevSecOps platforms, favoring vendors with integrated compliance dashboards.
- Rust and Go ecosystem specialization:Systems programming language adoption in cloud infrastructure and blockchain development creates underserved segments beyond JavaScript and Python tooling dominance.
Industry Challenges
- SOC 2 Type II certification timelines:Development tool vendors targeting enterprise procurement committees face 6-12 month audit cycles that delay market entry and strain startup cash reserves.
- Legacy monolith migration complexity:Financial services and industrial software incumbents maintain decades-old COBOL and Fortran codebases that resist integration with modern Git-based workflows and cloud-native deployment orchestration.
- AI-generated code liability fragmentation:EDPB guidance on automated decision-making and emerging U.S. state-level AI regulations create conflicting compliance obligations for cross-border development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Development Tools Software Market |
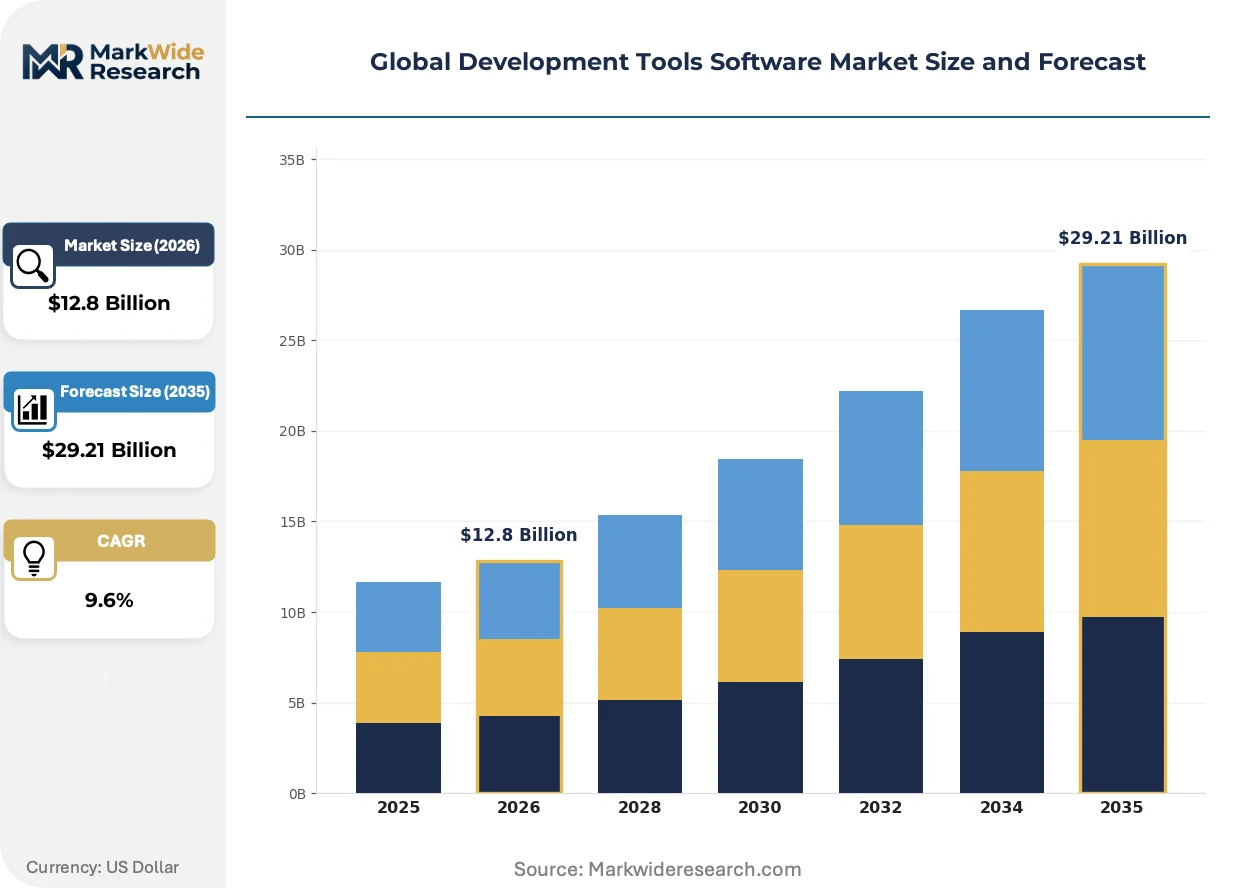
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
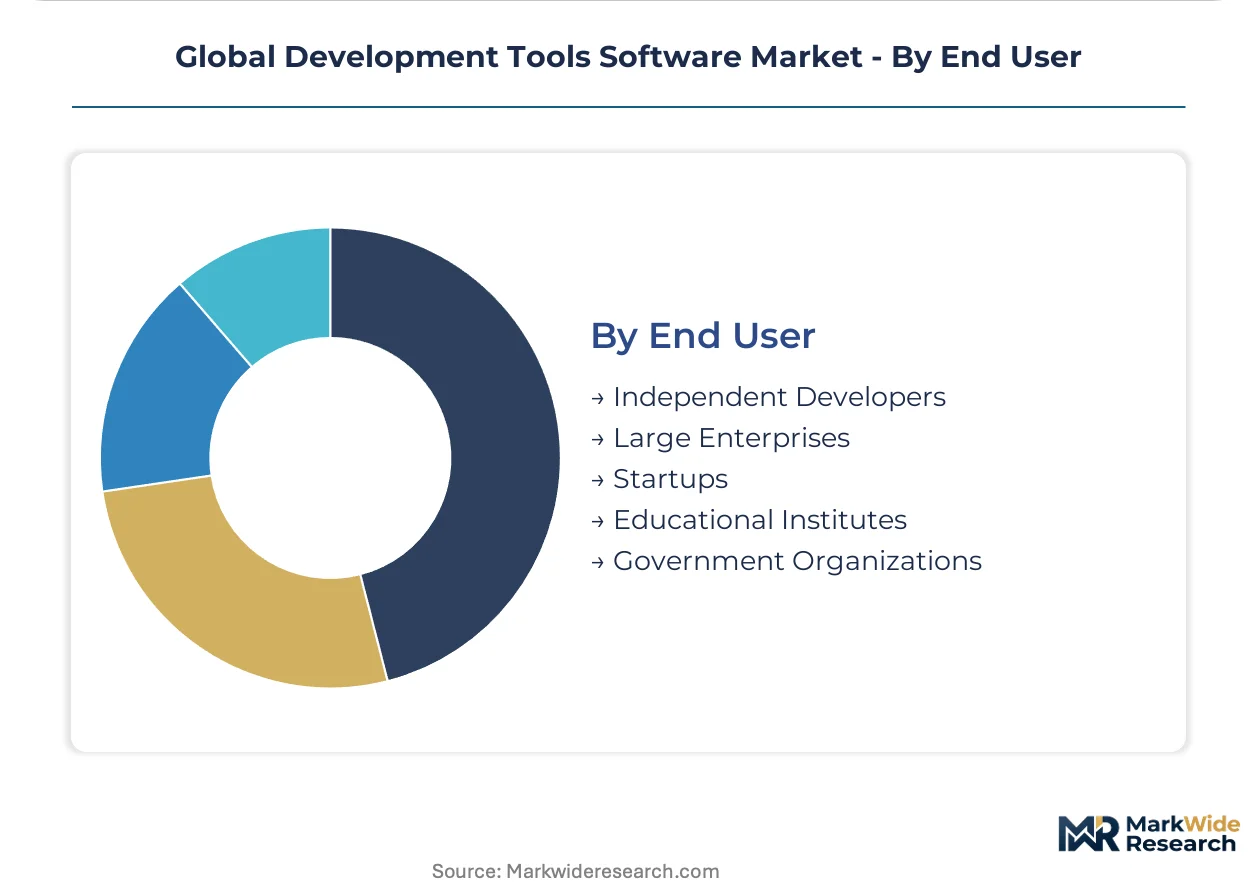
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Type: Integrated Development Environment, Version Control, Build Automation, Debugging Tools, Testing Frameworks Use Case: Web Application Development, Mobile App Development, Embedded Systems, Enterprise Software, Game Development End User: Independent Developers, Large Enterprises, Startups, Educational Institutes, Government Organizations |
| Companies Covered | Microsoft Corporation, JetBrains, Atlassian, Oracle Corporation, Synopsys, Perforce Software, International Business Machines Corporation, GitLab, GitHub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Development Tools Software Market Shifts & Advancements
Agentic AI coding assistants are rewriting productivity benchmarks across software engineering teams, while regulatory pressure on training data provenance and emissions disclosure is forcing tool architecture redesigns.
Large language model-powered code completion is absorbing routine development tasks across JavaScript, Python, and TypeScript ecosystems. Mid-size software vendors in North American fintech and healthtech verticals are deploying these assistants to contractor-heavy teams within 90-day procurement cycles. The technology is absorbing junior developer hours previously allocated to boilerplate implementation, compressing entry-level hiring pipelines while elevating demand for architectural and security review skills.
The EU CSRD mandates granular Scope 3 emissions reporting across enterprise software supply chains, compelling development tool vendors to instrument compiler and test execution layers with energy consumption telemetry. Industrial software procurement committees in Germany and France are now screening vendors on carbon-aware CI/CD capabilities. Build automation platforms are responding with green compute scheduling features that route workloads to low-carbon grid regions during off-peak hours.
Platform engineering teams are consolidating fragmented DevOps toolchains into internal developer platforms with self-service provisioning interfaces. Financial services and telecommunications buyers in the United Kingdom and Singapore are displacing point-solution procurement with unified portal contracts spanning IDE, repository, pipeline, and observability layers. This concentration favors vendors with open API ecosystems over best-of-breed specialists requiring custom integration middleware.
Global Development Tools Software Market Segmentation
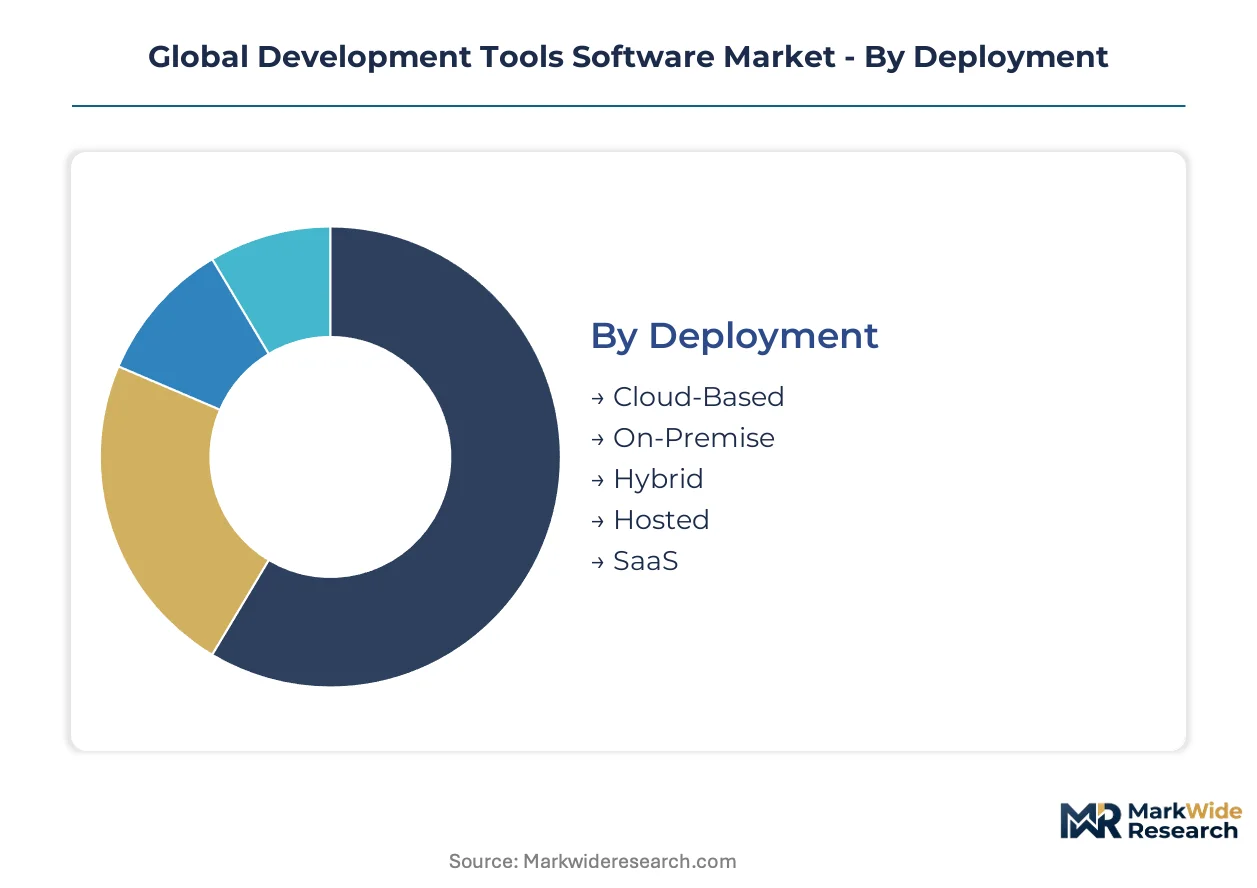
Development tools software procurement fragments across deployment models, solution architectures, and end-user scale, each dimension imposing distinct integration requirements and pricing sensitivities. Vendors must align product packaging with these structural divides to capture retention and expansion revenue.
Deployment:
The customization-vs-standardization spectrum spans fully managed SaaS offerings through self-hosted installations requiring dedicated infrastructure teams.
- Cloud-Based:Elastic compute provisioning enables GitOps-native workflows without capital expenditure on server infrastructure. Financial services teams in Singapore and London prioritize this model for SOC 2 audit streamlining and automatic security patching cadences.
- On-Premise:Air-gapped installations in defense contractors and classified government facilities mandate complete data sovereignty with no external network dependencies. German industrial software vendors maintain these deployments to satisfy Bundesamt für Sicherheit in der Informationstechnik certification requirements for critical infrastructure protection.
- Hybrid:Split workloads between private data centers and public cloud burst capacity accommodate regulated industries with seasonal development cycles.
- Hosted:Single-tenant managed deployments offer dedicated infrastructure without operational burden, popular among mid-market healthcare software vendors.
- SaaS:Fully multi-tenant consumption with per-seat billing dominates startup and independent developer procurement for zero-configuration onboarding.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Solution Type:
Cost tier separation distinguishes mature margin pools in established categories from investment-heavy emerging segments.
- Integrated Development Environment:Polyglot code editors with deep language server integration command premium subscription retention through ecosystem lock-in. JetBrains and Microsoft compete for Kotlin, Rust, and Go specialization in Bengaluru and Hyderabad engineering centers where multinational vendors concentrate procurement.
- Testing Frameworks:Shift-left quality mandates are collapsing separate unit, integration, and end-to-end testing procurement into pipeline-embedded automation. North American fintech and healthtech verticals deploy these tools within compressed 90-day procurement cycles to contractor-heavy teams.
- Version Control:Distributed repository management with branch protection and code review workflows remains foundational infrastructure across all team sizes.
- Build Automation:Container-native pipeline orchestration displaces legacy Jenkins installations as platform engineering teams standardize on Kubernetes-orchestrated GitOps workflows.
- Debugging Tools:Runtime inspection and memory profiling capabilities address specialized needs in embedded systems and high-performance computing environments.
Dominating by revenue: Integrated Development Environment. Expanding most quickly: Testing Frameworks.
Use Case:
Application maturity determines toolchain complexity requirements and compliance layering intensity.
- Web Application Development:Full-stack JavaScript and TypeScript tooling dominates this segment with extensive framework-specific plugin ecosystems. European financial services procurement committees screen vendors on EU AI Act compliance for automated code generation features.
- Enterprise Software:Legacy monolith migration complexity strains integration with modern Git-based workflows in decades-old COBOL and Fortran codebases maintained by industrial software incumbents.
- Mobile App Development:Cross-platform compilation and device farm testing address iOS and Android deployment fragmentation.
- Embedded Systems:Resource-constrained target hardware demands specialized compilers and hardware-in-the-loop debugging capabilities.
- Game Development:Real-time rendering engines and asset pipeline management impose unique performance profiling requirements.
Highest penetration: Web Application Development. Steepest expansion trajectory: Enterprise Software.
End User:
Customer scale correlates inversely with price sensitivity and directly with security certification requirements.
- Large Enterprises:Procurement committees mandate ISO 27001 and SOC 2 Type II certifications as market access prerequisites, with 6-12 month audit cycles delaying vendor market entry. United Kingdom and Singapore financial services buyers consolidate fragmented DevOps toolchains into unified internal developer platform contracts.
- Startups:Rapid team scaling and limited capital prioritize consumption-based SaaS pricing with immediate provisioning and minimal configuration overhead.
- Independent Developers:Individual licensing and community edition freemium tiers drive ecosystem adoption and future enterprise expansion.
- Educational Institutes:Volume licensing and curriculum integration shape procurement for computer science program tooling standardization.
- Government Organizations:FedRAMP and country-specific security clearances impose specialized compliance layers on standard product offerings.
Generating largest contract values: Large Enterprises. Gaining share fastest: Startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru and Hyderabad anchor procurement intensity for development tools software, with multinational vendors concentrating engineering centers in these Indian cities and driving localized demand for polyglot IDEs and collaborative debugging infrastructure.
United States
Financial services and healthtech verticals deploy AI coding assistants within compressed 90-day procurement cycles to contractor-heavy teams. The SEC climate disclosure rules mandate granular reporting on software supply chain emissions. Silicon Valley and Seattle host concentrated platform engineering expertise combining Kubernetes administration with security policy-as-code.
Germany
Industrial software procurement committees screen vendors on carbon-aware CI/CD capabilities mandated by the EU CSRD. The Bundesamt für Sicherheit in der Informationstechnik certification requirements sustain demand for air-gapped on-premise installations. Munich and Frankfurt engineering centers drive specialized demand for embedded systems debugging and legacy monolith migration tooling.
United Kingdom
Financial services and telecommunications buyers displace point-solution procurement with unified internal developer platform contracts spanning IDE, repository, pipeline, and observability layers. The UK financial regulator maintains scrutiny on automated decision-making systems. London anchors concentrated demand for DevSecOps platforms with integrated compliance dashboards.
Singapore
Financial services teams prioritize cloud-based deployment models for SOC 2 audit streamlining and automatic security patching cadences. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria. The city-state's engineering hubs drive procurement for GitOps-native workflows and multi-cloud pipeline orchestration.
Global Development Tools Software Market Competitive Landscape
The competitive structure tilts toward platform ecosystems with deep integration across the development lifecycle. Consolidation pressure favors vendors offering unified DevSecOps platforms over best-of-breed specialists requiring custom integration middleware. Three archetypes dominate: cloud-native suite providers anchoring enterprise workflows, polyglot IDE specialists retaining developer loyalty through language-specific depth, and open-core DevOps platforms monetizing through managed services. Dominant competitive moves include strategic partnerships for multi-cloud certification coverage and portfolio diversification into AI-assisted coding layers.
Within the cloud-native suite tier, Microsoft Corporation exemplifies ecosystem anchoring through Azure DevOps integration for regulated industries. JetBrains occupies a position among polyglot specialists sustaining retention through Kotlin, Rust, and Go ecosystem depth. GitLab represents the open-core archetype packaging security scanning and compliance dashboards into unified platforms. These three companies illustrate how competitive positioning stratifies across integration breadth, language specialization, and DevSecOps convergence.
| Leading Market Players |
|---|
| Microsoft Corporation |
| JetBrains |
| Atlassian |
| Oracle Corporation |
| Synopsys |
| Perforce Software |
| International Business Machines Corporation |
| GitLab |
| GitHub |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs cascade through development tools software pricing tiers, with hyperscale compute provisioning expenses from AWS, Azure, and GCP anchoring SaaS subscription floors while on-premise licensing absorbs capital expenditure recovery through multi-year enterprise contracts.
Pricing Analysis
Outcome-based pricing anchors enterprise procurement for AI-assisted coding platforms, with vendors tying seat licenses to measurable developer productivity gains or deployment frequency improvements. Three-tier pricing structure across premium, standard, and economy levels separates SOC 2 Type II certified suites from mid-market collaborative tiers and individual freemium offerings. Cost compression in the mid-market intensifies because contractor-heavy software vendors resist per-seat multiplication across offshore populations. Startups exhibit highest price sensitivity, while regulated financial services in London and Singapore accept premium tiers for integrated compliance dashboards.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated developer platforms, while value-added resellers and systems integrators serve mid-market verticals with customization requirements. Engineering talent supply concentrates in India, the United States, and Germany, with Bengaluru and Hyderabad hosting concentrated multinational R&D centers. The software supply chain draws from open-source repository ecosystems, proprietary language server protocols, and cloud API dependencies. Single-source vulnerability around GitHub's repository dominance creates systemic risk for distributed version control workflows. Distribution runs through cloud marketplaces, direct enterprise sales teams, and developer community channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agentic AI coding assistants are displacing legacy IDE-centric workflows, compressing procurement cycles and forcing vendors to re-architect around conversational interfaces and automated pipeline orchestration.
For Market Incumbents: Cement platform ecosystem lock-in by embedding carbon-aware CI/CD instrumentation ahead of EU CSRD enforcement timelines. Deepen vertical integration into security scanning layers to collapse separate SAST and SCA procurement into unified DevSecOps contracts. The threat of open-core challengers monetizing through managed services demands preemptive certification investment in ISO 27001 and FedRAMP pathways.
For New Entrants and Emerging Players: Capture white space in Rust and Go ecosystem tooling where JetBrains and Microsoft maintain thinner specialization relative to JavaScript and Python dominance. Target embedded systems debugging in German industrial corridors where legacy monolith migration complexity resists cloud-native displacement. A channel partnership strategy with Kubernetes platform engineering consultancies in London and Singapore accelerates enterprise trial conversion.
For Investors and Strategic Acquirers: EU AI Act audit trail mandates emerging from European financial services procurement committees is the leading indicator that compliance-layer vendors will command acquisition premiums. The 5-10 year viability window favors DevSecOps convergence plays with integrated compliance dashboards over point-solution debugging specialists. Acquisition target archetype: carbon-aware build automation platforms with existing Bundesamt für Sicherheit in der Informationstechnik certification traction.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates IDE, repository, and pipeline layers into unified internal developer portals for financial services buyers. |
| Carbon-Aware CI/CD Development | Embeds energy consumption telemetry into compiler layers to satisfy EU CSRD Scope 3 disclosure mandates. |
| AI Compliance Layer Investment | Architects audit trails and human oversight mechanisms for EU AI Act automated code generation requirements. |
| Rust and Go Ecosystem Expansion | Captures underserved systems programming segments beyond JavaScript and Python tooling saturation. |
| Strategic Partnership with Hyperscalers | Secures co-sell positioning in AWS Marketplace and Azure DevOps integration pathways for regulated industries. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory impact assessments formed the secondary backbone, supplemented by customs data on software services trade and venture financing databases tracking development tools funding rounds. Primary interviews with CTOs, platform engineering leads, IT procurement officers, and channel integration specialists validated demand-side assumptions. Bottom-up and top-down triangulation reconciled seat-license expansion rates with aggregate enterprise software spend allocations.
Bottom-up modeling aggregated deployment mode, organization size, vertical industry, and regional adoption pattern segments across the projection horizon. Top-down validation cross-checked against aggregate IT services expenditure and developer population estimates. CAGRs derived from segment-level growth rate reconciliation with macro technology adoption curves. Forecast inputs incorporated Kubernetes orchestration penetration rates and AI coding assistant deployment velocity in North American fintech and healthtech verticals.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EDPB guidance on AI training data provenance and U.S. Copyright Office liability rulings. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Europe Drone Software Market
Software & Services
Global Open Source Services Market
Software & Services
File Analysis Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Video Communications Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Software License Management (SLM) Market
Software & Services
API Testing Market
Software & Services
Photobooth Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Attendance Management Software Market