
 In-Memory Data Grids Software Market | 2026-2036
In-Memory Data Grids Software Market Size, Share, and Industry Trends Forecast 2026-2036
In-Memory Data Grids Software Market Insights
Distributed caching architectures is rewriting how enterprises build low-latency data layers for mission-critical applications. Oracle Corporation leverages its database heritage to anchor hybrid deployment scenarios across regulated industries. IBM Corporation sustains mainframe-era relationships while extending into cloud-native grid offerings. Hazelcast Inc. competes on open-source velocity and developer community scale.
In-memory data grids software deploys clustered RAM pools across distributed nodes to achieve sub-millisecond data access, typically operating at throughput levels exceeding 100,000 transactions per second per node for operational intelligence and real-time decisioning. Cloud-based deployment is capturing the fastest expansion as enterprises abandon capital-intensive on-premises infrastructure commitments. Real-time analytics applications command premium pricing within financial services and e-commerce end-user segments where latency directly correlates with revenue capture.
ISO 27001 and SOC 2 Type II frameworks govern data residency and security architecture for grid implementations handling personally identifiable information. The U.S. SEC and EU GDPR impose divergent audit and breach-notification obligations that shape multi-region deployment strategies. Stakeholders must evaluate whether vendor roadmaps align with emerging quantum-resistant encryption standards before committing to long-term grid infrastructure contracts.
Market Dynamics
Cloud-native architecture migration is compressing procurement cycles and forcing incumbent vendors to decouple monolithic platforms into containerized microservices. Financial services and e-commerce buyers now demand sub-millisecond latency guarantees backed by consumption-based pricing models.
Growth Catalysts
- Real-time transaction mandates:SEC Regulation SCI and EU MiFID II compliance requirements are compelling capital markets firms to deploy distributed caching layers for order-matching engines.
- Edge computing proliferation:5G network rollouts are creating distributed data gravity points that require localized in-memory processing for IoT telemetry streams.
- India's digital payment infrastructure:RBI's Unified Payments Interface volume thresholds are driving banks toward elastic grid architectures for settlement processing.
Market Restraints
- DRAM supply concentration:Three Korean and Taiwanese suppliers control over 90% of high-bandwidth memory output, creating input cost volatility for grid hardware stacks.
- GDPR data residency friction:Cross-border replication restrictions force redundant infrastructure deployments, inflating total cost of ownership for multi-region financial institutions.
- Serverless compute substitution:AWS Lambda and Azure Functions are capturing workloads below 100ms latency requirements, compressing addressable market for dedicated grid deployments.
Strategic Opportunities
- Brazil's open banking mandate:Central Bank of Brazil's PIX instant payment system is creating greenfield demand for real-time fraud detection grids among tier-2 institutions.
- Quantum-resistant encryption convergence:NIST post-quantum cryptography standards are opening retrofit contracts for grid vendors offering crypto-agile data protection.
- FinOps channel innovation:Cloud marketplaces and managed service providers are emerging as primary procurement channels for mid-market buyers seeking consumption-based grid access.
Industry Challenges
- Distributed systems engineering scarcity:Expertise in consensus protocols and partition tolerance design remains concentrated among Silicon Valley and Bangalore talent pools.
- ISO 27001 certification timelines:Eighteen-month audit cycles delay enterprise sales closures, particularly for vendors without existing Big Four attestation relationships.
- Mainframe integration complexity:COBOL transaction systems at Fortune 500 banks require specialized middleware bridges, inflating implementation costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Memory Data Grids Software Market |
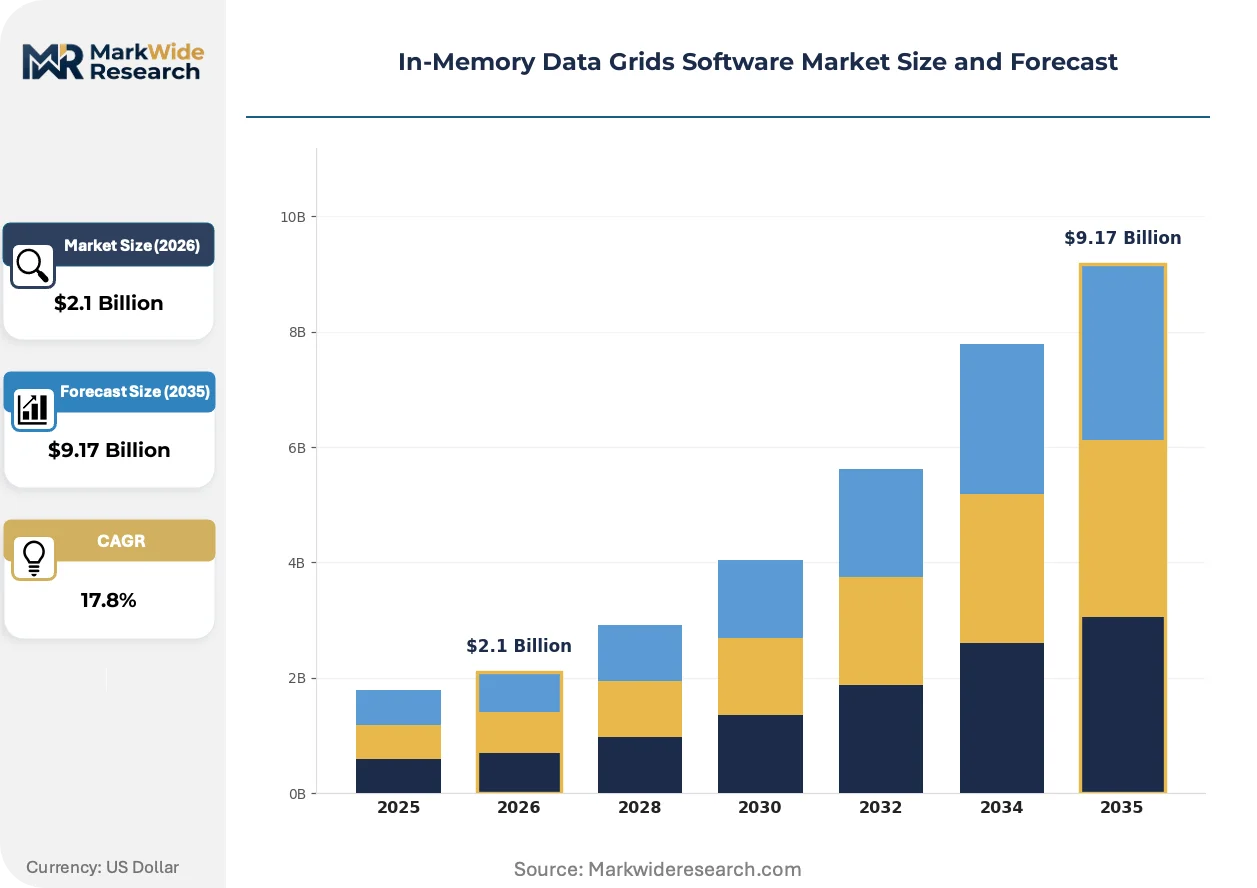
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.17 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Retail, E-Commerce, Financial Services, Healthcare Application: Data Caching, Session Management, Real-Time Analytics, Distributed Computing Solution: Open Source, Commercial, Managed, Serverless |
| Companies Covered | Oracle Corporation, IBM Corporation, Hazelcast Inc., GridGain Systems Inc., GigaSpaces Technologies Inc., TIBCO Software Inc., Software AG, ScaleOut Software, Alachisoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Memory Data Grids Software Market Trends and Innovations
Operational intelligence workloads are fragmenting monolithic data architectures into specialized compute tiers. Vendors are racing to embed AI inference engines directly within grid nodes to eliminate round-trip latency to external model services.
Native persistence architectures are migrating from pure volatile RAM to hybrid memory-storage engines combining Intel Optane-class persistent memory with traditional DRAM pools. Capital markets firms are piloting these configurations for trade surveillance applications requiring both microsecond access and crash recovery guarantees. This migration from ephemeral to durable in-memory designs is collapsing the historical boundary between operational databases and caching layers.
EU AI Act risk classification requirements are mandating explainability audit trails for automated decisioning systems. Grid vendors serving algorithmic trading and credit scoring segments must now embed lineage tracking and model versioning at the data layer. Financial institutions in Germany and France are prioritizing vendors with pre-built compliance modules over pure performance optimization.
Enterprise buyers are consolidating vendor relationships around platform engineering teams rather than infrastructure procurement departments. Grid evaluations now center on Kubernetes operator maturity and GitOps deployment patterns rather than raw throughput benchmarks. This organizational shift is most pronounced among US technology and fintech unicorns building internal developer platforms.
In-Memory Data Grids Software Market Segmentation
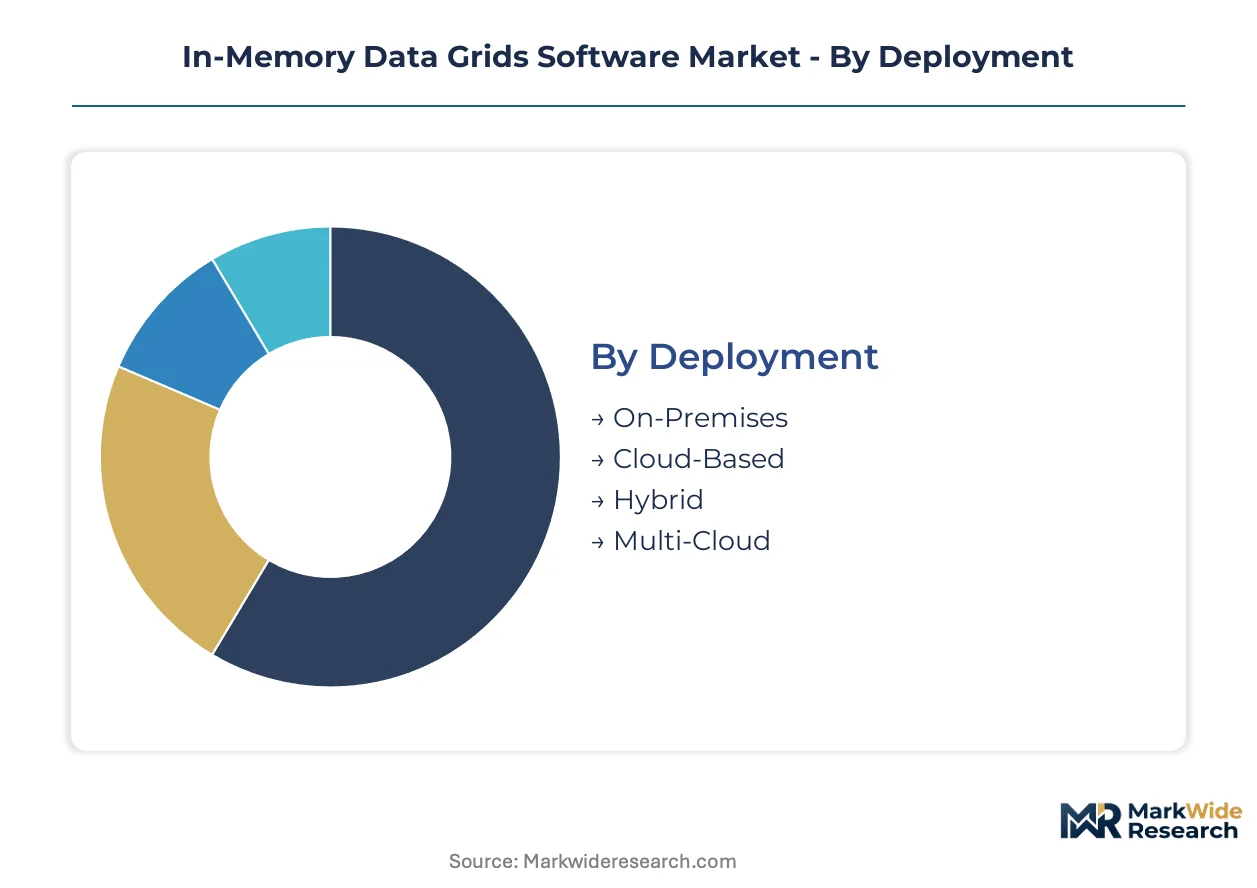
In-memory data grids software procurement cycles vary dramatically by deployment model and end-user sophistication. Buyers evaluate segments against latency requirements, compliance obligations, and internal platform engineering maturity. Vendor positioning strategies must align with these divergent purchasing rhythms rather than uniform feature comparisons.
Deployment:
Cloud-based implementations refresh procurement contracts every 18-24 months as consumption patterns stabilize, while on-premises deployments lock enterprises into 5-7 year hardware refresh cycles.
- Cloud-Based:Elastic compute provisioning eliminates capital expenditure approval delays. Financial services firms in New York and London are consolidating around consumption-based pricing for trading infrastructure. AWS, Azure, and GCP marketplaces now dominate mid-market acquisition channels.
- Hybrid:Split architectures maintain sensitive transaction processing on-premises while bursting analytics workloads to public cloud. German automotive manufacturers and Swiss private banks favor this model for GDPR data residency compliance.
- On-Premises:Dedicated hardware stacks persist among Fortune 500 institutions with mainframe integration requirements.
- Multi-Cloud:Vendor-agnostic orchestration prevents cloud provider lock-in for mission-critical systems.
On-premises deployments dominate installed base. Cloud-based configurations are where expansion concentrates.
End User:
Financial services buyers command premium pricing tiers, while retail implementations compress margins through standardized procurement templates.
- Financial Services:Capital markets firms require sub-millisecond latency guarantees for order-matching engines. SEC Regulation SCI and EU MiFID II audit trails mandate immutable data lineage. Tier-1 investment banks in Manhattan and the City of London drive vendor roadmaps.
- E-Commerce:Session persistence and cart abandonment recovery demand 99.999% availability SLAs. Flash sale events create unpredictable traffic spikes requiring elastic grid scaling.
- Retail:Inventory synchronization across omnichannel touchpoints consumes moderate throughput volumes.
- Healthcare:HIPAA audit requirements and patient data residency rules constrain architecture choices.
Financial services anchors vendor profitability. E-commerce is climbing the fastest.
Application:
Real-time analytics workloads expand node counts fastest, while session management functions stabilize at predictable scale.
- Real-Time Analytics:Algorithmic trading and fraud detection embed AI inference engines directly within grid nodes. Capital markets firms in Chicago and Singapore pilot persistent memory configurations for crash recovery.
- Data Caching:Distributed RAM pools accelerate legacy database queries without schema migration. Indian banks processing UPI transaction volumes favor this approach for settlement acceleration.
- Session Management:Web application state replication ensures seamless failover across availability zones.
- Distributed Computing:Parallel processing frameworks partition computational workloads across clustered nodes.
Data caching dominates operational deployments. Real-time analytics shows the steepest expansion trajectory.
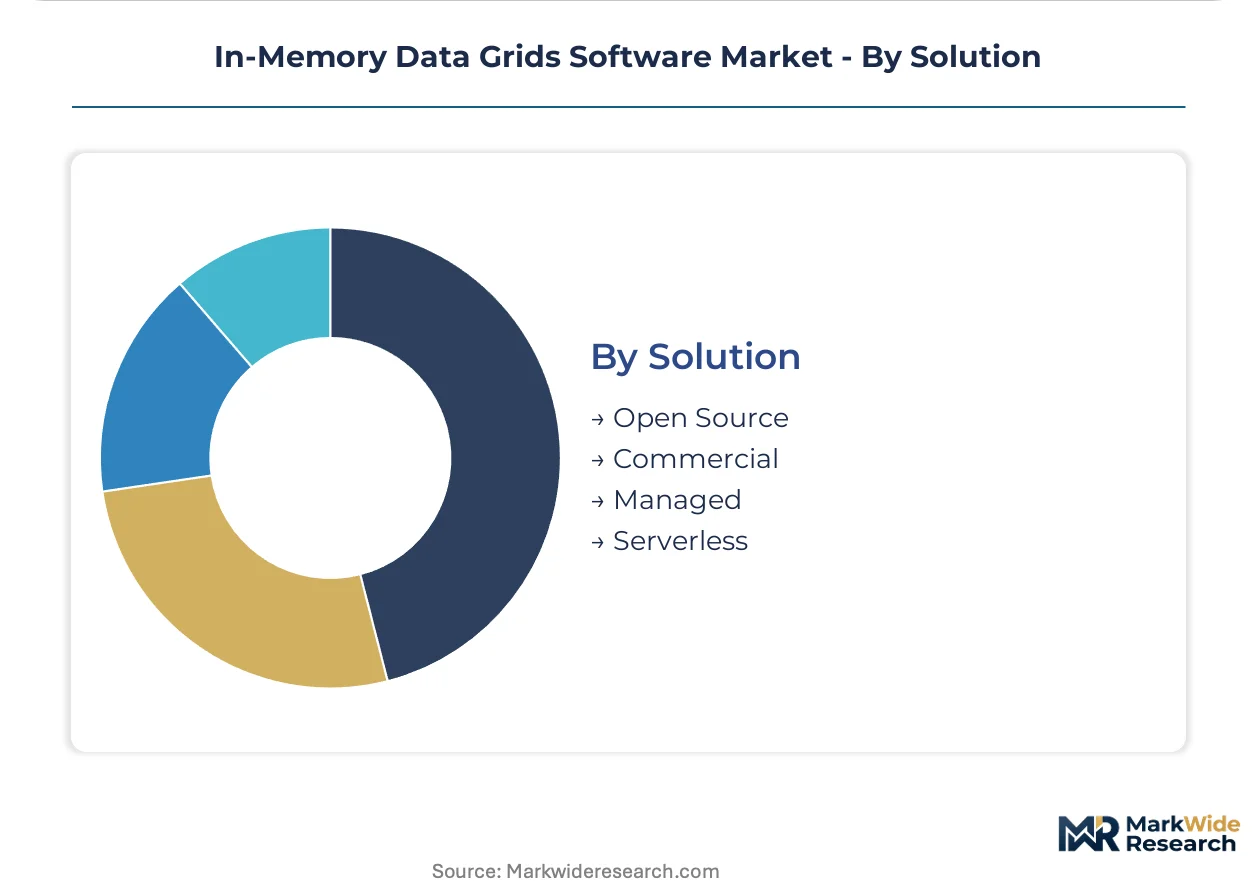
Solution:
Commercial licensing generates recurring revenue stability, while open-source adoption accelerates through developer community scale.
- Commercial:Enterprise support contracts include 24/7 incident response and dedicated customer success management. Regulated industries in Frankfurt and Paris prioritize vendors with pre-built EU AI Act compliance modules.
- Managed:Third-party operators assume infrastructure maintenance burden for mid-market buyers lacking platform engineering teams.
- Open Source:Apache Ignite and Hazelcast Community Edition attract fintech startups and digital-native retailers.
- Serverless:Function-as-a-service abstractions eliminate node provisioning overhead for variable workloads.
Commercial solutions dominate enterprise procurement. Managed services are gaining share fastest among mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based grid vendors export heavily to European financial centers and Singaporean trading hubs. Cross-border data flows concentrate licensing revenue in jurisdictions with harmonized cloud frameworks. Procurement patterns diverge sharply between mature banking clusters and emerging fintech corridors.
United States
Fortune 500 technology and banking clusters in Manhattan and Silicon Valley drive enterprise-grade deployments. SEC Regulation SCI mandates sub-millisecond latency for order-matching infrastructure. Chicago's derivatives exchanges pilot persistent memory configurations for trade surveillance applications.
Germany
Automotive manufacturers and private banks favor hybrid architectures for GDPR data residency compliance. The EU AI Act risk classification requirements mandate explainability audit trails for automated decisioning systems. Frankfurt's financial district prioritizes vendors with pre-built compliance modules over pure performance optimization.
United Kingdom
City of London capital markets firms anchor European demand for real-time analytics grids. MiFID II compliance requirements compel immutable data lineage for algorithmic trading infrastructure. London-based fintech unicorns building internal developer platforms consolidate vendor relationships around platform engineering teams.
India
RBI's Unified Payments Interface volume thresholds drive banks toward elastic grid architectures for settlement processing. The central bank's digital payment infrastructure mandates create greenfield demand among tier-2 institutions. Bangalore's technology talent pool concentrates distributed systems engineering expertise for consensus protocol design.
Singapore
Commodity trading houses and sovereign wealth funds deploy low-latency grids for regional market access. The Monetary Authority of Singapore's cloud risk management guidelines shape multi-region deployment strategies. Marina Bay's financial district serves as the primary Southeast Asian hub for latency-sensitive transaction processing.
In-Memory Data Grids Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement influence across enterprise infrastructure budgets. The market exhibits tiered consolidation with database incumbents anchoring regulated industries while open-source challengers capture developer-led adoption. Three archetypes dominate: legacy database vendors extending into distributed caching, cloud-native specialists building Kubernetes-native offerings, and open-source community projects commercializing through managed services. Competitive moves center on strategic partnerships with cloud hyperscalers and portfolio diversification into AI-embedded grid nodes.
Within the legacy database vendor tier, Oracle Corporation and IBM Corporation represent hybrid deployment anchors across Fortune 500 institutions with mainframe integration requirements. Hazelcast Inc. exemplifies the open-source velocity archetype, competing on developer community scale and containerized microservices alignment. These three occupy positions spanning the procurement spectrum from regulated banking infrastructure to cloud-native fintech platforms.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| Hazelcast Inc. |
| GridGain Systems Inc. |
| GigaSpaces Technologies Inc. |
| TIBCO Software Inc. |
| Software AG |
| ScaleOut Software |
| Alachisoft |
| Others |
Pricing and Supply Chain Analysis
Seoul's DRAM fabrication clusters anchor global memory supply for grid hardware stacks, with three Korean and Taiwanese suppliers controlling over 90% of high-bandwidth memory output. This concentration translates directly into pricing power for enterprise grid deployments, where memory costs dominate total cost of ownership calculations.
Pricing Analysis
Next-generation persistent memory configurations command 40-60% premiums over volatile DRAM pools, while prior-generation caching tiers face margin compression from serverless compute alternatives. Three-tier pricing structure across premium, standard, and economy levels segments buyers by latency requirements and compliance obligations. Pricing pressure stems from AWS Lambda and Azure Functions capturing workloads below 100ms latency thresholds. Mid-market buyers exhibit highest price sensitivity, while Tier-1 investment banks accept premium tiers for sub-millisecond guarantees.
Supply Chain Analysis
Upstream feedstock for in-memory data grids draws from South Korea, Taiwan, and Japan for high-bandwidth memory modules, Intel and Micron for persistent memory controllers, and specialized networking silicon from Broadcom and Marvell. Raw material dependencies include DRAM wafers, advanced packaging substrates, and precision cooling components. Single-source vulnerability concentrates in EUV lithography equipment held by ASML. Distribution runs through cloud hyperscaler marketplaces, systems integrators, and direct enterprise licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-memory data grids market exhibits cyclical recovery characteristics as financial services firms accelerate infrastructure refresh cycles following regulatory compliance deadlines. DRAM price volatility and cloud migration waves create predictable investment windows.
For Market Incumbents: Insulate recurring revenue streams by embedding quantum-resistant encryption modules ahead of NIST standard finalization. Acquire Kubernetes operator expertise through targeted talent raids in Bangalore and Silicon Valley. Defend against open-source displacement by pre-building EU AI Act compliance modules for Frankfurt and Paris buyers.
For New Entrants and Emerging Players: Brazil's tier-2 banking infrastructure offers the most penetrable white space, with Central Bank of Brazil's PIX instant payment system creating greenfield demand for real-time fraud detection grids. Target India's UPI settlement acceleration segment where elastic architectures outcompete legacy batch processing. Lead with consumption-based pricing through AWS Marketplace to bypass enterprise procurement cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors crypto-agile grid vendors with pre-built compliance modules over pure performance optimization plays. Long-term viability hinges on quantum-resistant retrofit contracts and AI inference engine integration. Monitor NIST post-quantum cryptography standard release timing as primary inflection signal for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Encryption Integration | NIST post-quantum standards open retrofit contracts for crypto-agile vendors. |
| AI Inference Engine Embedding | Grid nodes eliminating round-trip latency to external model services capture algorithmic trading premiums. |
| Kubernetes-Native Operator Development | Platform engineering teams prioritize GitOps deployment patterns over raw throughput benchmarks. |
| Cloud Marketplace Channel Expansion | AWS and Azure marketplaces dominate mid-market acquisition for consumption-based grid access. |
| EU AI Act Compliance Module Pre-Build | German and French financial institutions prioritize explainability audit trail capabilities. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and regulatory mandate documents preceded structured interviews with CTOs, platform engineering directors, IT procurement officers, and channel partners at systems integrators. Primary fieldwork combined telephonic and in-person engagements across Manhattan, London, Frankfurt, Bangalore, and Singapore financial districts. Secondary validation drew from cloud provider marketplace data, ISO certification registries, and open-source community contribution metrics. Bottom-up node deployment estimates triangulated against top-down enterprise software spending benchmarks.
Assumptions held fixed include regulatory compliance deadlines for SEC Regulation SCI and EU MiFID II, while DRAM supply concentration and quantum cryptography standard timelines were modeled as scenario variables. Segmentation dimensions spanned deployment model, organization size, vertical industry, integration complexity with legacy mainframe systems, and regional adoption patterns. CAGRs were derived from logistic diffusion curves fitted to historical grid deployment trajectories. Forecast inputs incorporated RBI UPI volume thresholds and Brazil Central Bank PIX transaction growth curves.
Practitioners should monitor DRAM spot price movements, NIST post-quantum cryptography draft releases, and EU AI Act enforcement precedents for early signals of forecast revision. Cross-checking against hyperscaler earnings call commentary on enterprise infrastructure spending is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Document Control Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Content Curation Software Market
Software & Services
Global Contract Management Software Market
Software & Services
Global Virtualization Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Model Based Testing Tools Market
Software & Services
User Interface Software Market
Software & Services
Global Architecture Software Market
Software & Services
MCAD Software Market
Software & Services
Binary Drivers Market
Software & Services
Data Preparation Tools Market
Software & Services
Hydraulic Modeling Software Market