
 Global Servicenow Store Apps Market | 2026-2036
Global Servicenow Store Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Servicenow Store Apps Market Foresight
Certified ServiceNow developer talent is bifurcating the competitive landscape, with scarce platform-specialized engineers commanding premium implementation rates. Okta leverages its identity federation expertise to dominate security-centric app integrations within the store ecosystem. Dynatrace sustains technology leadership through AI-powered observability modules that embed directly into ServiceNow workflows. Cisco Systems anchors enterprise network operations segments with incident management apps that bridge IT infrastructure and service desk automation.
ServiceNow Store Apps constitute third-party software extensions certified for deployment on the ServiceNow platform, typically built using JavaScript-based Service Portal frameworks and IntegrationHub connectors to extend core platform APIs. These applications automate enterprise workflows across IT operations, customer service, and human resources functions by leveraging the Now Platform's underlying data model and orchestration engine. IT Service Management applications occupy the most mature margin pool, while Security Operations modules represent the fastest-growing segment as cyber resilience mandates intensify. Workflow Automation solutions lead solution offering deployments, though Analytics & Reporting tools are displacing legacy BI integrations as enterprises demand unified operational dashboards.
FDA 21 CFR Part 11 requirements shape validation protocols for life sciences deployments, while EU GDPR and the EU AI Act constrain how European enterprises process personal data through automated workflow engines. ISO 27001 certification has become a de facto market access threshold for store app publishers targeting regulated industries. Stakeholders must monitor how NIST cybersecurity framework revisions and emerging SEC disclosure rules reshape procurement criteria for governance and compliance tracking modules.
Market Dynamics
ISO 27001 certification requirements are compressing vendor qualification timelines while simultaneously fragmenting procurement authority across enterprise security, IT, and procurement functions.
Growth Catalysts
- SOC 2 Type II mandates:US SaaS vendors face customer-driven audit requirements that accelerate ServiceNow Store App deployments for automated evidence collection and control monitoring.
- Japan:METI's cybersecurity guidelines for critical infrastructure operators are driving observability and incident management module adoption among manufacturing conglomerates.
- AI-powered workflow engines:Natural language processing capabilities embedded in IT service management modules are reducing mean time to resolution for enterprise service desks.
Market Restraints
- Certified developer scarcity:Platform-specialized JavaScript engineers command rates that inflate implementation costs for mid-market enterprises.
- IntegrationHub dependency:Core workflow orchestration relies on ServiceNow's proprietary connector framework, creating single-vendor technical risk.
- EU AI Act classification:Automated decision-making modules face heightened conformity assessment burdens that extend sales cycles in European deployments.
Strategic Opportunities
- Brazil:ANVISA's digital health transformation initiative creates demand for validated IT service management in pharmaceutical manufacturing facilities.
- Integration of observability and security operations:Converged threat detection and performance monitoring modules address CISO-CIO alignment pressures.
- Outcome-based pricing models:Vendors can capture value through workflow automation efficiency gains rather than per-seat licensing.
Industry Challenges
- FDA 21 CFR Part 11 validation:Life sciences deployments require documented software validation protocols that extend implementation timelines and require specialized quality assurance expertise.
- Legacy ERP synchronization:Bidirectional data flows between ServiceNow instances and SAP or Oracle systems demand complex middleware development and ongoing maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Servicenow Store Apps Market |
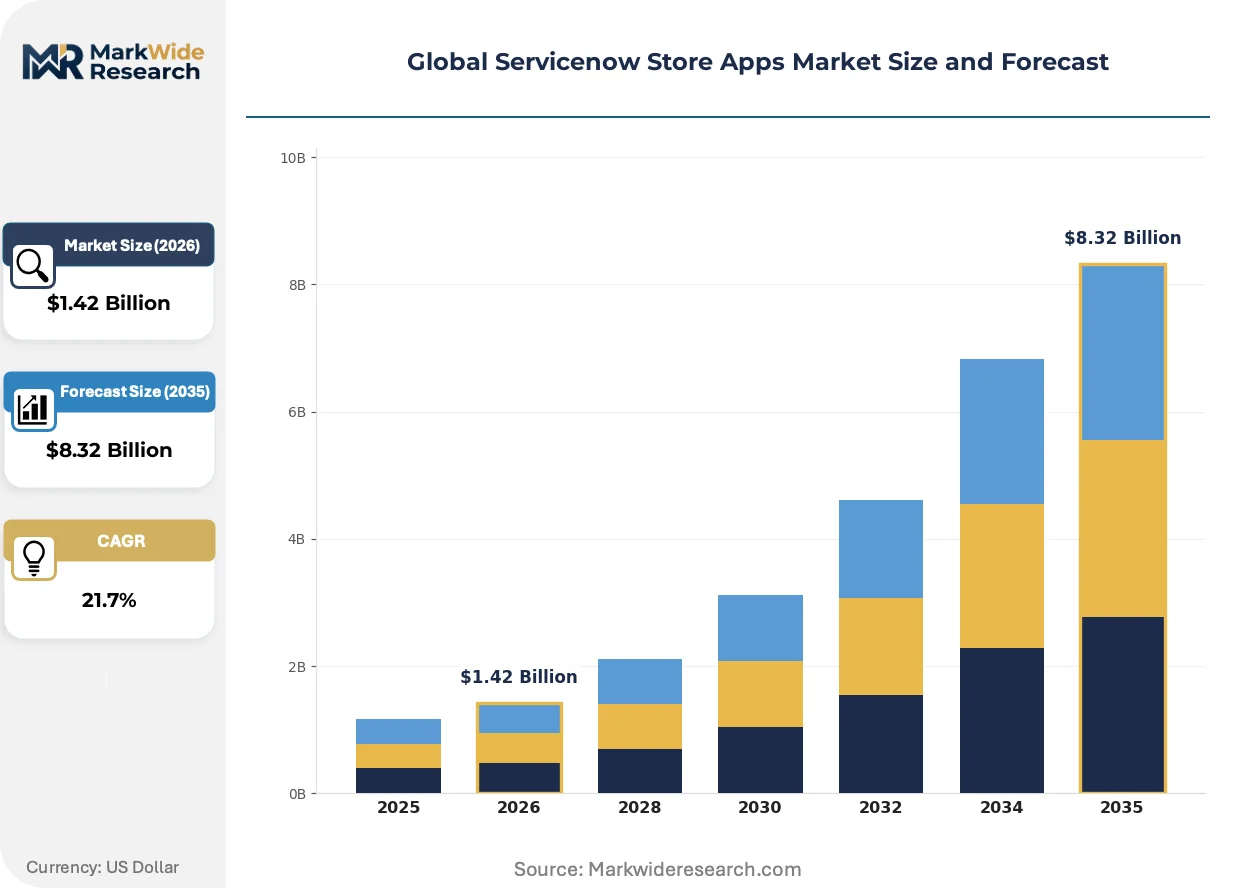
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $8.32 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: IT Service Management, Customer Support, Human Resources, DevOps, Security Operations, Finance Management Solution Offering: Workflow Automation, Analytics & Reporting, Asset Management, Incident Management, Change Management, Compliance Tracking End User Industry: Banking & Financial Services, Telecommunications, Government Agencies, Education Providers, Retail Chains, Energy Suppliers Deployment Model: Cloud-Based, On-Premise, Hybrid, Private Cloud, Public Cloud, Multi-Cloud |
| Companies Covered | SailPoint, IBM, TeamViewer, Dynatrace, Okta, PagerDuty, xMatters, Talkdesk, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Servicenow Store Apps Market Shifts & Advancements
Generative AI capabilities are embedding into workflow automation layers, while regulatory pressure on algorithmic accountability is reshaping how vendors architect decision-support modules.
Natural language interfaces for IT service management are bifurcating the user experience between technical operators and business stakeholders. Large enterprises in financial services are deploying conversational ticket creation for non-technical staff. This capability is compressing training requirements while expanding addressable user bases beyond traditional ITSM audiences.
EU AI Act risk classification requirements are forcing vendors to rearchitect automated decision modules with human-in-the-loop safeguards. High-risk workflow applications must now incorporate explainability features and audit trails. Security operations modules processing personal data across European enterprises face the most intensive conformity assessment redesigns.
Consolidated vendor preferences are displacing best-of-breed procurement patterns among Fortune 500 enterprises. Chief Information Officers are reducing supplier counts to simplify integration overhead and streamline support relationships. This concentration is most visible in United States federal agency deployments where FedRAMP authorization costs favor incumbent platform extensions over niche alternatives.
Global Servicenow Store Apps Market Segmentation
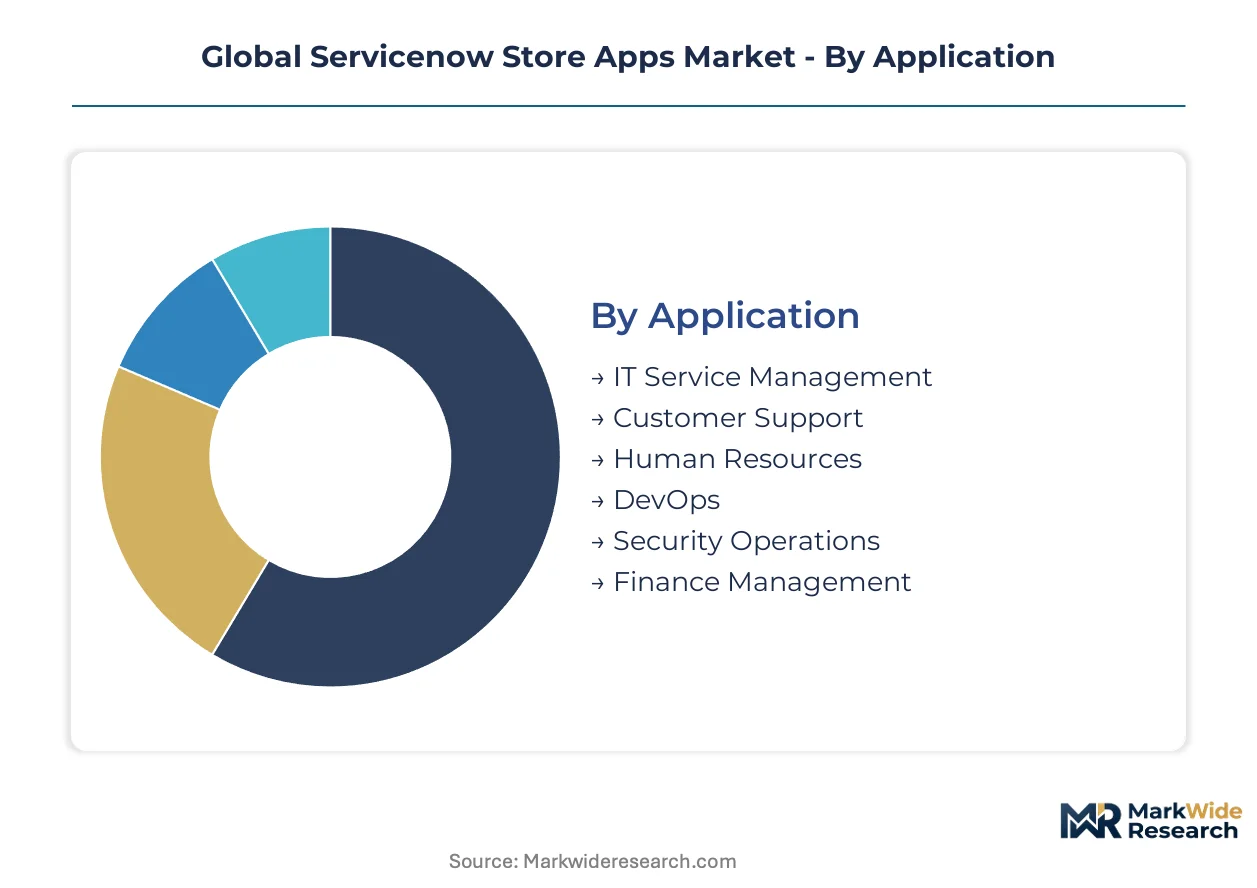
ServiceNow Store Apps serve heterogeneous enterprise needs across workflow automation, compliance, and IT operations. Segmentation reveals where platform specialization creates defensible margin pools versus commoditized deployment configurations.
Application:
IT Service Management faces substitution pressure from standalone SaaS ticketing platforms, while Security Operations modules build moats through compliance integration complexity.
- IT Service Management:Core incident, problem, and change management workflows built on ServiceNow's native data model. Banking & Financial Services in the United States drive premium deployments as FedRAMP authorization requirements favor incumbent platform extensions over niche alternatives.
- Security Operations:SOAR capabilities embedding threat intelligence and automated response into ITSM workflows. CISO-CIO alignment pressures in Fortune 500 enterprises accelerate procurement of converged observability and incident management modules.
- Customer Support:Field service and case management extensions for enterprise contact centers.
- Human Resources:Employee service delivery and onboarding automation modules.
- DevOps:CI/CD pipeline integration and release management tooling.
- Finance Management:Procurement workflow and vendor onboarding applications.
IT Service Management retains volume leadership; Security Operations holds the steepest expansion curve.
Solution Offering:
Cost tier differentiation separates enterprise-grade compliance modules from lightweight workflow builders targeting mid-market procurement budgets.
- Workflow Automation:Visual process designers and IntegrationHub connectors orchestrating cross-system tasks. Government Agencies in the United States deploy these for federal mandate tracking as OMB memoranda require automated evidence collection.
- Compliance Tracking:Control monitoring and audit trail modules for ISO 27001 and SOC 2 frameworks. European enterprises face EU AI Act conformity assessment burdens that extend sales cycles for automated decision-making components.
- Analytics & Reporting:Unified operational dashboards displacing legacy BI integrations.
- Asset Management:CMDB synchronization and hardware lifecycle tracking tools.
- Incident Management:PagerDuty-competitive alerting and escalation engines.
- Change Management:CAB automation and risk assessment workflows.
Workflow Automation captures the broadest deployment base; Compliance Tracking commands the highest per-seat pricing.
End User Industry:
Customer concentration varies sharply by vertical, with regulated industries tolerating longer implementation timelines for validated configurations.
- Banking & Financial Services:Fraud case management and regulatory reporting modules with hardened audit trails. Institutions in Switzerland deploy conversational ticket interfaces for non-technical staff, compressing training requirements while expanding addressable user bases.
- Government Agencies:FedRAMP-authorized ITSM and security operations suites. United States federal deployments favor incumbent platform extensions due to authorization cost barriers facing niche alternatives.
- Telecommunications:Network operations center integration and customer complaint routing.
- Education Providers:Student service portals and faculty onboarding systems.
- Retail Chains:Store-level IT support and supply chain incident tracking.
- Energy Suppliers:Critical infrastructure monitoring and NERC CIP compliance modules.
Banking & Financial Services generates the highest solution complexity; Government Agencies impose the most stringent procurement barriers.
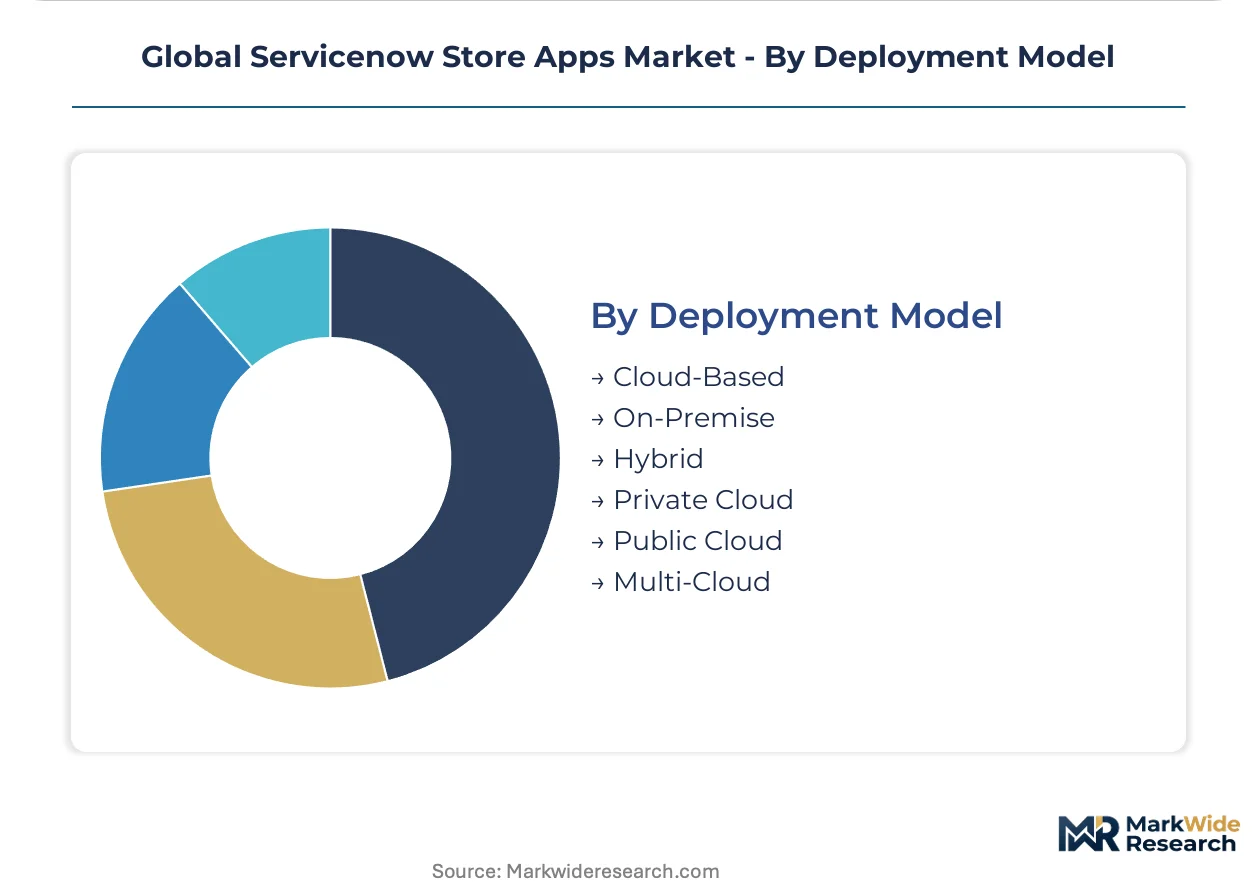
Deployment Model:
Supply concentration in ServiceNow's own cloud infrastructure limits differentiation among deployment configurations, with hybrid architectures gaining traction for data residency requirements.
- Cloud-Based:ServiceNow-hosted instances with automatic platform upgrades. Germany's BSI IT-Grundschutz requirements drive hybrid configurations for federal contractors processing personal data.
- Hybrid:Split workloads between cloud orchestration and on-premise data retention. Japanese manufacturing conglomerates under METI cybersecurity guidelines favor this model for observability modules protecting intellectual property.
- On-Premise:Self-managed instances for air-gapped environments.
- Private Cloud:Dedicated tenant isolation for single-organization deployments.
- Public Cloud:Shared infrastructure with standard security postures.
- Multi-Cloud:Cross-platform redundancy spanning AWS, Azure, and GCP footprints.
Cloud-Based deployments dominate new procurement; Hybrid configurations are climbing fastest among regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between compliance-heavy Western deployments and Asia-Pacific implementations driven by manufacturing operational efficiency rather than audit mandates.
United States
Federal agencies and Fortune 500 enterprises dominate premium procurement of IT service management and security operations modules. FedRAMP authorization requirements favor incumbent platform extensions over niche alternatives, compressing vendor qualification timelines. Washington D.C. and Northern Virginia clusters concentrate government deployments, while New York financial services firms drive conversational ticket interfaces for non-technical staff.
Germany
Industrial conglomerates under BSI IT-Grundschutz requirements favor hybrid cloud configurations for federal contractors processing personal data. Automotive and precision manufacturing headquarters in Stuttgart and Munich anchor demand for observability modules protecting intellectual property. METI-aligned Japanese manufacturers with German operations extend cybersecurity guidelines to European subsidiaries.
Japan
METI's cybersecurity guidelines for critical infrastructure operators drive observability and incident management module adoption among manufacturing conglomerates. Osaka and Nagoya industrial corridors concentrate deployments for supply chain workflow automation. Pharmaceutical facilities in Kansai region face ANVISA-aligned validation protocols for IT service management in regulated production environments.
Switzerland
Banking institutions in Zurich and Geneva deploy conversational ticket interfaces for non-technical staff, compressing training requirements while expanding addressable user bases. Swissmedic-regulated life sciences facilities require FDA 21 CFR Part 11 validation protocols for software deployments. Private banking compliance mandates accelerate procurement of governance and audit trail modules.
Brazil
ANVISA's digital health transformation initiative creates demand for validated IT service management in pharmaceutical manufacturing facilities. São Paulo state concentrates enterprise procurement of workflow automation tools as ISO 27001 compliance requirements tighten across Latin American operations. Energy suppliers in Rio de Janeiro deploy critical infrastructure monitoring modules under emerging national cybersecurity frameworks.
Global Servicenow Store Apps Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform-native certification and identity federation expertise creating separation between premium and standard service tiers. The competitive landscape bifurcates around certified developer scarcity, with platform-specialized engineers commanding implementation rates that inflate costs for mid-market enterprises. Three archetypes dominate: security-centric integrators leveraging identity expertise, AI-powered observability specialists embedding into workflows, and network infrastructure anchors bridging IT operations and service desk automation. M&A activity concentrates on workflow automation capabilities, while strategic partnerships target converged threat detection and performance monitoring modules.
Within the security-centric tier, Okta and SailPoint exemplify identity federation specialists that dominate sensitive app integrations. Dynatrace occupies a position among AI-powered observability leaders embedding modules directly into ServiceNow workflows. Cisco Systems anchors the network operations segment with incident management capabilities bridging infrastructure and service desk automation.
| Leading Market Players |
|---|
| SailPoint |
| IBM |
| TeamViewer |
| Dynatrace |
| Okta |
| PagerDuty |
| xMatters |
| Talkdesk |
| Cisco Systems |
| Others |
Supply & Pricing Matrix
Platform-scale economies in ServiceNow's cloud infrastructure compress marginal delivery costs for certified app publishers while elevating price floors for mid-market buyers lacking volume leverage. This concentration dynamic bifurcates the market between enterprise-grade compliance modules commanding premium positioning and lightweight workflow tools competing on accessibility.
Pricing Analysis
Contract structures in this market center on annual recurring subscriptions with tiered seat-based scaling, though outcome-based arrangements are gaining traction among Fortune 500 accounts seeking workflow efficiency guarantees. Price differentiation rests on ISO 27001 certification status and IntegrationHub connector depth, with FedRAMP-authorized extensions capturing substantial premiums over uncertified alternatives. Cost compression in the mid-market tier intensifies as standalone SaaS ticketing platforms erode ServiceNow's core ITSM pricing power. Government agencies and regulated financial services firms exhibit the lowest price sensitivity, while retail chains and education providers drive procurement negotiations toward standard-tier configurations.
Supply Chain Analysis
Inventory strategy preferences in enterprise software favor just-in-time deployment through ServiceNow's centralized app repository, minimizing customer-side infrastructure commitment. Supply concentration centers on the United States for FedRAMP-authorized development, Germany for BSI IT-Grundschutz-aligned engineering, and Japan for METI-guided observability modules. Critical dependencies include certified JavaScript engineering talent, proprietary IntegrationHub connector frameworks, and cloud compute capacity from hyperscaler partnerships. Single-source vulnerability runs through ServiceNow's platform governance layer, where certification gatekeeping controls market access. Distribution runs through direct enterprise sales channels, systems integrator partnerships, and the ServiceNow Store digital marketplace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from standalone AI-native workflow platforms that bypass ServiceNow's integration overhead, requiring defensive repositioning around compliance-embedded moats. Three stakeholder archetypes demand differentiated strategic responses.
For Market Incumbents: Shield core ITSM margins by deepening IntegrationHub connector ecosystems that increase customer switching costs. Acquire certified developer capacity in Germany and Japan to reduce reliance on premium contractor rates. Counter standalone AI ticketing threats by embedding generative capabilities natively into existing workflow modules rather than bolting on peripheral features. For New Entrants and Emerging Players: Mid-market compliance automation gaps in Brazil and Switzerland offer the most penetrable white space, where ANVISA validation requirements and Swissmedic audit protocols outpace incumbent coverage. Target pharmaceutical manufacturing facilities in São Paulo state with pre-validated IT service management configurations. Pursue channel partnerships with regional systems integrators possessing existing ServiceNow platform credentials to bypass direct certification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among security operations specialists with embedded SOAR capabilities and existing FedRAMP authorization. Long-term viability favors vendors converging observability and threat detection functions, as CISO-CIO alignment pressures consolidate procurement authority. Monitor EU AI Act conformity assessment completion rates as an inflection signal for European sales cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepening IntegrationHub connectors increases customer switching costs and retention. |
| Acquisition of Specialist Firm | Certified developer teams in Germany or Japan reduce implementation cost inflation. |
| Product Launch | FedRAMP-authorized security modules capture federal procurement preference. |
| Strategic Partnership | Identity federation alliances with Okta or SailPoint accelerate enterprise adoption. |
| Geographic Expansion | ANVISA-aligned validation capabilities unlock Brazilian pharmaceutical manufacturing demand. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and ServiceNow platform certification databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and systems integration specialists. Primary fieldwork across North America, Europe, and Asia-Pacific validated deployment timelines, pricing benchmarks, and regulatory compliance burdens. Secondary sources included FDA 21 CFR Part 11 guidance documents, EU AI Act implementing acts, and METI cybersecurity framework updates. Bottom-up sizing of certified app publisher revenues triangulated against top-down platform ecosystem value estimates.
Variance decomposition across the projection horizon isolates growth contributions from workflow automation expansion, security operations module adoption, and compliance tracking displacement of legacy BI tools. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to historical platform extension penetration patterns. Industry-specific forecast inputs encompass FedRAMP authorization queue lengths and EU AI Act conformity assessment completion rates.
Underlying assumptions cover sustained enterprise SaaS procurement budgets, stable ServiceNow platform governance frameworks, and gradual AI capability embedding without disruptive architecture shifts, with deviation risk concentrated in regulatory timeline delays and certified developer supply constraints. Revision becomes warranted when standalone AI-native workflow platforms achieve functional parity on core ITSM use cases or when NIST cybersecurity framework revisions materially alter control monitoring requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Technical Illustration Software Market
Software & Services
Software Release Management Tools Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Sales Training Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Stock Control Software Market
Software & Services
Device Tracking Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Saas Based HRM Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Global Apparel Management Software Market
Software & Services
Global Business Management Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Global VR Game Engine Software Market