
 Asia-Pacific Digital Signage Software Market | 2026-2036
Asia-Pacific Digital Signage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Signage Software Market Outlook
ISO/IEC 27001 certification is unwinding competitive access across the Asia-Pacific Digital Signage Software Market, filtering out vendors lacking enterprise-grade security credentials. Samsung Electronics leverages its vertical display manufacturing base to anchor premium hardware-software bundles across South Korean and Australian deployments. LG Electronics sustains cloud-based platform R&D through captive data centers in Singapore and Japan. BrightSign LLC specializes in compact media player firmware that competes on low-latency synchronization for multi-screen retail environments.
Asia-Pacific digital signage software comprises applications that schedule, distribute, and monitor multimedia content across networked display endpoints, typically requiring HTML5 rendering engines and API connectivity to IoT sensors for real-time content adaptation. The primary commercial purpose centers on audience engagement analytics and centralized brand messaging across distributed physical locations. Cloud-based deployment leads solution architecture as enterprises prioritize remote management and subscription economics over capital-intensive on-premise installations. Content management solutions anchor margin pools where recurring licensing integrates with creative workflow tools, while analytics modules represent the fastest-growing segment as retailers demand footfall-to-conversion attribution.
Japan's METI enforces energy efficiency standards for commercial displays that shape hardware procurement criteria cascading into software optimization requirements. China's MIIT governs data localization for cloud-hosted content platforms, compelling vendors to maintain domestic server infrastructure. India's TRAI regulations on broadband quality of service indirectly influence network management solution specifications for reliable content delivery. Stakeholders must weigh certification burdens against localization mandates when selecting market entry sequencing across the region's fragmented compliance terrain.
Market Dynamics
Cloud-native deployment architectures are compressing vendor margins while expanding addressable customer bases across mid-market retailers in Asia-Pacific, forcing incumbents to restructure licensing models around consumption-based billing.
Growth Catalysts
- Smart city infrastructure mandates:China's MIIT guidelines for urban digitalization require integrated display networks in transit hubs, creating procurement pipelines for software vendors with real-time data integration capabilities.
- Retail footfall analytics demand:Southeast Asian shopping mall operators are deploying computer vision-enabled signage to track shopper pathways and optimize tenant placement, driving subscription growth for analytics modules.
- ISO/IEC 27001 certification requirements:Enterprise buyers across Australia and Japan are filtering vendor shortlists to certified providers, accelerating security investment among mid-tier software developers.
Market Restraints
- Data localization compliance costs:China's MIIT and India's TRAI requirements for domestic server infrastructure force vendors to maintain fragmented cloud architectures, elevating operational overhead.
- Display hardware supply concentration:South Korean and Chinese panel manufacturers control premium commercial display output, creating margin pressure on software bundling negotiations.
- Legacy on-premise installation base:Japanese enterprises with extensive existing signage networks face high switching costs to cloud architectures, slowing replacement cycles.
Strategic Opportunities
- Tier-two and tier-three Chinese cities:Smart city budgets are expanding beyond Beijing, Shanghai, and Shenzhen into provincial capitals where first-mover software vendors can anchor municipal contracts.
- Healthcare wayfinding applications:Australian hospital networks are piloting interactive directory systems, opening a vertical with specialized compliance requirements and long contract durations.
- India's PLI scheme for electronics manufacturing:Domestic display production incentives are reducing hardware costs for Indian deployers, expanding the addressable market for software licensing.
Industry Challenges
- Multi-protocol integration complexity:Retailers demand seamless connectivity between signage platforms, POS systems, and inventory databases, requiring vendor investment in API development and certification testing.
- Cybersecurity talent scarcity:Vendors serving Australian financial services and government buyers struggle to recruit personnel with both ISO/IEC 27001 implementation experience and regional language capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Signage Software Market |
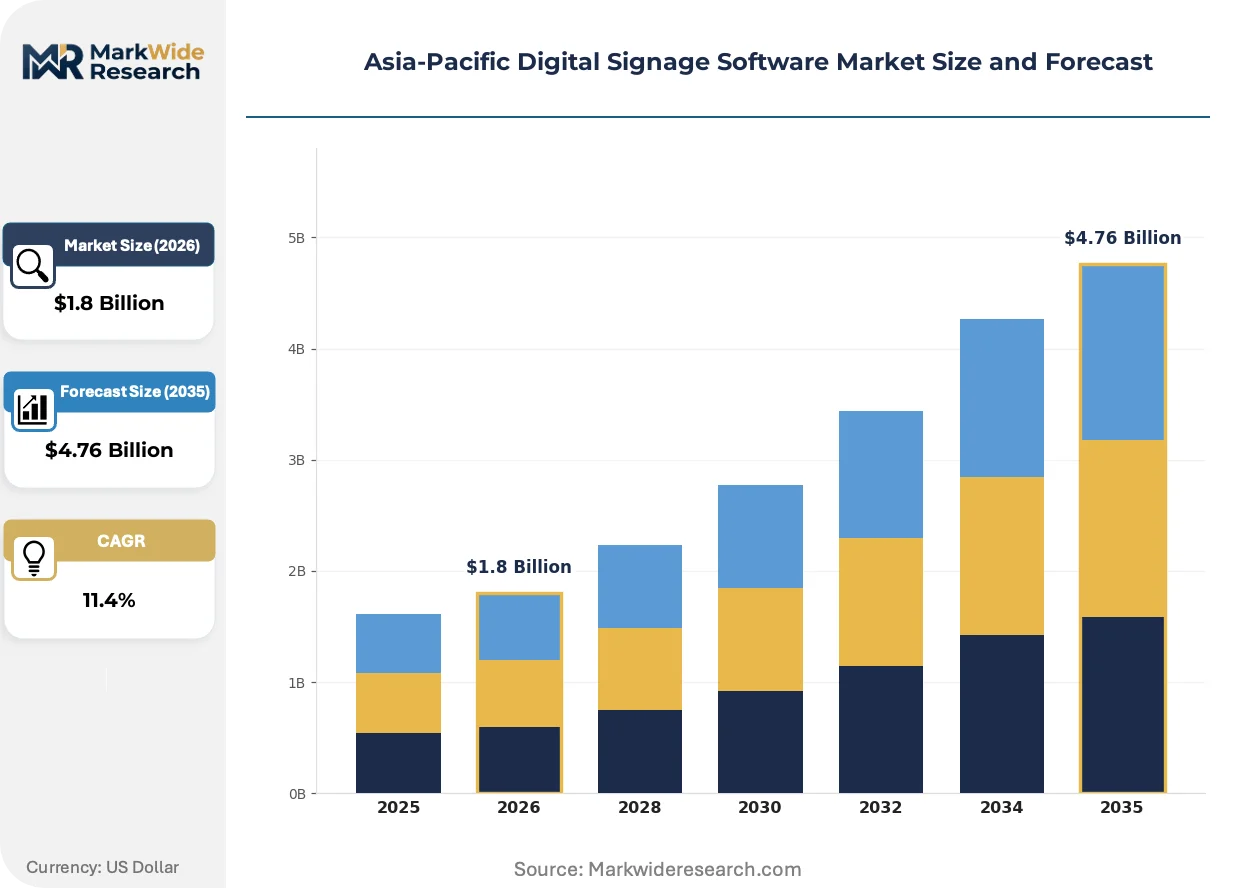
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Retail, Education, Transportation, Healthcare Solution: Content Management, Network Management, Analytics, Security Industry Vertical: Hospitality, Banking, Entertainment, Corporate |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics, Sony Group Corporation, Sharp NEC Display Solutions, Ltd., Panasonic Holdings Corporation, BrightSign LLC, Scala, NEC Display Solutions, AUO Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Signage Software Market Strategic Shifts
Edge computing architectures are redistributing processing loads away from centralized clouds, enabling sub-second content adaptation that responds to local environmental triggers without latency penalties.
HTML5 rendering engines with WebGL acceleration are fragmenting the competitive landscape between lightweight browser-based players and proprietary firmware stacks. Mid-market retailers in Thailand and Vietnam are adopting open-standard solutions to avoid vendor lock-in, compressing pricing power for integrated hardware-software bundles while expanding the addressable base for pure-play software vendors.
Japan's METI energy efficiency standards for commercial displays are cascading into software optimization requirements, compelling developers to implement adaptive brightness algorithms and sleep-mode scheduling. Vendors serving the Japanese market must now certify power consumption metrics alongside content performance, adding compliance layers that favor established players with dedicated certification resources.
Subscription-based procurement is displacing perpetual licensing across Australian and South Korean enterprise buyers, who prefer operational expenditure treatment for digital signage deployments. Systems integrators are responding by unbundling hardware procurement from software licensing, creating multi-vendor solution architectures that shift margin capture toward ongoing service relationships rather than upfront installation fees.
Asia-Pacific Digital Signage Software Market Segmentation
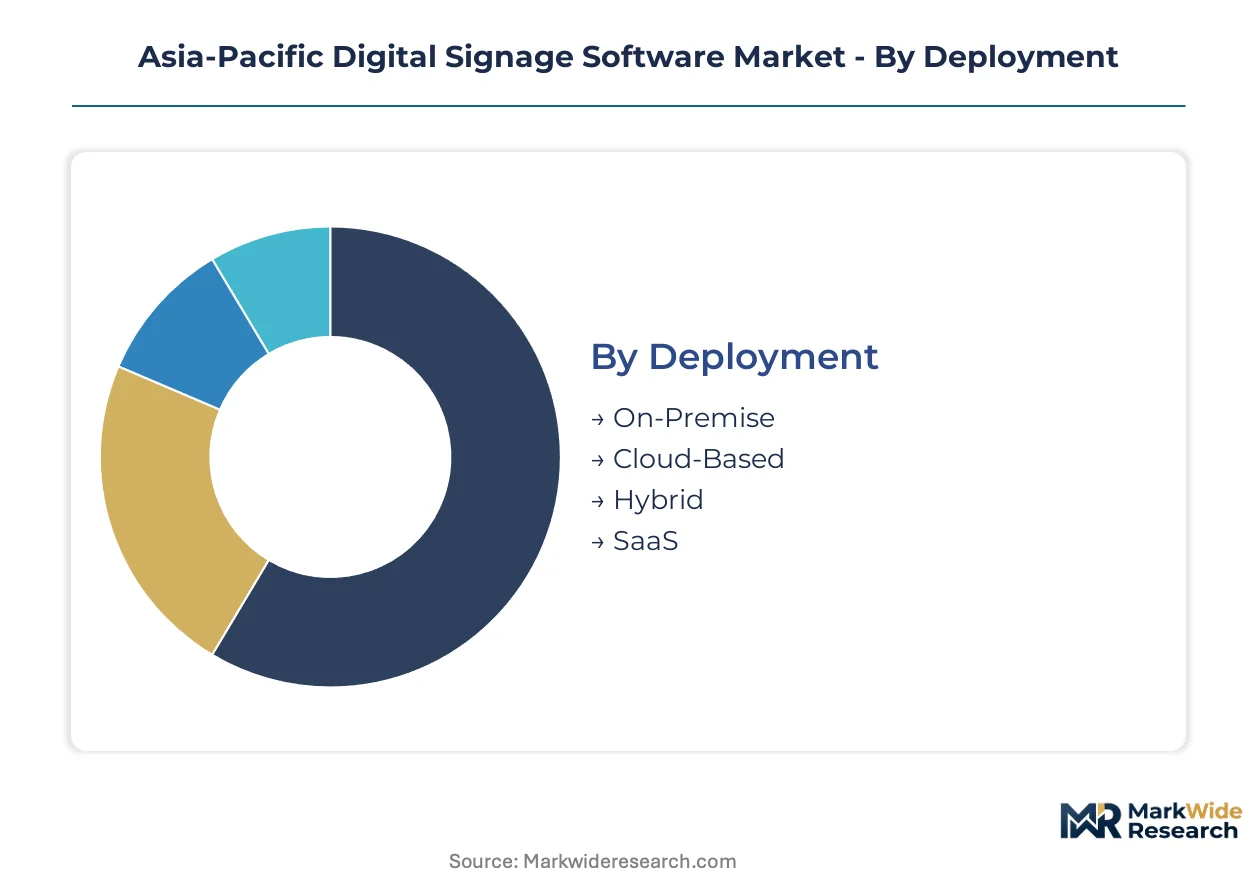
Segmentation in Asia-Pacific digital signage software reveals how deployment choices, end-user requirements, and solution architectures map to distinct compliance burdens and margin structures across the region's fragmented regulatory terrain.
Deployment:
China's MIIT data localization mandates and India's TRAI server requirements create divergent infrastructure obligations that reshape total cost of ownership across deployment modes.
- Cloud-Based:Dominant architecture utilizing distributed server infrastructure to enable remote content management and subscription billing. Australian and Japanese enterprise buyers prioritize ISO/IEC 27001-certified cloud platforms for multi-site retail networks, though China's MIIT regulations force domestic server replication that elevates operational overhead.
- On-Premise:Legacy installations residing within customer data centers requiring dedicated IT maintenance staff. Japanese manufacturing conglomerates and South Korean chaebol subsidiaries retain substantial on-premise footprints due to existing capital investments and internal security protocols that predate cloud-native alternatives.
- Hybrid:Split architectures combining local edge processing with centralized cloud orchestration. Southeast Asian shopping mall operators deploy hybrid models to balance real-time content adaptation with centralized analytics aggregation across dispersed locations.
- SaaS:Pure subscription delivery eliminating hardware procurement through browser-based management portals. Mid-market retailers in Thailand and Vietnam favor SaaS consumption to convert capital expenditure into operational expenditure for financial statement treatment.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
End User:
Application intensity varies sharply by sector, with footfall analytics investment and compliance requirements driving divergent software specification priorities.
- Retail:Primary demand vertical encompassing department stores, convenience chains, and specialty merchandisers deploying screen networks for promotional content and shopper journey mapping. China's tier-one city retail operators integrate digital signage with smart city transit data for dynamic promotional timing.
- Healthcare:Hospital networks and clinic operators utilizing wayfinding directories and queue management displays. Australian state health systems pilot interactive directory installations with specialized accessibility compliance and extended contract durations that reshape vendor cash flow profiles.
- Transportation:Airports, rail terminals, and municipal transit authorities requiring real-time information dissemination. China's MIIT smart city mandates create procurement pipelines for vendors with IoT sensor integration and emergency broadcast capabilities.
- Education:Universities and K-12 institutions deploying campus-wide communication networks. Indian educational technology budgets expand screen installations for hybrid learning infrastructure, though procurement cycles remain elongated due to public sector tender requirements.
Retail commands current deployment scale; Healthcare offers the steepest expansion trajectory.
Solution:
Margin capture concentrates in workflow-integrated modules where recurring licensing meets creative production tools, while adjacent functions compete on technical differentiation.
- Content Management:Core scheduling and distribution platforms with HTML5 rendering engines and template libraries. Content Management anchors margin pools across the region where recurring licensing integrates with creative workflow tools for brand marketing teams.
- Analytics:Computer vision-enabled footfall tracking and conversion attribution modules. Southeast Asian shopping mall operators drive subscription growth for Analytics as tenant placement optimization demands granular shopper pathway data.
- Network Management:Device monitoring, firmware update orchestration, and bandwidth optimization tools. India's TRAI quality of service regulations indirectly shape Network Management specifications for reliable content delivery across variable broadband infrastructure.
- Security:Encryption, access control, and audit logging functions achieving ISO/IEC 27001 alignment. Australian financial services and government buyers filter vendor shortlists to Security-certified providers, accelerating investment among mid-tier developers.
Content Management captures recurring revenue depth; Analytics gains share fastest.
Industry Vertical:
Vertical specialization requirements fragment addressable markets, with hospitality and banking presenting contrasting compliance and integration complexity profiles.
- Hospitality:Hotels, resorts, and food service operators deploying guest-facing information and promotional displays. Japan's METI energy efficiency standards cascade into Hospitality software requirements through adaptive brightness algorithms and sleep-mode scheduling mandates.
- Banking:Financial institutions utilizing queue management and product marketing screens across branch networks. Australian banking regulators emphasize cybersecurity frameworks that elevate Security module procurement specifications for domestic deployments.
- Corporate:Enterprise internal communication networks and lobby displays for brand messaging. South Korean conglomerate headquarters drive Corporate segment demand for synchronized multi-screen installations with low-latency firmware requirements.
- Entertainment:Cinemas, gaming venues, and live event spaces requiring high-refresh dynamic content. China's tier-one city entertainment complexes integrate digital signage with social media feeds for real-time audience engagement.
Hospitality leads current vertical penetration; Banking presents the most demanding certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific submarine cable network carrying 99% of intra-regional data traffic underwrites digital signage software deployment scalability from Seoul to Sydney.
China
Smart city infrastructure mandates in transit hubs and commercial districts drive procurement pipelines for vendors with real-time data integration capabilities. MIIT data localization requirements force domestic server infrastructure maintenance, elevating operational overhead for cloud-hosted platforms. Tier-one cities Beijing, Shanghai, and Shenzhen anchor initial deployments, while provincial capitals expand municipal budgets for integrated display networks.
Japan
Enterprise buyers filter vendor shortlists to ISO/IEC 27001-certified providers, accelerating security investment among mid-tier software developers. METI enforces energy efficiency standards for commercial displays that cascade into software optimization requirements through adaptive brightness algorithms. Tokyo and Osaka manufacturing conglomerates retain substantial on-premise footprints due to existing capital investments.
India
Retail chains expand screen networks for in-store engagement while educational technology budgets grow screen installations for hybrid learning infrastructure. BIS certification requirements for electronic displays tighten product compliance timelines. Maharashtra and Karnataka host pilot smart city deployments where software vendors anchor municipal contracts for transit-integrated signage.
Australia
Hospital networks pilot interactive directory systems, opening a vertical with specialized accessibility compliance and long contract durations. Financial services and government buyers emphasize cybersecurity frameworks that elevate procurement specifications for security-certified providers. New South Wales and Victoria concentrate enterprise subscription growth as operational expenditure treatment displaces perpetual licensing.
South Korea
Conglomerate headquarters drive demand for synchronized multi-screen installations with low-latency firmware requirements. Cloud-native deployment architectures expand addressable customer bases across mid-market retailers, forcing restructuring of licensing models around consumption-based billing. Seoul anchors premium hardware-software bundle negotiations leveraging domestic vertical display manufacturing.
Asia-Pacific Digital Signage Software Market Competitive Environment
Listed leaders compete with private specialists across security certification and cloud infrastructure dimensions, producing a tiered structure where enterprise-grade credentials filter market access. The vendor base concentrates around three strategic archetypes: diversified electronics conglomerates with captive display manufacturing, pure-play software developers with API-centric platforms, and systems integrators unbundling hardware from software procurement. Dominant competitive moves include geographic expansion through domestic server replication and portfolio diversification into analytics modules for footfall attribution.
Among diversified electronics conglomerates, Samsung Electronics Co., Ltd. and LG Electronics exemplify the hardware-software bundle archetype, while BrightSign LLC occupies a position within the compact media player specialization tier. Samsung Electronics leverages vertical manufacturing bases to anchor premium deployments, LG Electronics sustains cloud-based platform development through regional data center infrastructure, and BrightSign competes on low-latency synchronization capabilities for multi-screen retail environments.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| Sony Group Corporation |
| Sharp NEC Display Solutions, Ltd. |
| Panasonic Holdings Corporation |
| BrightSign LLC |
| Scala |
| NEC Display Solutions |
| AUO Corporation |
| Others |
Value Chain & Pricing Dynamics
HTML5 rendering engines substituting for proprietary firmware stacks are redistributing procurement geography toward Vietnam and Thailand while compressing margin capture for integrated hardware-software bundles across the Asia-Pacific Digital Signage Software Market.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and small-business bands. Pricing differentiates by ISO/IEC 27001 certification grade and deployment scale, with uncertified vendors competing on raw subscription rates. Cost compression in the mid-market tier is intensifying because open-source rendering engines eliminate proprietary player premiums. Small-business buyers in Vietnam and Thailand exhibit highest price sensitivity, while Australian financial services buyers prioritize security-certified platforms regardless of cost premium.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors fluctuate with container availability across the China-South Korea trade lane. Panel supply concentrates in South Korea and China, while media player assembly draws from Taiwan and Malaysia. Semiconductor components for edge-computing nodes rest on single-source vulnerability from foundry concentration. Distribution runs through systems integrators who unbundle hardware procurement from software licensing across Australian and Japanese enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against browser-based open-source platforms that threaten proprietary firmware margins across Southeast Asian retail deployments.
For Market Incumbents: Fortify certification moats by accelerating ISO/IEC 27001 investment among mid-tier developer portfolios. Deepen backward integration into captive display manufacturing to preserve hardware-software bundle pricing power against pure-play software erosion. Anchor municipal smart city contracts in China's tier-two provincial capitals before cloud-native entrants establish first-mover positions. For New Entrants and Emerging Players: Lead with SaaS consumption models targeting Thai and Vietnamese mid-market retailers seeking operational expenditure treatment. India's PLI-scheme electronics manufacturing incentives create white-space opportunity as domestic hardware cost reductions expand software addressable markets. Position through API-centric platforms that promise open-standard connectivity without vendor lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed analytics specialists possessing computer vision footfall attribution capabilities but lacking cloud infrastructure scale. Long-term viability hinges on recurring revenue depth from content management workflows rather than one-time installation fees. Watch for inflection when Australian hospital wayfinding pilots convert to system-wide procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Investment | Filters vendor shortlists for Australian financial services and government buyers demanding enterprise-grade security credentials. |
| Domestic Server Infrastructure Replication | Complies with China's MIIT data localization mandates while elevating operational overhead for cloud-hosted platforms. |
| Analytics Module Development | Captures subscription growth from Southeast Asian mall operators optimizing tenant placement through shopper pathway data. |
| Edge Computing Architecture Deployment | Enables sub-second content adaptation for Japanese METI energy efficiency compliance without latency penalties. |
| API Integration Ecosystem Expansion | Addresses retailer demand for seamless connectivity between signage platforms, POS systems, and inventory databases. |
Study Parameters
A standing panel of digital signage software product managers, retail IT procurement officers, systems integration specialists, and cloud platform engineers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against SEC filings of listed electronics conglomerates, MIIT smart city procurement disclosures, and TRAI broadband quality of service reports. Bottom-up deployment counts triangulated against top-down addressable market estimates from cloud infrastructure hyperscaler capex disclosures.
Consistency checks validated volume and value outputs against external benchmarks including regional data center expansion timelines and commercial display import records. The analytical framework modeled deployment mode, organization size, vertical application, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level adoption curves weighted by compliance burden intensity and infrastructure readiness indices.
The analysis sits within stated boundaries; outcomes outside sustained cloud-native migration, stable data localization enforcement, or continued smart city budget expansion would require recalibration. Forecasts reflect assumptions regarding certification timeline adherence and panel supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Contract Abstraction Software Market
Software & Services
Staffing Software Market
Software & Services
Global Microscope Software Market
Software & Services
Labeling Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Hotel Management Software Market
Software & Services
Global Nosql Database Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Batch Management Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Global Virtualization Software Market