
 Configure Price and Quote (CPQ) Market | 2026-2036
Configure Price and Quote (CPQ) Market Size, Share, and Industry Trends Forecast 2026-2036
Configure Price and Quote (CPQ) Market Insights
Mid-market manufacturers is bifurcating CPQ demand away from legacy enterprise buyers as configure-to-order workflows penetrate industrial machinery and medical device sectors. Salesforce, Inc. leverages its CRM-native architecture to embed quoting logic within existing sales workflows. SAP SE anchors its position through deep ERP integration that synchronizes engineering change orders with pricing rules. Oracle Corporation competes by extending cloud infrastructure advantages into subscription-based CPQ modules for recurring revenue models.
Configure Price and Quote software automates the multi-variable assembly of product configurations, dynamic pricing calculations, and proposal generation through rule-based engines that constrain incompatible feature combinations. Its primary commercial purpose eliminates manual quoting errors and accelerates sales cycle velocity for businesses offering customizable or engineer-to-order portfolios. Cloud-Based deployment leads segment expansion as vendors retire on-premises maintenance streams and redirect R&D toward API-first architectures. The Integrated solution type captures widening preference as buyers reject standalone quoting tools that fragment customer data across CRM and ERP systems.
The EU AI Act imposes algorithmic transparency requirements on automated pricing engines deployed across European operations, compelling vendors to document decision logic for configurable quote generation. In the United States, the SEC's evolving disclosure frameworks for software procurement indirectly elevate CPQ audit trails as enterprises document sales technology investments. ISO 27001 certification has become a de facto market access threshold for vendors serving finance and healthcare verticals. Stakeholders must evaluate how generative AI integration into configuration engines alters liability exposure and compliance documentation burdens.
Market Dynamics
Cloud migration mandates under the EU AI Act and analogous data governance frameworks are forcing CPQ vendors to rearchitect algorithmic transparency into automated pricing engines while mid-market manufacturers accelerate adoption of configure-to-order workflows.
Growth Catalysts
- EU AI Act compliance:Algorithmic transparency requirements for automated pricing engines are compelling enterprises to upgrade legacy quoting systems, creating replacement demand across European industrial machinery and medical device sectors.
- Configure-to-order penetration:Engineer-to-order workflows in complex equipment manufacturing are driving CPQ adoption as product configurability requirements intensify beyond what spreadsheet-based quoting can support.
- Mid-market acceleration:Industrial machinery manufacturers in the United States, Germany, and Japan are expanding CPQ procurement as sales cycle velocity becomes a competitive differentiator against larger enterprise rivals.
Market Restraints
- Integration complexity:Fragmented data architectures between CRM, ERP, and PLM systems create implementation friction that extends deployment timelines and elevates professional services costs.
- Technical debt accumulation:Legacy on-premises CPQ installations in industrial equipment sectors resist cloud migration due to customized rule engines that lack equivalent API-first alternatives.
- Skill scarcity:Shortage of professionals capable of bridging sales operations, product engineering, and software configuration constrains enterprise deployment velocity.
Strategic Opportunities
- Generative AI convergence:Large language models integrated with constraint-based configuration engines can automate natural language proposal generation and technical specification drafting.
- Subscription pricing expansion:Equipment-as-a-service business models in industrial automation create demand for CPQ modules that handle recurring revenue calculations alongside traditional capital equipment quotes.
- API-first architectures:Headless CPQ deployments embedded within vertical SaaS platforms open channel partnerships with industry-specific software vendors serving niche manufacturing segments.
Industry Challenges
- ISO 27001 certification burden:Finance and healthcare verticals require documented information security management systems, extending vendor sales cycles and elevating compliance costs.
- Rule engine maintenance overhead:Product configuration logic requires continuous updates as engineering change orders propagate through bill-of-materials structures, demanding dedicated administrator resources.
- Liability exposure from AI-generated quotes:Generative AI integration into pricing recommendations creates uncertainty around accountability for erroneous configurations or discriminatory pricing outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Configure Price and Quote (CPQ) Market |
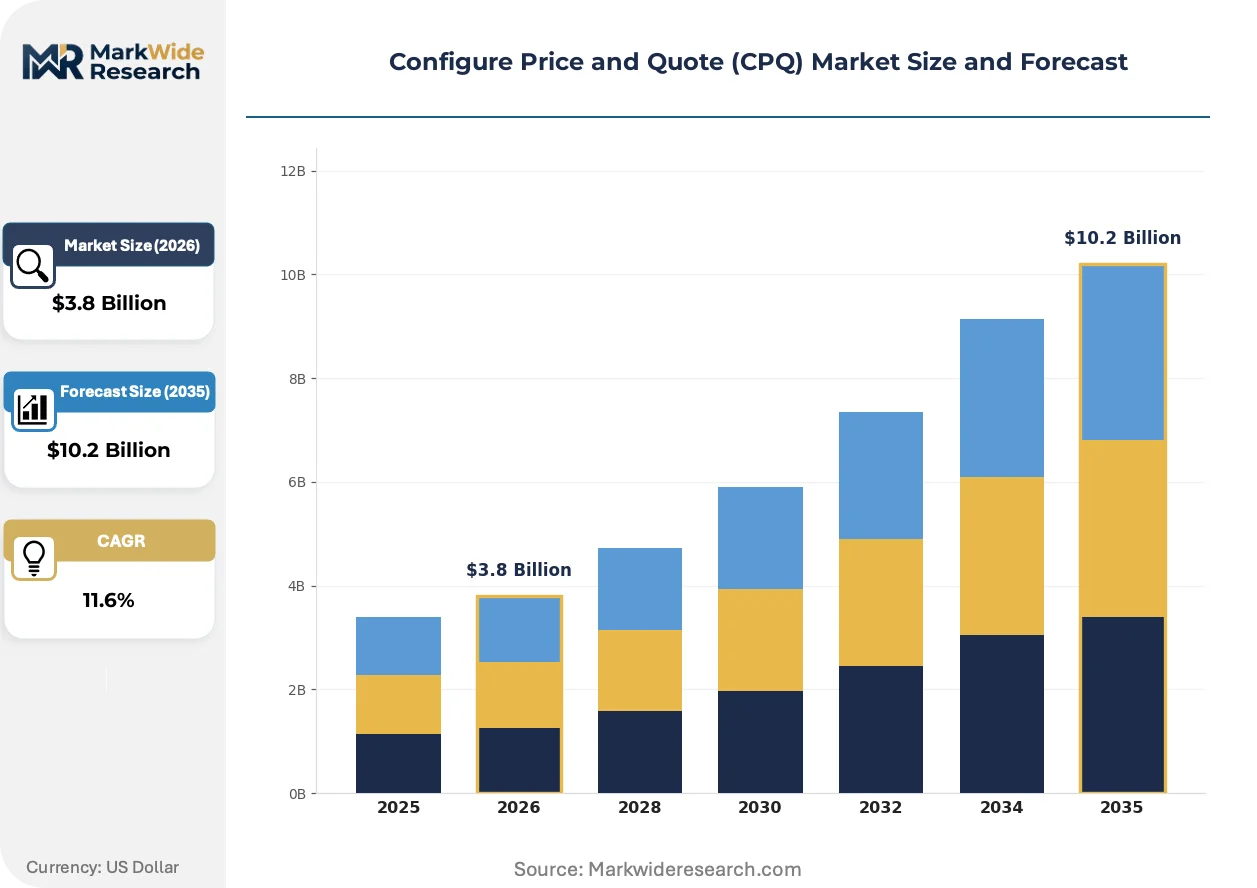
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
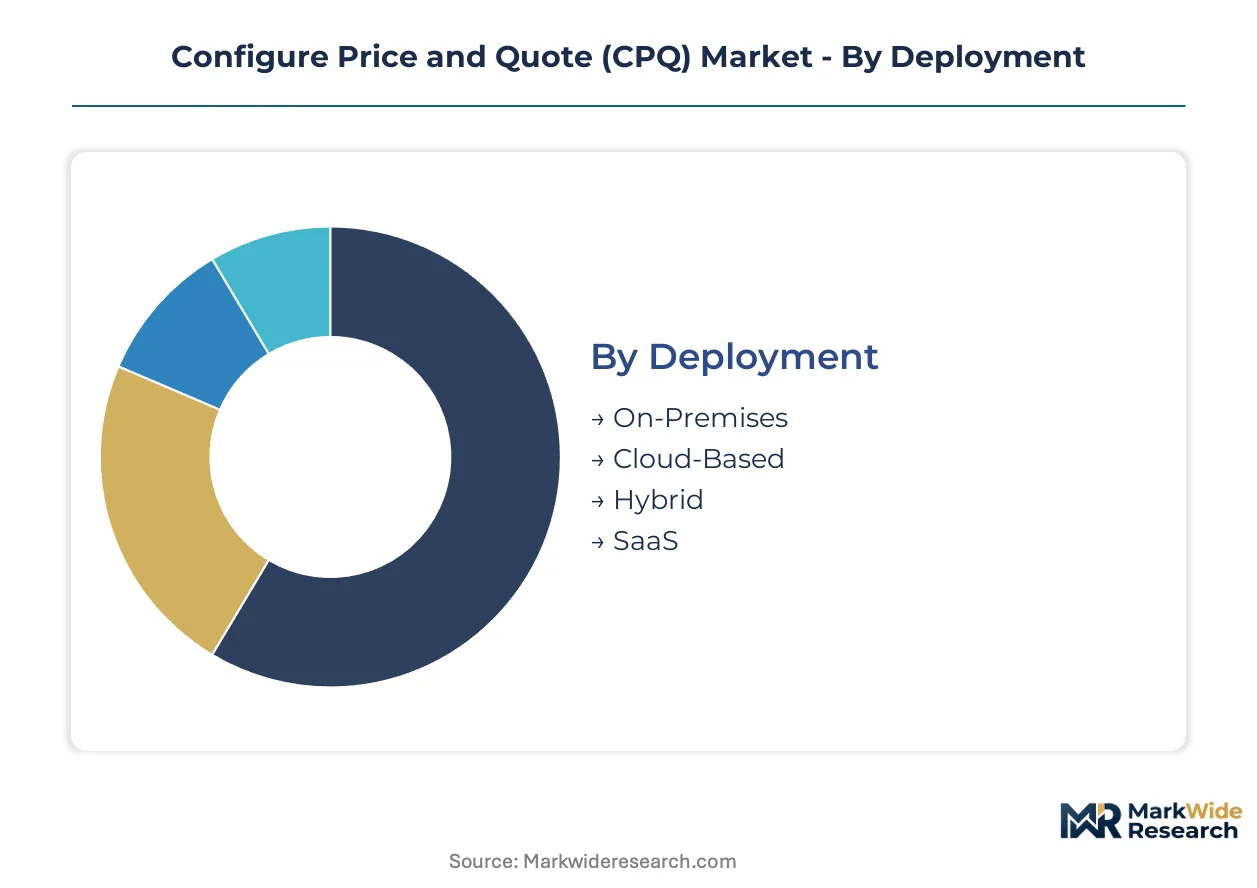
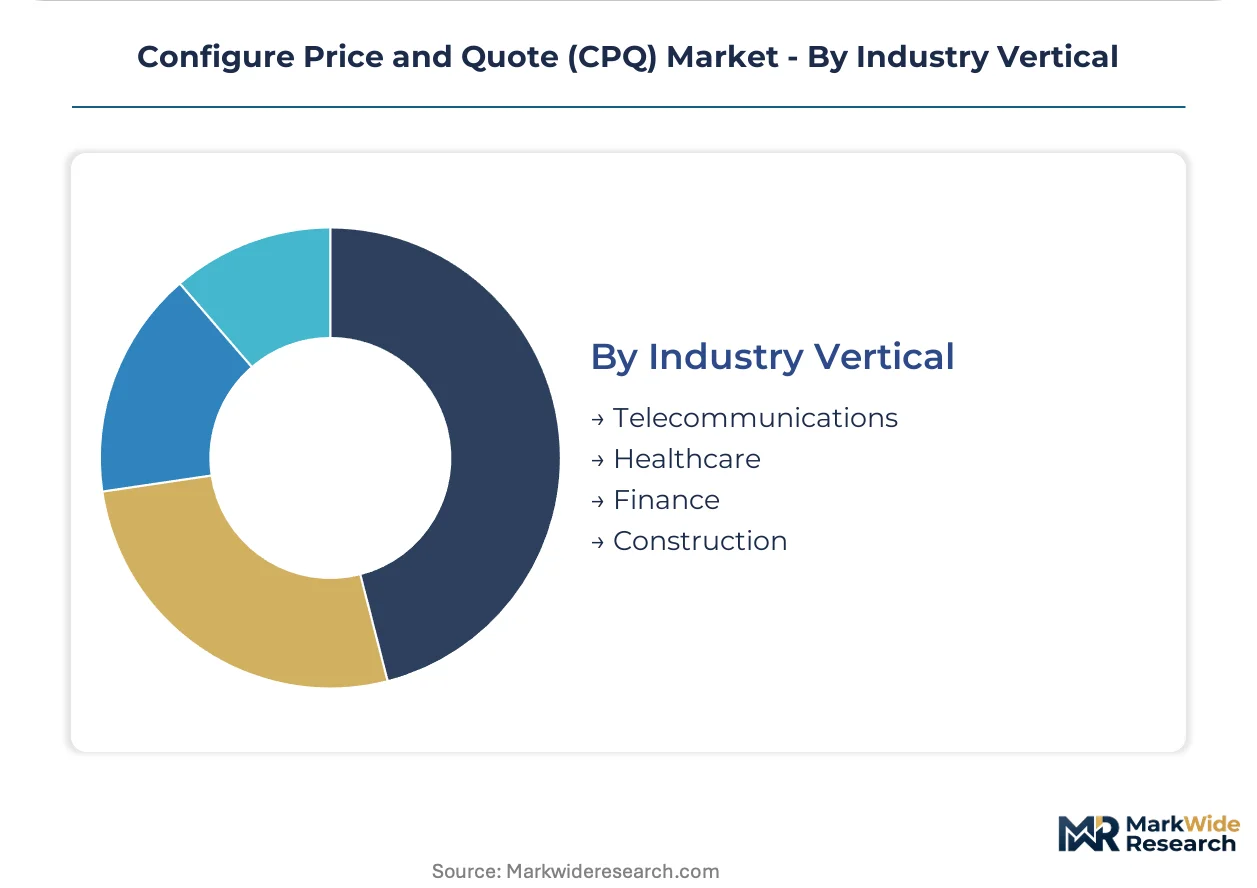
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Solution Type: Stand-Alone, Integrated, Mobile, Customizable End User: Manufacturers, Distributors, Service Providers, Retailers Industry Vertical: Telecommunications, Healthcare, Finance, Construction |
| Companies Covered | Salesforce, Inc., Oracle Corporation, SAP SE, PROS Holdings, Inc., Conga, Inc., Tacton Systems, Revalize, Pricefx, Epicor Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Configure Price and Quote (CPQ) Market Trends and Innovations
CPQ architectures are converging with adjacent enterprise systems while regulatory pressure reshapes vendor development priorities and buyer procurement criteria across industrial software categories.
Constraint-based configuration engines are miniaturizing into embeddable microservices that industrial OEMs deploy within proprietary customer portals. Medical device manufacturers in Germany and Japan are adopting these lightweight modules to power direct-to-physician ordering platforms. The technology is compressing deployment timelines from multi-quarter implementations to weeks-long integrations.
REACH and RoHS compliance documentation requirements are forcing CPQ vendors to embed substance restriction checks directly into product configuration workflows. Industrial equipment manufacturers must now generate automated compliance certificates alongside price quotes for EU-bound shipments. The machinery sector bears the heaviest adaptation burden as material traceability rules tighten.
Buyer committees in capital equipment procurement are consolidating vendor evaluation authority, displacing decentralized sales-led software selection. Large industrial conglomerates in the United States now mandate enterprise architecture review for all CPQ investments, extending sales cycles but favoring integrated suite providers over standalone specialists. This concentration is most visible in aerospace and defense supply chains where procurement centralization has accelerated post-pandemic.
Configure Price and Quote (CPQ) Market Segmentation
CPQ segmentation reveals how deployment architecture, integration depth, and vertical specialization determine vendor competitive positioning. Regulatory mandates and buyer procurement centralization are compressing viable segment combinations while elevating compliance requirements across all categories.
Deployment:
EU AI Act algorithmic transparency requirements and analogous data governance frameworks are bifurcating deployment preferences between compliance-ready cloud architectures and legacy on-premises holdouts in regulated industrial sectors.
- Cloud-Based:API-first architectures enable real-time synchronization with CRM and ERP systems while embedding automated audit trails for regulatory documentation. Demand concentrates among mid-market manufacturers in Germany and Japan where configure-to-order workflows require scalable infrastructure without capital expenditure burdens.
- SaaS:Subscription pricing models align vendor incentives with customer success metrics through usage-based licensing that scales with quote volume. United States industrial machinery manufacturers favor this segment for rapid deployment without dedicated IT infrastructure investments.
- Hybrid:Combines sensitive pricing rule engines on-premises with customer-facing configuration portals in cloud environments.
- On-Premises:Persists in aerospace and defense supply chains where air-gapped networks satisfy security classification requirements.
Established volume favors Cloud-Based; emerging adoption favors SaaS.
Solution Type:
Integration complexity costs are displacing standalone quoting tools as enterprise architecture committees mandate unified data models across sales and operations systems.
- Integrated:Native connectivity with ERP bill-of-materials structures and CRM opportunity pipelines eliminates manual data reconciliation. Medical device manufacturers in Germany prioritize this segment to synchronize engineering change orders with pricing rules across distributed sales organizations.
- Customizable:Open rule engine frameworks accommodate proprietary product logic without vendor dependency for configuration updates. Japanese industrial equipment OEMs deploy these systems for engineer-to-order portfolios with unique constraint requirements.
- Mobile:Field sales teams access configuration capabilities through tablet-optimized interfaces during customer site visits.
- Stand-Alone:Retains niche relevance for distributors with simple product catalogs and minimal ERP integration requirements.
Procurement centralization advantages Integrated; mid-market flexibility requirements favor Customizable.
End User:
Customer type determines implementation scope from self-service portals to multi-layered approval workflows with engineering review gates.
- Manufacturers:Engineer-to-order and configure-to-order production models demand constraint-based engines that validate technical feasibility during quotation. United States, Germany, and Japan industrial machinery sectors drive procurement as product configurability requirements exceed spreadsheet-based quoting capacity.
- Distributors:Multi-vendor catalog aggregation requires CPQ systems that normalize disparate product data structures into unified quoting interfaces.
- Service Providers:Subscription and consumption-based pricing models necessitate recurring revenue calculation modules alongside traditional capital equipment quotes.
- Retailers:High-volume, low-complexity configurations prioritize speed over engineering validation in product customization workflows.
Revenue concentration sits with Manufacturers; fastest expansion trajectory belongs to Service Providers.
Industry Vertical:
Sector-specific compliance documentation and pricing governance requirements shape vertical solution packaging and certification priorities.
- Healthcare:ISO 27001 certification and FDA quality system documentation requirements elevate vendor qualification thresholds. Medical device manufacturers in Germany and Japan deploy CPQ systems that generate automated compliance certificates alongside price quotes for EU-bound shipments under REACH and RoHS frameworks.
- Finance:SEC disclosure frameworks for software procurement investments and audit trail requirements for pricing decisions create demand for transparent algorithmic documentation.
- Telecommunications:Complex service bundling and promotional pricing rules require real-time eligibility validation across subscription tiers.
- Construction:Project-based quoting with milestone payment schedules and material escalation clauses demands flexible contract term management.
Compliance burden advantages Healthcare; pricing complexity favors Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Lyon rail freight corridor underwrites Germany's central role in CPQ software procurement for industrial machinery, while the US-Canada data center interconnects and Japan's Tokyo-Osaka fiber backbone anchor cloud deployment capacity for configure-to-order platforms.
United States
SEC disclosure frameworks for software procurement investments drive enterprise architecture review mandates for CPQ systems. Industrial machinery manufacturers in Michigan and Ohio deploy configure-to-order workflows to accelerate sales cycles against larger rivals. The Midwest manufacturing belt concentrates procurement authority within centralized IT committees.
Germany
EU AI Act algorithmic transparency requirements compel automated pricing engine upgrades across industrial equipment sectors. REACH and RoHS compliance documentation mandates from ECHA force substance restriction checks into configuration workflows. Bavarian medical device manufacturers embed CPQ microservices within direct-to-physician ordering portals.
Japan
METI industrial digitalization programs subsidize cloud migration for mid-market manufacturers adopting engineer-to-order platforms. JIS standards for software interoperability elevate API-first architecture requirements. The Nagoya-Chubu industrial corridor concentrates demand from automotive and precision equipment OEMs.
United Kingdom
GDPR data governance frameworks reshape vendor compliance obligations for pricing algorithm audit trails. London-based financial services firms demand ISO 27001 certification for CPQ investments. The Southeast technology corridor hosts procurement decision-making for multinational industrial conglomerates.
India
PLI scheme incentives for manufacturing automation expand configure-to-order adoption among industrial machinery producers. BIS software quality standards elevate vendor qualification thresholds. Karnataka's Bangalore-Pune technology corridor concentrates implementation partnerships for mid-market exporters.
Configure Price and Quote (CPQ) Market Competitive Landscape
Listed leaders compete with private specialists across integration depth and deployment architecture. The vendor base clusters around three strategic archetypes: CRM-native platforms leveraging existing sales workflows, ERP-anchored suites synchronizing engineering change orders, and standalone specialists offering open rule engine frameworks. Dominant competitive moves include API-first architecture investments and vertical SaaS partnership programs.
Within the enterprise suite tier, Salesforce, Inc., Oracle Corporation, and SAP SE exemplify divergent integration strategies. Salesforce anchors its position through CRM-native embedding that reduces workflow friction for sales teams. Oracle extends cloud infrastructure advantages into subscription billing modules for equipment-as-a-service models. SAP occupies the ERP-synchronized position where engineering change orders propagate directly into pricing rule engines.
| Leading Market Players |
|---|
| Salesforce, Inc. |
| Oracle Corporation |
| SAP SE |
| PROS Holdings, Inc. |
| Conga, Inc. |
| Tacton Systems |
| Revalize |
| Pricefx |
| Epicor Software |
| Others |
Pricing and Supply Chain Analysis
API-first architecture substitution for legacy on-premises rule engines simultaneously reshapes supply geography toward cloud infrastructure hubs and pricing economics toward subscription-based consumption models. This shift concentrates vendor development capacity in United States and German data center corridors while compressing upfront licensing revenue into recurring streams.
Pricing Analysis
Volume-discount tiering structures dominate CPQ procurement with three-tier pricing separating enterprise-grade integrated suites from mid-market SaaS modules and entry-level standalone tools. Price differentiation rests on integration depth and ISO 27001 certification status rather than core configuration capabilities. Cost compression in the standalone tier is intensifying because mid-market buyers consolidate procurement authority under enterprise architecture committees. Distributors with simple product catalogs exhibit highest price sensitivity; aerospace and defense contractors with air-gapped security requirements show least.
Supply Chain Analysis
Frankfurt-Lyon rail freight transit underwrites European CPQ implementation velocity for industrial machinery manufacturers requiring rapid on-site deployment support. Software development capacity concentrates in United States, Germany, and Japan where METI subsidies and EU AI Act compliance investments feed engineering talent pipelines. Raw material dependencies include cloud compute infrastructure, API middleware licenses, and specialized configuration engine IP. Single-source vulnerability runs through hyperscaler cloud platforms that host majority of new deployments. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex ERP synchronization.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CPQ market evolution frames recurring revenue from subscription billing modules and managed rule engine maintenance as the fastest-expanding service layer, outpacing perpetual license transactions as equipment-as-a-service models penetrate industrial automation.
For Market Incumbents: Fortify ERP-synchronized positioning through deeper engineering change order automation while accelerating API-first architecture investments to counter CRM-native competitors embedding quoting logic within existing sales workflows. Prioritize ISO 27001 certification maintenance for healthcare and finance verticals where documentation burdens extend sales cycles but create switching costs. For New Entrants and Emerging Players: Differentiate on headless CPQ microservices that compress deployment timelines from quarters to weeks for mid-market manufacturers in Germany and Japan. Target medical device direct-to-physician ordering platforms as the most penetrable segment, leveraging vertical SaaS partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward API-first specialists with proven constraint-based engine miniaturization and established channel partnerships with industry-specific software vendors. Long-term viability hinges on generative AI integration capabilities that automate natural language proposal generation. Watch for inflection when mid-market manufacturers in United States industrial machinery sectors accelerate replacement of spreadsheet-based quoting at scale.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Investment | Enables real-time ERP synchronization for configure-to-order workflows in German medical device manufacturing. |
| Generative AI Module Development | Automates technical specification drafting for engineer-to-order portfolios in Japanese precision equipment. |
| Vertical SaaS Partnership Program | Opens channel access to niche manufacturing segments through embedded headless CPQ microservices. |
| ISO 27001 Certification Expansion | Creates market access threshold for finance and healthcare procurement committees in London and New York. |
| Subscription Billing Module Launch | Captures equipment-as-a-service pricing calculations for industrial automation recurring revenue models. |
Research Methodology
Initial hypotheses were tested against primary input from CPQ implementation specialists, enterprise sales operations directors, and ERP integration architects and refined through secondary validation against SEC software procurement disclosures, EU AI Act regulatory documentation, and METI industrial digitalization program reports. Bottom-up triangulation across vendor deployment records and top-down reconciliation against enterprise software spending patterns anchored volume estimates.
Variance-decomposition framing separated growth contributions by deployment architecture, solution type, and end-user category across the projection horizon. Segmentation dimensions modeled include cloud versus on-premises infrastructure, integrated versus standalone solution packaging, and manufacturer versus service provider customer archetypes. CAGRs derived from logistic adoption curves fitted to mid-market penetration patterns in United States, Germany, and Japan industrial machinery sectors, with algorithmic transparency compliance deadlines and configure-to-order workflow maturity as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or accelerated cloud migration subsidy programs would require recalibration. Forecasts reflect documented assumptions about mid-market procurement centralization trajectories and generative AI liability frameworks. Practitioners should keep alternative scenarios live as REACH substance restriction documentation requirements and SEC software investment disclosure frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Scanning and Migration Software Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Structured Data Management Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Orchestration Tools Market
Software & Services
Global Video Streaming Software Market
Software & Services
PCB Layout Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Train Reservation Software Market
Software & Services
Business Productivity Software Market
Software & Services
Global Document Management Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Compositing Software Market
Software & Services
United States IT Services Market