
 Global Janitorial Software Market | 2026-2036
Global Janitorial Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Janitorial Software Market Outlook
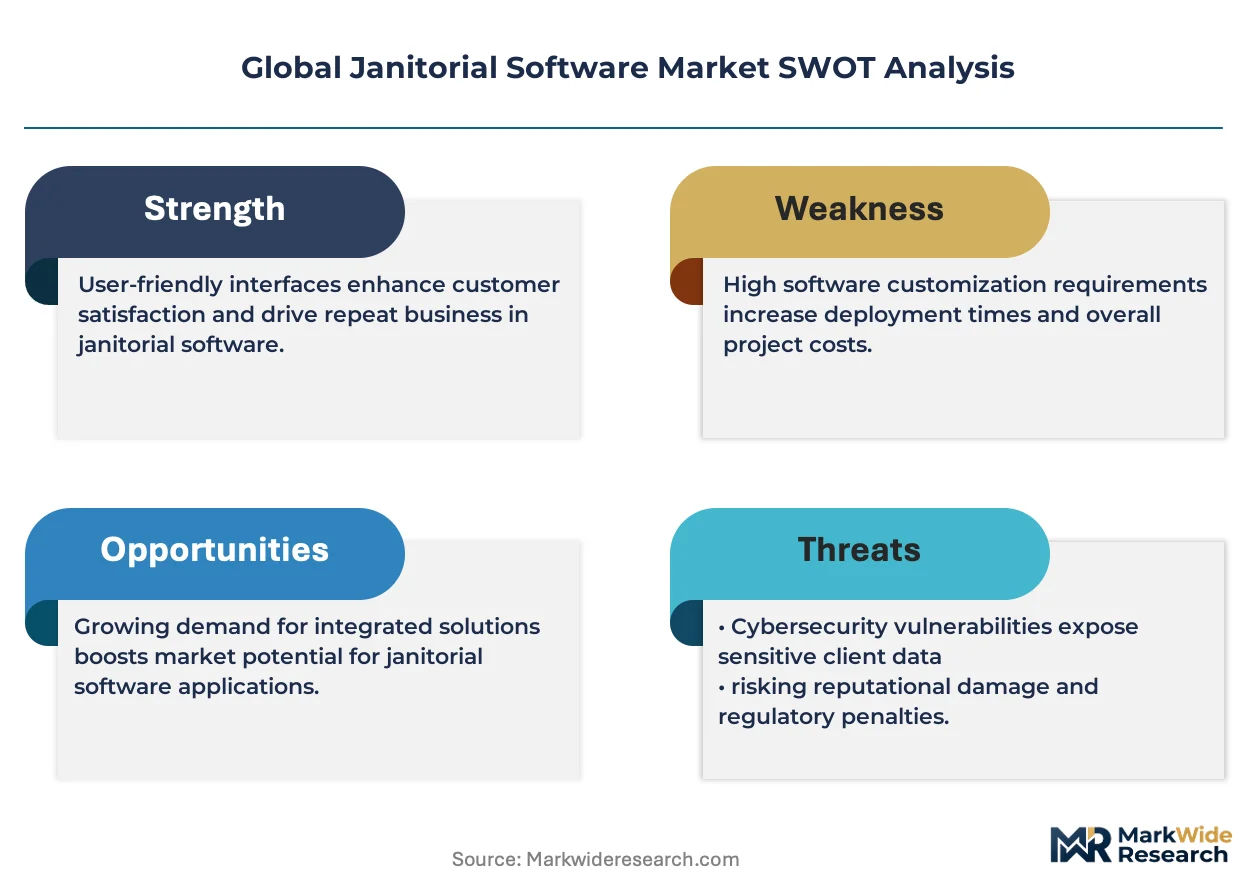
ISO 41001 facility management certification is rotating vendor eligibility across enterprise accounts, disqualifying providers lacking integrated compliance modules. ServiceTitan leverages its contractor software heritage to anchor positions in multi-location cleaning contracts. Swept Technologies specializes in mobile-first workforce tracking for mid-sized janitorial fleets. CleanTelligent Software competes through purpose-built quality inspection tools that map directly to accreditation audit trails.
Janitorial software denotes digital platforms that coordinate workforce scheduling, supply replenishment, and service verification for commercial cleaning operations, typically incorporating GPS check-ins, photo-based proof-of-completion, and consumables par-level monitoring to ensure contract compliance. Cloud-based deployment leads segment uptake as distributed workforces require real-time synchronization across multiple sites, while on-premises solutions retain footholds in healthcare and government facilities with stringent data residency requirements. Subscription-based service models concentrate recurring revenue pools, though pay-per-usage structures gain traction among seasonal or event-driven cleaning operators seeking variable cost alignment.
FDA sanitation requirements for healthcare facilities and OSHA workplace safety recordkeeping mandates shape product feature roadmaps, particularly around incident documentation and chemical handling logs. The EU AI Act and GDPR constrain automated workforce monitoring algorithms deployed across European cleaning contracts. Stakeholders must evaluate how emerging building IoT integrations and predictive maintenance overlays will redefine software value propositions beyond task management into asset lifecycle optimization.
Market Dynamics
Facility management ISO 41001 certification is rotating vendor eligibility across enterprise accounts, forcing software providers to embed integrated compliance modules or face disqualification from multi-location cleaning contracts.
Growth Catalysts
- EU Green Deal building energy mandates:Procurement criteria across European commercial real estate now require software platforms to document carbon footprint reduction in cleaning operations, accelerating platform upgrades.
- Healthcare FDA sanitation protocols:Hospital systems demand digital chemical handling logs and incident documentation features that automate compliance with FDA sanitation requirements for medical facilities.
- Mobile workforce GPS synchronization:Distributed janitorial fleets require real-time check-in capabilities across multiple sites, pulling cloud-based deployment ahead of on-premises alternatives.
Market Restraints
- Data residency compliance costs:Healthcare and government facilities in Germany, France, and Australia require on-premises solutions that carry 40-60% higher total cost of ownership versus cloud alternatives.
- GDPR algorithmic constraints:The EU AI Act and GDPR limit automated workforce monitoring algorithms, constraining feature development for European cleaning contracts.
- Legacy system integration friction:Building management system vendors maintain proprietary protocols that block seamless API connections with third-party janitorial platforms.
Strategic Opportunities
- Predictive maintenance overlay convergence:IoT sensor integration with janitorial scheduling software enables asset lifecycle optimization beyond task management, opening subscription revenue streams.
- Seasonal operator pay-per-usage models:Event-driven and seasonal cleaning contractors in Australia seek variable cost alignment through usage-based pricing rather than fixed subscriptions.
- Mid-sized fleet mobile-first penetration:Workforce tracking solutions for 50-200 employee cleaning operations remain underserved relative to enterprise and micro-fleet segments.
Industry Challenges
- ISO 41001 certification timeline compression:Vendors must accelerate compliance module development to meet rotating enterprise procurement windows or lose anchor contract positions.
- Cross-platform workforce data standardization:Cleaning contractors operating hybrid fleets struggle to unify GPS check-in, photo verification, and supply monitoring data across incompatible software stacks.
- OSHA recordkeeping feature complexity:Workplace safety documentation requirements demand specialized incident logging capabilities that stretch engineering resources at smaller software providers.
Report Scope
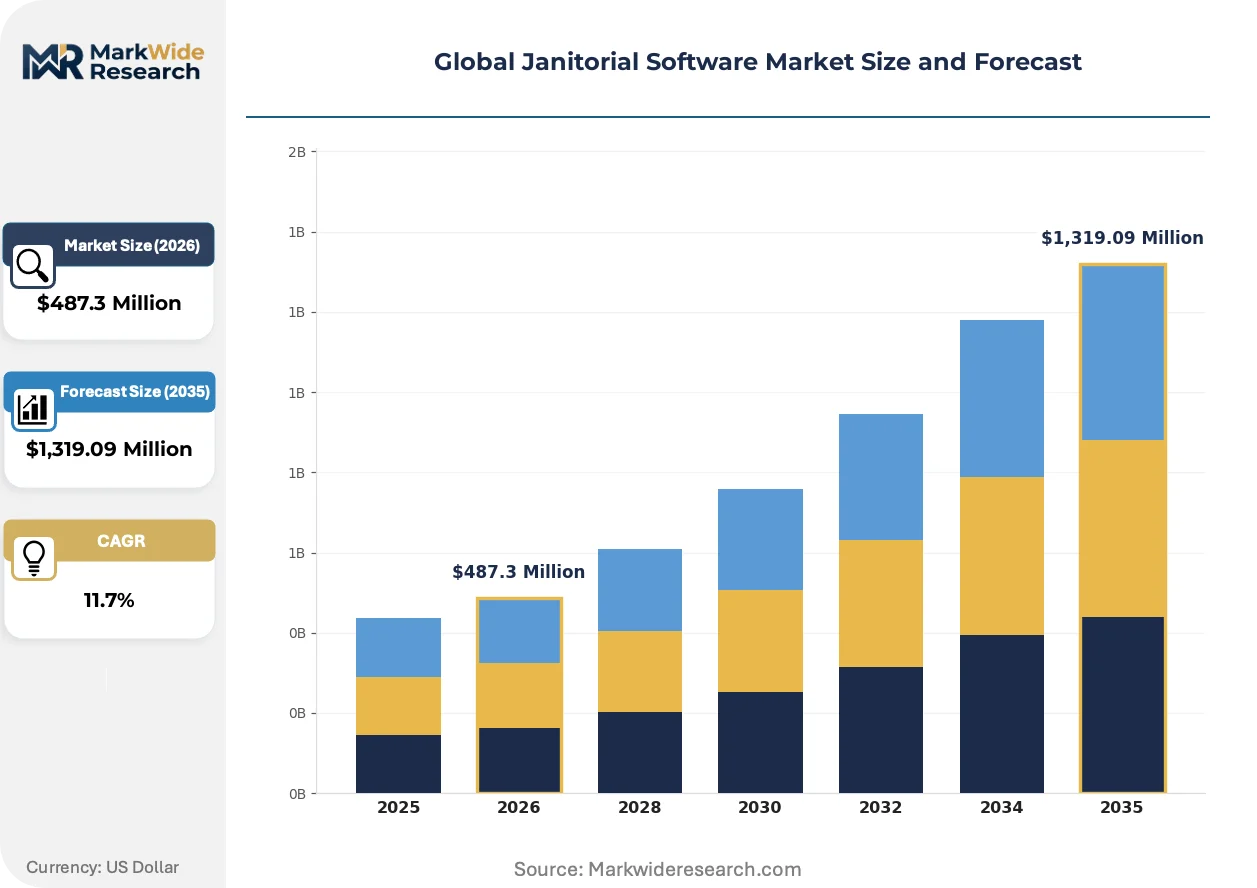
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Janitorial Software Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Inventory Management, Reporting Tools, Mobile Applications End User: Cleaning Companies, Facility Managers, Educational Institutions, Healthcare Facilities Deployment: On-premises, Cloud-based, Hybrid Solutions, Web-based Platforms Service Type: Subscription-based, Pay-per-usage, Licensing, Custom Solutions |
| Companies Covered | CleanTelligent Software, Janitorial Manager, ServiceTitan, Service Fusion, Swept Technologies, Smart Service, Service Autopilot, Jobber, Housecall Pro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Janitorial Software Market Strategic Shifts
Digital proof-of-completion systems are compressing the verification layer between cleaning execution and client billing, eliminating invoice disputes while embedding quality metrics directly into payment workflows.
Photo-based service verification with timestamp and geolocation metadata is supplanting paper sign-off sheets and manual supervisor inspections. Multi-location property managers in the United States and Germany are mandating image documentation for 90% of contracted tasks. This technology is compressing payment cycles from 45 days to 7 days while building defensible audit trails for accreditation reviews.
The EU AI Act algorithmic transparency requirements are forcing vendors to document automated scheduling decision logic. European cleaning contractors must now explain workforce allocation algorithms to regulators and union representatives. Mid-sized fleet operators in France and the Netherlands are responding by hybridizing automated recommendations with manual override capabilities.
Subscription fatigue among seasonal operators is fragmenting pricing models across the industry. Fixed monthly fees now compete with task-credit systems and per-site licensing in Australia and the United States. Smaller contractors in Texas and Florida are piloting revenue-share arrangements where software fees scale with contract values rather than user counts.
Global Janitorial Software Market Segmentation
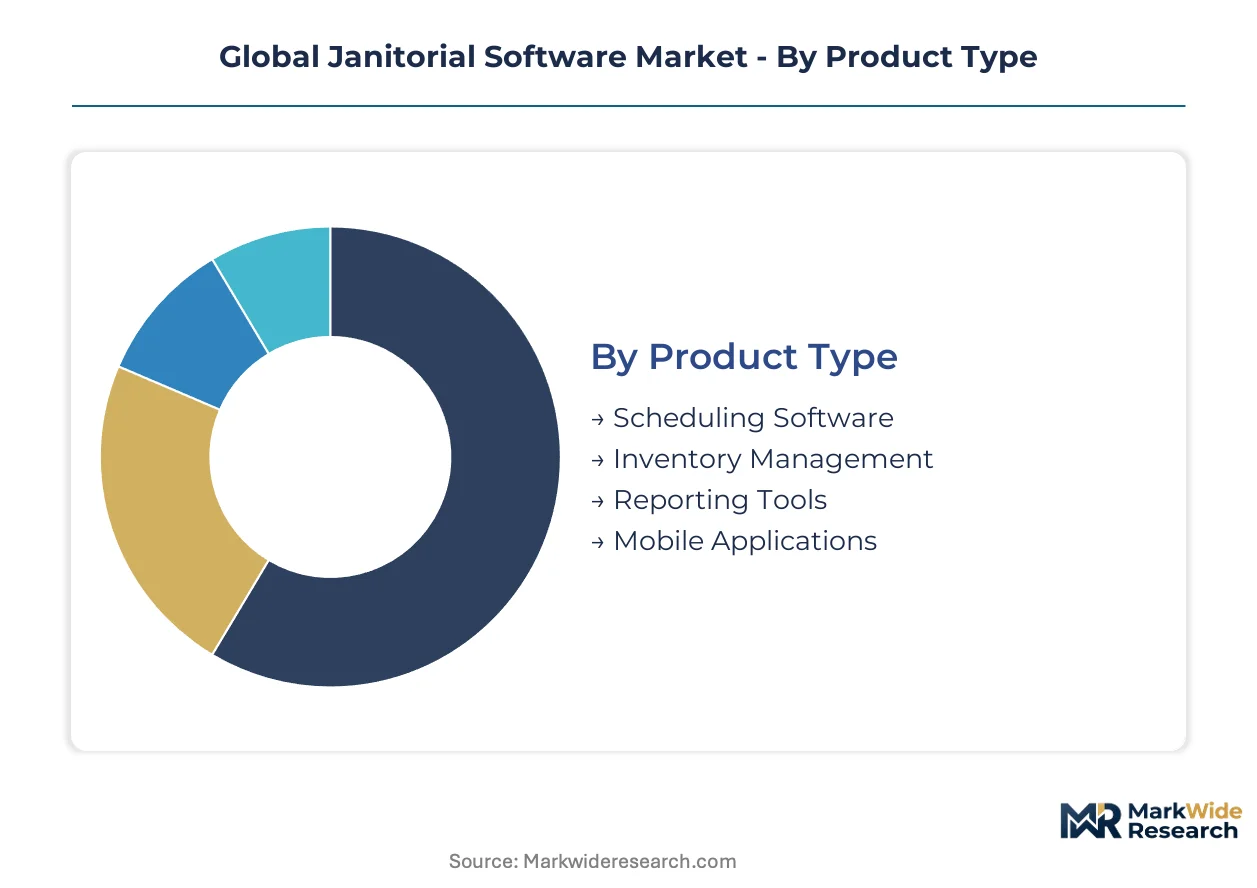
Janitorial software vendors face divergent substitution pressures across product architectures, with standalone mobile applications threatening legacy scheduling platforms while integrated suites consolidate adjacent functionality. Understanding segment boundaries clarifies where modular point solutions cede ground to unified platforms.
Product Type:
Scheduling software confronts the most acute substitution threat as workforce management platforms from adjacent categories absorb core functionality into broader facility management suites.
- Scheduling Software:Core workforce coordination engines manage shift allocation, route optimization, and real-time dispatcher interfaces across distributed cleaning crews. Demand concentrates among multi-location commercial cleaning contractors in the United States and Germany seeking to compress overtime labor costs while maintaining SLA compliance.
- Inventory Management:Par-level monitoring systems track consumables depletion across supply closets and automatically trigger replenishment orders when chemical or paper stock hits reorder thresholds. Hospital systems in Australia prioritize these modules to prevent sanitation supply outages that trigger Joint Commission audit failures.
- Reporting Tools:Dashboard and analytics suites aggregate operational metrics for contract performance reviews.
- Mobile Applications:Native smartphone interfaces enable field-based photo verification and GPS check-ins.
Scheduling software anchors the volume base while mobile applications gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise-grade deployments from budget-constrained implementations, with healthcare and education verticals occupying opposite ends of the pricing spectrum.
- Cleaning Companies:Dedicated janitorial contractors operating commercial, industrial, and residential cleaning fleets represent the primary demand pool, requiring end-to-end platforms spanning dispatch through billing. Mid-sized operators in Texas and Florida are migrating fastest from paper-based workflows to cloud-based alternatives.
- Facility Managers:Corporate and property management in-house teams seek software that integrates with existing building management systems and CAFM platforms. German facility managers under EU Green Deal mandates prioritize carbon footprint documentation features.
- Educational Institutions:School districts and university physical plant departments operate on constrained capital budgets favoring modular, low-cost implementations.
- Healthcare Facilities:Hospital environmental services departments face FDA sanitation protocol requirements that elevate software selection criteria toward specialized compliance modules.
Cleaning companies generate the highest absolute transaction volume while facility managers deliver the most favorable margin profiles.
Deployment:
Application context determines architecture selection, with data residency requirements in regulated verticals preserving on-premises relevance despite cloud momentum.
- On-premises:Self-hosted installations maintain data within facility-controlled servers, mandatory for German healthcare providers under national data protection frameworks and Australian government contracts with sovereignty stipulations. Total cost of ownership runs substantially above cloud alternatives due to hardware maintenance and dedicated IT staffing.
- Cloud-based:Multi-tenant SaaS platforms deliver real-time synchronization across distributed workforces without capital infrastructure investment. United States commercial real estate portfolios and Australian retail cleaning chains favor this model for rapid site onboarding.
- Hybrid Solutions:Architectures split sensitive data on-premises while routing non-critical operations through cloud interfaces.
- Web-based Platforms:Browser-accessible systems eliminate native app installation requirements for contractor workforces.
Cloud-based deployment captures the majority of new implementations while hybrid solutions expand most quickly among privacy-sensitive verticals.
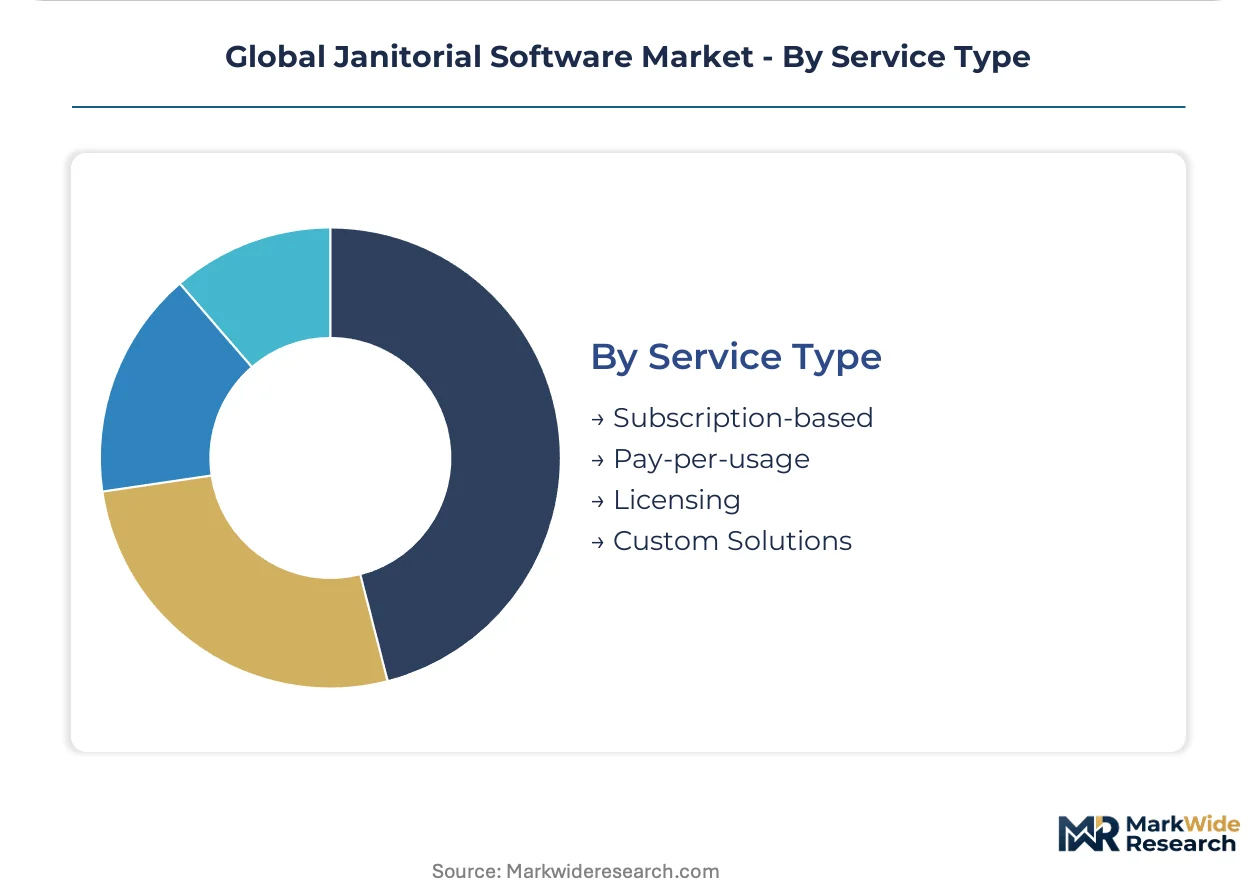
Service Type:
Customer type and contract volatility shape pricing model preferences, with seasonal operators rejecting fixed subscriptions in favor of variable cost structures.
- Subscription-based:Recurring monthly or annual fees per user or site provide predictable revenue streams for software vendors and simplify budgeting for stable cleaning operations. Enterprise multi-location contracts in the United States and Germany predominantly utilize this structure.
- Pay-per-usage:Variable pricing tied to completed work orders, inspected sites, or active scheduling hours aligns costs with revenue for event-driven and seasonal operators. Australian post-construction cleaning contractors and Florida hurricane-response fleets favor this model.
- Licensing:Perpetual software licenses with maintenance agreements persist among healthcare facilities with long capital depreciation cycles.
- Custom Solutions:Bespoke development engagements address unique integration requirements or specialized compliance workflows.
Subscription-based service dominates recurring revenue pools while pay-per-usage models climb the fastest among non-traditional cleaning segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal building energy performance standards and national data sovereignty frameworks are fragmenting procurement criteria across major janitorial software markets, compelling vendors to architect region-specific compliance modules.
United States
Commercial real estate portfolios in Texas and Florida are modernizing legacy maintenance workflows at the fastest clip. OSHA workplace safety recordkeeping mandates shape product roadmaps around incident documentation features. Dallas-Fort Worth cleaning contractors anchor cloud migration momentum among mid-sized fleets.
Germany
Facility managers under EU Green Deal procurement criteria prioritize carbon footprint documentation in cleaning operations software. National data protection frameworks preserve on-premises relevance for healthcare providers despite cloud momentum. The Rhine-Ruhr metropolitan corridor concentrates multi-location contract demand.
Australia
Post-construction cleaning contractors and retail cleaning chains favor variable cost alignment through pay-per-usage models rather than fixed subscriptions. TGA-equivalent healthcare sanitation protocols elevate software selection criteria for hospital environmental services departments. Sydney and Melbourne anchor distributed workforce GPS synchronization demand.
France
Mid-sized fleet operators in Paris and the Netherlands-adjacent regions hybridize automated scheduling recommendations with manual override capabilities under EU AI Act algorithmic transparency requirements. CNIL oversight constrains automated workforce monitoring feature deployment. Île-de-France property managers mandate photo-based service verification for contracted tasks.
United Kingdom
Corporate in-house facility management teams seek CAFM platform integration for building management system connectivity. London commercial real estate portfolios compress payment cycles through digital proof-of-completion systems. The Southeast England corridor concentrates enterprise multi-location cleaning contract volume.
Global Janitorial Software Market Competitive Environment
Player mix skews toward specialized SaaS vendors with contractor software heritage alongside purpose-built quality inspection tool developers. Market structure exhibits moderate concentration around integrated facility management platforms and mobile-first workforce tracking specialists. Two strategic archetypes dominate: vertically integrated suite providers absorbing adjacent functionality and modular point solution vendors defending niche compliance workflows. Competitive moves concentrate on API integration partnerships with building IoT sensor networks and geographic expansion into underpenetrated mid-sized fleet segments.
Within the contractor software heritage tier, ServiceTitan anchors positions among multi-location cleaning contracts through field service platform adjacencies. Swept Technologies exemplifies the mobile-first workforce tracking archetype for mid-sized janitorial fleets. CleanTelligent Software occupies the purpose-built quality inspection niche, mapping tools directly to accreditation audit trails. These three companies represent the dominant strategic vectors shaping competitive positioning.
| Leading Market Players |
|---|
| CleanTelligent Software |
| Janitorial Manager |
| ServiceTitan |
| Service Fusion |
| Swept Technologies |
| Smart Service |
| Service Autopilot |
| Jobber |
| Housecall Pro |
| Others |
Value Chain & Pricing Dynamics
Sixty-day implementation cycles for cloud-based janitorial platforms concentrate vendor pricing power in the United States and Germany, where rapid site onboarding demands compress procurement negotiations and anchor subscription premiums against slower-moving on-premises alternatives in regulated healthcare verticals.
Pricing Analysis
Certification level creates the primary spread across deployment tiers, with ISO 41001-compliant modules commanding subscription premiums against baseline scheduling tools. Three-tier pricing structure across premium, standard, and economy levels aligns with feature depth: enterprise suites with predictive maintenance overlays, mid-market workforce tracking platforms, and stripped-down mobile check-in applications. Pricing pressure stems from pay-per-usage alternatives gaining traction among Australian seasonal operators seeking variable cost alignment. Small contractors in Texas and Florida exhibit highest price sensitivity, while German facility managers under EU Green Deal mandates prioritize carbon documentation features over cost minimization.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for North American deployments, while Germany and Australia concentrate data center capacity for regional residency compliance. Software development draws from Indian engineering hubs for mobile application builds and Eastern European centers for compliance module architecture. Supply chain risk centers on single-source vulnerability in building management system API protocols that block seamless third-party integration. Distribution runs through direct sales teams for enterprise multi-location contracts and channel partners for mid-sized fleet penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across compliance requirements, deployment architectures, and pricing models creates multiple entry points for specialized vendors as ISO 41001 certification rotates enterprise eligibility and seasonal operators reject fixed subscriptions.
For Market Incumbents: Fortify anchor contract positions by accelerating ISO 41001 compliance module development ahead of rotating procurement windows. Deepen API integration partnerships with building IoT sensor networks to preempt predictive maintenance overlay competition from adjacent facility management platforms.
For New Entrants and Emerging Players: Differentiate on mobile-first workforce tracking for 50-200 employee cleaning operations in Texas and Florida, the most penetrable segment between underserved mid-sized fleets and saturated enterprise accounts. Target pay-per-usage model adoption among Australian post-construction and event-driven cleaning contractors seeking variable cost structures.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical SaaS consolidation play because compliance module specialization and IoT integration capabilities will separate acquisition targets from commodity scheduling providers. Watch for inflection in building IoT sensor deployment rates as the signal indicating predictive maintenance overlay revenue acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Compliance Module Development | Rotating certification requirements disqualify non-compliant vendors from enterprise procurement cycles. |
| Building IoT Sensor Integration | Predictive maintenance overlays expand software value propositions into asset lifecycle optimization. |
| Pay-per-Usage Pricing Launch | Variable cost alignment captures Australian seasonal operators and Florida hurricane-response fleets. |
| Mobile-First Workforce Tracking | Native smartphone interfaces with GPS check-ins address underserved 50-200 employee fleet segments. |
| API Partnership with CAFM Platforms | Seamless building management system connectivity satisfies German facility manager integration demands. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory databases through structured interviews with janitorial software product managers, facility management procurement directors, commercial cleaning contractor operations heads, and building IoT integration specialists. Bottom-up triangulation aggregates deployment model adoption rates and pricing structure preferences across customer segments, while top-down validation cross-references against facility management software market sizing frameworks.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical compliance intensity, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base growth rates and average revenue per account expansion trajectories, with specific inputs including ISO 41001 certification penetration curves and cloud infrastructure cost decline slopes.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated OSHA digitization mandates would require recalibration. Forecasts assume continued fragmentation in data residency requirements and stable building management system API accessibility. Recalibration cycles align with material shifts in certification rotation schedules and IoT sensor deployment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Computer Backup Software Market
Software & Services
Global Cinema Software Market
Software & Services
India Software Services Export Market
Software & Services
Deck Design Software Market
Software & Services
E-Clinical Solution Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Online Lottery Software Market
Software & Services
Webcasting Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Artwork Management Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Business Analytics Software Market