
 Rupture Discs Market | 2026-2036
Rupture Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Rupture Discs Market Analytics
Capital-intensity divergence between integrated manufacturers and component assemblers is bifurcating competitive returns in the rupture discs landscape. BS&B Safety Systems L.L.C leverages captive metallurgy capabilities to sustain margin capture across high-cycle applications. Fike Corporation anchors North American demand through extensive channel control in hazardous process industries. Mersen Group specializes in graphite-composite architectures that differentiate its offering in corrosive chemical environments.
A rupture disc is a non-reclosing pressure relief device engineered from calibrated metal, polymer, or composite membranes that fracture at predetermined differential pressures to protect vessels and piping from catastrophic failure. Metallic rupture discs dominate installed base volumes due to proven performance in extreme temperature cycling, though polymer rupture discs are capturing faster growth in pharmaceutical cleanroom applications where metallic ion contamination poses batch rejection risks. Composite rupture discs command premium positioning by combining corrosion-resistant facings with structural substrates, concentrating margin pools in chemical processing end uses where fluoropolymer linings extend service intervals.
The ASME Boiler and Pressure Vessel Code Section VIII shapes product certification requirements across North American jurisdictions, while CE marking under the EU Pressure Equipment Directive governs market access throughout European member states. OSHA Process Safety Management standards mandate documented overprotection strategies that institutionalize replacement demand rather than deferring maintenance. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as high-pressure electrolyzer and fuel cell applications introduce novel burst-pressure specifications outside traditional petrochemical experience bases.
Market Dynamics
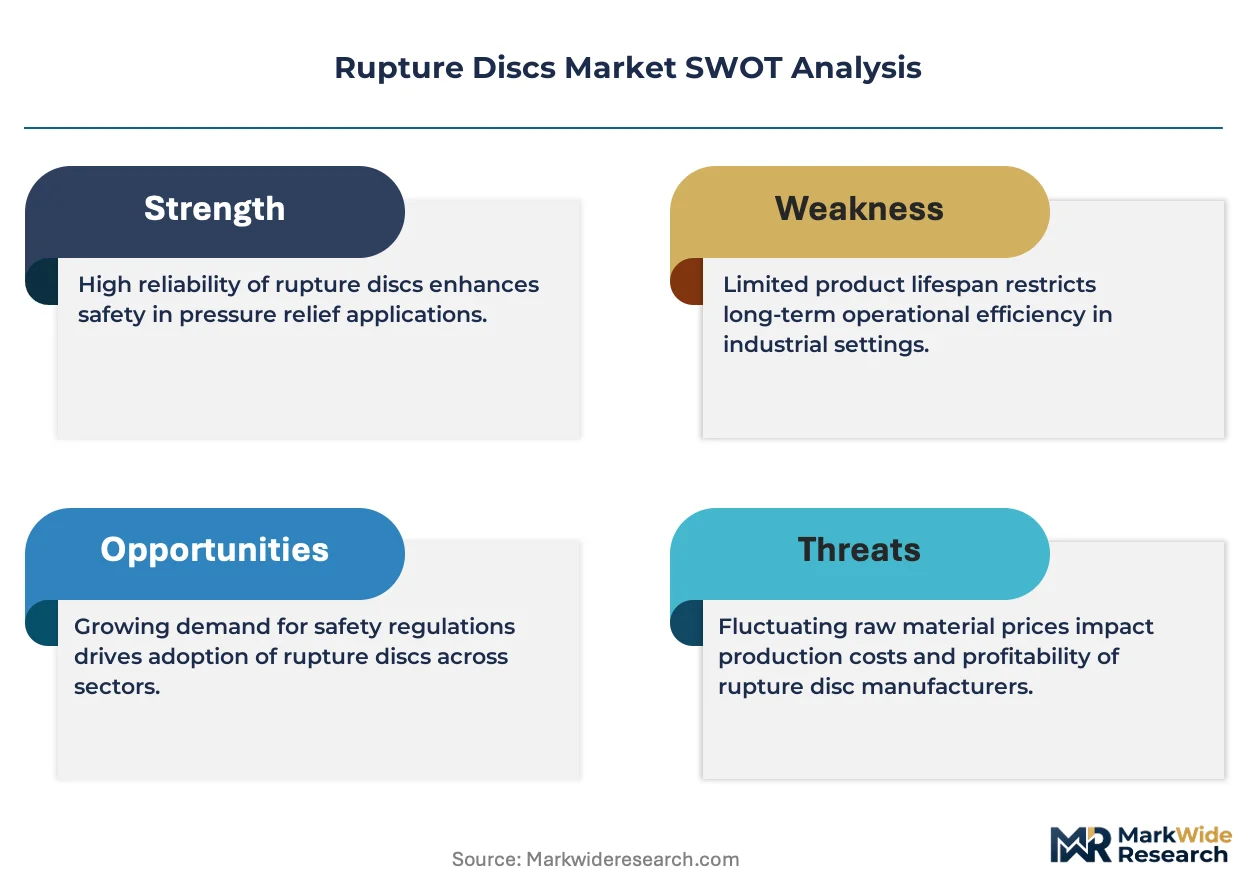
The rupture discs market is being reshaped by tightening process safety mandates that institutionalize replacement cycles rather than permitting deferred maintenance, compressing effective equipment lifespans across chemical processing and energy infrastructure.
Growth Catalysts
- OSHA Process Safety Management:Documented overprotection strategies in US hazardous process industries mandate scheduled replacement of pressure relief devices, creating predictable demand pull.
- Graphite-composite architectures:Corrosion-resistant facings combined with structural substrates extend service intervals in fluoropolymer-lined chemical vessels, expanding addressable applications.
- Hydrogen economy infrastructure codes:High-pressure electrolyzer and fuel cell applications introduce novel burst-pressure specifications outside traditional petrochemical baselines.
Market Restraints
- Specialized alloy input volatility:Nickel-based superalloys and corrosion-resistant metals face price instability from concentrated mining geographies, pressuring manufacturer margins.
- ASME Section VIII certification friction:North American jurisdictions impose extended testing timelines for novel composite designs, delaying commercialization of next-generation membranes.
- Spring-loaded relief valve substitution:Reclosing pressure relief devices capture share in applications permitting periodic reseating, constraining rupture disc volume in lower-criticality installations.
Strategic Opportunities
- Pharmaceutical cleanroom expansion:Polymer rupture discs eliminate metallic ion contamination risks in batch-sensitive biologics manufacturing, opening premium positioning.
- EU Pressure Equipment Directive alignment:CE marking harmonization across European member states reduces certification redundancy for multi-jurisdictional suppliers.
- Digital monitoring convergence:Integration of burst detection sensors with rupture disc assemblies enables predictive maintenance contracts and recurring revenue streams.
Industry Challenges
- Metallurgical engineering talent scarcity:Specialized expertise in membrane calibration and exotic alloy forming functions constrains production scaling for integrated manufacturers.
- Legacy system integration complexity:Retrofitting advanced composite discs into existing piping configurations requires custom flange adapters, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rupture Discs Market |
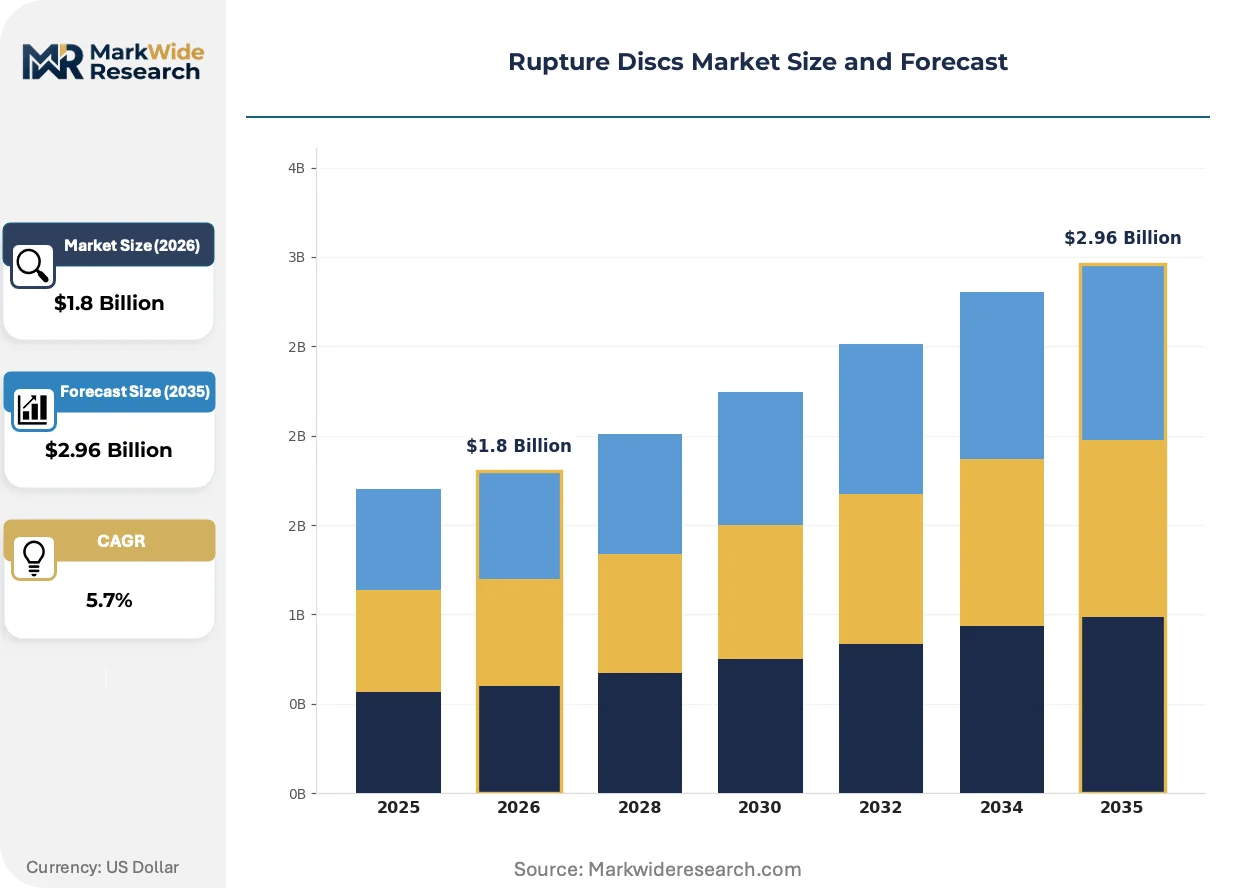
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Rupture Discs, Polymer Rupture Discs, Composite Rupture Discs, Standard Rupture Discs Installation Type: Inline Installation, Side Installation, Flanged Installation, Type A Installation End User: Oil & Gas, Chemical Processing, Pharmaceuticals, Food & Beverage Size: Small, Medium, Large, Extra Large |
| Companies Covered | Emerson Electric Co., BS&B Safety Systems L.L.C, Fike Corporation, Continental Disc Corp., Parker Hannifin Corp, Graco Inc., Halma Plc, Leser GmbH & Co. KG, Mersen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rupture Discs Market Evolving Landscape
Membrane engineering and regulatory harmonization are converging to redefine competitive advantage, with material science advances enabling service interval extension while certification digitization compresses market access timelines.
Reverse-acting scored disc technology is fragmenting traditional forward-acting designs by enabling tighter burst tolerance windows and eliminating fragmentation upon activation. Pharmaceutical manufacturers in Switzerland and Germany are adopting these architectures for sterile process containment. The technology is fragmenting procurement patterns as buyers specify performance-based specifications rather than legacy geometry categories.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of fluoropolymer linings in composite disc facings. Chemical processors in the Netherlands and Belgium face accelerated replacement schedules for existing installed bases. Manufacturers are responding with ceramic-polymer hybrid coatings that maintain chemical inertness while satisfying substance registration requirements.
Consolidated procurement by multinational chemical conglomerates is compressing supplier rosters and demanding lifecycle cost documentation. Engineering, procurement, and construction firms in the US Gulf Coast are bundling rupture disc specification into turnkey pressure system contracts. This concentration is most visible in Texas and Louisiana, where integrated petrochemical clusters favor single-source safety system suppliers with captive metallurgy capabilities.
Rupture Discs Market Segmentation
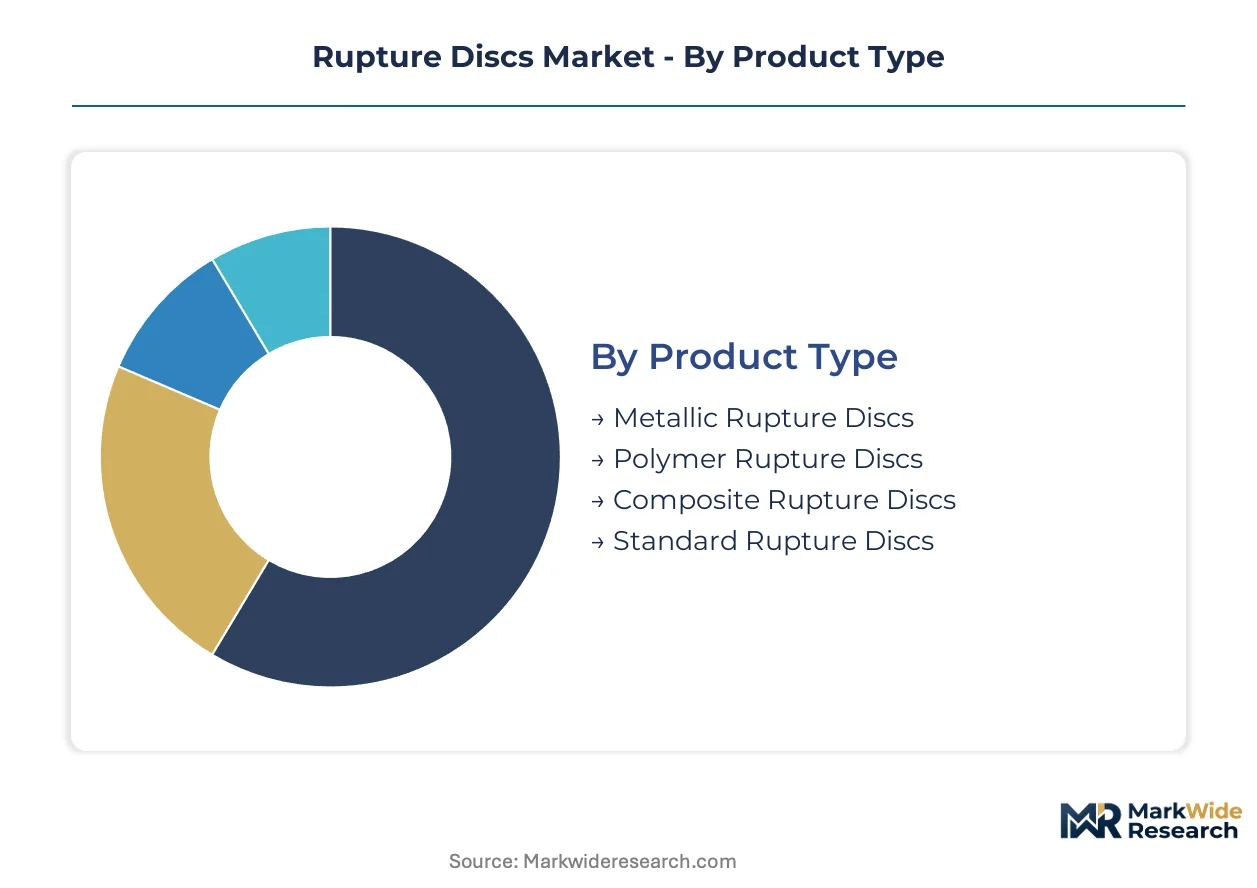
Rupture disc procurement patterns diverge sharply across product architectures and installation configurations. End-use specialization and sizing requirements create distinct margin pools that reward targeted manufacturing capabilities over undifferentiated volume production.
Product Type:
Domestic production concentrates in metallic and composite architectures serving regional chemical clusters, while polymer disc manufacturing exhibits stronger cross-border trade intensity driven by pharmaceutical cleanroom standards.
- Metallic Rupture Discs:Engineered from calibrated nickel alloys and stainless steel membranes that fracture at precise differential pressures across extreme temperature cycling. Demand clusters in German petrochemical corridors and US Gulf Coast refineries where ASME Section VIII certification mandates scheduled replacement cycles.
- Composite Rupture Discs:Layered fluoropolymer facings bonded to structural substrates deliver corrosion resistance in fluorochemical processing. Dutch and Belgian processors are accelerating procurement under REACH substance restriction compliance timelines.
- Polymer Rupture Discs:Thermoplastic membranes eliminate metallic ion contamination in Swiss and German biologics manufacturing.
- Standard Rupture Discs:Conventional forward-acting designs serve general industrial pressure protection with shorter specification cycles.
Metallic rupture discs command the established base. The steepest expansion runs through composite architectures.
Installation Type:
Cost tiering separates engineered flange systems from commodity inline configurations, with premium positioning concentrating in hazardous process environments requiring documented overprotection.
- Inline Installation:Direct piping integration dominates volume procurement across standard chemical processing applications with predictable pressure profiles.
- Flanged Installation:Bolted connection systems enable rapid replacement in high-cycle facilities. German chemical processors specify these architectures to minimize vessel downtime during scheduled maintenance windows.
- Side Installation:Branch connection mounting serves auxiliary relief points in complex piping networks.
- Type A Installation:Specialized holder configurations address legacy vessel retrofits requiring custom adapter geometries.
Flanged systems anchor premium positioning. Inline configurations deliver volume scale.
End User:
Application criticality stratifies procurement — process safety mandates institutionalize replacement in chemical and energy infrastructure, while pharmaceutical demand rewards contamination-free architectures.
- Chemical Processing:Fluoropolymer-lined vessels and corrosive media handling drive specification of extended-service composite discs. OSHA Process Safety Management documentation requirements in US facilities compress effective replacement intervals.
- Pharmaceuticals:Sterile biologics manufacturing in Basel and Munich clusters demands polymer rupture discs that eliminate batch contamination risks from metallic ion leaching.
- Oil & Gas:Hydrocarbon extraction and refining operations specify high-reliability metallic discs for extreme pressure-temperature cycling.
- Food & Beverage:Sanitary process applications require corrosion-resistant relief protection with clean-in-place compatibility.
Chemical processing anchors replacement demand. Pharmaceutical applications are climbing the fastest.
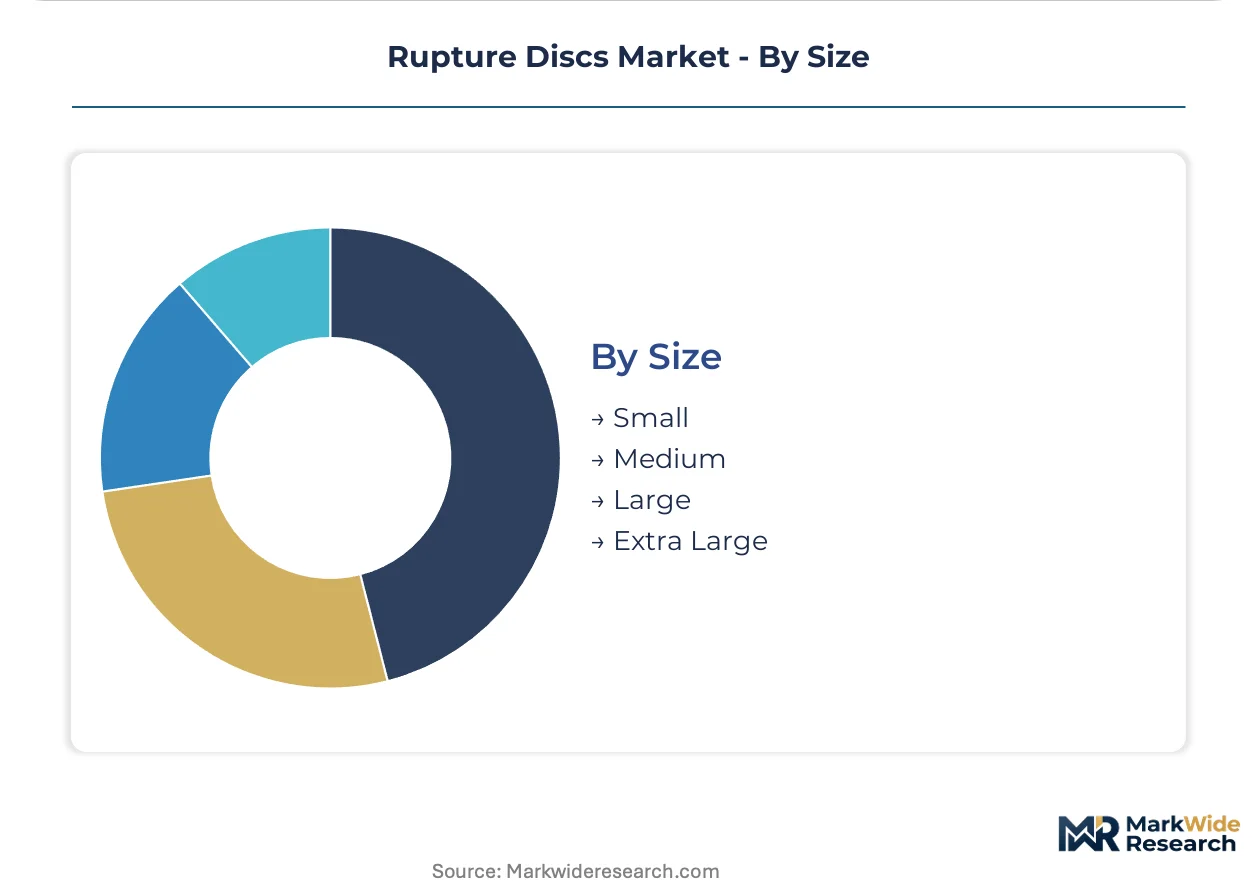
Size:
Volume concentration in medium and large formats reflects mainstream industrial vessel dimensions, while specialized sizing serves modular process skids and legacy infrastructure.
- Medium:Standard vessel dimensions across chemical and pharmaceutical batch processing equipment.
- Large:Refinery reactor and storage tank protection in Rotterdam and Houston petrochemical clusters.
- Small:Laboratory-scale and pilot plant applications with precision burst requirements.
- Extra Large:Specialized pressure vessel protection in heavy industrial and power generation infrastructure.
Medium and large sizes dominate procurement volume. Small formats serve niche precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German chemical corridors exhibit the lowest price elasticity, prioritizing certified replacement cycles over procurement cost, while price-sensitive operators in emerging industrial clusters defer maintenance and source commodity-grade alternatives.
United States
Gulf Coast petrochemical operators drive procurement of ASME-certified metallic rupture discs under OSHA Process Safety Management mandates. The EPA enforces documented overprotection strategies that compress replacement intervals. Houston and Louisiana industrial clusters favor single-source safety system suppliers with captive metallurgy capabilities.
Germany
Dense petrochemical clustering in the Rhine-Ruhr and Ludwigshafen corridors sustains above-average replacement cycles for high-reliability assemblies. The country's national pressure equipment regulator enforces strict CE marking compliance under EU Pressure Equipment Directive alignment. Bavarian pharmaceutical manufacturers in Munich specify polymer rupture discs for sterile biologics production.
China
Expanding chemical processing capacity and hydrogen economy infrastructure development generate novel burst-pressure specifications outside traditional petrochemical baselines. The Ministry of Emergency Management tightens process safety codes for high-pressure electrolyzer applications. Yangtze River Delta chemical processors accelerate procurement of corrosion-resistant composite architectures.
Netherlands
Fluorochemical processors face accelerated replacement schedules as ECHA REACH substance restrictions force reformulation of fluoropolymer linings in composite disc facings. The national chemical industry association coordinates compliance timelines for installed base retrofits. Rotterdam petrochemical clusters drive demand for ceramic-polymer hybrid coatings that maintain chemical inertness.
Switzerland
Basel's pharmaceutical cleanroom expansion rewards polymer rupture discs that eliminate metallic ion contamination risks in batch-sensitive biologics manufacturing. Swissmedic maintains stringent sterile process containment standards that institutionalize premium procurement. Reverse-acting scored disc technology penetrates Swiss facilities seeking tighter burst tolerance windows.
Rupture Discs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive metallurgy capabilities separating margin-capturing manufacturers from component assemblers. The upper tier commands specification influence through ASME Section VIII certification depth and channel control in hazardous process industries. Mid-scale specialists compete on application-specific architectures—graphite-composite, polymer membrane, or exotic alloy forming. Consolidated procurement by multinational chemical conglomerates and bundled EPC contracts represent the dominant competitive moves compressing supplier rosters.
Within the integrated metallurgy tier, BS&B Safety Systems L.L.C and Fike Corporation exemplify North American fabricators with established channel control, while Mersen Group occupies a position representing European specialization in corrosion-resistant composite architectures. These three anchors illustrate how geographic certification bases and material science focus determine competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| BS&B Safety Systems L.L.C |
| Fike Corporation |
| Continental Disc Corp. |
| Parker Hannifin Corp |
| Graco Inc. |
| Halma Plc |
| Leser GmbH & Co. KG |
| Mersen Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German chemical processors and integrated rupture disc manufacturers lock in nickel alloy supply access while providing multi-year price visibility against nickel price volatility on the London Metal Exchange. These arrangements concentrate procurement power among ASME-certified fabricators with captive metallurgy capabilities, compressing margin capture for component assemblers dependent on spot alloy purchases.
Pricing Analysis
Aftermarket service contracts and scheduled replacement programs generate lifetime value exceeding initial hardware sales by substantial multiples. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels separates ASME Section VIII-certified assemblies from CE-marked alternatives and uncertified imports. Cost compression in the economy tier is intensifying because Chinese fabricators are flooding Asian spot markets with nickel-plated steel discs. Pharmaceutical cleanroom operators in Basel and Munich exhibit the lowest price sensitivity, prioritizing polymer membrane purity guarantees over procurement cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for graphite composite substrates sourced from Japanese specialty carbon producers. Manufacturing concentrates in Germany, the United States, and China, with German fabricators dominating high-reliability metallic disc production and Chinese suppliers scaling polymer membrane output. Nickel-based superalloy feedstock draws from concentrated mining geographies in Indonesia and Russia, creating tariff exposure for Western manufacturers. Single-source vulnerability characterizes fluoropolymer facing supply for composite architectures. Distribution runs through engineering-procurement-construction firms bundling rupture disc specification into turnkey pressure system contracts along the US Gulf Coast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital monitoring convergence is transforming rupture disc procurement from transactional component sales to platform-based predictive maintenance ecosystems, with burst detection sensor integration creating recurring revenue streams that mirror software subscription economics.
For Market Incumbents: Secure ASME Section VIII certification depth for next-generation composite membrane designs before EPA enforcement timelines compress replacement windows further. Deepen backward integration into nickel alloy forming to offset input volatility from Indonesian supply concentration. Channel control in Houston and Louisiana petrochemical clusters remains the priority defensive lever against EPC bundling trends. For New Entrants and Emerging Players: Lead with ceramic-polymer hybrid coating formulations targeting Dutch and Belgian fluorochemical processors facing accelerated REACH compliance-driven replacement schedules. Pharmaceutical cleanroom applications in Swiss biologics manufacturing represent the most penetrable white-space segment given contamination-risk premiums. A go-to-market angle through sterile process engineering consultants bypasses incumbent EPC relationships. For Investors and Strategic Acquirers: Captive metallurgy specialists with ASME and CE dual certification offer the strongest acquisition profile for long-term viability across the hydrogen economy infrastructure buildout. Watch hydrogen electrolyzer burst-pressure specification standardization as the inflection indicator for next-generation membrane demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Forming | Captive metallurgy insulates margins against LME price volatility and Indonesian supply risk. |
| Digital Monitoring Platform Development | Burst detection sensor integration enables predictive maintenance contracts with recurring revenue. |
| Ceramic-Polymer Hybrid Coating Launch | REACH-compliant formulations capture Dutch fluorochemical processor replacement demand. |
| ASME Section VIII Certification Expansion | Dual certification depth secures specification influence in OSHA-mandated replacement cycles. |
| Pharmaceutical Cleanroom Partnership | Swissmedic-sterile process containment standards institutionalize premium polymer disc procurement. |
Research Methodology
The analysis maps metallic, composite, and polymer rupture disc sub-sectors, each validated through plant engineers at chemical processing facilities, procurement leads at pharmaceutical manufacturers, aftermarket service heads at safety system distributors, and regulatory compliance officers. Primary interview insights combined with secondary validation from ASME Boiler and Pressure Vessel Code filings, ECHA REACH substance restriction databases, SEC 10-K disclosures by listed safety equipment manufacturers, and EU Pressure Equipment Directive harmonization records. Bottom-up vessel count modeling and top-down industrial safety expenditure analysis provide triangulation consistency checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, installation configuration, end-use industry criticality tier, vessel size format, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates under tightening process safety mandates and hydrogen infrastructure code development trajectories. Industry-specific forecast inputs incorporate OSHA Process Safety Management documentation requirements and EU Pressure Equipment Directive alignment timelines.
The analysis sits within stated boundaries; outcomes outside sustained chemical processing capital expenditure and hydrogen economy infrastructure deployment would require recalibration. Forecasts reflect documented assumptions regarding nickel alloy price stability and REACH substance restriction enforcement intensity. Recalibration cycles align with material shifts in ASME Section VIII certification timelines and hydrogen electrolyzer standardization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
North America Residential Ball Valves Market
Valves
Emergency Shutdown Valves Market
Valves
Vacuum Insulated Pipe Market
Valves
Motorized Valves Market
Valves
Air Vent Heads Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
North America High Voltage Switchgear Market
Valves
Orifice Reducers Market
Valves
Global Plug Valve Market
Valves
Industrial Valves and Actuators Market
Valves
Valve Remote Control System Market
Valves
Steam Trap Valve Market
Valves
India Industrial Valves Market
Valves
Flanges Market
Valves
Choke and Kill Manifold Market