
 Food Allergy Treatment Market | 2026-2036
Food Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Allergy Treatment Market Insights
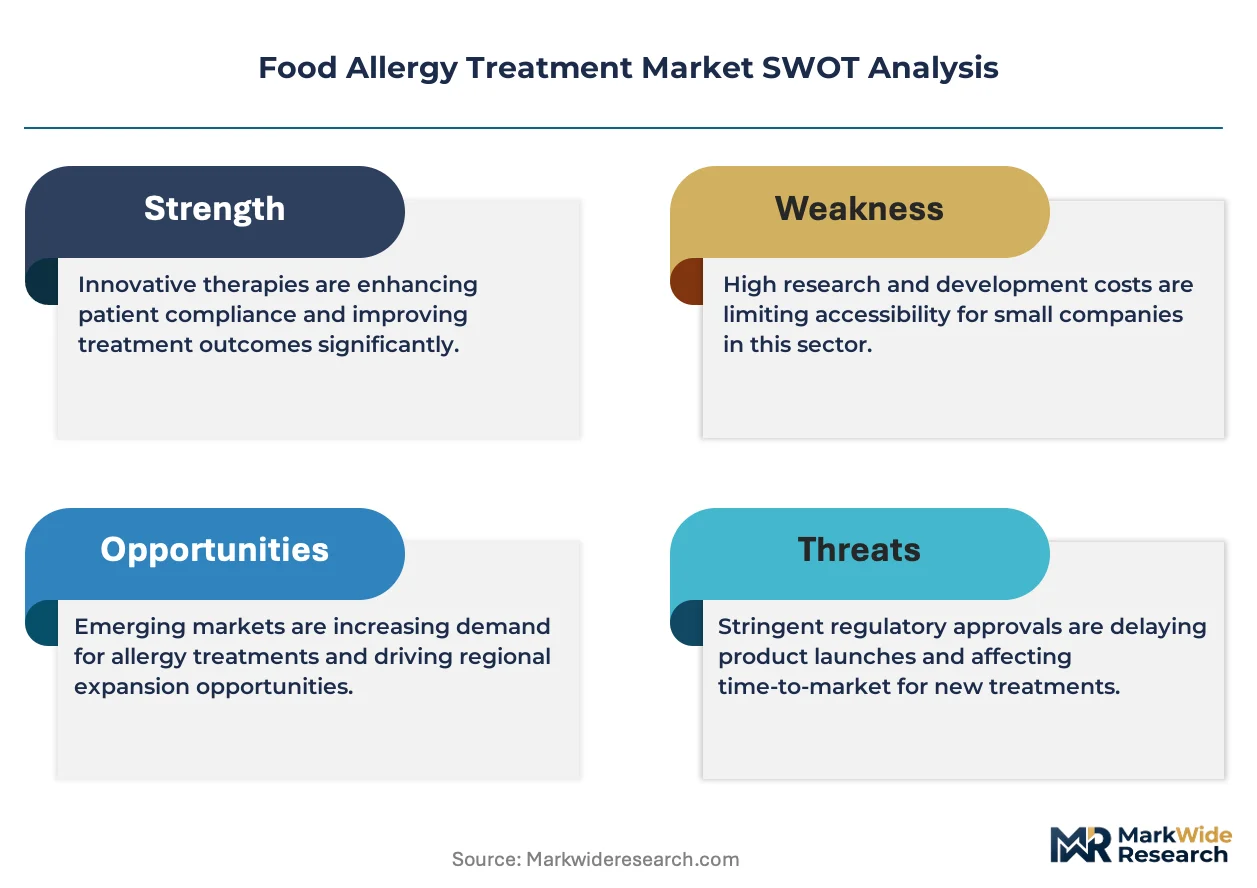
Multi-source biologic sourcing is expanding as developers diversify their CMO networks beyond single-vendor dependencies. DBV Technologies leverages its patch-based delivery platform to differentiate from injectable competitors. Aimmune Therapeutics anchors the peanut allergy segment with its oral immunotherapy approach. Novartis competes through biologic manufacturing scale and established immunology infrastructure.
Food allergy treatment encompasses pharmacologic and immunologic interventions designed to prevent, mitigate, or desensitize hypersensitivity reactions to dietary proteins, with biologic therapies targeting IgE-mediated pathways through monoclonal antibodies that interrupt mast cell activation. The primary purpose spans acute rescue during anaphylactic episodes and long-term immune modulation to reduce threshold sensitivity in affected individuals. Oral immunotherapy leads in clinical trial volume but biologic therapy captures the highest margin pools due to precision-targeting mechanisms and extended dosing intervals. EpiPens remain the standard emergency intervention across all patient demographics, while sublingual immunotherapy shows faster uptake in European pediatric protocols where palatability drives adherence.
FDA accelerated approval pathways compress development timelines for novel biologics, while EMA's MDR framework imposes stricter post-market surveillance on combination-device therapies. The EU F-Gas Regulation indirectly constrains propellant choices for metered-dose emergency inhalers, altering formulation strategies for European markets. Stakeholders must monitor how FDA label expansions for existing biologics reshape competitive dynamics in peanut, milk, and multi-allergy indications without requiring de novo trials.
Market Dynamics
FDA accelerated approval pathways compress development timelines for novel biologics, while pediatric clinics across the United States expand allergen desensitization programs. These dual pressures reshape competitive positioning between patch-based, oral, and injectable delivery platforms.
Growth Catalysts
- Accelerated FDA Pathways:The FDA's expedited review frameworks for biologics targeting IgE-mediated pathways reduce time-to-market for mast cell activation inhibitors. Developers leverage this to outpace conventional immunotherapy trial timelines.
- German Cross-Border Demand:Specialized immunotherapy centers in Germany attract pediatric patients from neighboring European states, concentrating reimbursement expertise and clinical infrastructure in Munich and Berlin clusters.
- Patch-Based Delivery Innovation:Epicutaneous immunotherapy platforms eliminate injection burden, improving adherence in pediatric populations where needle avoidance drives protocol completion rates.
Market Restraints
- Biologic Manufacturing Concentration:Single-source dependencies in monoclonal antibody production create vulnerability to CMO capacity constraints and viral contamination events.
- EMA Post-Market Surveillance:The MDR framework imposes extended follow-up requirements on combination-device therapies, delaying revenue recognition for patch-injector products.
- Propellant Supply Constraints:The EU F-Gas Regulation restricts hydrofluorocarbon availability for metered-dose emergency inhalers, forcing reformulation investments for European market access.
Strategic Opportunities
- Multi-Allergen Indication Expansion:FDA label expansions for existing biologics enable peanut-milk-multi-allergy portfolios without de novo trials, compressing development costs.
- Sublingual Pediatric Protocols:European pediatric allergy networks demonstrate faster uptake of palatable immunotherapy formats, creating template for US adoption.
- CMO Network Diversification:Developers building multi-continent manufacturing partnerships reduce geographic concentration risk and secure supply continuity.
Industry Challenges
- Biologic Cold Chain Integrity:Temperature excursions during monoclonal antibody distribution compromise potency, requiring validated packaging investments across last-mile networks.
- Immunotherapy Protocol Standardization:Variable dosing escalation schedules across clinical sites complicate meta-analysis and payer evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Allergy Treatment Market |
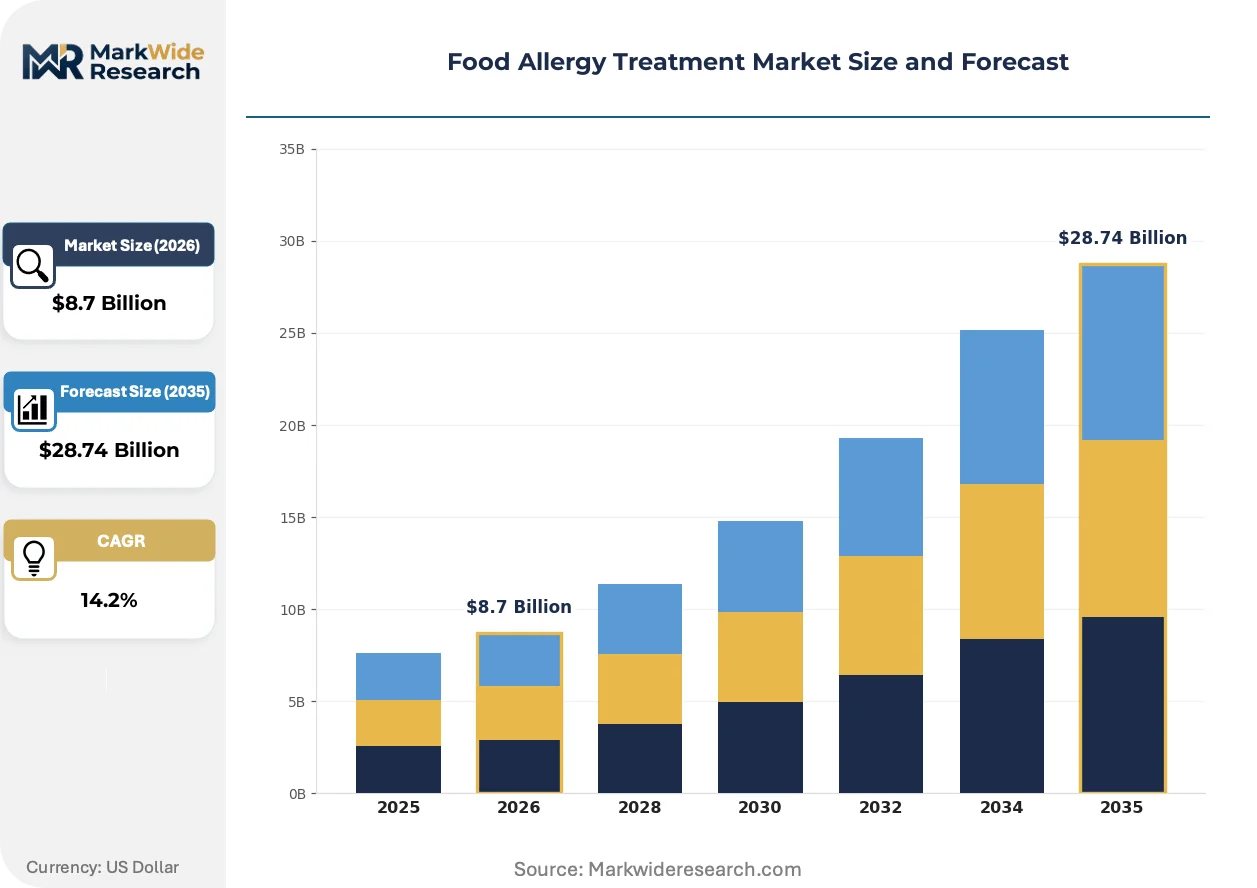
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Inhalers, EpiPens Therapy Area: Oral Immunotherapy, Sublingual Immunotherapy, Injection Therapy, Biologic Therapy End User: Pediatrics, Adults, Hospitals, Clinics Delivery Mode: Oral, Subcutaneous, Intravenous, Topical |
| Companies Covered | DBV Technologies, Vedanta Biosciences, Aimmune Therapeutics, Alladapt Immunotherapeutics, Prota Therapeutics, Aravax, Novartis, Stallergenes Greer, HAL Allergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Allergy Treatment Market Trends and Innovations
Delivery platform diversification is fragmenting the injectable-dominant paradigm. Biologic precision-targeting converges with device miniaturization to reshape patient adherence economics.
Epicutaneous immunotherapy is expanding into the pediatric maintenance segment. Patch-based platforms deposit allergen proteins through intact skin, eliminating systemic exposure risks during dose escalation. Leading pediatric allergy networks in Germany and the Netherlands now prioritize patch protocols for patients with anxiety-related injection refusal, compressing dropout rates during the critical 12-month buildup phase.
The EU MDR framework tightens clinical evidence requirements for combination products. Device-drug pairings must demonstrate human factors validation and post-market performance tracking beyond prior standards. Patch-based delivery systems face extended notified body review timelines, while emergency auto-injectors require updated usability studies for pediatric and caregiver handling scenarios.
Pediatric caregivers increasingly demand home-based dosing options that minimize clinic visits. Sublingual immunotherapy formats gain preference in European protocols where taste-masking technology improves child compliance. This behavioral shift pressures developers to reformulate biologic therapies for non-injectable administration, with oral film and buccal tablet investments accelerating in Swiss and Dutch R&D clusters.
Food Allergy Treatment Market Segmentation
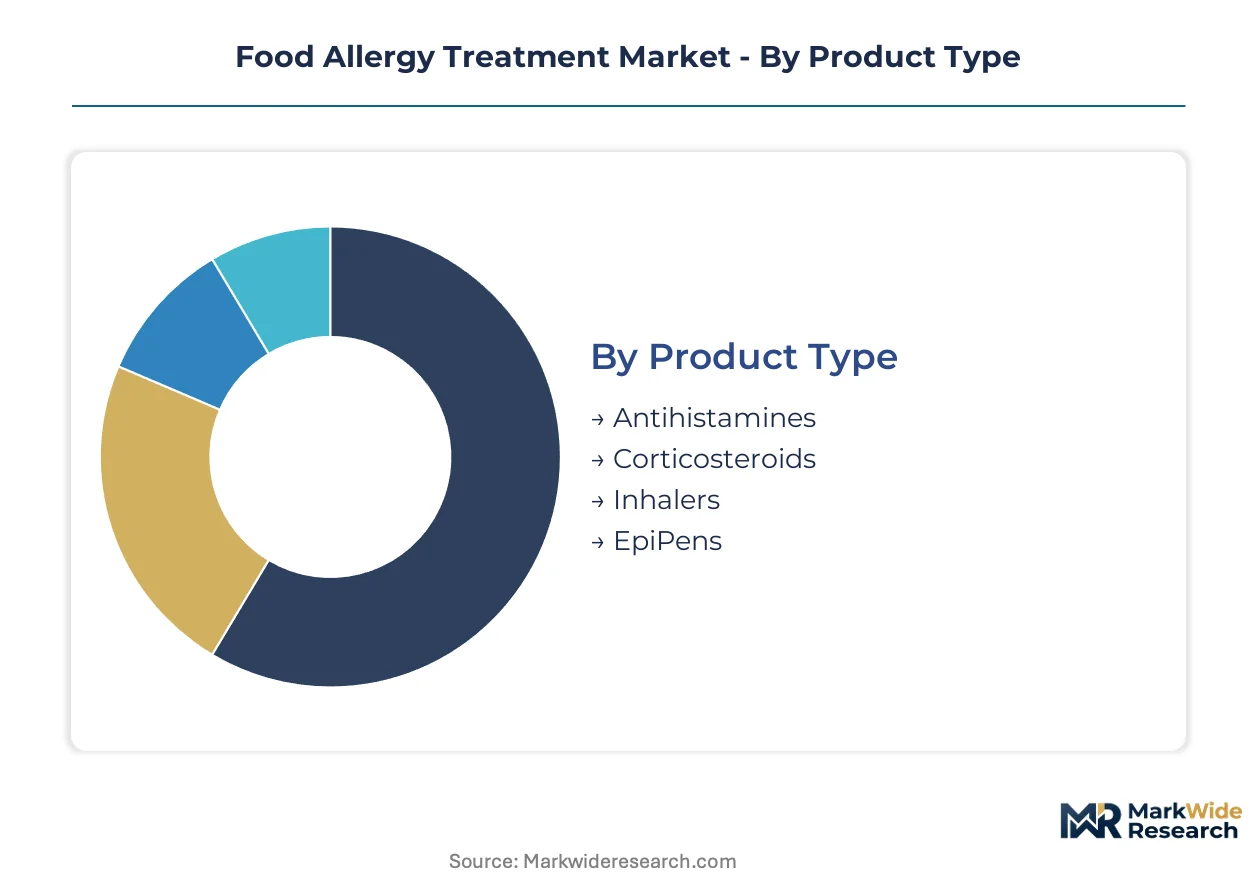
Food allergy treatment segmentation reveals divergent margin profiles across acute rescue versus long-term immune modulation. Product type and therapy area classifications expose where biologic precision commands premium positioning against commoditized emergency interventions.
Product Type:
Standalone emergency devices dominate outpatient dispensing while embedded pharmaceutical formats integrate into broader allergy management protocols.
- Antihistamines:First-generation and second-generation H1 receptor antagonists block histamine-mediated symptoms in mild allergic reactions. Demand concentrates in retail pharmacy chains across the United States where over-the-counter availability drives volume; generic substitution compresses margin per unit.
- Corticosteroids:Systemic and topical glucocorticoid formulations suppress late-phase inflammatory responses in moderate reactions. German hospital formularies prioritize intravenous methylprednisolone for acute admissions; outpatient preference shifts toward short-course oral taper regimens.
- Inhalers:Pressurized and dry-powder bronchodilator devices address respiratory manifestations of anaphylaxis.
- EpiPens:Epinephrine auto-injector systems remain the standard-of-care for anaphylaxis rescue.
Volume placements concentrate in antihistamines; the faster expansion belongs to EpiPens.
Therapy Area:
Cost tier stratification separates acute rescue interventions from multi-year immune retraining investments with divergent reimbursement profiles.
- Oral Immunotherapy:Controlled ingestion protocols escalate allergen doses to raise reaction thresholds in peanut and milk allergies. Aimmune Therapeutics anchors US commercial infrastructure; pediatric adherence challenges limit completion rates to specialized clinic networks.
- Sublingual Immunotherapy:Allergen extracts administered under the tongue build tolerance through mucosal dendritic cell exposure. Dutch and Swiss pediatric protocols demonstrate superior palatability-driven compliance versus injectable alternatives; taste-masking investments accelerate in European R&D clusters.
- Injection Therapy:Subcutaneous allergen immunotherapy requires physician-supervised administration in clinical settings.
- Biologic Therapy:Monoclonal antibodies targeting IgE or mast cell pathways interrupt hypersensitivity at molecular level.
Injection therapy captures current volume leadership; biologic therapy claims the steepest expansion trajectory.
End User:
Application context distinguishes between protocol-driven pediatric desensitization and adult self-management of established allergies.
- Pediatrics:Age-specific dosing and adherence support requirements shape product formulation and delivery design. German cross-border referral networks concentrate specialized immunotherapy expertise in Munich and Berlin; patch-based protocols reduce needle-related dropout.
- Adults:Self-directed management of long-diagnosed allergies emphasizes convenience and portability. US retail pharmacy auto-injector refill patterns indicate episodic purchasing tied to expiration date awareness rather than proactive stockpiling.
- Hospitals:Acute care settings require multi-dose epinephrine reserves and intensive care escalation pathways.
- Clinics:Outpatient allergy specialty practices host supervised immunotherapy administration and dose escalation.
Hospital procurement concentrates volume in emergency rescue formats; pediatric segments are climbing the fastest.
Delivery Mode:
Supply concentration in parenteral manufacturing creates bottleneck vulnerability while non-invasive alternatives reshape patient preference economics.
- Oral:Swallowed formulations span antihistamines, corticosteroids, and emerging immunotherapy protocols. FDA accelerated approval pathways compress timelines for novel oral biologic candidates; European palatability standards demand additional formulation investment.
- Subcutaneous:Depot injections and auto-injector devices deliver epinephrine and biologic therapies through adipose tissue. CMO capacity constraints in monoclonal antibody fill-finish operations create queue delays for new product launches.
- Intravenous:Hospital-administered corticosteroids and emergency epinephrine infusions address severe reactions.
- Topical:Epicutaneous patches deposit allergen proteins through intact skin barrier.
Subcutaneous delivery anchors current manufacturing scale; topical formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric allergen desensitization programs concentrate demand in specialized clinical clusters across North America and Europe, with cross-border patient flows amplifying infrastructure investments in Germany and the Netherlands.
United States
Pediatric clinics expand allergen desensitization programs at academic medical centers in Boston and Philadelphia. FDA accelerated approval pathways compress biologic development timelines for mast cell activation inhibitors. The Research Triangle Park cluster in North Carolina anchors contract manufacturing for monoclonal antibody fill-finish operations.
Germany
Specialized immunotherapy centers in Munich and Berlin attract pediatric patients from Austria, Switzerland, and Poland. The EU MDR framework imposes extended notified body review timelines on patch-injector combination products. Heidelberg and Hamburg host the highest concentration of European pediatric allergy trial sites.
Netherlands
Dutch pediatric protocols demonstrate superior palatability-driven compliance for sublingual immunotherapy formats. The EU F-Gas Regulation restricts propellant availability for metered-dose emergency devices. Utrecht and Rotterdam R&D clusters accelerate taste-masking technology investments for child-compliant formulations.
United Kingdom
London and Manchester pediatric networks prioritize patch-based protocols for needle-averse patients. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit surveillance requirements with EMA MDR standards. Cambridge biotech incubators concentrate oral film and buccal tablet development for non-injectable biologic administration.
Switzerland
Swissmedic maintains accelerated review pathways for biologics targeting IgE-mediated pathways. Basel and Zurich pharmaceutical clusters invest in oral film formulations to address home-based dosing preferences. Geneva hosts specialized referral centers for complex multi-allergy pediatric cases from France and Italy.
Food Allergy Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek manufacturing scale and delivery platform diversification. The market structures around three tiers: large-cap pharmaceutical manufacturers with immunology infrastructure, mid-cap biotech specialists with single-platform focus, and emerging venture-backed innovators with novel mechanism assets. Competitive positioning hinges on FDA label expansion strategies for multi-allergy indications and CMO network diversification to reduce single-source dependencies. Portfolio diversification into patch-based, oral, and injectable formats reshapes rivalry beyond mechanism alone.
Within the platform-specialist tier, DBV Technologies and Aimmune Therapeutics exemplify divergent delivery archetypes. DBV Technologies occupies a position centered on epicutaneous immunotherapy for pediatric populations, while Aimmune Therapeutics anchors the oral immunotherapy segment with established peanut allergy protocols. Novartis sits within the large-cap manufacturer tier, leveraging biologic manufacturing scale and existing immunology infrastructure. These three players collectively represent the competitive tension between precision-targeting biologics, patient-compliant delivery innovation, and manufacturing scale economics.
| Leading Market Players |
|---|
| DBV Technologies |
| Vedanta Biosciences |
| Aimmune Therapeutics |
| Alladapt Immunotherapeutics |
| Prota Therapeutics |
| Aravax |
| Novartis |
| Stallergenes Greer |
| HAL Allergy |
| Others |
Pricing and Supply Chain Analysis
Patch-based delivery platform transitions simultaneously compress manufacturing complexity and concentrate supply relationships among specialized CMOs, reshaping cost economics for pediatric immunotherapy formats while fragmenting pricing power across delivery modalities.
Pricing Analysis
Warranty and cold-chain assurance bundling separates premium biologic tiers from standard emergency device offerings. Three-tier pricing structure across premium, standard, and economy levels tracks FDA approval status and pediatric indication breadth. Price differentiation hinges on monoclonal antibody fill-finish certification grade and after-sales temperature monitoring service inclusion. Cost compression in standard EpiPen tiers is intensifying because generic auto-injector entrants erode brand premiums. Hospital procurement committees demonstrate highest price sensitivity; specialized German immunotherapy centers show lowest sensitivity due to cross-border reimbursement premiums.
Supply Chain Analysis
Dual-sourcing qualification requirements from FDA and EMA now mandate redundant CMO relationships for monoclonal antibody production. Fill-finish capacity concentrates in the United States, Germany, and Switzerland; active pharmaceutical ingredient synthesis draws from India and China. Supply chain risk centers on single-source viral contamination events in mammalian cell culture facilities. Distribution runs through validated cold-chain logistics networks with last-mile pharmacy partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoclonal antibody fill-finish capacity constraints prop pricing power for qualified CMOs, creating supply-constrained dynamics that favor incumbents with secured manufacturing slots.
For Market Incumbents: Anticipate biosimilar pressure on IgE-targeting biologics by securing multi-allergy label expansions through FDA accelerated pathways. Prioritize backward integration into patch manufacturing to reduce combination-device notified body delays under EU MDR. For New Entrants and Emerging Players: Enter via sublingual pediatric protocols in Dutch and Swiss referral networks where palatability-driven compliance gaps persist. Target home-based dosing formats for needle-averse patient segments; partner with established CMOs rather than building captive capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-specialist acquisitions by large-cap immunology manufacturers seeking delivery diversification. Five-to-ten year viability favors developers with multi-allergy pipelines and de-risked CMO relationships. Watch FDA label expansion velocity for existing biologics as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CMO Network Diversification | Reduces single-source viral contamination risk across FDA and EMA jurisdictions. |
| Multi-Allergen Label Expansion | Compresses development costs through FDA accelerated approval pathway reuse. |
| Patch Manufacturing Scale-Up | Addresses EU MDR notified body bottlenecks for combination-device submissions. |
| Sublingual Formulation Investment | Captures Dutch and Swiss pediatric protocol preference for palatable formats. |
| Cold Chain Packaging Validation | Secures last-mile potency integrity for temperature-sensitive monoclonal antibodies. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up prescription and procedure volume estimates triangulated against top-down reimbursement expenditure analysis.
Historical trendline analysis of biologic launch trajectories and immunotherapy protocol adoption informed projection modeling across the analysis window. Segmentation dimensions included therapy area, delivery mode, end user, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for FDA approval pathway acceleration effects and EMA MDR implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EMA notified body review delays or CMO capacity constraints. Deviation in monoclonal antibody fill-finish queue times would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Idiopathic Short Stature Market