
 Zinc Ingots Market | 2026-2036
Zinc Ingots Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Ingots Market Analysis
Long-term offtake contracts with embedded price-adjustment clauses is rebalancing how zinc ingots change hands between smelters and downstream fabricators. Korea Zinc leverages its integrated refining network to sustain volume commitments across Asian galvanizers. Hindustan Zinc anchors Indian supply through captive mine-to-metal operations in Rajasthan. Nyrstar competes in European spot markets with flexible smelter output calibrated to power pricing.
Zinc ingots are refined metal blocks typically cast to specifications such as SHG 99.995% purity, produced through roast-leach-electrowin or blast furnace-distillation routes, and serve primarily as feedstock for corrosion protection and alloy manufacturing. Electrolytic zinc dominates value capture in galvanization applications where coating consistency commands premium pricing. Special High Grade zinc differentiates through battery-grade qualification pathways that are tightening purity thresholds. Recycled zinc is accelerating as smelters integrate secondary feed to reduce energy intensity and raw material exposure.
China's MEE enforces emissions caps on smelter SO₂ discharge that redirect capacity toward cleaner roast-leach-electrowin circuits. REACH in Europe mandates supply chain disclosure for zinc compounds that affects alloy producer market access. India's BIS certification for galvanized structural steel propagates downstream to ingot purity requirements. Stakeholders must monitor how carbon border adjustments and power cost differentials redistribute competitive advantage between Chinese integrated producers and regional recyclers.
Market Dynamics
China's MEE emissions caps are forcing smelter consolidation toward roast-leach-electrowin circuits, while dual carbon targets redirect capital toward energy-efficient refining. This regulatory pressure concentrates production in compliant integrated facilities and raises barriers for marginal operators.
Growth Catalysts
- Construction galvanization:Infrastructure investment across India's National Infrastructure Pipeline drives structural steel demand. BIS certification mandates for galvanized products propagate purity requirements upstream to ingot suppliers.
- Battery-grade qualification:Special High Grade zinc is capturing value in energy storage applications. Purity thresholds for battery cathodes are tightening specifications beyond traditional SHG 99.995% standards.
- Secondary feed integration:Smelters in Hunan and Yunnan provinces are accelerating recycled zinc incorporation. Secondary feed reduces energy intensity and raw material exposure in primary production circuits.
Market Restraints
- Power cost volatility:European smelters face margin compression from natural gas-linked electricity pricing. Nyrstar's flexible output calibration demonstrates operational vulnerability to input cost swings.
- Supply concentration risk:Primary capacity clusters in China's southwestern provinces create geographic vulnerability. Hunan and Yunnan smelters account for disproportionate global refined output.
- Substitution pressure:Aluminum alloys and organic coatings are displacing zinc in select corrosion protection applications. Lightweighting demands in automotive manufacturing accelerate material substitution trials.
Strategic Opportunities
- Underpenetrated Indian fabrication:Rajasthan's captive mine-to-metal operations anchor domestic supply. Hindustan Zinc's integrated model demonstrates scalable backward integration potential for regional expansion.
- Carbon border adjustment positioning:EU CBAM implementation creates competitive openings for low-carbon zinc producers. Korean integrated refiners can leverage cleaner energy profiles for European market access.
- Long-term contract restructuring:Embedded price-adjustment clauses are rebalancing smelter-fabricator relationships. Volume commitments with Korea Zinc demonstrate template for risk-sharing mechanisms.
Industry Challenges
- Electrowin technician scarcity:Roast-leach-electrowin circuit optimization requires specialized metallurgical expertise. Smelter expansion plans confront constrained talent pipelines for process engineers.
- REACH compliance complexity:European alloy producers face supply chain disclosure mandates for zinc compounds. Documentation burdens extend from smelters through downstream fabrication networks.
- Legacy blast furnace transition:Distillation-based operations require substantial capital for emissions retrofit. MEE SO₂ caps accelerate obsolescence of conventional thermal reduction circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Ingots Market |
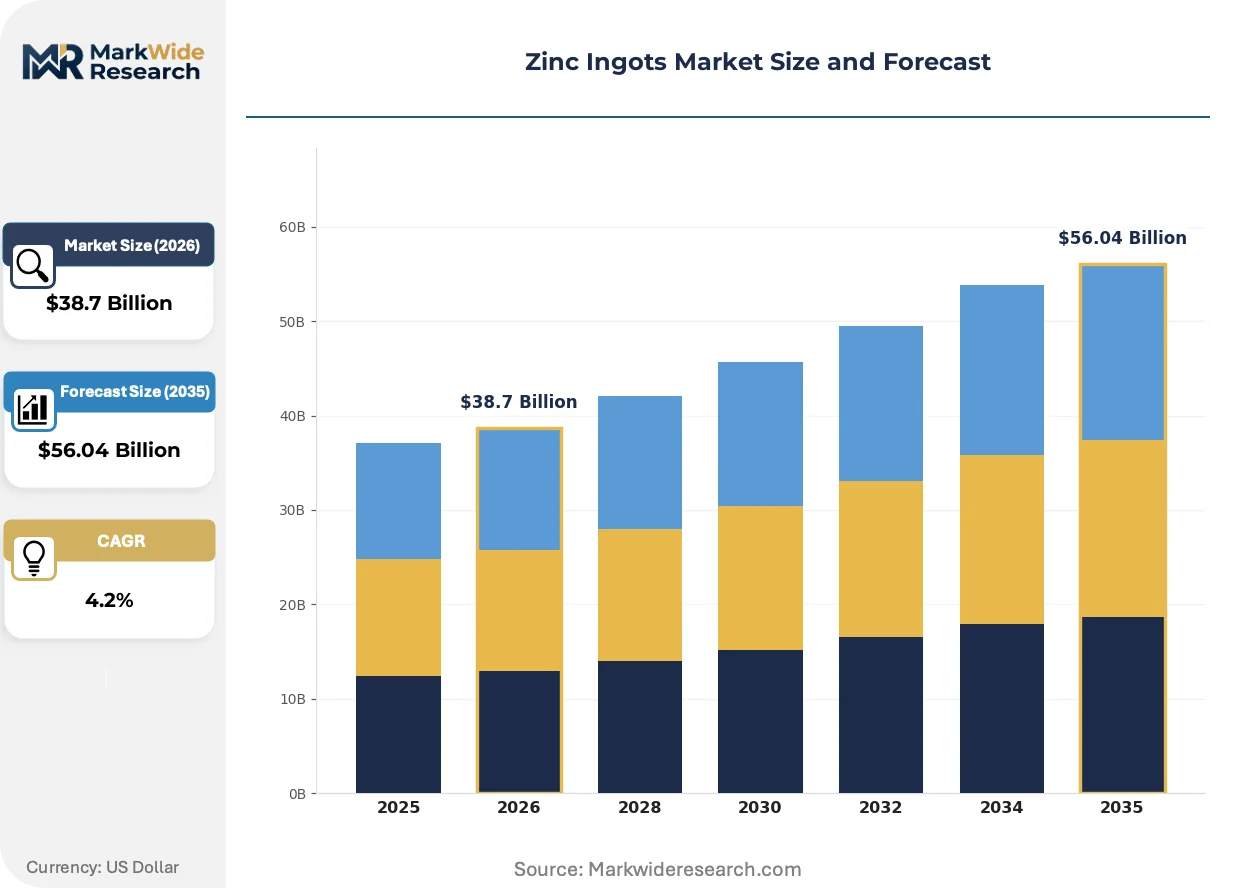
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Zinc, Special High Grade Zinc, Zinc-Alloy, Recycled Zinc End User: Construction, Automotive, Electronics, Agriculture Distribution Channel: Direct Sales, Wholesale, Retail, Online Application: Galvanization, Die Casting, Coating, Alloy Production |
| Companies Covered | Kazzinc, Liaoning Huludao Zinc Industry Co., Ltd., Hindustan Zinc, Yunnan Chihong Zn & Ge, Guangdong Zhongjin Lingnan, Nyrstar, Hunan Zhuzhou Smelter Group Co., Ltd., Henan Yuguang Gold & Lead, Korea Zinc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Ingots Market Emerging Trajectories
Refining technology convergence and procurement recalibration are compressing traditional value chain arrangements. Smelters and fabricators are restructuring commercial relationships around risk-sharing mechanisms.
Direct solvent extraction-electrowinning circuits are electrifying zinc production economics by eliminating intermediate roasting stages. Korean refiners are adopting these configurations to reduce energy intensity and SO₂ generation. The technology is compressing capital requirements for greenfield capacity and enabling modular expansion in power-constrained regions.
China's dual carbon goals are mandating smelter emissions intensity benchmarks that favor electrowinning over blast furnace routes. MEE enforcement redirects investment toward captive renewable power integration. European galvanizers are responding by qualifying Chinese suppliers against CBAM carbon intensity thresholds ahead of full implementation.
Buyers are consolidating procurement through multi-year offtake agreements with embedded price-adjustment mechanisms. Spot market participation is concentrating among traders and non-integrated fabricators lacking volume commitments. This shift is most visible across East Asian manufacturing clusters where Korean and Chinese smelters anchor supply security for downstream galvanizers.
Zinc Ingots Market Segmentation
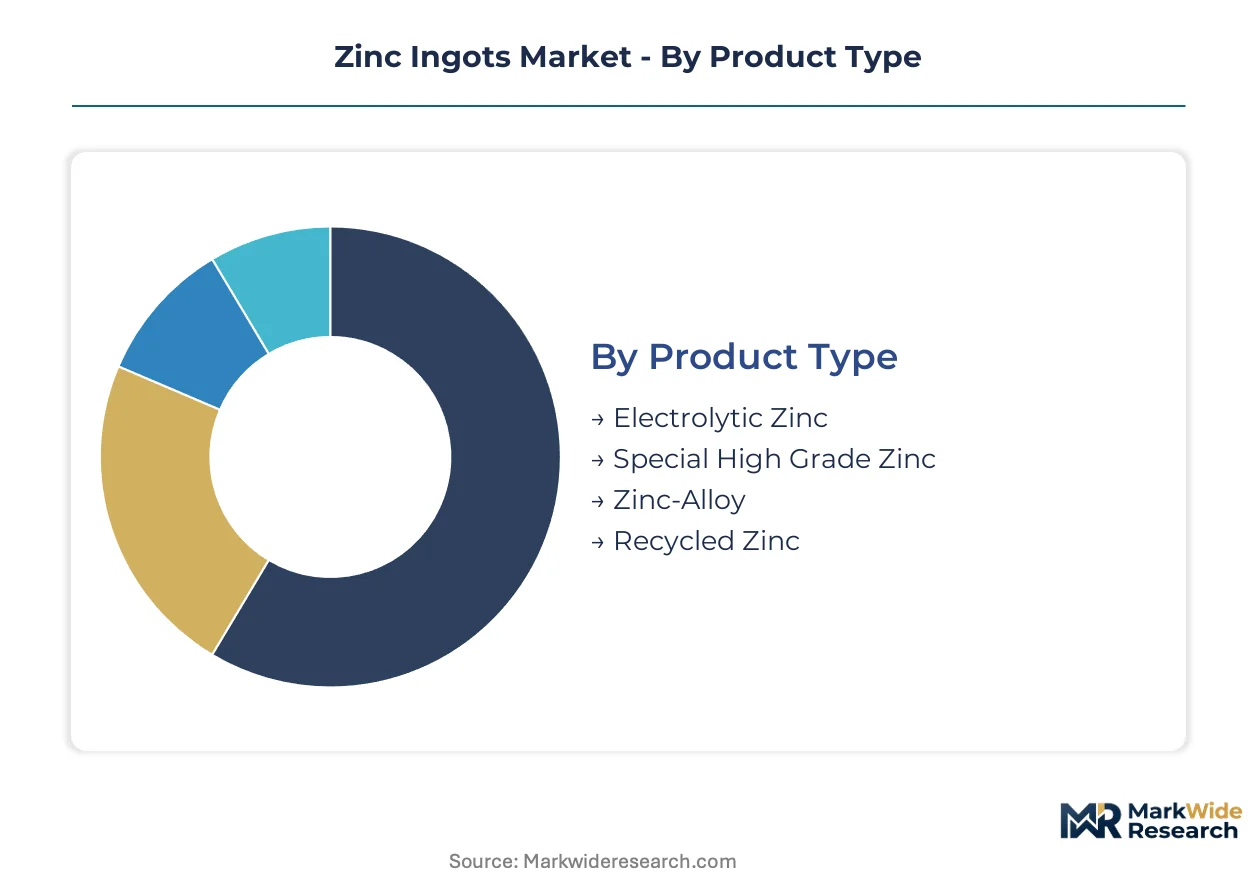
Zinc ingot segmentation tracks how purity specifications, end-use requirements, and procurement channels redistribute value across the value chain. Supply concentration in Chinese smelting clusters amplifies how product-grade differentiation and channel selection determine competitive access.
Product Type:
Primary smelter output concentrates in electrolytic circuits across Hunan and Yunnan provinces, while secondary feed integration is reshaping cost structures for marginal grades.
- Electrolytic Zinc:SHG 99.995% purity metal produced through roast-leach-electrowin circuits dominates galvanization feedstock where coating consistency commands premium placement. Demand concentrates in East Asian manufacturing clusters serving infrastructure and automotive OEMs, with MEE emissions enforcement favoring cleaner electrowinning configurations over legacy thermal routes.
- Special High Grade Zinc:Ultra-pure metal exceeding traditional SHG specifications serves battery cathode applications where trace element thresholds are tightening beyond legacy standards. Korean refiners leverage integrated networks to qualify material against emerging energy storage purity protocols, capturing value as electrochemical storage expands.
- Zinc-Alloy:Pre-formulated ingots with controlled aluminum, copper, or magnesium additions streamline die casting operations for automotive and electronics fabricators.
- Recycled Zinc:Secondary feed from galvanized scrap and manufacturing returns reduces energy intensity in primary smelter circuits, with Hunan operators accelerating integration to manage raw material exposure.
Today's leader: Electrolytic Zinc. Tomorrow's challenger: Special High Grade Zinc.
End User:
Construction galvanization absorbs the largest volume flows, though automotive lightweighting and electronics miniaturization are recalibrating grade requirements across customer segments.
- Construction:Structural steel galvanization for infrastructure projects drives SHG 99.995% offtake, with India's National Infrastructure Pipeline propagating BIS certification requirements upstream to ingot suppliers. Fabricators in Rajasthan and Gujarat anchor regional demand through captive mine-to-metal supply chains.
- Automotive:Die casting alloys for powertrain housings and chassis components consume high-purity electrolytic grades, with OEMs qualifying secondary feed content for sustainability reporting compliance.
- Electronics:Precision die casting for connectors and shielding applications demands tight compositional control, with surface finish specifications driving alloy selection.
- Agriculture:Zinc oxide feedstock for fertilizer and animal nutrition applications operates on lower purity tolerances, with regional compounders sourcing standard-grade material through wholesale channels.
Construction maintains volume dominance. Battery-grade qualification for automotive electrification is climbing the fastest.
Distribution Channel:
Long-term contract structures are compressing spot market participation, with direct sales capturing integrated fabricator relationships and wholesale channels serving fragmented regional processors.
- Direct Sales:Multi-year offtake agreements with embedded price-adjustment clauses anchor volume commitments between Korean and Chinese smelters and downstream galvanizers, reducing spot price exposure for qualified buyers.
- Wholesale:Regional distributors aggregate smaller fabricator demand across India's western and southern states, managing inventory positions against LME price volatility.
- Retail:Small-lot sales to machine shops and maintenance operations operate on spot pricing with limited contract coverage.
- Online:Digital procurement platforms are emerging for standardized grade spot purchases, though physical inspection requirements limit adoption for critical applications.
Direct sales lock in supply security. Online channels face the steepest adoption constraints from material verification requirements.
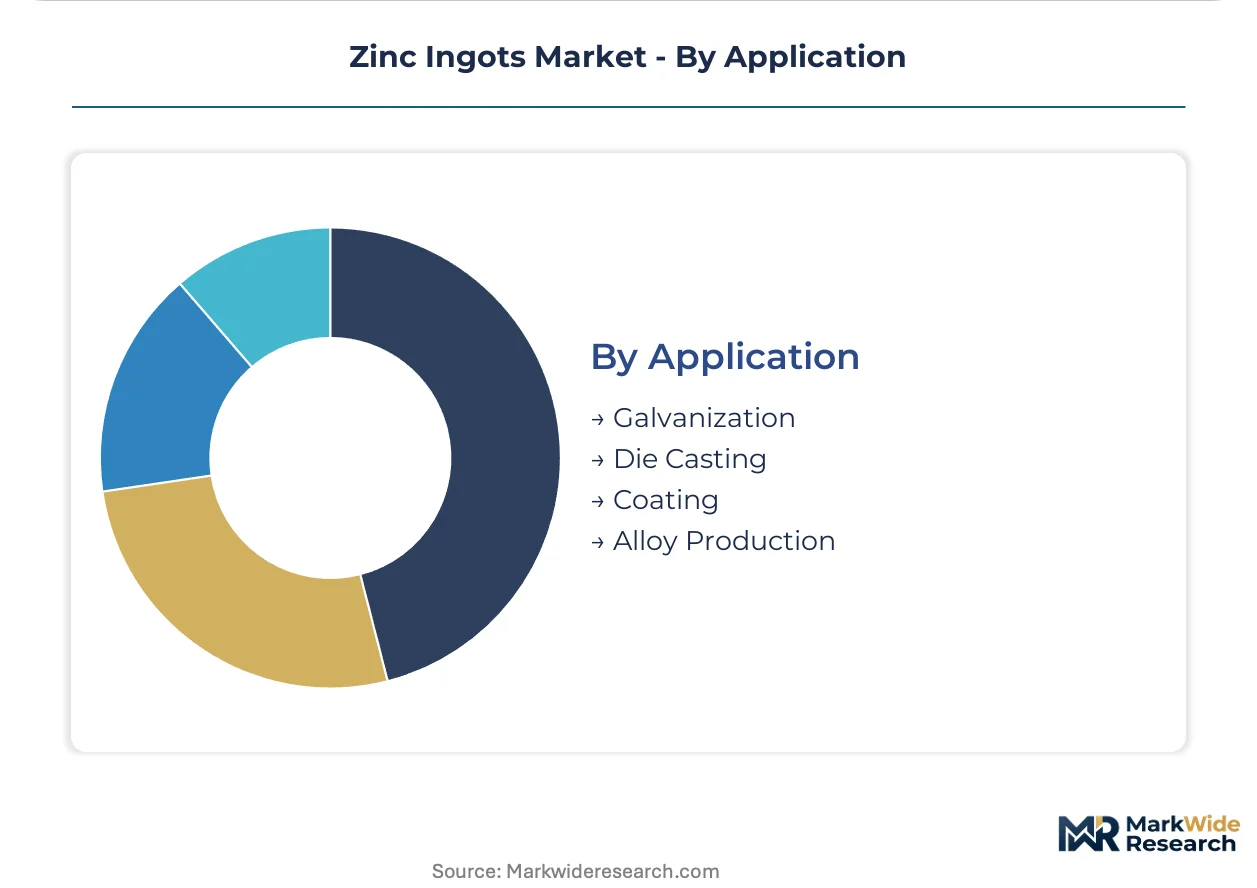
Application:
Galvanization commands the purest grades and tightest supply relationships, while die casting and alloy production accommodate broader specification ranges and secondary feed incorporation.
- Galvanization:Hot-dip and continuous coating lines for structural steel and automotive sheet demand SHG electrolytic zinc with minimal lead and cadmium content, with European galvanizers qualifying Chinese suppliers against CBAM carbon intensity thresholds.
- Die Casting:High-pressure injection molding for automotive and electronics housings consumes zinc-aluminum alloys with controlled copper content, with Rajasthan's captive operations serving Indian fabricator clusters.
- Coating:Paints, pigments, and chemical processing applications utilize lower-purity grades with broader compositional tolerances.
- Alloy Production:Brass and bronze manufacturers blend primary and secondary zinc with copper feedstock, with REACH disclosure mandates extending documentation burdens through European supply chains.
Galvanization holds the premium tier. Die casting is gaining share fastest from automotive lightweighting substitution trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's smelter consolidation outpaces India's mine-to-metal expansion, creating divergent supply security models across Asia. European galvanizers face carbon border exposure while North American fabricators navigate power cost volatility. Regional regulatory regimes are redistributing competitive advantage toward integrated producers with captive energy and cleaner refining circuits.
China
Dual carbon targets and MEE emissions caps are shuttering marginal blast furnace operations in Hunan and Yunnan provinces. Roast-leach-electrowin circuits absorb displaced capacity as compliant smelters integrate captive renewable power. Zhuzhou and Chihong industrial clusters anchor refined output, with secondary feed incorporation accelerating to manage concentrate exposure.
India
National Infrastructure Pipeline spending propagates BIS certification requirements from galvanized structural steel back to ingot purity standards. Hindustan Zinc's captive mine-to-metal operations in Rajasthan anchor domestic supply security for western fabricator clusters. Gujarat die casters qualify secondary feed content for automotive OEM sustainability reporting.
South Korea
Integrated refiners leverage cleaner energy profiles to position against EU CBAM carbon intensity thresholds. Korea Zinc's long-term offtake structures with Asian galvanizers demonstrate risk-sharing contract templates. Busan-Ulsan industrial corridor concentrates export-oriented capacity serving battery-grade qualification pathways.
Germany
REACH supply chain disclosure mandates extend documentation burdens from smelters through alloy producer networks. ECHA enforcement redirects procurement toward qualified suppliers with verified compound traceability. North Rhine-Westphalia fabrication clusters face margin compression from natural gas-linked power pricing.
United States
EPA emissions oversight and state-level renewable portfolio standards reshape smelter power sourcing decisions. Midwest galvanizers serving infrastructure projects confront concentrate supply volatility from concentrated Chinese sourcing. Southeast manufacturing expansion drives die casting alloy demand for automotive lightweighting trials.
Zinc Ingots Market Vendor Landscape
Top-tier vendors anchor integrated mine-to-metal supply chains, while mid-scale operators compete through flexible output calibration and secondary feed optimization. Market structure concentrates around three strategic archetypes: captive resource holders with backward integration, power-advantaged refiners with tolling flexibility, and alloy specialists with die casting formulation expertise. Capacity expansion and long-term contract restructuring represent the dominant competitive moves reshaping smelter-fabricator relationships.
Within the integrated resource tier, Hindustan Zinc and Korea Zinc exemplify mine-to-metal models that control concentrate exposure through captive mining operations. Yunnan Chihong Zn & Ge occupies a position among Chinese state-affiliated producers consolidating compliant capacity under MEE emissions enforcement. Nyrstar represents the power-sensitive European archetype, with operational vulnerability to input cost swings demonstrating how regional energy pricing redistributes margin capture across the value chain.
| Leading Market Players |
|---|
| Kazzinc |
| Liaoning Huludao Zinc Industry Co., Ltd. |
| Hindustan Zinc |
| Yunnan Chihong Zn & Ge |
| Guangdong Zhongjin Lingnan |
| Nyrstar |
| Hunan Zhuzhou Smelter Group Co., Ltd. |
| Henan Yuguang Gold & Lead |
| Korea Zinc |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals gate both qualified supply and premium-tier pricing access, forcing European galvanizers to qualify Chinese smelters against CBAM carbon intensity thresholds before contract execution. MEE emissions enforcement concentrates compliant capacity in Hunan and Yunnan roast-leach-electrowin circuits, while power cost differentials between Asian integrated producers and European spot-market operators compress margin capture across the value chain.
Pricing Analysis
Capacity additions in China's southwestern provinces are reshaping price floors for SHG 99.995% electrolytic grades. Contract-based long-term offtake with embedded price-adjustment clauses dominates volume flows between Korean smelters and downstream galvanizers. Price differentiation rests on carbon intensity certification and purity thresholds for battery-grade qualification. Cost compression in European spot tiers is intensifying because natural gas-linked electricity pricing erodes Nyrstar's flexible output margins. Small-lot retail buyers exhibit highest price sensitivity; integrated automotive OEMs with multi-year commitments show least.
Supply Chain Analysis
Battery-grade qualification pathways are gating supplier access as Korean refiners tighten trace element thresholds beyond legacy SHG standards. Geographic supply concentrates in China, South Korea, and India. Raw material flows draw from zinc concentrate imports, secondary galvanized scrap, and captive mining operations in Rajasthan. Single-source vulnerability runs through Hunan and Yunnan smelter clusters that anchor disproportionate global refined output. Distribution runs through direct sales channels locking multi-year volume commitments between integrated producers and qualified fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through secondary feed integration that reduces energy intensity and raw material exposure in primary circuits. Premium-tier capture accelerates for Special High Grade zinc qualified against tightening battery cathode protocols.
For Market Incumbents: Anchor supply security through captive renewable power integration in compliant Chinese smelters. Lock long-term offtake structures with embedded price-adjustment clauses to defend against aluminum alloy substitution in automotive lightweighting trials. Deepen backward integration into secondary feed streams to manage concentrate price volatility.
For New Entrants and Emerging Players: Capture underpenetrated Indian fabrication demand through Rajasthan-adjacent tolling arrangements serving Gujarat die casters. Target battery-grade qualification pathways where purity thresholds exceed legacy SHG standards and incumbent capacity faces electrowin technician scarcity. Pursue joint venture entry with Hunan operators seeking secondary feed optimization expertise.
For Investors and Strategic Acquirers: Roll-up economics work for power-advantaged refiners because regional electricity pricing differentials redistribute margin capture toward integrated Asian producers. Long-term viability favors mine-to-metal archetypes with captive concentrate supply and carbon-compliant refining circuits. Watch EU CBAM implementation pace as inflection indicator for European market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Feed Integration | Hunan smelters reduce energy intensity and raw material exposure through accelerated scrap incorporation. |
| Long-term Supply Agreement | Korean refiners anchor volume commitments with Asian galvanizers through risk-sharing contract templates. |
| Green Manufacturing Transition | Roast-leach-electrowin circuits displace blast furnace capacity under MEE emissions enforcement. |
| Backward Integration | Hindustan Zinc's captive Rajasthan mining anchors domestic supply security for western fabricator clusters. |
| Joint Venture | European galvanizers partner with Chinese smelters to secure CBAM-compliant supply ahead of full implementation. |
Methodological Framework
Multiple input streams — primary interviews with smelter operations directors, procurement leads at downstream galvanizers, and technical R&D heads at alloy producers; secondary validation through customs trade data, SEC filings of listed miners, LME warehouse stock reports, and MEE emissions disclosure filings; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates. Conversations with electrowin process engineers and REACH compliance officers at European alloy producers provided operational context for technology and regulatory segmentation.
Historical volume trajectories were cross-referenced against panel input from industry participants to project growth across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use industry, and distribution channel structure. CAGRs were derived from slope analysis of normalized demand curves. Forecast inputs incorporated power cost differentials between regional grids and secondary feed incorporation rates at Chinese smelters.
Underlying measurement precision varies by segment; battery-grade qualification pathways and construction galvanization volumes carry tighter precision than fragmented agricultural compounder demand. Forecasts reflect assumptions about MEE enforcement continuity, CBAM implementation sequencing, and concentrate supply concentration. A model refresh is warranted upon material change in Chinese smelter emissions policy or EU carbon border adjustment scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metallurgical Coal Market
Metals
Pump Casing Materials Market
Metals
Crude Steel Market
Metals
Global Welding Powder Market
Metals
Copper and Copper Alloy Market
Metals
Global Steel Market
Metals
Europe Aluminum Extrusion Market
Metals
Niobium Market
Metals
High Purity Pig Iron Market
Metals
Ferro Aluminum Market
Metals
Metal Casting Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Copper Powder Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Ferrite Market
Metals
Potassium Platinochloride Market