
 Platform Architecture Market | 2026-2036
Platform Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Platform Architecture Market Analytics
The EU AI Act is pivoting enterprise procurement toward auditable, interoperable platform stacks. Microsoft Corp. leverages its Azure sovereign cloud investments to compete for regulated European workloads. Amazon Web Services anchors demand through its GovCloud and dedicated local zone expansions. Google LLC differentiates via Kubernetes-native tooling and open-source ecosystem control.
Platform architecture encompasses the structural design of integrated hardware, software, and middleware layers that enable scalable application deployment, typically specified through container runtime compatibility, API gateway throughput thresholds, and service mesh latency parameters. Its primary commercial purpose is to abstract infrastructure complexity so development teams can deploy, monitor, and scale applications without managing underlying compute resources. Infrastructure as a Service retains the largest revenue pool as enterprises maintain legacy workload hosting, while Platform as a Service captures the fastest expansion as organizations seek managed runtime environments. Microservices architecture dominates new build decisions, though monolithic refactoring still commands substantial professional services expenditure.
The Federal Risk and Authorization Management Program (FedRAMP) and the EU Cybersecurity Act shape market access by mandating standardized security attestations for cloud platform providers. ISO 27001 and SOC 2 Type II certifications function as baseline procurement filters across enterprise and government segments. Stakeholders must monitor evolving data sovereignty requirements as jurisdictions fragment platform deployment strategies across jurisdictional boundaries.
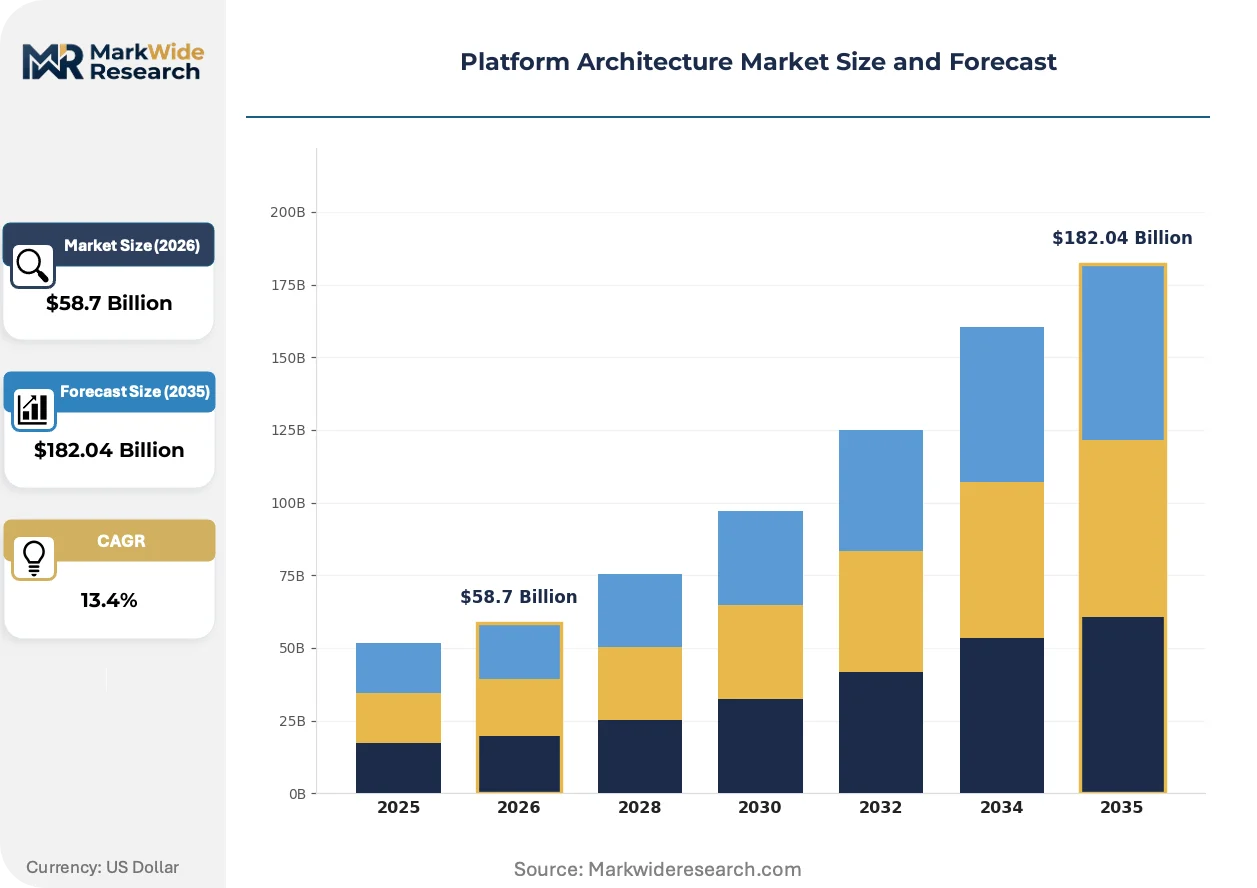
Market Dynamics
Container orchestration and microservices adoption is compressing deployment cycles across enterprise infrastructure stacks, forcing legacy system integrators to restructure service delivery models around API-first architectures.
Growth Catalysts
- FedRAMP Authorization:Federal cloud modernization directives mandate standardized security attestations, creating procurement pipelines for compliant platform providers serving United States government agencies.
- Financial Services Operational Resilience Mandates:Banking regulators in the United States and European Union require redundant, auditable infrastructure architectures, accelerating platform modernization budgets.
- Hyperscaler Local Zone Expansion:Dedicated cloud infrastructure deployments in Germany, France, and the United Kingdom address data sovereignty requirements while lowering latency for regulated workloads.
Market Restraints
- Certified Talent Scarcity:Kubernetes and service mesh engineering expertise concentrates in technology hubs, inflating professional services costs and extending implementation timelines.
- Legacy Integration Complexity:Mainframe and monolithic application dependencies in financial services and healthcare sectors create technical debt that resists containerization.
- Input Cost Volatility:Specialized silicon for AI inference workloads experiences supply constraints, compressing margins for platform providers offering GPU-enabled managed runtimes.
Strategic Opportunities
- EU AI Act Compliance Services:Auditable, interoperable platform stacks present white space for vendors offering pre-certified governance tooling to European enterprise buyers.
- Edge-Native Microservices:Manufacturing and logistics sectors in Japan and South Korea deploy lightweight container runtimes for latency-sensitive industrial automation.
- Sovereign Cloud Partnerships:National data localization requirements in India, Brazil, and Saudi Arabia create channel opportunities through joint ventures with domestic infrastructure operators.
Industry Challenges
- Multi-Cloud Skill Fragmentation:Platform engineering teams struggle to maintain operational proficiency across AWS, Azure, and Google Cloud native tooling simultaneously.
- Service Mesh Certification Delays:ISO 27001 and SOC 2 Type II attestation timelines extend 6-12 months, blocking revenue recognition for new platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platform Architecture Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $182.04 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Model: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service Technology Stack: Microservices, Serverless, Containers, Monolithic End User Industry: Telecommunications, Healthcare, Finance, Education |
| Companies Covered | Amazon Web Services, Microsoft Corp., Google LLC, IBM Corp., Cisco Systems, Inc., Oracle Corporation, SAP SE, Synopsys Inc., Apprenda Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platform Architecture Market Evolving Landscape
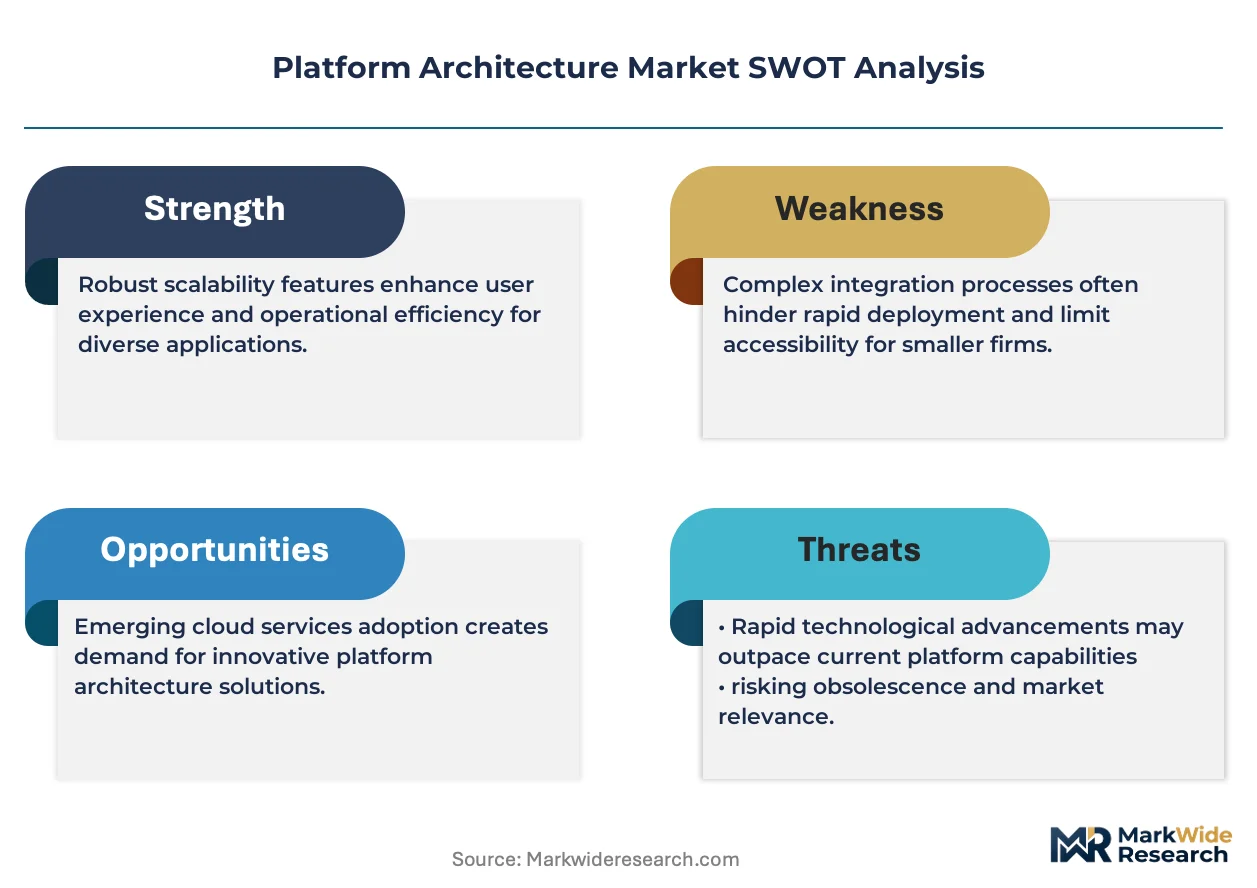
Platform architecture markets are experiencing fundamental restructuring around API governance models, regulatory compliance automation, and consumption-based procurement frameworks that displace traditional enterprise licensing.
Service mesh technologies are expanding into regulated financial services and healthcare deployments as organizations seek zero-trust networking without custom engineering. Large United States banks and European insurers adopt Istio and Linkerd implementations to satisfy audit requirements for inter-service traffic encryption. The technology is expanding into compliance tooling markets by embedding policy-as-code enforcement directly into data plane operations.
GDPR and the EU AI Act are mandating algorithmic transparency and data lineage tracking that platform vendors must architect into core infrastructure layers. European enterprises now require explainable inference pipelines and automated consent management as table-stakes procurement criteria. French and German healthcare systems lead adoption of these capabilities, filtering vendor selection toward providers with pre-built compliance modules.
Enterprise buyers are consolidating vendor relationships around integrated platform suites rather than best-of-breed component assembly. Procurement teams in United States federal agencies and German automotive manufacturers now prioritize single-vendor accountability for runtime, observability, and security layers. This concentration is most visible in defense and aerospace verticals where supply chain attestation requirements favor vertically integrated platform stacks.
Platform Architecture Market Segmentation
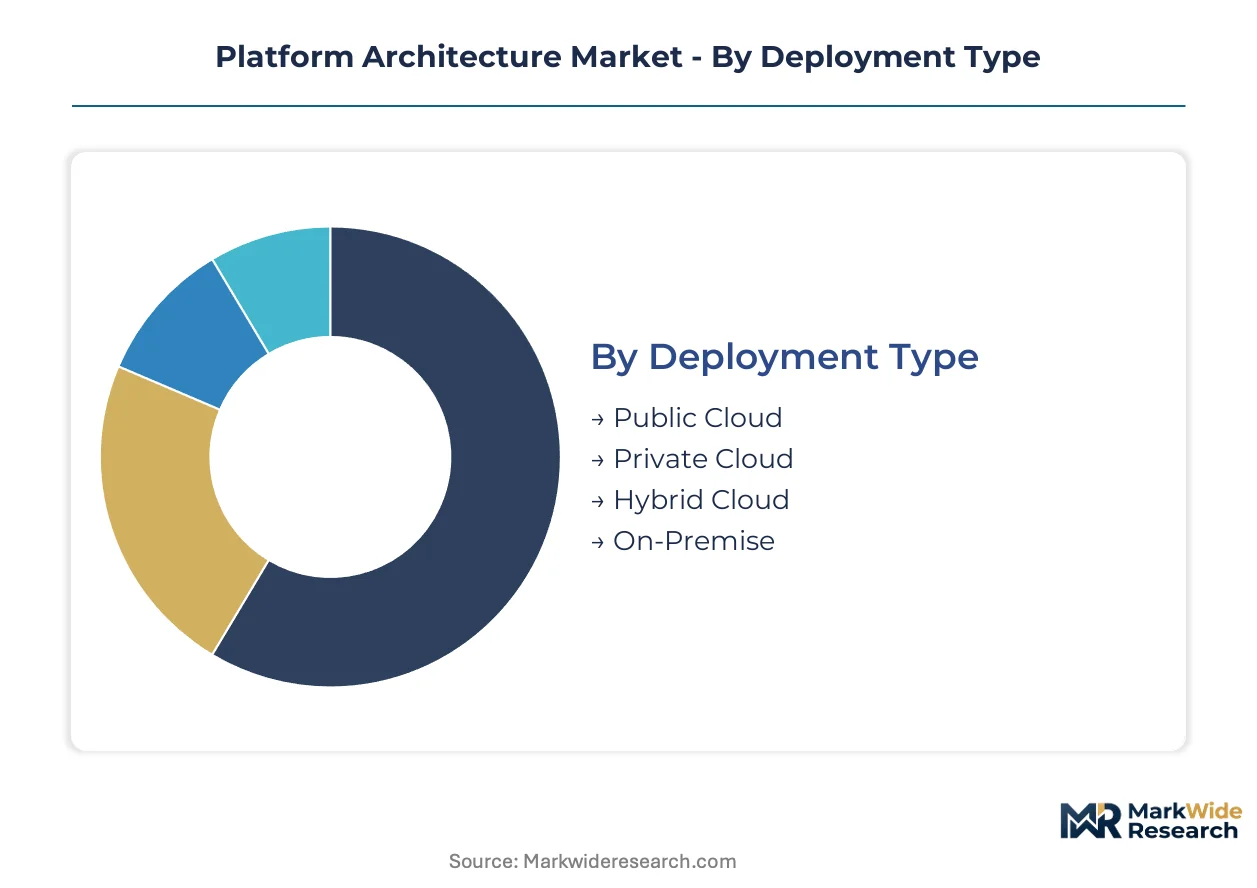
Platform architecture procurement decisions hinge on workload sensitivity, compliance posture, and legacy system interdependencies. Deployment patterns diverge sharply between regulated financial services requiring sovereign data control and technology startups optimizing for elasticity.
Deployment Type:
Deployment architecture determines data residency capabilities, latency profiles, and operational control boundaries for enterprise platform engineering teams.
- Public Cloud:Multi-tenant infrastructure pools compute resources across shared physical substrates, delivering elasticity through hyperscaler-managed data centers in Virginia, Frankfurt, and Singapore. United States federal agencies and European pharmaceutical manufacturers deploy FedRAMP and GDPR-compliant configurations to satisfy audit requirements without capital expenditure.
- Private Cloud:Dedicated single-tenant environments provision virtualized resources on customer-controlled hardware or exclusive third-party facilities. German automotive manufacturers and Swiss banking consortia mandate private deployments to satisfy national data localization statutes and sector-specific supervisory requirements.
- Hybrid Cloud:Orchestrated workload portability across on-premise and cloud substrates enables burst capacity for seasonal demand spikes. Retailers and logistics operators in Japan deploy hybrid configurations to maintain inventory systems on-premise while scaling customer-facing applications to public cloud during peak transaction windows.
- On-Premise:Fully captive infrastructure operates within customer-owned facilities with no external network dependency. Defense contractors and critical infrastructure operators in Saudi Arabia and Australia maintain air-gapped deployments to satisfy national security classifications and operational continuity mandates.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Service Model:
Abstraction depth shapes procurement economics, with higher-layer services commanding premium pricing for reduced engineering overhead.
- Infrastructure as a Service:Raw compute, storage, and network virtualization permits maximum configuration flexibility for platform engineering teams. Financial services firms in London and New York maintain IaaS dominance for legacy workload hosting while modernizing adjacent systems.
- Platform as a Service:Managed runtime environments automate container orchestration, database provisioning, and middleware maintenance. Healthcare technology startups in Tel Aviv and Bangalore accelerate product iteration by outsourcing Kubernetes cluster management to specialized providers.
- Software as a Service:Fully managed application delivery eliminates infrastructure administration entirely, with API integration becoming the primary procurement consideration. Enterprise resource planning and customer relationship management platforms in Brazil and Mexico consolidate around SaaS delivery models.
- Function as a Service:Event-driven compute primitives execute code fragments without persistent server allocation, optimizing for intermittent workloads. IoT data processing pipelines and payment gateway webhooks in South Korea deploy FaaS to minimize idle resource expenditure.
Infrastructure as a Service dominates current expenditure; Platform as a Service exhibits the steepest expansion trajectory.
Technology Stack:
Architectural patterns determine team structure, release velocity, and technical debt accumulation across application lifecycles.
- Microservices:Decomposed service boundaries enable independent deployment cycles and technology heterogeneity. Large United States banks and European insurers adopt Istio service meshes to satisfy zero-trust networking mandates for inter-service traffic encryption.
- Serverless:Event-triggered execution models eliminate capacity planning and infrastructure provisioning overhead. Retail analytics and fraud detection workloads in Singapore and Dubai deploy serverless functions for cost-proportional scaling.
- Containers:Operating-system-level virtualization packages applications with dependencies for consistent deployment across environments. Manufacturing and logistics sectors in Japan deploy lightweight container runtimes for latency-sensitive industrial automation at the edge.
- Monolithic:Unified codebase architectures persist in maintenance-mode systems where refactoring economics remain unfavorable. Healthcare claims processing and government pension administration systems in Canada and France retain monolithic structures due to regulatory validation costs.
Microservices leads on new-build decisions; Containers leads on deployment velocity.
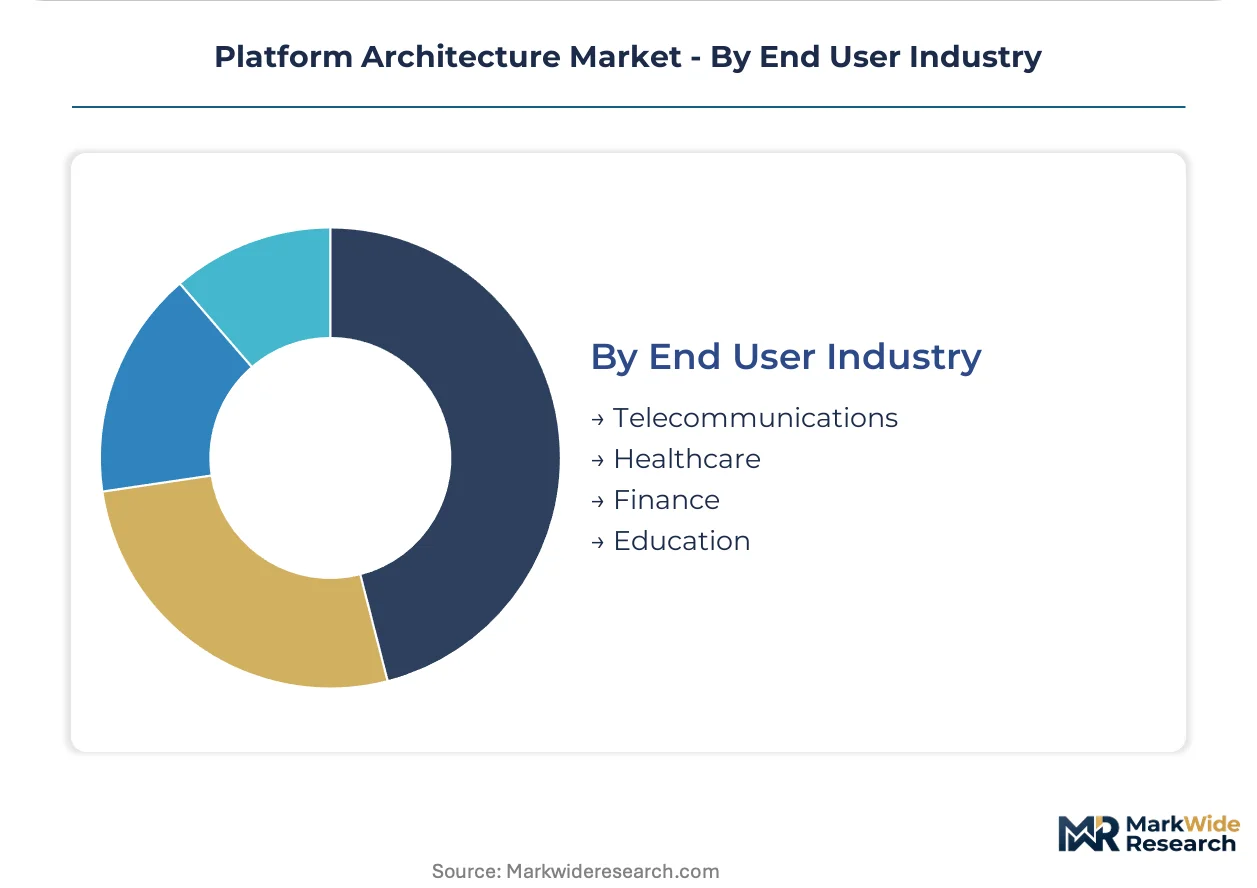
End User Industry:
Sector-specific compliance frameworks and latency requirements filter platform architecture selection toward specialized configurations.
- Telecommunications:5G network function virtualization and edge computing infrastructure demand ultra-low latency platform stacks. Operators in Germany and South Korea deploy containerized radio access network components to meet milliseconds-grade performance specifications.
- Healthcare:Electronic health record systems and diagnostic imaging platforms require HIPAA and GDPR-aligned data lineage tracking. French and German hospital systems lead adoption of explainable inference pipelines and automated consent management modules.
- Finance:Trading systems and risk calculation engines mandate deterministic latency and operational resilience attestations. Banking regulators in the United States and European Union require redundant, auditable infrastructure architectures.
- Education:Learning management systems and research computing platforms balance cost efficiency with intermittent usage spikes. Universities in Australia and the Netherlands deploy hybrid configurations to accommodate semester-based demand patterns.
Finance leads on security expenditure; Healthcare leads on compliance tooling adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform architecture markets trace their commercial origins to hyperscaler data center buildouts in the United States during the mid-2000s, with subsequent regulatory fragmentation driving geographic specialization in deployment strategies.
United States
FedRAMP authorization requirements and federal cloud modernization directives sustain procurement pipelines for compliant platform providers. The SEC and banking regulators enforce operational resilience mandates that accelerate redundant infrastructure spending. Northern Virginia's data center corridor hosts the densest concentration of container orchestration deployments serving government and financial services workloads.
Germany
Automotive manufacturers and banking consortia mandate private cloud configurations to satisfy national data localization statutes. The EU AI Act and GDPR impose algorithmic transparency requirements that filter vendor selection toward auditable platform stacks. Frankfurt's financial district anchors demand for sovereign cloud partnerships addressing supervisory requirements from BaFin.
Japan
Manufacturing and logistics operators deploy lightweight container runtimes for latency-sensitive industrial automation at the edge. METI policies promote 5G network function virtualization and domestic cloud infrastructure development. The Kansai region around Osaka concentrates automotive platform engineering teams modernizing legacy production systems.
South Korea
Telecommunications operators containerize radio access network components to meet milliseconds-grade 5G performance specifications. MFDS and national cybersecurity frameworks shape procurement criteria for healthcare and critical infrastructure platforms. Seoul Capital Area hosts the densest cluster of IoT data processing pipelines utilizing function-as-a-service architectures.
United Kingdom
Financial services firms in London maintain hybrid configurations balancing legacy workload hosting with public cloud burst capacity. The Financial Conduct Authority's operational resilience rules mandate recovery time objectives that drive platform redundancy investments. The Thames Valley corridor concentrates fintech platform engineering teams serving trading system modernization.
Platform Architecture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and sovereign cloud specialization. Hyperscalers with dedicated local zone networks command pricing power in regulated European and Asia-Pacific markets. Three archetypes dominate: vertically integrated cloud providers, specialized platform engineering consultancies, and open-source tooling vendors. Consolidation accelerates through sovereign cloud joint ventures and API governance platform acquisitions.
Within the hyperscaler tier, Amazon Web Services, Microsoft Corp., and Google LLC occupy positions defined by divergent specialization vectors. AWS anchors government segment presence through FedRAMP-authorized infrastructure investments. Microsoft exemplifies the sovereign cloud archetype via Azure regional deployments targeting EU data residency requirements. Google represents the Kubernetes-native positioning vector, leveraging open-source ecosystem control to differentiate managed runtime offerings.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corp. |
| Google LLC |
| IBM Corp. |
| Cisco Systems, Inc. |
| Oracle Corporation |
| SAP SE |
| Synopsys Inc. |
| Apprenda Inc. |
| Others |
Value Network & Pricing Analysis
Kubernetes and service mesh engineering expertise concentrates in technology hubs, inflating professional services costs and extending implementation timelines. Labor-cost differentials between certified platform engineers in Northern Virginia and generalist cloud administrators in secondary markets drive pricing-tier spreads across deployment complexity bands.
Pricing Analysis
Consumption-based procurement frameworks displace traditional enterprise licensing across platform architecture markets. Pricing stratifies across FedRAMP-authorized premium tiers, SOC 2 Type II standard configurations, and uncertified economy runtimes for non-regulated workloads. Cost compression in the economy tier intensifies because hyperscalers bundle managed Kubernetes into broader cloud commitments. Financial services firms exhibit the lowest price sensitivity due to operational resilience mandates, while education sector buyers prioritize cost efficiency over certification depth.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II attestation timelines extend six to twelve months, blocking revenue recognition for new platform deployments and gating vendor participation. Specialized silicon supply concentrates in Taiwan, South Korea, and the United States for AI inference workloads. GPU-enabled managed runtimes draw from constrained foundry capacity, NAND memory supply, and high-bandwidth interconnect components. Single-source vulnerability in advanced node semiconductor fabrication creates supply chain risk for platform providers offering accelerated computing tiers. Distribution runs through hyperscaler marketplaces, systems integrator channel partners, and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform architecture markets represent a late-cycle quality story as enterprise buyers consolidate vendor relationships around integrated platform suites. Procurement teams in United States federal agencies and German automotive manufacturers now prioritize single-vendor accountability for runtime, observability, and security layers.
For Market Incumbents: Deepen sovereign cloud partnerships in India, Brazil, and Saudi Arabia to preempt domestic infrastructure operator joint ventures. Expand Azure regional deployments and AWS GovCloud local zones to defend against emerging Kubernetes-native competitors. Invest in pre-certified EU AI Act compliance modules to capture algorithmic transparency mandates filtering vendor selection in France and Germany. For New Entrants and Emerging Players: The price-point gap between hyperscaler premium tiers and uncertified economy runtimes presents white space for specialized platform engineering consultancies. Target edge-native microservices deployments in Japanese manufacturing and South Korean telecommunications as the most penetrable segment. Pursue channel partnerships with domestic infrastructure operators rather than direct hyperscaler competition. For Investors and Strategic Acquirers: Hyperscalers with dedicated local zone networks are the most active acquirers in this space, consolidating API governance platform capabilities. Platform engineering consultancies with deep FedRAMP or EU AI Act certification expertise represent the highest-probability acquisition targets. Watch for service mesh certification delays blocking revenue recognition as an inflection indicator for vendor financial performance stress.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Joint ventures with domestic operators in India and Saudi Arabia satisfy data localization statutes. |
| Compliance Module Development | Pre-certified EU AI Act tooling captures algorithmic transparency mandates from French healthcare systems. |
| Edge-Native Runtime Expansion | Lightweight container deployments address latency specifications for South Korean 5G network virtualization. |
| Service Mesh Acquisition | Istio and Linkerd capabilities satisfy zero-trust networking requirements for United States banks. |
| Certification Acceleration Program | Compressed ISO 27001 timelines unblock revenue recognition for new platform deployments. |
Research Methodology
Multiple input streams — primary interviews with platform engineering directors, cloud procurement officers, and systems integrator architects, alongside secondary validation — were reconciled to construct market estimates. Hyperscaler capex disclosures, SEC 10-K infrastructure segment filings, and FedRAMP authorization databases anchored supply-side assessment. Bottom-up triangulation across deployment type, service model, and technology stack dimensions was cross-checked against top-down regulatory mandate impact analysis.
Data-stream reconciliation informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include deployment architecture, abstraction depth, and architectural pattern, supplemented by compliance posture as an industry-specific filter. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure modernization budget trajectories. Kubernetes penetration rates and microservices refactoring expenditure patterns served as platform architecture-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for container orchestration standardization would alter the outlook. Forecasts reflect assumptions regarding regulatory timeline adherence and hyperscaler local zone buildout pacing. A model refresh is warranted upon material change in FedRAMP authorization velocity or EU AI Act enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Digital Signage Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Online Dating Market