
 Japan Digital Twin Market | 2026-2036
Japan Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital Twin Market Insights
Subscription-based software-defined simulation layers is shifting how Japanese industrial vendors monetize digital twin deployments. Toshiba leverages its energy infrastructure heritage to anchor utility-scale twin implementations. Hitachi competes through its Lumada platform, extending IoT integration across factory floors. Siemens dominates the imported simulation stack, positioning its Xcelerator portfolio for cross-sector standardization.
A digital twin constitutes a virtual representation of a physical asset, system, or process maintained through real-time data synchronization via IoT sensors, simulation algorithms, and machine learning feedback loops. It enables predictive maintenance, operational optimization, and lifecycle management across industrial environments. Manufacturing applications lead adoption due to legacy automation density and kaizen-driven efficiency culture, while smart city deployments represent the fastest-growing segment as municipal utilities modernize grid and transit infrastructure. Cloud-based deployment captures expanding margin pools as Japanese enterprises migrate from on-premise legacy systems to hybrid architectures.
METI's industrial standards division, alongside JIS certification bodies and the Cybersecurity Agency of Japan, shapes compliance requirements for data interoperability and operational technology security. These frameworks mandate encrypted sensor-to-cloud pipelines and cross-platform data exchange protocols, directly influencing procurement specifications for digital twin vendors. Stakeholders must monitor evolving cybersecurity certifications and local content requirements as policy tightens around critical infrastructure digitization.
Market Dynamics
Japan's Society 5.0 digitization mandate is compressing procurement cycles for industrial simulation platforms as manufacturers face METI-mandated interoperability deadlines. This policy pressure is restructuring vendor selection criteria toward certified, cross-platform architectures.
Growth Catalysts
- Automotive Production Line Modernization:Japanese vehicle manufacturers deploy process twins to synchronize multi-supplier assembly networks. Kaizen culture accelerates iterative simulation deployment.
- METI's Industrial Data Interoperability Framework:The ministry's cross-platform data exchange protocols mandate encrypted sensor-to-cloud pipelines. Procurement specifications now require JIS-certified digital twin implementations.
- Smart Grid Infrastructure Rollout:Municipal utilities in the Kanto corridor adopt asset twins for predictive maintenance of aging transmission networks. Real-time load balancing drives simulation layer investments.
Market Restraints
- Legacy System Integration Costs:On-premise SCADA architectures from the 1990s require expensive middleware layers. Retrofit expenses consume 40-60% of initial deployment budgets.
- Domestic Cloud Provider Concentration:Three hyperscale operators control government-certified infrastructure. Limited vendor choice restricts negotiation leverage for enterprise buyers.
- Cybersecurity Certification Delays:The Cybersecurity Agency of Japan's OT security audits extend procurement timelines by 8-14 months. Certification backlogs stall critical infrastructure deployments.
Strategic Opportunities
- Kansai Manufacturing Belt Penetration:Osaka-Kyoto industrial clusters lag Tokyo in twin adoption. Machinery and precision tool sectors present greenfield deployment potential.
- Digital Twin-as-a-Service Models:Subscription-based simulation layers reduce upfront capital barriers. SMEs in metal fabrication and plastics access enterprise-grade analytics.
- 5G-Edge Convergence:Low-latency private networks enable real-time physics simulation at production line endpoints. Latency-sensitive quality control applications unlock new use cases.
Industry Challenges
- Mechatronics-Simulation Skill Gap:Japanese engineering education produces hardware specialists faster than systems modeling experts. Cross-disciplinary talent commands 35-50% wage premiums.
- Multi-Vendor Data Sovereignty Disputes:Industrial IoT sensor networks generate contested ownership claims. Contractual ambiguity over derivative analytics delays platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital Twin Market |
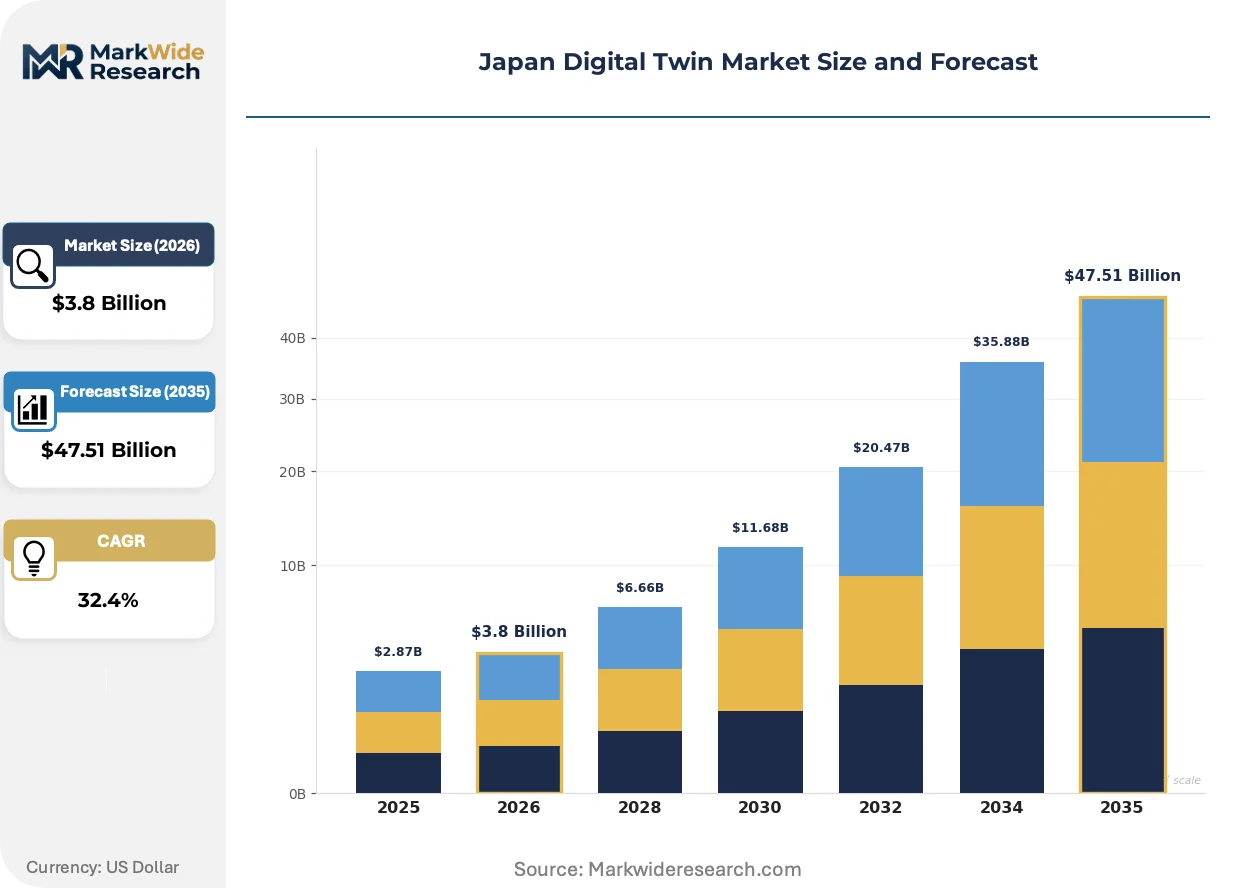
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $47.51 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Smart Cities, Healthcare, Automotive Technology: IoT, AI, Machine Learning, Simulation End User: Industrial Firms, Service Providers, Research Institutes, Government Bodies Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | ENEOS Corporation, Toshiba, Hitachi, Siemens, NEC, Mitsubishi Electric, Fujitsu, Dassault Systèmes, TOPPAN Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital Twin Market Trends and Innovations
Simulation architectures are fragmenting into composable microservices as Japanese manufacturers reject monolithic legacy platforms. This decomposition is enabling faster iteration cycles and supplier diversification.
Physics-based modeling software is modularizing into discrete functional blocks—thermal, mechanical, electrical—that integrate through standardized APIs. Automotive tier-1 suppliers in Nagoya and Yokohama adopt componentized simulation stacks to swap vendor modules without full platform replacement. This modularity is compressing vendor lock-in durations and expanding procurement options for multi-site manufacturers.
METI's 2023 amendment to the Cybersecurity Basic Act mandates encrypted operational technology pipelines for critical infrastructure digital twins. The regulation requires real-time anomaly detection layers and incident response protocols for utility-scale deployments. Power generation and water treatment operators in the Kanto region are restructuring vendor contracts to embed continuous compliance monitoring.
Japanese industrial buyers are consolidating simulation procurement under centralized IT governance functions rather than distributed engineering departments. Manufacturing conglomerates in Tokyo and Osaka are establishing enterprise-wide digital twin centers of excellence. This centralization is visible most acutely among precision equipment makers seeking to harmonize multi-facility data architectures.
Japan Digital Twin Market Segmentation
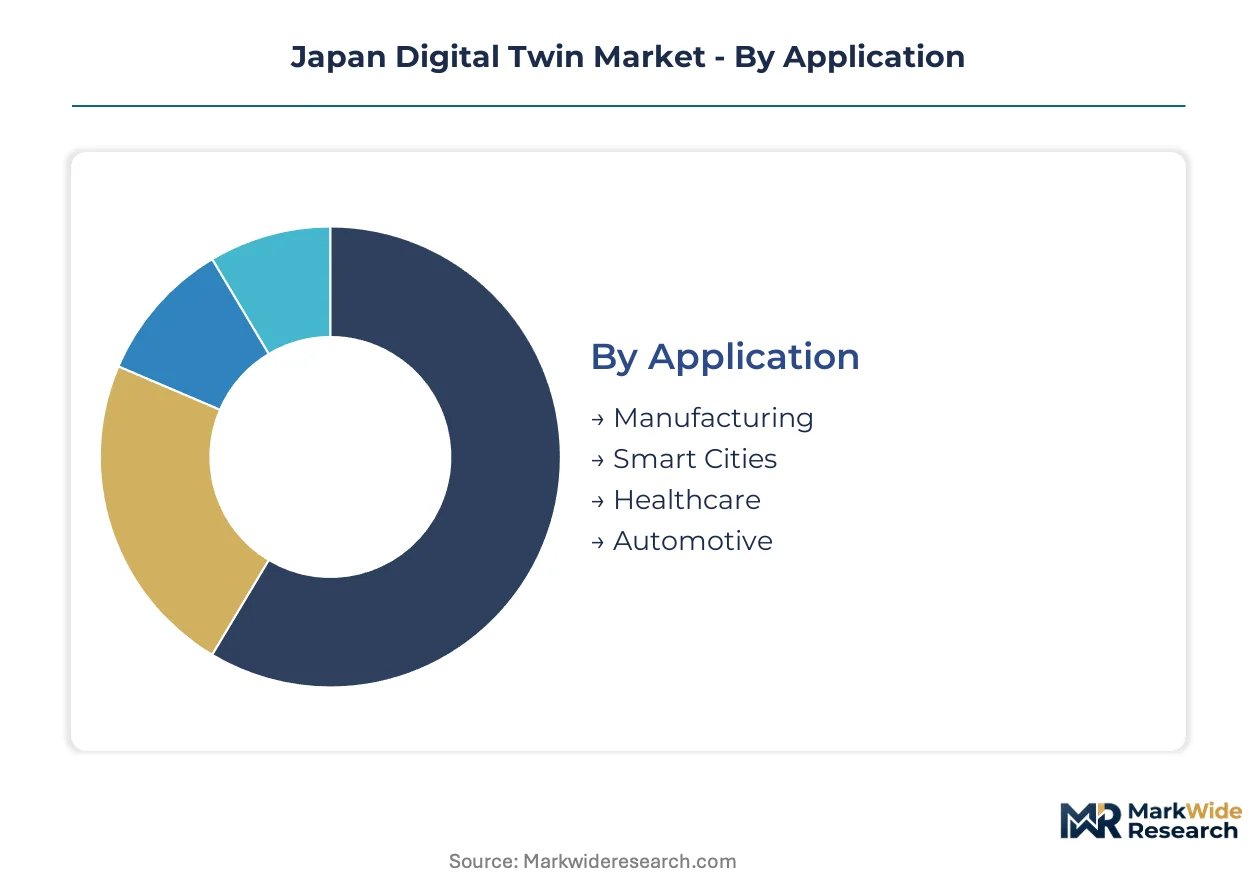
Segmentation in the Japan Digital Twin Market reveals distinct procurement patterns across industrial buyers. Application requirements and deployment constraints shape vendor selection more than technology specifications alone.
Application:
Manufacturing buyers prioritize real-time synchronization capabilities; smart city purchasers emphasize interoperability mandates.
- Manufacturing:Process twins integrate with legacy SCADA architectures to optimize production line throughput. Automotive tier-1 suppliers in Aichi and Kanagawa prefectures drive demand for multi-facility synchronization layers. Kaizen-driven iteration cycles compress deployment timelines.
- Smart Cities:Municipal infrastructure twins coordinate grid, transit, and water systems through centralized data platforms. Tokyo Metropolitan Government procurement specifications mandate METI-certified interoperability protocols. Real-time load balancing applications accelerate adoption.
- Healthcare:Patient-specific organ modeling and hospital workflow optimization drive niche deployments.
- Automotive:Vehicle lifecycle twins span design, production, and predictive maintenance phases.
Volume sits with Manufacturing; growth tilts toward Smart Cities.
Technology:
Technology selection separates buyers by in-house data science capability and legacy system complexity.
- IoT:Sensor-to-cloud pipelines form the data foundation for all twin implementations. Industrial firms in the Kanto corridor deploy hardened edge sensors for factory floor telemetry. METI's encrypted pipeline mandates raise procurement barriers.
- AI:Machine learning inference layers enable predictive maintenance and anomaly detection. Cloud-native manufacturers leverage pre-trained models; on-premise buyers face integration complexity.
- Machine Learning:Feedback loops refine simulation accuracy through operational data ingestion.
- Simulation:Physics-based modeling software modularizes into discrete functional blocks for thermal, mechanical, and electrical analysis.
Adoption concentrates in IoT infrastructure; AI layers are expanding most quickly.
End User:
End user type determines budget authority and compliance requirements.
- Industrial Firms:Manufacturing conglomerates consolidate procurement under centralized IT governance. Precision equipment makers in Tokyo and Osaka establish enterprise-wide centers of excellence. Multi-facility harmonization drives architecture standardization.
- Service Providers:Systems integrators and consultancies deliver twin implementations to mid-market clients. Subscription-based models reduce upfront capital barriers for metal fabrication and plastics SMEs.
- Research Institutes:Academic and national laboratory users advance simulation methodologies.
- Government Bodies:Municipal utilities and infrastructure agencies mandate JIS-certified implementations.
Procurement volume clusters with Industrial Firms; Service Providers are gaining share fastest.
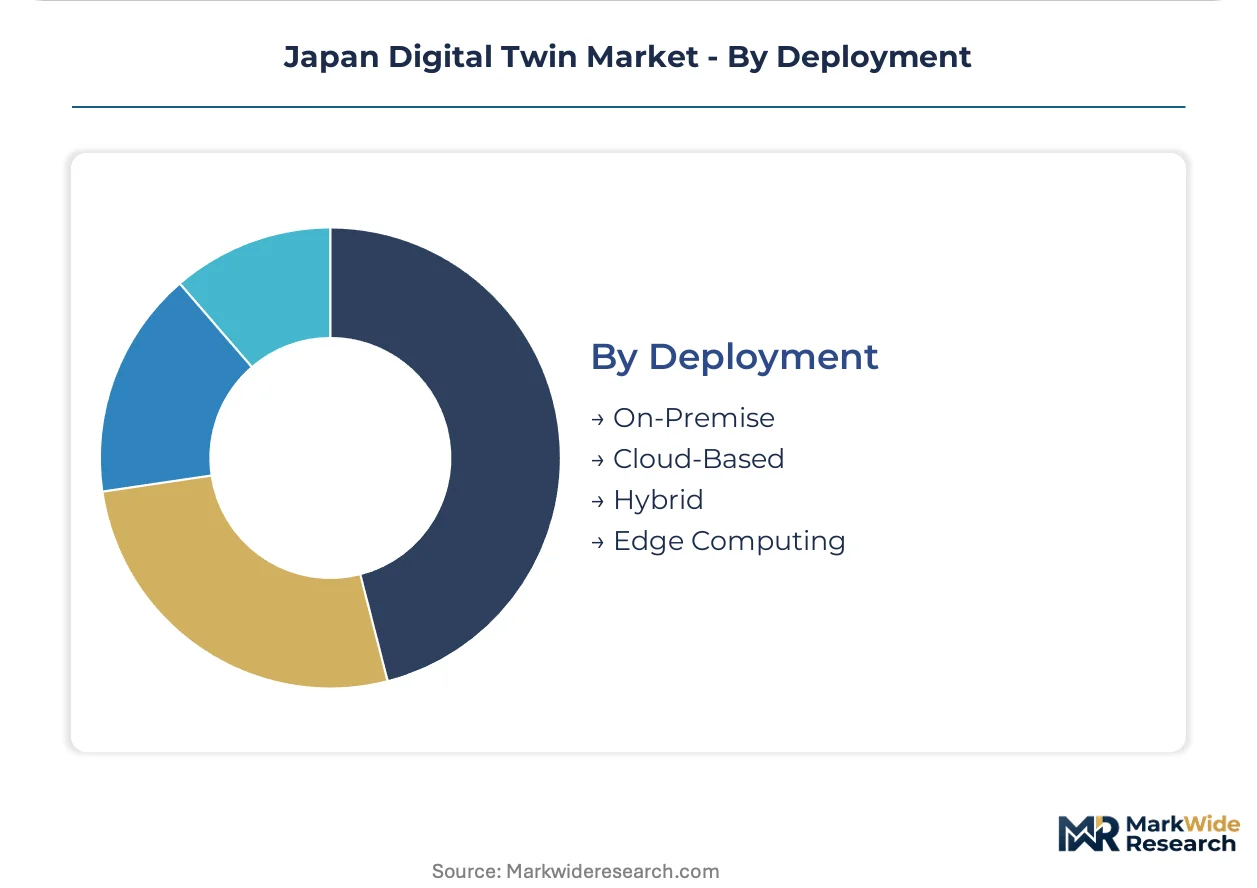
Deployment:
Deployment architecture reflects data sovereignty requirements and latency sensitivity.
- Cloud-Based:Hybrid architectures capture expanding margin pools as enterprises migrate from legacy systems. Three government-certified hyperscale operators control infrastructure certification, limiting vendor negotiation leverage.
- On-Premise:Air-gapped installations persist in defense and critical infrastructure sectors. Retrofit expenses consume substantial portions of deployment budgets.
- Hybrid:Split architectures balance sensitive on-premise processing with cloud analytics.
- Edge Computing:Low-latency private networks enable real-time physics simulation at production line endpoints. 5G convergence unlocks quality control applications.
Cloud-Based deployments dominate new procurement; Edge Computing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's digital twin production concentrates in industrial conglomerate headquarters while consumption spreads across regional manufacturing belts. Kanto dominates deployment volume; Kansai and Chubu present expansion frontiers. Regional policy variations and infrastructure maturity create distinct procurement environments.
Kanto/Tokyo
Automotive tier-1 suppliers and precision equipment makers drive twin adoption for multi-facility synchronization. METI's interoperability mandates accelerate encrypted pipeline deployments across manufacturing corridors. Tokyo Metropolitan Government procurement specifications for smart city infrastructure create standardized demand templates.
Kansai/Osaka
Machinery and metal fabrication sectors lag Tokyo in adoption but present greenfield deployment potential. Osaka Prefecture's industrial digitization subsidies reduce upfront capital barriers for SMEs. The Osaka-Kyoto corridor's precision tool manufacturers establish pilot centers of excellence.
Chubu/Nagoya
Toyota's supplier network anchors process twin deployments for assembly line optimization. Aichi Prefecture's automotive density generates concentrated demand for real-time physics simulation. Nagoya-based industrial IoT integrators serve mid-market metalworking clients.
Kyushu
Semiconductor and electronics manufacturing clusters drive edge computing deployments for latency-sensitive quality control. Fukuoka Prefecture's 5G infrastructure investments enable private network pilots. Local machinery makers access subscription-based simulation layers through regional service providers.
Hokkaido
Agricultural and food processing applications represent niche digital twin use cases. Sapporo municipal utilities pilot grid infrastructure twins for remote load balancing. Limited industrial density constrains vendor presence compared to southern prefectures.
Japan Digital Twin Market Competitive Landscape
Capital-heavy industrial conglomerates compete with asset-light software specialists for digital twin platform dominance. The vendor structure tiers between integrated hardware-software providers and pure-play simulation developers. Three archetypes occupy distinct positions: diversified electronics manufacturers leveraging IoT heritage, imported industrial software stacks targeting cross-sector standardization, and domestic systems integrators delivering localized implementation services. Competitive moves center on strategic partnerships for interoperability certification and subscription model transitions to capture recurring revenue streams.
Within the diversified electronics tier, Toshiba, Hitachi, and Mitsubishi Electric exemplify capital-intensive players converting industrial infrastructure heritage into utility-scale twin implementations. These conglomerates anchor their positioning through captive customer relationships in energy and manufacturing verticals. Siemens represents the imported software stack archetype, competing through platform standardization across automotive and industrial machinery segments. Domestic systems integrators occupy the implementation layer, with NEC and Fujitsu delivering JIS-certified deployments to government and enterprise clients. TOPPAN Holdings occupies a specialized position in visualization and display technologies supporting twin interfaces.
| Leading Market Players |
|---|
| ENEOS Corporation |
| Toshiba |
| Hitachi |
| Siemens |
| NEC |
| Mitsubishi Electric |
| Fujitsu |
| Dassault Systèmes |
| TOPPAN Holdings |
| Others |
Pricing and Supply Chain Analysis
Mechatronics-simulation specialists concentrated in the Tokyo-Osaka corridor command wage premiums that compress margins in economy-tier deployments and widen spreads between certified premium implementations and basic sensor-to-cloud packages. Labor-cost differentials between hardware-focused engineers and systems modeling experts force vendors to stratify pricing across skill-intensive customization levels.
Pricing Analysis
Margin tightening in economy-tier subscriptions reflects compressed differentiation as domestic cloud providers standardize base-layer offerings. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified implementations with continuous compliance monitoring from uncertified pilot deployments. Price differentiation rests on cybersecurity certification grade and after-sales service bundling. SMEs in metal fabrication exhibit highest price sensitivity; municipal utilities in the Kanto corridor demonstrate lowest sensitivity due to mandated interoperability spending.
Supply Chain Analysis
Industrial edge sensor supply rests on Japanese and Taiwanese component producers with concentrated semiconductor fabrication in South Korea. Key inputs include hardened telemetry sensors, physics simulation engines, and encrypted pipeline middleware. Single-source vulnerability in government-certified hyperscale infrastructure creates procurement bottlenecks. Distribution runs through systems integrators delivering JIS-certified implementations to enterprise and government clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
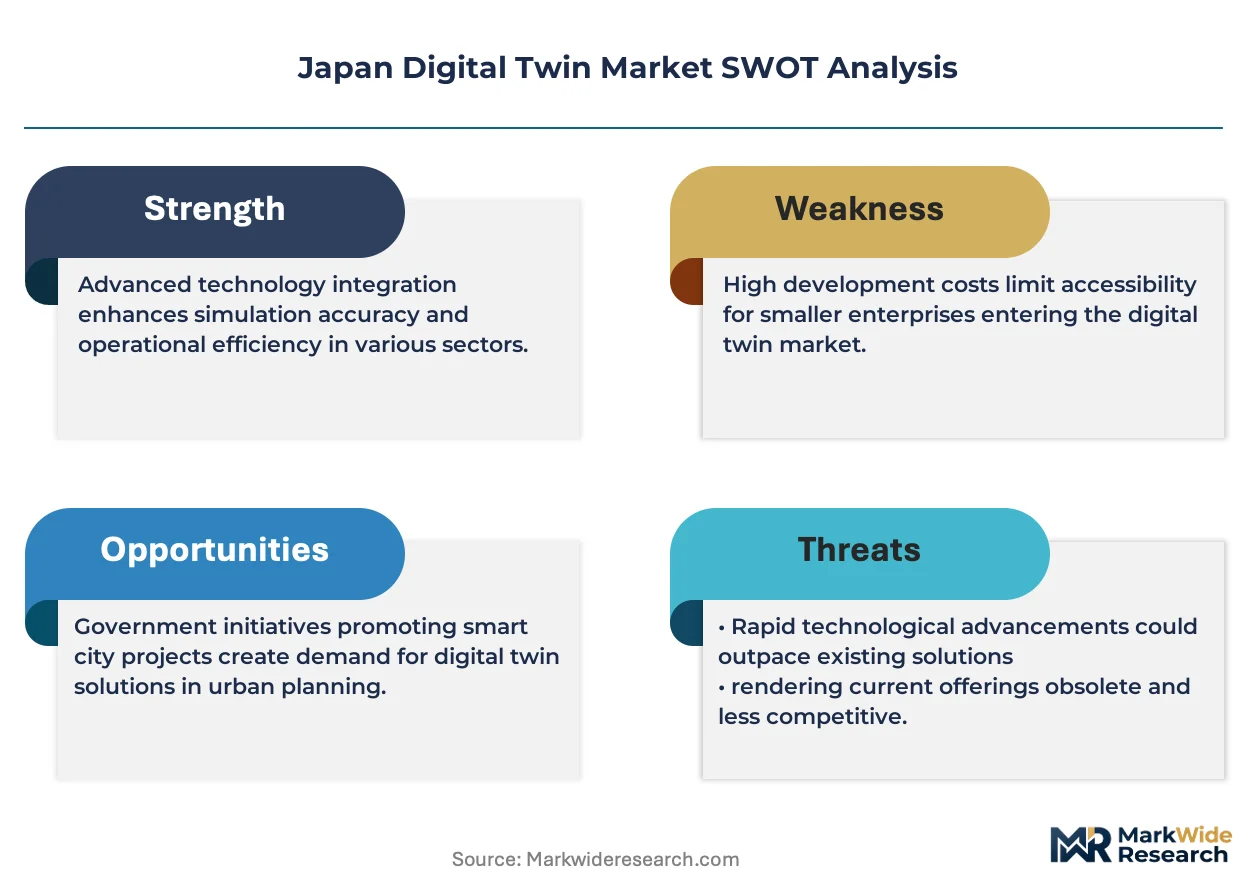
METI's encrypted pipeline mandates have erected a compliance moat that favors incumbent vendors with established certification pathways and burdens unproven entrants with 8-14 month audit timelines.
For Market Incumbents: Anticipate margin pressure from modular simulation microservices by anchoring utility-scale implementations through captive energy infrastructure relationships. Deepen backward integration into edge sensor manufacturing to reduce exposure to semiconductor supply constraints. Prioritize continuous compliance monitoring contracts that embed recurring revenue streams. For New Entrants and Emerging Players: METI's 2023 Cybersecurity Basic Act amendment in Japan opens a window for specialized anomaly detection layer providers to attach to incumbent platform deployments. Target the Kansai manufacturing belt's machinery and precision tool sectors where greenfield adoption lags Tokyo penetration. Pursue Digital Twin-as-a-Service subscription models that reduce upfront capital barriers for SME metal fabricators. For Investors and Strategic Acquirers: Re-rating potential sits with domestic systems integrators possessing JIS certification expertise given accelerating municipal smart grid procurement. Long-term viability favors vendors with hybrid cloud-on-premise architectures that satisfy data sovereignty requirements across industrial and government segments. Watch cybersecurity certification backlog resolution as an inflection indicator for deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Modular microservices architectures enable faster iteration cycles for Nagoya automotive suppliers. |
| Strategic Partnership | Interoperability certification alliances with METI accelerate procurement approval timelines. |
| Acquisition of Specialist Firm | Systems modeling talent scarcity in Japan drives consolidation of cross-disciplinary engineering teams. |
| Geographic Expansion | Kansai belt penetration captures machinery sector greenfield deployments outside Tokyo saturation. |
| Product Launch | 5G-edge convergence offerings unlock latency-sensitive quality control applications for Kyushu semiconductor clusters. |
Research Methodology
Multi-period observation of encrypted pipeline deployment timelines, certification backlog durations, and municipal procurement cycles anchored the trend analysis, supplemented by interviews with plant engineers at automotive tier-1 suppliers, IT procurement officers at precision equipment makers, platform engineers at domestic hyperscale operators, and integration specialists at systems integrators. Secondary validation drew from METI policy bulletins, JIS certification registry updates, Cybersecurity Agency of Japan audit disclosures, and municipal utility procurement specifications. Bottom-up facility-level deployment tracking and top-down ministry spending estimates provided triangulation.
Segment-weighting across application type, deployment architecture, technology layer, and end-user governance structure shaped the analytical framework throughout the forecast period. CAGRs derived from fitted adoption curves incorporating Society 5.0 policy compliance deadlines and cloud migration trajectories. Industry-specific inputs included SCADA retrofit cost ratios and 5G private network rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for edge-native simulation architectures would alter the outlook. Forecasts reflect assumptions regarding METI interoperability mandate enforcement consistency and hyperscale certification velocity. A small set of triggers—cybersecurity audit backlog resolution, Kansai subsidy program expansion, and mechatronics-education curriculum reform—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Workspace As a Service Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Email Marketing Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
US Digital Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Product Data Management Market
Digital Solutions
Enterprise Imaging Solutions Market