
 Global Intelligent Document Processing Market | 2026-2036
Global Intelligent Document Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Document Processing Market Foresight
GDPR is pivoting data residency and consent management into mandatory cost layers for IDP vendors serving European enterprises. UiPath leverages robotic process automation integration to anchor its platform within Fortune 500 shared service centers. ABBYY competes on computer vision specialization for complex multilingual document layouts. Microsoft extends cloud-native AI services through Azure AI Document Intelligence, dominating mid-market deployments.
Intelligent Document Processing combines optical character recognition, natural language processing, and machine learning to extract structured data from unstructured documents such as scanned invoices, contracts, and handwritten forms. The technology processes documents at throughput rates exceeding thousands of pages per hour while maintaining field-level accuracy thresholds above ninety-five percent for typed text. Workflow Automation and Natural Language Processing segments are capturing disproportionate R&D investment as enterprises demand end-to-end straight-through processing rather than point extraction tools. Cloud deployment is displacing on-premises installations among mid-market buyers seeking elastic capacity during quarterly close peaks and tax filing surges.
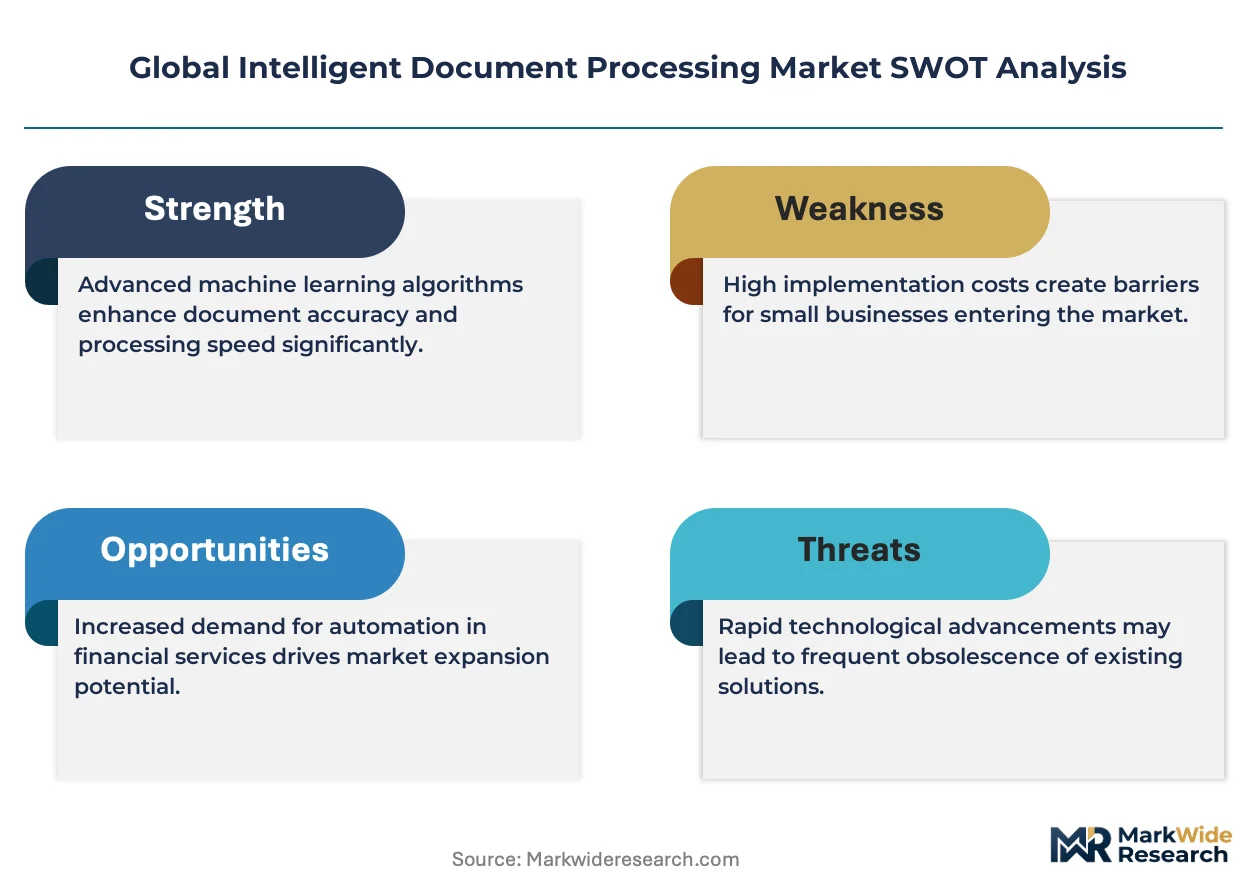
FDA 21 CFR Part 11 in the United States mandates electronic signature and audit trail capabilities for document systems serving pharmaceutical quality assurance, while India's BIS pushes data localization standards affecting cross-border SaaS architectures. The EU AI Act's risk classification framework is forcing IDP vendors to reengineer high-stakes applications like credit decisioning and medical claims review for transparency and human oversight. Stakeholders must monitor how divergent national AI governance regimes fragment product roadmaps and inflate compliance engineering headcount.
Market Dynamics
The EU AI Act's risk classification framework is compressing vendor roadmaps as enterprises demand transparent extraction pipelines for high-stakes credit and medical decisions. Compliance engineering headcount is displacing pure R&D investment across the competitive set.
Growth Catalysts
- Pharmaceutical Quality Mandates:FDA 21 CFR Part 11 mandates electronic signatures and immutable audit trails for document systems serving drug quality assurance. US pharmaceutical manufacturers are replacing legacy paper batch records with validated IDP workflows.
- India's Data Localization Push:BIS standards require domestic data residency for financial services document processing. SaaS vendors are rearchitecting multi-tenant platforms to capture Indian banking modernization budgets.
- Straight-Through Processing Demand:Insurance carriers require end-to-end automation from document intake to claims payment. Natural language processing engines are eliminating manual handoffs in property and casualty underwriting.
Market Restraints
- GPU Compute Cost Volatility:Training and inference for large document models depends on NVIDIA data center chip availability. Cloud service providers are passing through silicon scarcity premiums to enterprise buyers.
- Optical Character Recognition Saturation:Typed text extraction accuracy has plateaued above ninety-five percent, compressing differentiation among point-solution vendors. Handwritten and low-quality scan recognition remains technically constrained.
- Cross-Border Regulatory Friction:Divergent national AI governance regimes fragment product architectures. Engineering teams must maintain separate model versions for EU transparency requirements versus US performance optimization.
Strategic Opportunities
- German Mittelstand Automation:Mid-sized industrial enterprises in Baden-Württemberg and Bavaria operate paper-heavy procurement and quality workflows. Native German-language document layouts create defensible specialization for regional vendors.
- Large Language Model Convergence:Generative AI is converging with traditional extraction pipelines to enable zero-shot document understanding. Early deployments in contract analysis are eliminating template-based training requirements.
- EU Green Deal Documentation:Corporate Sustainability Reporting Directive mandates granular emissions and supply chain disclosure. IDP platforms are capturing ESG data extraction workloads from sustainability consulting practices.
Industry Challenges
- Machine Learning Operations Talent Scarcity:Production-grade document model deployment requires rare combinations of computer vision expertise and regulated industry domain knowledge. Compensation inflation in Bangalore and Berlin is compressing vendor margins.
- Legacy Enterprise Resource Planning Integration:SAP and Oracle systems from the 1990s lack modern API architectures. Custom connector development consumes forty to sixty percent of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Document Processing Market |
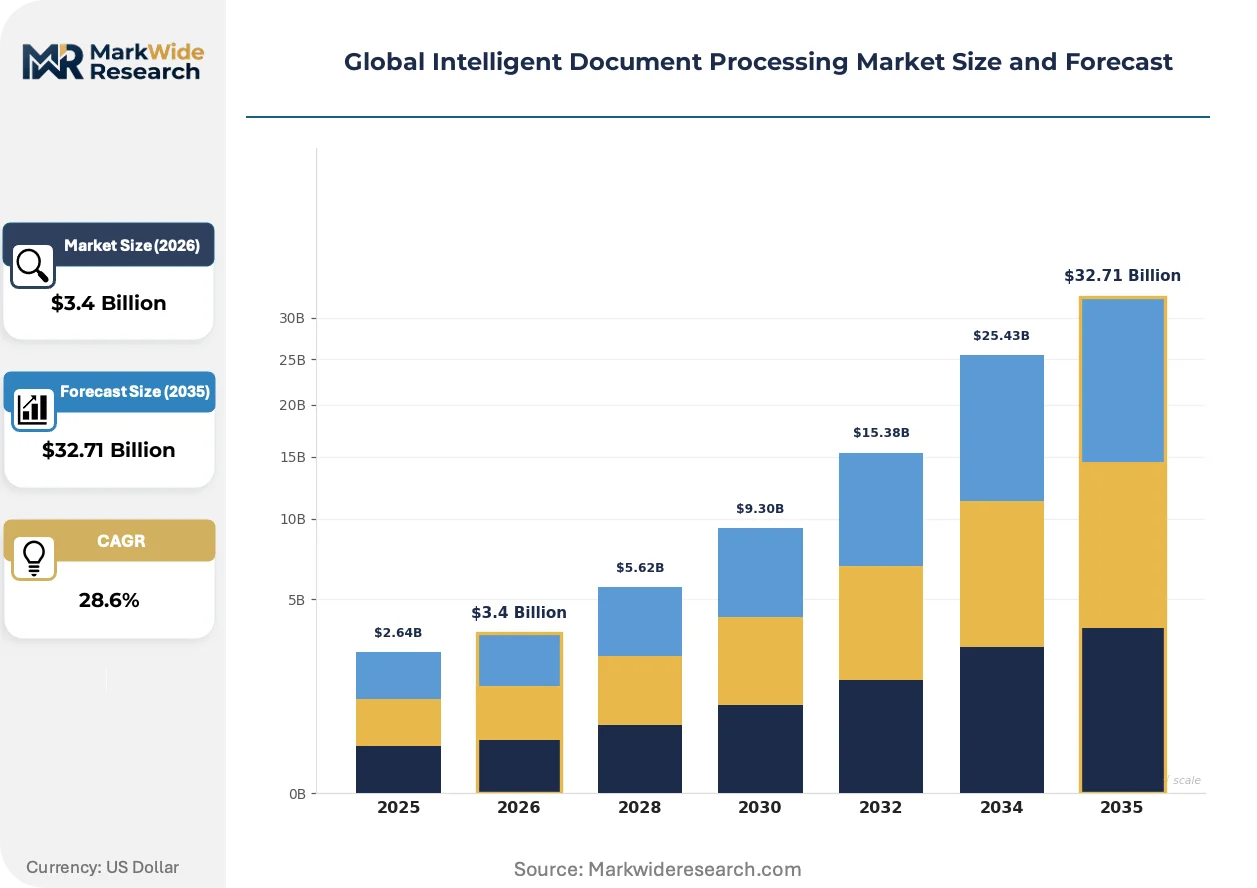
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $32.71 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
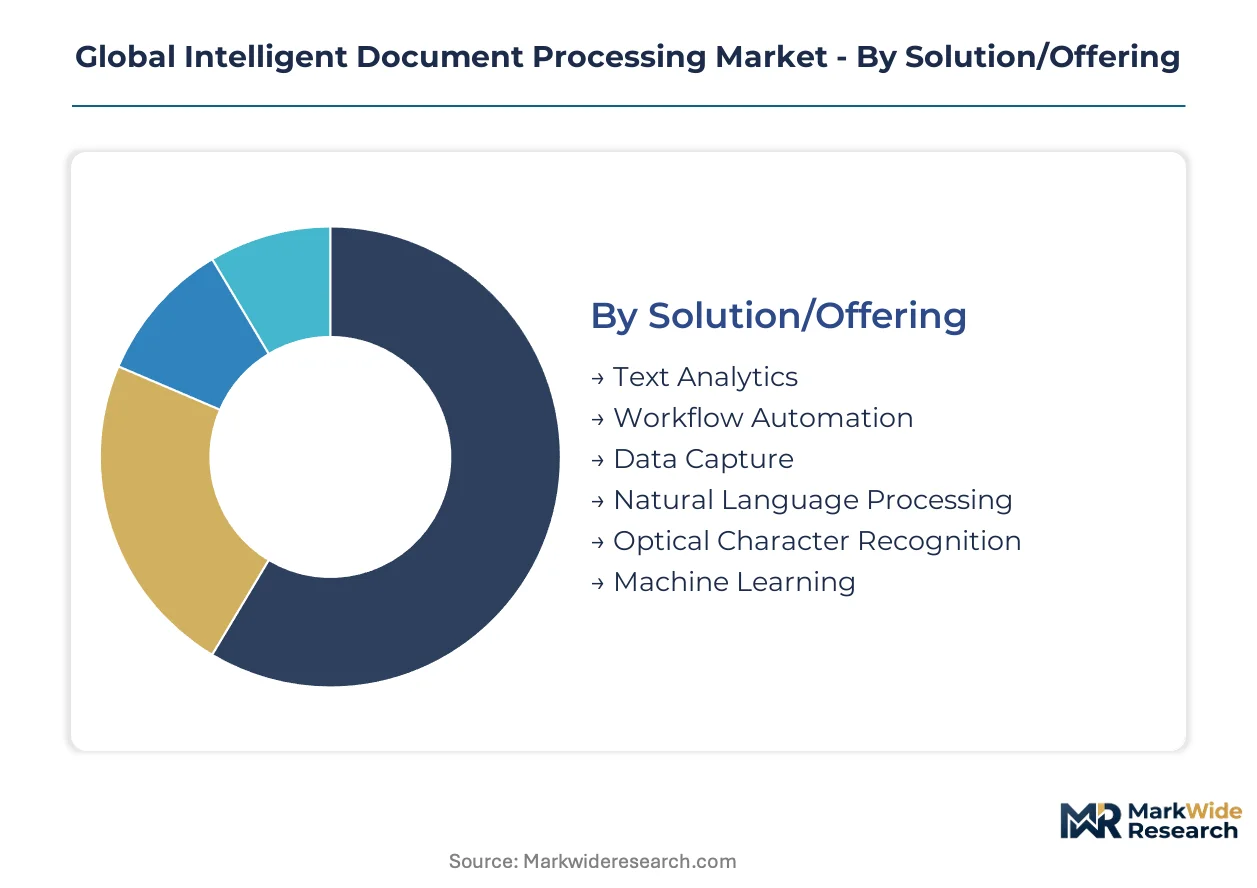
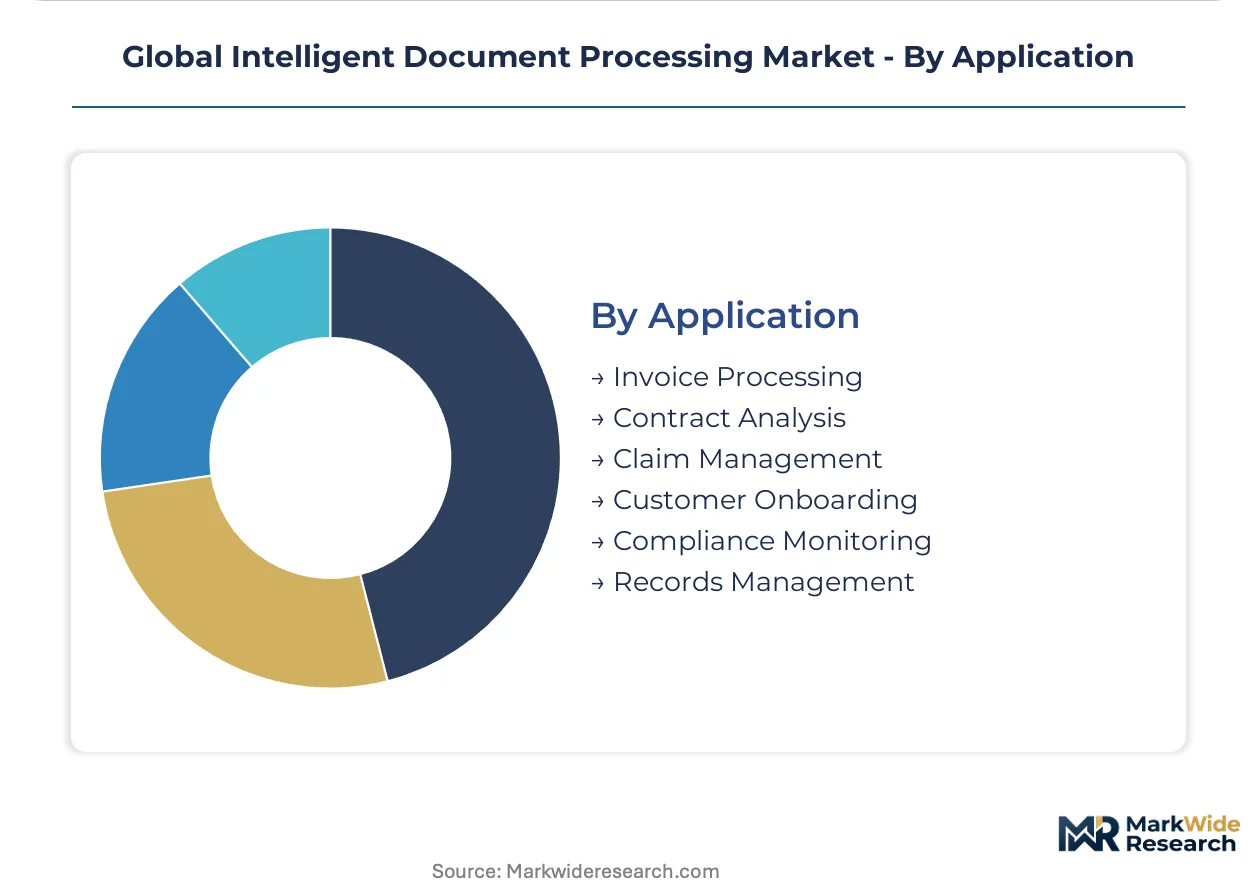
| Segmentation | Solution/Offering: Text Analytics, Workflow Automation, Data Capture, Natural Language Processing, Optical Character Recognition, Machine Learning Deployment: Cloud, On-Premises, Hybrid, Edge Computing End User Industry Vertical: BFSI, Government Agencies, Legal Firms, Manufacturing Companies, Telecom Providers, Education Institutions Application: Invoice Processing, Contract Analysis, Claim Management, Customer Onboarding, Compliance Monitoring, Records Management |
| Companies Covered | IBM Corporation, ABBYY, UiPath, Automation Anywhere, OpenText Corporation, Appian, Microsoft, AntWorks, Hyperscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Document Processing Market Shifts & Advancements
Foundation models trained on billions of document pages are compressing the traditional machine learning pipeline from months to days. Vendors are racing to embed these capabilities without sacrificing the auditability that regulated industries require.
Multimodal AI architectures are converging with robotic process automation to enable context-aware document handling. Banking shared service centers in Charlotte and Singapore are piloting systems that read, interpret, and act on loan files without human intervention. The technology is collapsing the boundary between extraction and downstream workflow execution.
REACH and RoHS documentation requirements in the European Union are forcing chemical and electronics manufacturers to automate supplier certificate verification. ECHA substance database integration is becoming a standard procurement gate. German automotive suppliers are prioritizing IDP vendors with pre-built regulatory content packs.
Enterprise buyers are unbundling implementation services from software subscriptions and awarding separate contracts to system integrators. Mid-market manufacturers in the US Midwest are bypassing vendor professional services for regional consulting firms with industry-specific expertise. This channel fragmentation is visible most acutely in medical device quality management deployments.
Global Intelligent Document Processing Market Segmentation
Intelligent Document Processing vendors architect product portfolios around extraction accuracy thresholds, regulatory auditability requirements, and integration depth with legacy enterprise systems. Segmentation choices directly determine addressable market scope and implementation complexity for platform providers.
Solution/Offering:
Standardized API modules compete against bespoke enterprise deployments across this category, with customization premiums widening as regulated industries demand field-level explainability.
- Workflow Automation:Orchestrates multi-step document journeys from intake through approval routing, with pre-built connectors for SAP and Oracle systems. Insurance carriers in Charlotte and Singapore deploy these engines for claims straight-through processing, driven by pressure to collapse manual handoff delays.
- Natural Language Processing:Extracts semantic meaning from contracts, correspondence, and unstructured text blocks using transformer architectures. Legal departments at German automotive suppliers prioritize these tools for multilingual clause analysis, constrained by EU AI Act transparency mandates for high-stakes decisions.
- Text Analytics:Surfaces patterns and sentiment across document corpora for compliance surveillance.
- Data Capture:Ingests documents from scanners, email, and mobile capture channels.
- Optical Character Recognition:Converts scanned images to machine-readable text with accuracy plateaus above ninety-five percent for typed content.
- Machine Learning:Underlies adaptive field extraction models that improve with document volume exposure.
Leading the category by volume: Workflow Automation. Expanding most quickly: Natural Language Processing.
Deployment:
Elastic capacity demands during quarterly financial closes reshape infrastructure preferences across customer tiers, with data residency requirements fragmenting architecture choices.
- Cloud:Delivers metered processing capacity through hyperscaler infrastructure, eliminating capital expenditure for variable document volumes. Mid-market manufacturers in the US Midwest favor this model for tax filing surge absorption, though GPU compute cost volatility squeezes operating margins.
- Hybrid:Combines on-premises extraction engines with cloud-based model training and analytics layers. Indian banks under BIS data localization mandates deploy these architectures to retain sensitive KYC documents domestically while accessing global AI improvements.
- On-Premises:Maintains complete infrastructure control for air-gapped security environments.
- Edge Computing:Processes documents at distributed locations with limited connectivity.
Dominating transaction volume: Cloud. Steepest expansion trajectory: Hybrid.
End User Industry Vertical:
Regulatory documentation burdens vary dramatically across verticals, with pharmaceutical and financial services carrying the heaviest audit trail obligations.
- BFSI:Encompasses retail banking, insurance underwriting, and capital markets compliance workflows. US pharmaceutical manufacturers replacing paper batch records under FDA 21 CFR Part 11 drive validated system demand, while property and casualty carriers automate claims adjudication.
- Government Agencies:Processes citizen-facing forms, benefits applications, and regulatory filings at scale. Indian state governments modernizing land record digitization create substantial data capture procurement pipelines.
- Legal Firms:Deploys contract analysis and discovery document review.
- Manufacturing Companies:Automates supplier certificate verification and quality documentation.
- Telecom Providers:Manages customer identity verification and service agreements.
- Education Institutions:Handles admissions processing and transcript evaluation.
Highest procurement intensity: BFSI. Gaining share fastest: Government Agencies.
Application:
Template-based extraction yields to zero-shot document understanding as foundation models mature, reshaping implementation economics.
- Invoice Processing:Extracts line-item details, tax calculations, and payment terms from supplier documents across formats. German Mittelstand enterprises in Baden-Württemberg prioritize these deployments for procurement automation, confronting persistent handwritten and low-quality scan recognition constraints.
- Contract Analysis:Identifies obligations, risks, and renewal clauses across agreement portfolios. Banking legal departments leverage generative AI convergence to eliminate template-based training requirements, accelerating deployment timelines from months to days.
- Claim Management:Automates insurance loss documentation and settlement workflows.
- Customer Onboarding:Verifies identity documents and risk profiles for new account establishment.
- Compliance Monitoring:Surveils document flows for regulatory violations and policy deviations.
- Records Management:Classifies, retains, and retrieves documents per retention schedules.
Widest deployment base: Invoice Processing. Climbing the fastest: Contract Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore, Singapore, and Charlotte concentrate IDP vendor delivery centers and enterprise procurement budgets. Tax incentives for software exports and R&D credits in these jurisdictions accelerate platform development while compliance mandates in Frankfurt and Mumbai reshape data architecture requirements.
United States
Pharmaceutical manufacturers in Research Triangle Park and Boston replace paper batch records with validated IDP workflows under FDA 21 CFR Part 11 mandates. Banking shared service centers in Charlotte pilot multimodal AI systems for straight-through loan processing. The SEC's climate disclosure rules drive ESG document automation procurement from sustainability consulting practices.
Germany
Baden-Württemberg's Mittelstand industrial enterprises automate paper-heavy procurement workflows with native German-language document specialists. The EU AI Act's risk classification framework forces credit decisioning system vendors to reengineer for transparency and human oversight. ECHA substance database integration requirements dominate automotive supplier certificate verification procurement.
India
BIS data localization standards require domestic data residency for financial services document processing. SaaS vendors rearchitect multi-tenant platforms to capture Mumbai and Bangalore banking modernization budgets. State governments in Telangana and Karnataka accelerate land record digitization pipelines.
Singapore
Monetary Authority of Singapore guidelines on AI governance shape regional procurement standards for banking automation. Insurance carriers in the Marina Bay financial district deploy claims straight-through processing systems. The city-state's trade documentation hub status drives shipping and logistics document automation demand.
United Kingdom
FCA operational resilience requirements pressure London financial institutions to automate document-intensive compliance workflows. The Information Commissioner's Office enforces GDPR-aligned consent management for IDP platforms serving European enterprises. Legal departments in the City prioritize contract analysis tools for multilingual clause review.
Global Intelligent Document Processing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction accuracy and regulatory auditability dimensions. Cloud hyperscalers leverage infrastructure scale to capture mid-market deployments while computer vision specialists defend premium positioning in complex multilingual layouts. Three archetypes dominate: platform-integrated automation suites, standalone extraction engines, and industry-vertical bundles. M&A activity concentrates on compliance engineering capabilities and pre-built regulatory content packs.
Within the platform-integrated tier, UiPath and Microsoft exemplify divergent scale strategies. UiPath anchors Fortune 500 shared service centers through robotic process automation convergence. Microsoft extends Azure AI Document Intelligence through metered cloud capacity. ABBYY occupies a specialized position in computer vision for complex document layouts. These three represent the competitive tension between horizontal platform breadth and vertical extraction depth.
| Leading Market Players |
|---|
| IBM Corporation |
| ABBYY |
| UiPath |
| Automation Anywhere |
| OpenText Corporation |
| Appian |
| Microsoft |
| AntWorks |
| Hyperscience |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-validated enterprise suites and commodity API offerings manifests in both subscription economics and cloud infrastructure sourcing strategies. Premium tiers command three-to-five-year contractual lock-in with dedicated GPU clusters, while standard offerings ride hyperscaler spot capacity with elastic surge pricing.
Pricing Analysis
Short lead-time deployments for quarterly financial close surges carry twenty-to-forty percent premiums over baseline SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by audit trail granularity and human-in-the-loop oversight requirements. Cost compression in the economy tier intensifies because mid-market manufacturers negotiate aggressively for per-page transactional rates. Indian banking modernization budgets show highest price sensitivity; pharmaceutical quality assurance buyers demonstrate least.
Supply Chain Analysis
Regional distribution centers in Bangalore, Singapore, and Charlotte anchor hub-and-spoke delivery patterns for implementation services and model training infrastructure. NVIDIA data center silicon feeds from Taiwan and South Korea; hyperscaler cloud capacity draws from domestic data centers in India, Germany, and the United States under BIS and GDPR mandates. Single-source vulnerability in GPU compute creates procurement bottlenecks during training pipeline scaling. Distribution runs through system integrator partnerships rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU compute scarcity props pricing power for vendors with secured NVIDIA allocation, constraining capacity expansion for competitors without forward silicon commitments.
For Market Incumbents: To counter generative AI convergence from cloud hyperscalers, anchor Fortune 500 relationships through backward integration into robotic process automation stacks and pre-built regulatory content packs for FDA and EU AI Act compliance. Prioritize compliance engineering headcount expansion over pure R&D to defend auditability positioning. For New Entrants and Emerging Players: German Mittelstand procurement automation represents the most penetrable buyer archetype given native German-language specialization gaps among incumbent platforms. Capture Baden-Württemberg industrial clusters through regional system integrator partnerships and pre-configured supplier certificate verification workflows aligned with ECHA substance database requirements. For Investors and Strategic Acquirers: Re-rating potential sits with computer vision specialists given EU AI Act transparency mandates accelerating consolidation toward explainable extraction pipelines. Long-term viability favors vendors with hybrid deployment architectures serving Indian data localization requirements. Watch BIS enforcement intensity in Mumbai and Bangalore as inflection indicator for SaaS rearchitecture spend.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Engineering Expansion | EU AI Act risk classification mandates human oversight capabilities in credit decisioning pipelines. |
| Hybrid Cloud Architecture | BIS data localization standards require Indian banks to retain KYC documents domestically while accessing global AI. |
| Regulatory Content Pack Development | FDA 21 CFR Part 11 validation accelerates pharmaceutical manufacturer replacement of paper batch records. |
| System Integrator Channel Partnership | Mid-market US Midwest manufacturers bypass vendor professional services for regional consulting expertise. |
| Foundation Model Integration | Generative AI convergence eliminates template-based training requirements in banking contract analysis deployments. |
Research Methodology
Independent corroboration across CTOs at Fortune 500 shared service centers, compliance officers at pharmaceutical manufacturers, and procurement leads at German automotive suppliers underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 11 guidance documents, EU AI Act regulatory texts, BIS data localization circulars, and hyperscaler capex disclosures. Bottom-up segment sizing triangulates against top-down market boundary estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window. Segmentation dimensions span deployment model, organization size, vertical regulatory intensity, integration complexity with SAP and Oracle systems, and regional adoption pattern. CAGRs derive from logistic diffusion curves fitted to technology penetration benchmarks, with explicit modeling of GPU compute cost volatility and compliance engineering headcount inflation.
Revisions become necessary when NVIDIA supply allocation shifts, EU AI Act enforcement intensity exceeds baseline assumptions, or Indian BIS localization mandates expand to additional sectors. Forecasts reflect documented assumptions about foundation model convergence timelines and regulatory fragmentation persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Revenue Management Software Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Bahrain ICT Market