
 Customer-To-Customer (C2C) Community Market | 2026-2036
Customer-To-Customer (C2C) Community Market Size, Share, and Industry Trends Forecast 2026-2036
Customer-To-Customer (C2C) Community Market Outlook
Platform-grade trust verification is bifurcating the C2C community landscape into high-integrity marketplaces and unmoderated exchange forums. Facebook leverages its identity-graph infrastructure to sustain seller credibility across peer-to-peer transactions. Eventbrite anchors event-based C2C commerce through integrated ticketing and community discovery tools. Meetup competes on localized interest clustering, dominating hobbyist-to-hobbyist service exchanges in urban density corridors.
The Customer-To-Customer (C2C) Community denotes decentralized exchange networks where individuals transact goods, services, or digital assets through platform-mediated interfaces without institutional intermediaries. These ecosystems rely on reputation algorithms, escrow-integrated payment rails, and real-time messaging protocols to reduce counterparty risk and enable scalable trust at low coordination cost. The product type dimension shows second-hand items and digital products capturing the fastest expansion, as circular economy participation and creator monetization tools mature; handmade goods retain premium margin pools where craft authentication and provenance tracking add defendable value. Service type segmentation reveals peer-to-peer rentals and skill bartering outpacing auction formats, reflecting users' preference for recurring utility over speculative price discovery.
Regulatory oversight from the EU Digital Services Act, the US FTC's commercial surveillance rulemaking, and India's forthcoming digital competition framework are collectively elevating platform accountability for fraud mediation and data portability. These compliance burdens favor operators with in-house legal infrastructure and modular API architectures that adapt to jurisdictional variance. Stakeholders must monitor emerging interoperability mandates that could dismantle proprietary network effects and redistribute transaction liquidity across federated C2C protocols.
Market Dynamics
Platform-mediated trust infrastructure is compressing coordination costs for peer-to-peer exchanges while regulatory fragmentation across jurisdictions forces operators to maintain modular compliance architectures. The EU Digital Services Act and India's PLI scheme for digital infrastructure are creating divergent operational templates that favor capitalized incumbents with in-house legal capacity.
Growth Catalysts
- Mobile-first commerce participation:Tier-two city users in India are accelerating platform adoption through smartphone-native interfaces, with the PLI scheme subsidizing digital infrastructure buildout.
- EU Digital Services Act compliance frameworks:Mandatory trust verification protocols are bifurcating marketplaces into high-integrity tiers, creating premium positioning for compliant operators.
- Circular economy participation:Second-hand item exchanges are expanding as environmental accountability tools mature, with provenance tracking adding defendable value to resale transactions.
Market Restraints
- Payment security standard fragmentation:Escrow-integrated rails face interoperability friction across national banking regulators, elevating transaction failure rates in cross-border exchanges.
- Platform liability concentration:Fraud mediation obligations under the EU Digital Services Act concentrate compliance burdens on marketplace operators with limited legal infrastructure.
- Identity verification cost inflation:Real-name authentication systems require ongoing investment in biometric and document-check pipelines, compressing margins for mid-scale platforms.
Strategic Opportunities
- Skill bartering protocol expansion:Hobbyist-to-hobbyist service exchanges in urban density corridors remain underpenetrated, with localized interest clustering enabling recurring utility models.
- Federated C2C protocol development:Emerging interoperability mandates could redistribute transaction liquidity across decentralized networks, dismantling proprietary network effects.
- Creator monetization tooling:Digital product marketplaces for micro-entrepreneurs show white space as authentication and provenance tracking mature for intangible assets.
Industry Challenges
- Reputation algorithm calibration:Balancing fraud detection sensitivity against false-positive rates requires specialized data science talent scarce outside major technology hubs.
- Jurisdictional variance adaptation:Modular API architectures must accommodate divergent national frameworks without fragmenting user experience or elevating maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer-To-Customer (C2C) Community Market |
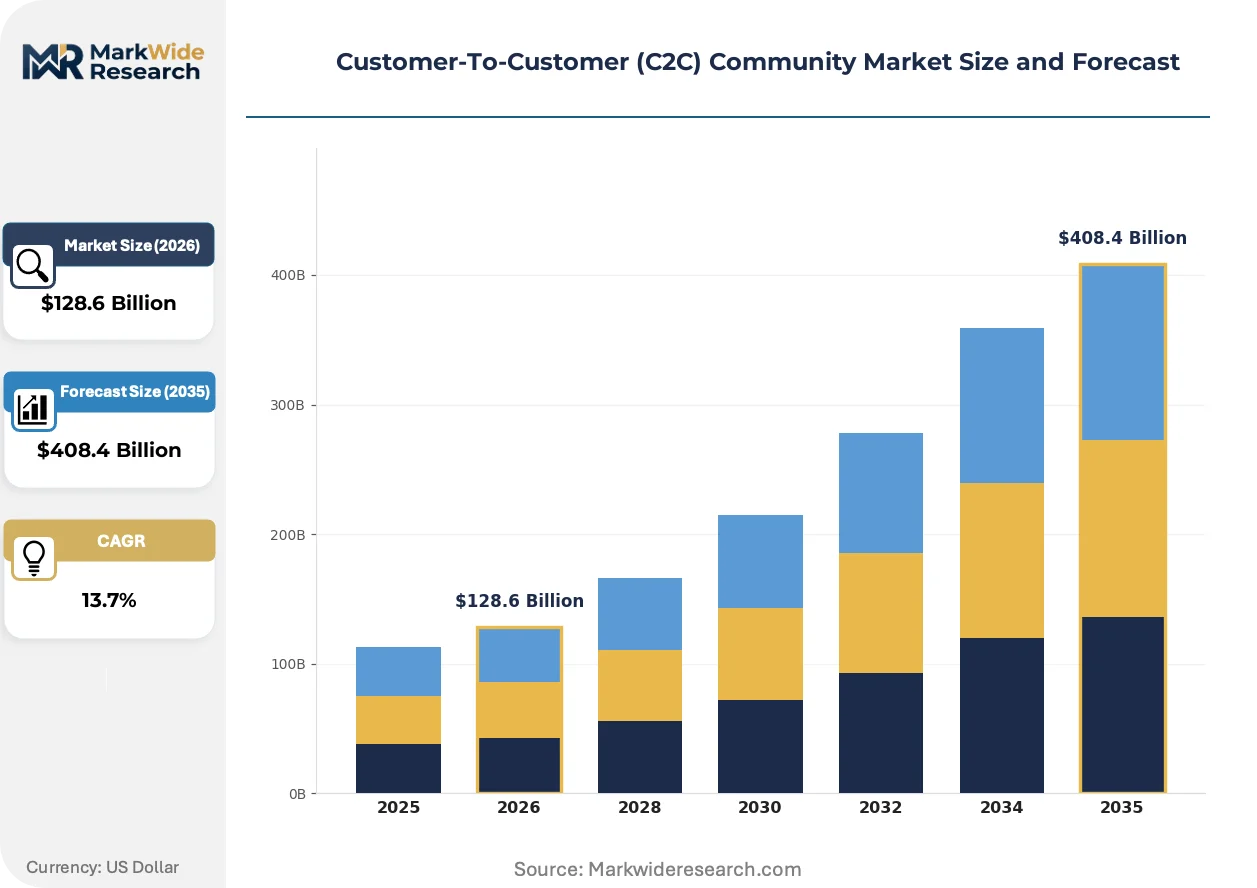
| Market Size in 2026 | $128.6 Billion |
| Market Size in 2035 | $408.4 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Marketplace, Bartering, Auction Product Type: Handmade Goods, Second-hand Items, Digital Products, Collectibles Platform Feature: Rating System, Secure Payment, Chat Functionality, User Profiles Customer Type: Individuals, Small Businesses, Craftspeople, Hobbyists |
| Companies Covered | Facebook, Bevy, Eventbrite, LinkedIn, Meetup, NationBuilder, Peatix, Localist, DownToMeet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer-To-Customer (C2C) Community Market Strategic Shifts
Decentralized identity verification and real-time messaging protocols are actively compressing the trust-formation timeline for peer-to-peer transactions. Three developments are restructuring how C2C platforms capture and retain transaction liquidity.
Blockchain-based escrow systems are miniaturizing the settlement infrastructure for peer-to-peer exchanges. Micro-entrepreneurs and hobbyist sellers are adopting these rails fastest, drawn by reduced chargeback exposure and faster fund release. The technology is miniaturizing the role of traditional banking intermediaries in low-value, high-frequency transactions.
India's forthcoming digital competition framework is mandating data portability for marketplace users. This regulatory pressure forces operators to architect exportable reputation histories and transaction records, eroding proprietary lock-in. Micro-entrepreneurs on domestic platforms face the most disruption as interoperability requirements accelerate.
After-sales service unbundling is fragmenting buyer expectations for peer-to-peer transactions. Auction formats are losing ground to fixed-price listings with integrated dispute resolution, particularly in second-hand goods categories. Germany and France show the strongest migration toward utility-predictable exchange models over speculative price discovery.
Customer-To-Customer (C2C) Community Market Segmentation
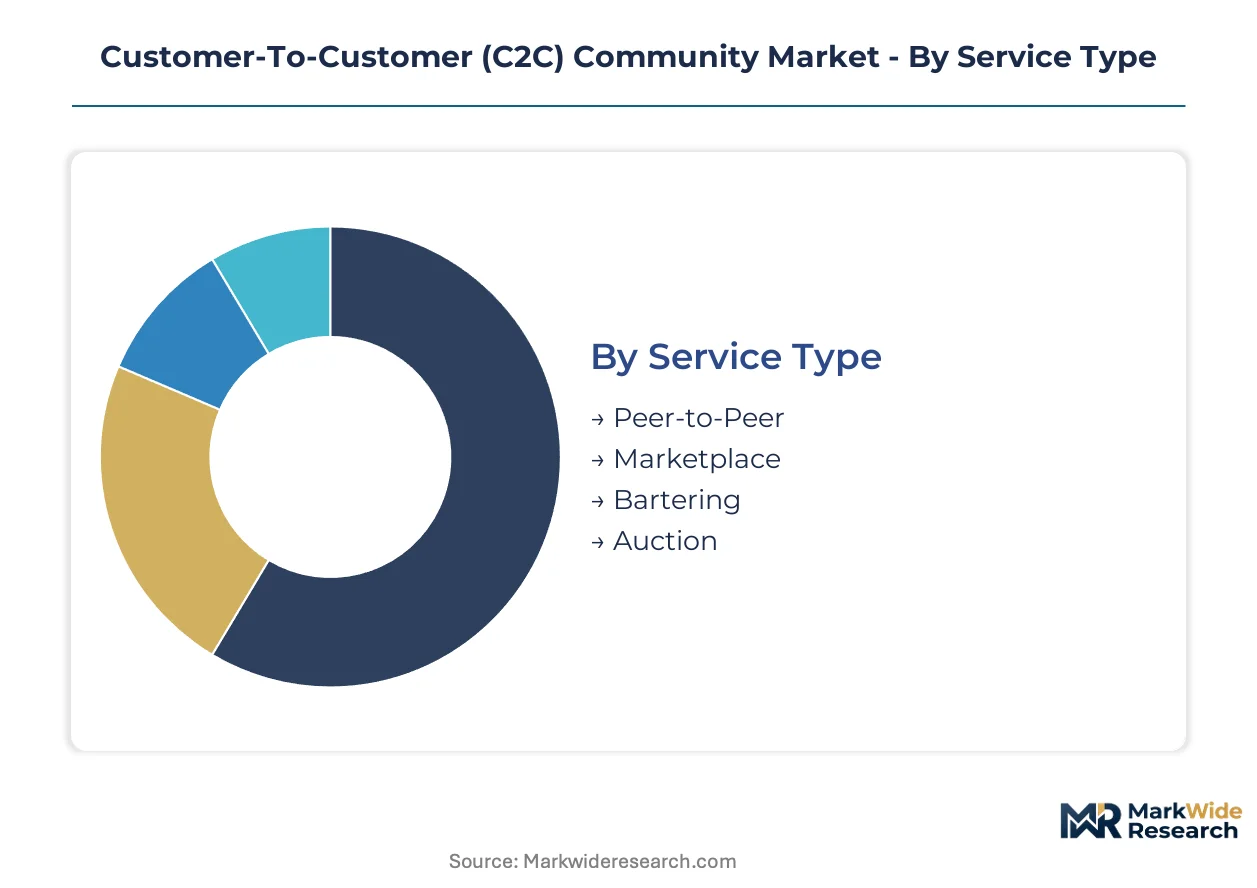
Segmentation in the C2C Community Market reveals how platform operators allocate engineering resources across trust infrastructure, payment rails, and discovery algorithms. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Service Type:
Margin pools concentrate in recurring transaction formats that reduce customer acquisition costs through network effects rather than paid marketing.
- Peer-to-Peer:Direct bilateral exchanges between verified users, typically mediated by escrow-integrated payment rails. Demand clusters among hobbyist sellers in India's tier-two cities, where the PLI scheme for digital infrastructure reduces friction for first-time platform entrants.
- Marketplace:Centralized listing and discovery infrastructure with algorithmic matching. Small businesses in Germany and France are migrating toward fixed-price utility models over speculative formats, drawn by integrated dispute resolution and predictable transaction timelines.
- Bartering:Non-monetary skill and goods exchanges with reputation-weighted matching.
- Auction:Price-discovery formats with time-limited competitive bidding.
The dominant share belongs to Marketplace, while Peer-to-Peer is closing the gap fastest.
Product Type:
Application intensity varies sharply across physical and intangible goods, with digital products requiring minimal logistics infrastructure.
- Second-hand Items:Circular economy participation is expanding resale volumes as environmental accountability tools mature. EU Digital Services Act compliance frameworks are bifurcating marketplaces into high-integrity tiers, creating premium positioning for operators with provenance tracking capabilities.
- Digital Products:Creator monetization tools for intangible assets including templates, courses, and licensed content. Micro-entrepreneurs across India are adopting these formats fastest, drawn by zero inventory carrying costs and instant global distribution.
- Handmade Goods:Craft authentication and provenance tracking add defendable value in premium margin pools.
- Collectibles:Authenticated rare items with blockchain-verified ownership histories.
Second-hand Items command the largest transaction volume, though Digital Products are expanding most quickly.
Platform Feature:
Cost tier differentiation separates capitalized incumbents with in-house infrastructure from lean operators relying on third-party APIs.
- Secure Payment:Escrow-integrated rails with fraud mediation obligations. Payment security standard fragmentation across national banking regulators elevates transaction failure rates in cross-border exchanges, compressing margins for mid-scale platforms without dedicated compliance teams.
- Rating System:Algorithmic reputation scoring with fraud detection sensitivity calibration. Specialized data science talent for balancing false-positive rates concentrates in major technology hubs, creating capability scarcity outside Bangalore, Berlin, and San Francisco corridors.
- Chat Functionality:Real-time messaging protocols for negotiation and dispute resolution.
- User Profiles:Identity verification pipelines with biometric and document-check components.
Secure Payment represents the largest infrastructure investment category, while Rating Systems are climbing the fastest as operators differentiate on trust verification.
Customer Type:
Maturity levels diverge between casual participants and commercial sellers with structured inventory management needs.
- Individuals:Casual sellers with episodic listing behavior and minimal platform tooling requirements. India's rising mobile-first commerce participation is accelerating adoption among first-time users in tier-two cities, where smartphone-native interfaces reduce onboarding friction.
- Craftspeople:Skilled producers with authenticated output and recurring production schedules. Urban density corridors in France and Germany support localized interest clustering for hobbyist-to-hobbyist service exchanges with recurring utility models.
- Small Businesses:Commercial sellers with inventory tracking and tax reporting obligations.
- Hobbyists:Enthusiast communities with social discovery priorities and skill-bartering preferences.
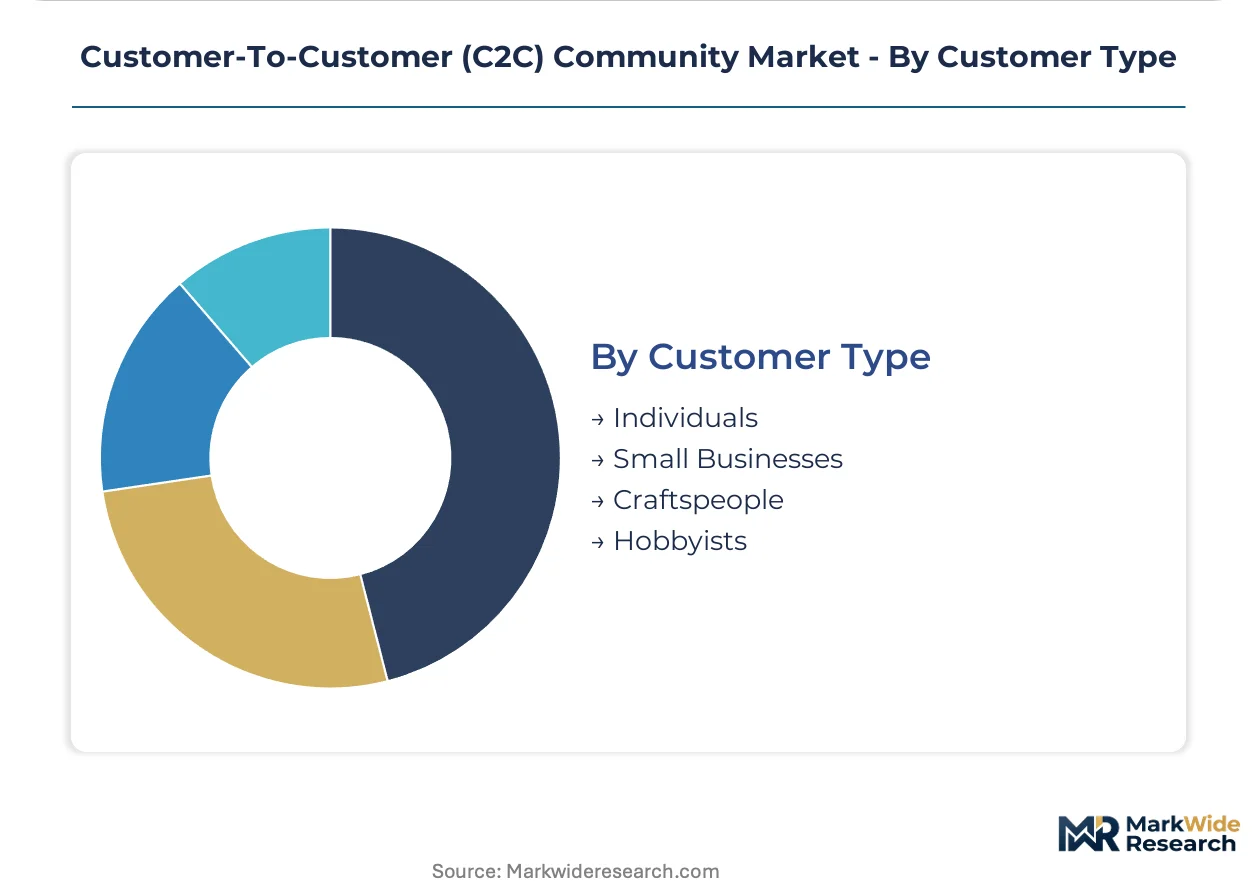
Individuals constitute the broadest user base, though Craftspeople are gaining share fastest as authentication tooling matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure investment concentrates in jurisdictions with mature digital payment rails and enforceable liability frameworks. India, Germany, the United States, France, and the United Kingdom each present distinct regulatory templates that reshape operator economics and user adoption curves.
India
Tier-two city users are driving mobile-first commerce participation through smartphone-native interfaces. The PLI scheme for digital infrastructure subsidizes connectivity buildout in secondary urban centers. Bangalore and Hyderabad anchor technical talent clusters where platform operators localize trust verification algorithms for vernacular language markets.
Germany
Small businesses are migrating from auction formats toward fixed-price utility models with integrated dispute resolution. The EU Digital Services Act imposes fraud mediation obligations that favor capitalized incumbents with dedicated compliance infrastructure. Berlin and Munich host density corridors where hobbyist-to-hobbyist service exchanges cluster around authenticated craft marketplaces.
United States
Micro-entrepreneurs are adopting creator monetization tools for digital products at accelerating rates. The FTC's commercial surveillance rulemaking elevates data portability requirements that erode proprietary network effects. San Francisco and New York concentrate specialized data science talent for reputation algorithm calibration.
France
Environmental accountability tools are expanding circular economy participation in second-hand goods exchanges. GDPR-derived consent frameworks and the EU AI Act intersect to constrain automated decision-making in seller verification pipelines. Paris anchors premium margin pools where craft authentication and provenance tracking add defendable value.
United Kingdom
Peer-to-peer rental formats are outpacing speculative auction structures as users prioritize recurring utility. The Digital Markets, Competition and Consumers Bill is mandating interoperability standards that could redistribute transaction liquidity. London's fintech corridor supplies escrow-integrated payment rails with reduced chargeback exposure for cross-border exchanges.
Customer-To-Customer (C2C) Community Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the C2C community landscape. Capitalized incumbents with in-house legal infrastructure dominate compliance-heavy jurisdictions, while lean operators relying on third-party APIs capture price-sensitive segments. Two strategic archetypes have emerged: identity-graph platforms leveraging social verification at scale, and event-centric operators integrating ticketing with community discovery. Dominant competitive moves include modular API architectures for jurisdictional adaptation and federated protocol development to preempt interoperability mandates.
Within the identity-graph tier, Facebook and LinkedIn occupy positions where social verification infrastructure reduces counterparty risk without dedicated marketplace investment. Eventbrite exemplifies the integrated ticketing archetype, anchoring event-based C2C commerce through combined discovery and transaction tooling. Meetup sits within the localized interest clustering segment, representing operators who monetize hobbyist-to-hobbyist density in urban corridors rather than transaction volume directly.
| Leading Market Players |
|---|
| Bevy |
| Eventbrite |
| Meetup |
| NationBuilder |
| Peatix |
| Localist |
| DownToMeet |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with escrow-integrated payment providers lock in both supply access and price visibility for C2C marketplace operators navigating EU Digital Services Act compliance costs and India's PLI scheme infrastructure subsidies. These contractual structures tether transaction liquidity to verified identity pipelines while compressing margin exposure for mid-scale platforms.
Pricing Analysis
The EU Digital Services Act dictates the pricing tier structure across C2C community platforms by mandating fraud mediation infrastructure that separates high-integrity marketplaces from unmoderated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differential investment in biometric verification and real-time messaging protocols. Cost compression in the economy tier is intensifying because identity verification cost inflation demands ongoing document-check pipeline investment. Hobbyist sellers in India's tier-two cities show the highest price sensitivity, while craft authentication-enabled marketplaces in France command premium positioning with minimal elasticity.
Supply Chain Analysis
Biometric API provider concentration in Bangalore and data center infrastructure clustering in Hyderabad create chokepoints that tether platform reliability to Indian digital infrastructure buildout. Payment rail dependencies draw from Mumbai fintech corridors and Singapore cross-border settlement hubs, with escrow-integrated systems resting on modular compliance architectures. Single-source vulnerability concentrates in tier-two city connectivity where PLI scheme subsidies have not yet reached full deployment. Distribution runs through smartphone-native interfaces that compress onboarding friction for first-time micro-entrepreneurs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federated C2C protocols and decentralized identity verification networks threaten to dismantle proprietary network effects that incumbent platforms have built through reputation algorithm lock-in. Incumbents must defend against substitute infrastructure that redistributes transaction liquidity across interoperable marketplaces.
For Market Incumbents: Consolidate trust verification infrastructure through backward integration into biometric authentication pipelines, reducing third-party API dependency that regulatory fragmentation exploits. Acquire modular compliance architecture capabilities in Bangalore and Berlin talent corridors to preempt EU Digital Services Act liability concentration. Channel control over escrow-integrated payment rails defends against fintech entrants capturing transaction economics.
For New Entrants and Emerging Players: Differentiate on localized interest clustering for hobbyist-to-hobbyist service exchanges in urban density corridors where Meetup's density model remains underextended. Target tier-two Indian cities where mobile-first commerce participation accelerates fastest and incumbent platform presence thins. A community discovery-first go-to-market angle, anchored through event-based C2C commerce tooling, bypasses capital requirements for proprietary payment infrastructure.
For Investors and Strategic Acquirers: Platforms with in-house legal infrastructure and exportable reputation histories represent the most defensible acquisition archetype as India's digital competition framework mandates data portability. Long-term viability hinges on operators who architected federated protocol compatibility before interoperability mandates crystallized. Watch for EU AI Act implementation timelines as the inflection indicator that accelerates compliance cost divergence between capitalized incumbents and lean operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular API Architecture Development | Enables jurisdictional adaptation to EU Digital Services Act and India's PLI scheme without fragmenting user experience. |
| Biometric Verification Pipeline Integration | Reduces identity verification cost inflation for mid-scale platforms competing with Facebook's identity-graph infrastructure. |
| Federated Protocol Partnership | Preempts interoperability mandates from India's digital competition framework that erode proprietary network effects. |
| Creator Monetization Tooling Launch | Captures white space in digital product marketplaces as micro-entrepreneurs adopt zero-inventory formats fastest. |
| Localized Interest Clustering Expansion | Monetizes hobbyist-to-hobbyist density in urban corridors where skill bartering protocols remain underpenetrated. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with platform engineering leads, trust verification product managers, regulatory compliance officers, and micro-entrepreneur sellers across India, Germany, and the United States; and secondary validation through EU Digital Services Act implementation guidance, India's PLI scheme policy documents, SEC filings from marketplace operators, and mobile commerce adoption statistics from national telecom regulators. Bottom-up transaction volume estimates and top-down addressable market sizing were triangulated to anchor segmentation splits.
Across the analysis window, the forecasting framework modeled service type segmentation between peer-to-peer and marketplace formats, product type splits across second-hand items and digital products, and platform feature intensity tiers for secure payment versus rating system investment. CAGRs were derived from adoption curve analysis of mobile-first commerce participation in tier-two Indian cities and circular economy participation rates in EU member states. Escrow-integrated payment rail penetration and real-time messaging protocol deployment served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme infrastructure subsidies and stable EU Digital Services Act enforcement timelines would require recalibration. Forecasts reflect assumptions regarding biometric verification cost trajectories and interoperability mandate implementation pace. Revision becomes warranted when federated protocol adoption crosses thresholds that materially redistribute transaction liquidity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Global Metadata Management Tools Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Master Data Management Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market