
 Online on-Demand Home Services Market | 2026-2036
Online on-Demand Home Services Market Size, Share, and Industry Trends Forecast 2026-2036
Online on-Demand Home Services Market Intelligence
The capital-intensity divergence between asset-light marketplace operators and vertically integrated service networks is bifurcating competitive returns. Taskrabbit leverages its contractor marketplace model to sustain low fixed-cost expansion across North American metros. Urban Company anchors its position through in-house training academies and standardized service protocols in Indian cities.
Online on-demand home services coordinate localized labor supply with consumer demand through algorithmic matching platforms, typically integrating GPS dispatch, real-time availability dashboards, and escrow payment rails to reduce transaction friction between dispersed households and independent technicians. Mobile apps dominate consumer acquisition channels, while subscription pricing models capture recurring revenue streams from property managers seeking predictable maintenance budgets. Fixed pricing structures within electrical and plumbing segments attract first-time users who distrust hourly-rate uncertainty.
GDPR compliance costs weigh on European platform data architectures, while US state labor departments scrutinize contractor classification tests that determine benefit obligations. India's Consumer Protection (E-Commerce) Rules impose liability frameworks on aggregators for service failures. Stakeholders must monitor regulatory divergence across jurisdictions where platform liability standards remain unsettled.
Market Dynamics
Algorithmic labor-matching platforms are restructuring competitive economics by collapsing coordination costs between dispersed households and independent technicians, forcing incumbents to choose between asset-light marketplace models and capital-intensive vertical integration.
Growth Catalysts
- GDPR compliance frameworks:European data governance mandates are accelerating investment in encrypted payment rails and consent-management architectures that reduce fraud liability for cross-border service platforms.
- Urban millennial household formation:Dense metro clusters in India and Southeast Asia are generating sufficient technician density to sustain sub-30-minute dispatch windows for plumbing and electrical requests.
- Gig-worker classification tests:US state labor department rulings are clarifying benefit obligations, reducing legal uncertainty that previously constrained platform expansion into regulated trades.
Market Restraints
- Input cost volatility:Fluctuating fuel and vehicle maintenance expenses for technician fleets compress already-thin per-job margins in transportation-dependent categories like appliance repair.
- Supply concentration risk:India's Consumer Protection (E-Commerce) Rules impose direct liability on aggregators for service failures, elevating compliance costs disproportionately for foreign entrants.
- Technical limitation:Real-time GPS dispatch systems struggle with indoor location accuracy in high-rise residential towers, degrading arrival-time predictions and customer satisfaction scores.
Strategic Opportunities
- Subscription pricing models:Property management firms in Germany and France are adopting fixed-fee maintenance contracts that lock in recurring revenue streams and reduce customer acquisition costs.
- Regulatory tailwind:India's PLI scheme for digital infrastructure is subsidizing cloud-native platform development, lowering capital barriers for domestic service aggregators.
- Technology convergence:Integration of IoT-enabled home devices with predictive maintenance algorithms is creating preemptive service dispatch before homeowner-initiated requests.
Industry Challenges
- Certified technician scarcity:Licensed electricians and plumbers require months of credential verification, creating onboarding bottlenecks that throttle geographic expansion velocity.
- Escrow payment integration complexity:Legacy banking systems in emerging markets resist API connectivity, forcing platforms to absorb higher transaction fees or accept settlement delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online on-Demand Home Services Market |
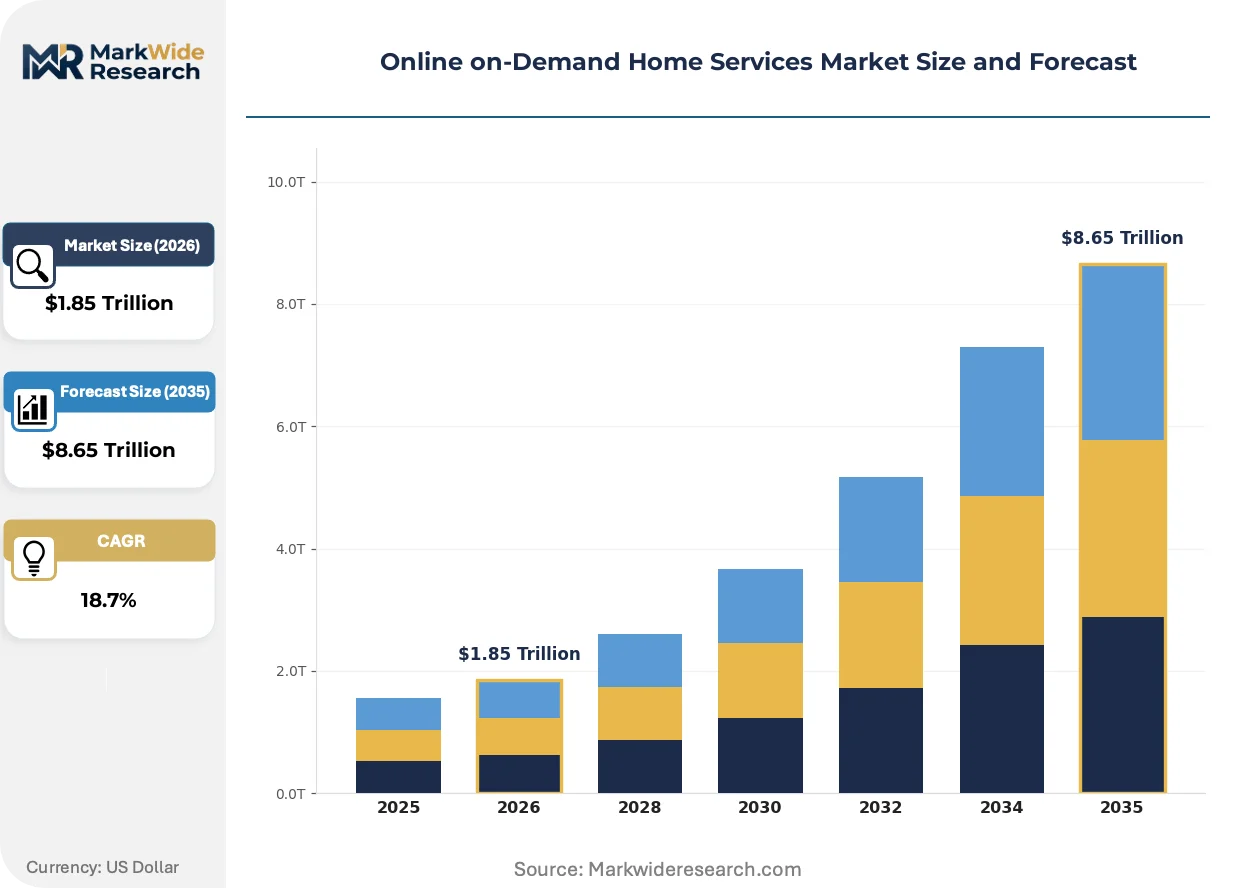
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $8.65 Trillion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Plumbing, Electrical Services, Landscaping Customer Type: Residential, Commercial, Property Managers, Realtors Technology: Mobile Apps, Web Platforms, Payment Systems, Scheduling Software Pricing Model: Subscription, Hourly Rates, Fixed Pricing, Pay-As-You-Go |
| Companies Covered | Taskrabbit, Thumbtack, Angi, Urban Company, Handy, Airtasker, HomeAdvisor, Amazon.com, Helpling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online on-Demand Home Services Market Strategic Shifts & Innovations
Mobile-first service orchestration is collapsing traditional contractor discovery and scheduling friction, while regulatory pressure on data handling and labor classification forces architectural redesign of platform operations.
AI-powered dynamic pricing engines are supplanting static rate cards by adjusting quotes in real-time based on technician proximity, demand spikes, and historical completion reliability. Property managers in the Netherlands and Belgium are adopting these tools to cap annual maintenance budgets. The shift is compressing price transparency gaps that previously favored incumbent contractors with established customer relationships.
GDPR's data minimization requirements are compelling European platforms to rearchitect customer profile storage, deleting location histories after service completion rather than retaining them for remarketing. This is elevating operational costs for cross-border operators while creating compliance advantages for regionally focused competitors. German and French regulators are now auditing algorithmic decision-making for discriminatory dispatch patterns.
Fixed-fee service bundles are displacing hourly-rate uncertainty that previously deterred first-time users from booking specialized trades. Indian and Brazilian households are gravitating toward guaranteed-outcome pricing for plumbing and electrical work, with platforms absorbing cost overruns. The model is most visible in Bangalore and São Paulo, where dense technician networks enable accurate job-cost prediction.
Online on-Demand Home Services Market Segmentation
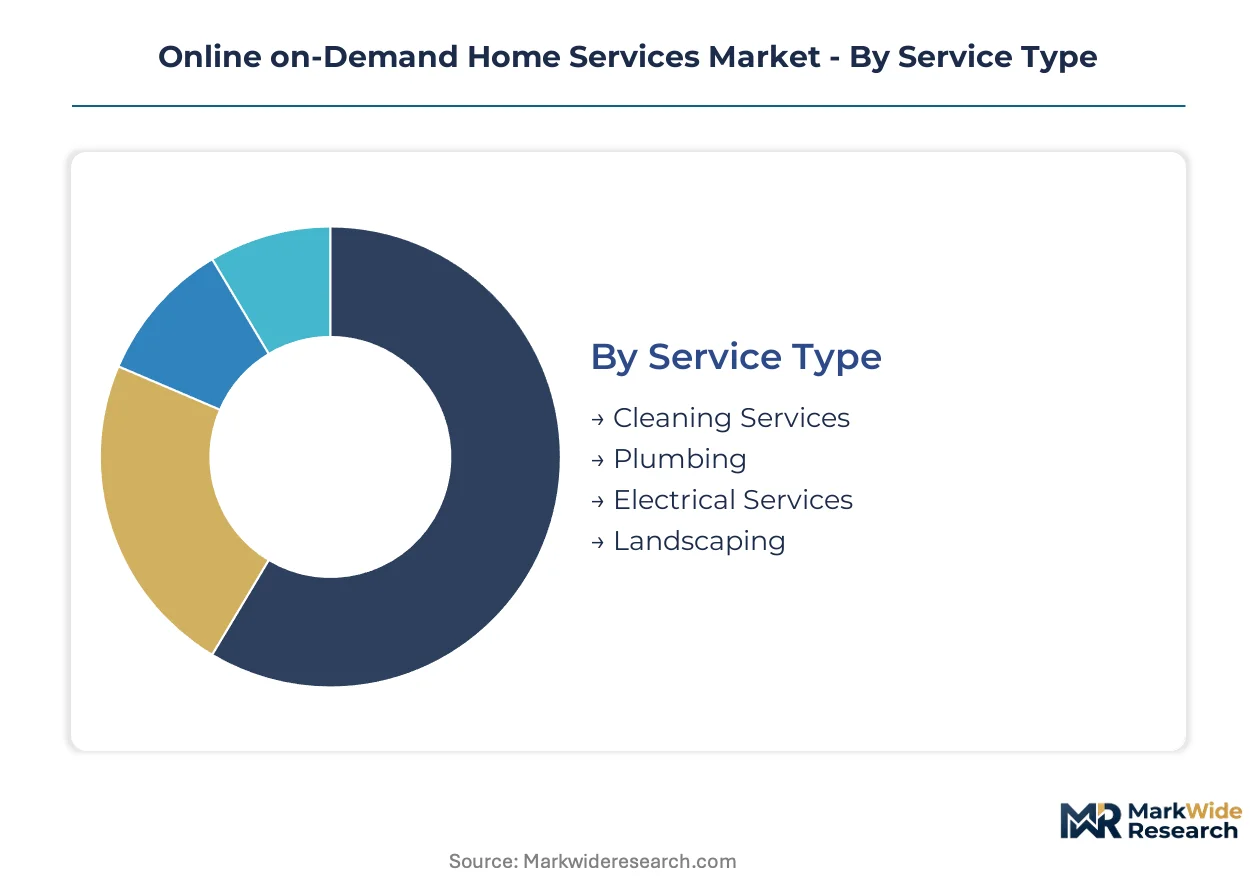
Segmentation in online on-demand home services determines platform architecture and capital allocation. Service type shapes technician recruitment and training investments. Customer type drives channel strategy between direct-to-consumer apps and B2B sales teams.
Service Type:
Cleaning services flow predominantly through mobile app channels with minimal pre-qualification, while specialized trades require web-platform documentation and certification uploads. The channel mix diverges sharply between low-skill categories with instant booking and licensed trades with multi-step onboarding.
- Cleaning Services:Standardized tasks with low technician credential barriers enable rapid marketplace scaling. Demand concentrates in Bangalore, Mumbai, and Delhi metro clusters where Urban Company has built dense supply networks. Recurring bookings from dual-income households sustain subscription revenue pools.
- Plumbing:Licensed trade requiring verified credentials and liability insurance before platform activation. Demand concentrates in São Paulo and Mexico City high-rise residential towers where indoor GPS limitations degrade dispatch accuracy. Water damage risk elevates customer preference for fixed-fee guarantees over hourly uncertainty.
- Electrical Services:Certification mandates from national electrical regulators create onboarding bottlenecks that throttle expansion velocity.
- Landscaping:Seasonal demand patterns and equipment transport costs favor local contractor networks over algorithmic matching platforms.
By volume, Cleaning Services leads. By growth pace, Electrical Services is ahead.
Customer Type:
Cost tier differentiation separates price-sensitive residential bookings from premium commercial contracts with SLA guarantees. Property managers represent the highest-margin segment due to predictable maintenance schedules and reduced acquisition costs.
- Residential:Individual households booking sporadic repairs and maintenance through mobile-first interfaces. German and French millennials drive fixed-fee bundle adoption to eliminate hourly-rate anxiety. GDPR compliance costs for data retention elevate operational overhead for cross-border operators serving this segment.
- Commercial:Small businesses and retail locations requiring after-hours service windows and invoice-based billing. Demand concentrates in Dutch and Belgian logistics hubs where facility managers cap annual maintenance budgets through dynamic pricing tools. Contract minimums and credit terms extend cash conversion cycles.
- Property Managers:Multi-unit portfolio operators in Germany and France adopting subscription pricing for predictable cost structures.
- Realtors:Pre-sale preparation and staging services with transaction-tied demand volatility and high customer acquisition costs.
By revenue concentration, Property Managers dominate. By expansion velocity, Residential is climbing the fastest.
Technology:
Application maturity determines infrastructure investment sequencing, with mobile apps commanding the largest development budgets and payment systems requiring the densest regulatory compliance architecture.
- Mobile Apps:Dominant consumer acquisition channel integrating GPS dispatch, real-time availability dashboards, and escrow payment rails. India's PLI scheme for digital infrastructure subsidizes cloud-native development for domestic aggregators. Push notification fatigue and app store commission structures erode long-term economics.
- Web Platforms:Preferred interface for commercial customers and licensed technicians uploading certification documentation. Demand concentrates in European markets where GDPR consent-management architectures impose heavier frontend development requirements. Browser-based access reduces friction for one-time users.
- Payment Systems:Legacy banking API resistance in emerging markets forces platforms to absorb elevated transaction fees or settlement delays.
- Scheduling Software:Back-office optimization tools for multi-technician operations with limited standalone revenue potential.
By deployment scale, Mobile Apps leads. By margin improvement potential, Payment Systems is gaining share fastest.
Pricing Model:
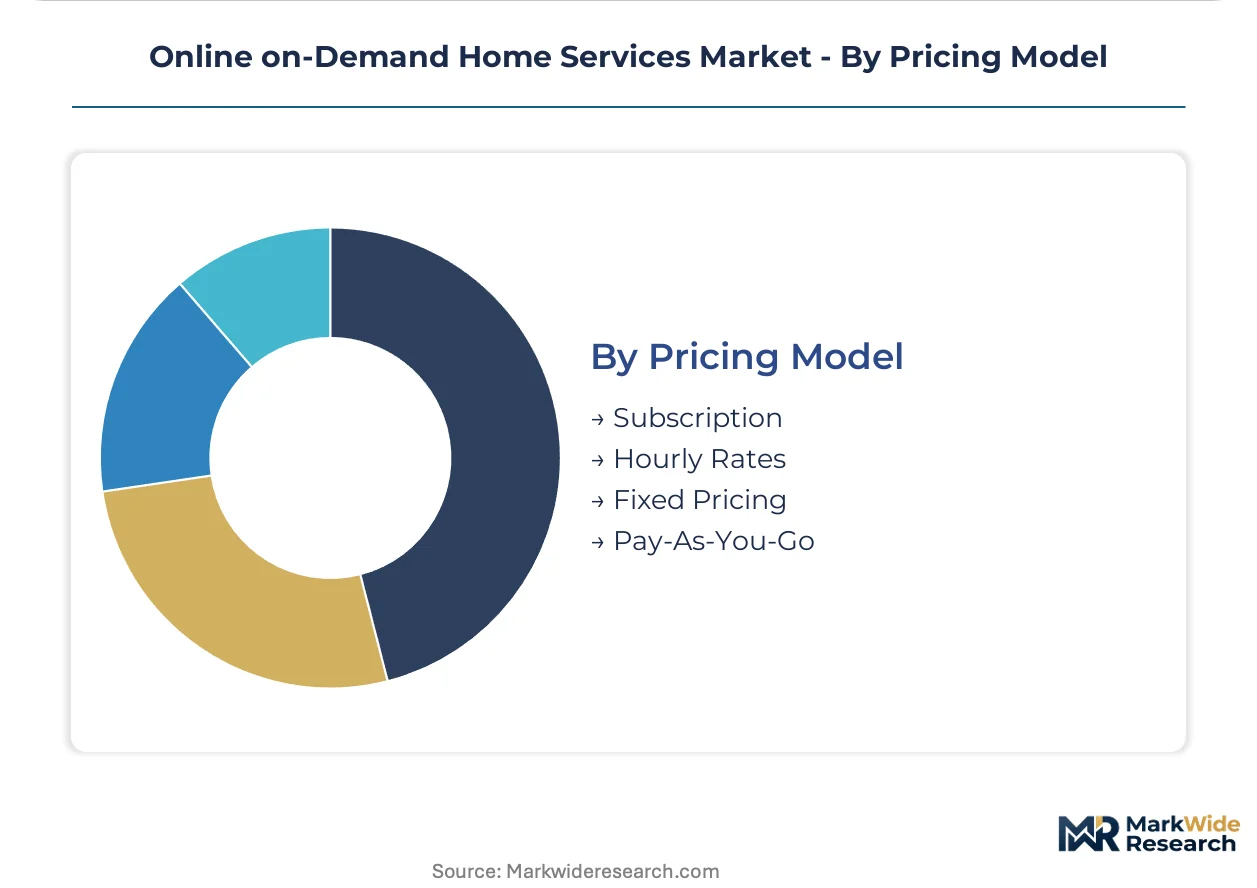
Customer type alignment shapes pricing architecture, with subscriptions capturing property management firms and fixed pricing converting first-time users from hourly-rate uncertainty.
- Subscription:Recurring revenue contracts locking in property managers and high-frequency residential users. German and French portfolio operators adopt fixed-fee maintenance contracts to reduce budget volatility. Churn risk concentrates in seasonal service categories with irregular utilization patterns.
- Hourly Rates:Traditional contractor pricing model experiencing displacement in Indian and Brazilian markets. Customer distrust of open-ended billing drives migration toward guaranteed outcomes. Technician preference for hourly structures creates platform-operator tension in labor negotiations.
- Fixed Pricing:Guaranteed-outcome structures for plumbing and electrical work where platforms absorb cost overruns.
- Pay-As-You-Go:Minimal-commitment option for sporadic users with highest per-transaction acquisition costs.
By revenue stability, Subscription leads. By customer acquisition efficiency, Fixed Pricing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes on-demand home services through dense metro app ecosystems, while Germany and France favor subscription contracts with property managers. The United States splits between gig-marketplace spontaneity and commercial SLA structures. Brazil absorbs fixed-fee guarantees to offset hourly-rate distrust.
India
Urban millennial household formation drives app-based booking density in Bangalore, Mumbai, and Delhi. The PLI scheme for digital infrastructure subsidizes cloud-native platform development, lowering capital barriers for domestic aggregators. Urban Company anchors technician training academies in these metro clusters, standardizing service protocols across electrical and plumbing trades.
Germany
Property managers in Berlin and Hamburg adopt fixed-fee maintenance contracts to eliminate budget volatility. GDPR compliance costs elevate operational overhead for cross-border operators, creating advantages for regionally focused competitors. The KBA and federal labor courts scrutinize algorithmic dispatch patterns for discriminatory outcomes.
United States
State labor departments clarify contractor classification tests, reducing legal uncertainty for platform expansion into regulated trades. OSHA and state-level gig-worker laws reshape liability frameworks and pricing structures. California and New York metro areas sustain low fixed-cost marketplace expansion through contractor density.
Brazil
São Paulo households gravitate toward guaranteed-outcome pricing for plumbing and electrical work, with platforms absorbing cost overruns. ANVISA and consumer protection regulators impose liability frameworks on service aggregators. Dense technician networks in São Paulo and Rio de Janeiro enable accurate job-cost prediction for fixed-fee bundles.
France
Facility managers in Paris and Lyon cap annual maintenance budgets through dynamic pricing tools. The CNIL audits algorithmic decision-making for discriminatory dispatch patterns under GDPR data minimization requirements. Subscription pricing models lock in recurring revenue from multi-unit portfolio operators.
Online on-Demand Home Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence bifurcating competitive returns. Asset-light marketplace operators sustain low fixed-cost expansion, while vertically integrated service networks absorb higher training and certification investments. Two strategic archetypes dominate: contractor marketplaces and in-house protocol standardizers. Competitive moves concentrate on geographic metro densification and subscription pricing adoption.
Within the integrated tier, Urban Company exemplifies the vertically structured archetype through its Indian metro concentration. Taskrabbit and Thumbtack occupy positions within the asset-light marketplace vector, leveraging contractor density across North American and European cities. These three anchors illustrate the structural choice between capital-intensive supply control and low-fixed-cost demand aggregation.
| Leading Market Players |
|---|
| Taskrabbit |
| Thumbtack |
| Angi |
| Urban Company |
| Handy |
| Airtasker |
| HomeAdvisor |
| Amazon.com |
| Helpling |
| Others |
Cost & Logistics Intelligence
India's Consumer Protection (E-Commerce) Rules impose liability frameworks that simultaneously gate technician onboarding and stratify pricing tiers across domestic and foreign platform operators. This regulatory architecture compresses margins for entrants lacking localized supply networks while rewarding incumbents with dense metro technician density.
Pricing Analysis
Long-term subscription contracts dominate property manager relationships in Germany and France, while spot-market bookings persist among sporadic residential users. Price differentiation hinges on technician certification tier and guaranteed-outcome bundling for plumbing and electrical trades. Cost compression in transportation-dependent categories intensifies as fuel volatility erodes per-job margins. Price-sensitive residential millennials in Indian metros drive fixed-fee adoption, while commercial facility managers exhibit lowest sensitivity due to budget-capped maintenance contracts.
Supply Chain Analysis
Port congestion along Asia-Europe trade lanes elevates inbound logistics costs for IoT-enabled diagnostic equipment deployed in technician fleets. Supply concentrates in India, Brazil, and the United States for platform development talent and cloud infrastructure. Raw material dependencies span GPS hardware modules, encrypted payment processing chips, and mobile device components. Single-source vulnerability concentrates in legacy banking API providers across emerging markets. Distribution runs through app store ecosystems and direct enterprise sales teams serving property management portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Online on-demand home services sits in early-cycle expansion as urban millennial household formation accelerates platform penetration across dense metro clusters. Fixed-fee pricing adoption and subscription contract penetration remain below saturation thresholds in most markets.
For Market Incumbents: Secure technician certification pipelines through in-house training academies to defend against marketplace-model entrants with lower fixed-cost structures. Anchor position in high-frequency metro clusters where density sustains sub-30-minute dispatch windows. Invest in GDPR-compliant data architectures to reduce cross-border liability exposure.
For New Entrants and Emerging Players: Certification fast-track partnerships with national electrical regulators unlock licensed trade segments where onboarding bottlenecks throttle incumbent expansion. White-space concentrates in São Paulo and Mexico City high-rise towers where indoor GPS limitations degrade arrival-time predictions. Target commercial facility managers in Dutch and Belgian logistics hubs through dynamic pricing tools that cap annual maintenance budgets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vertically integrated service networks as training academy investments compound. Long-term viability favors platforms controlling supply-side quality through standardized protocols rather than pure marketplace aggregation. Acquisition targets should display metro-level technician density above critical mass thresholds. Watch subscription revenue share as the signal indicating platform transition from transactional to recurring revenue models.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Academy Expansion | Urban Company's Bangalore academy standardizes electrical protocols, reducing service failure liability under India's e-commerce rules. |
| Subscription Pricing Model Rollout | German property managers lock in recurring revenue streams, compressing customer acquisition costs for platform operators. |
| GDPR-Compliant Data Architecture | Encrypted payment rails and consent-management systems reduce fraud liability for cross-border European service platforms. |
| IoT Predictive Maintenance Integration | Smart home device algorithms enable preemptive dispatch before homeowner-initiated requests in dense metro markets. |
| Fixed-Fee Bundle Introduction | São Paulo households absorb cost overrun risk, eliminating hourly-rate distrust that deters first-time plumbing bookings. |
Research Approach
Findings reconcile primary fieldwork against secondary review of platform operator disclosures, national labor department rulings, and consumer protection regulatory filings. Primary interviews engaged platform operations executives, technician network managers, property management procurement leads, and regulatory compliance officers across India, Germany, the United States, Brazil, and France. Secondary sources encompassed GDPR implementation guidance, OSHA contractor classification determinations, ANVISA service aggregator liability frameworks, and cloud infrastructure subsidy documentation under India's PLI scheme. Bottom-up technician density modeling and top-down market sizing triangulated volume estimates.
Segmentation dimensions modeled span service type, customer archetype, technology deployment, and pricing structure across the projection horizon. CAGRs derive from technician network expansion velocity, subscription contract adoption curves, and fixed-fee bundle penetration rates. Industry-specific inputs include GPS dispatch accuracy degradation in high-rise residential towers, escrow payment settlement delays in legacy banking environments, and certification onboarding bottlenecks for licensed electrical and plumbing trades.
Decision-makers should treat outputs as directional under assumptions of sustained urban millennial household formation and stable gig-worker classification frameworks; material deviation would warrant model refresh. Specific risks encompass regulatory divergence on platform liability, fuel cost volatility compressing transportation-dependent margins, and indoor location accuracy limitations degrading customer satisfaction scores. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Green IT Services Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Docketing Solution Market
Digital Solutions
IT Service Management Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Global E-Visa Market
Digital Solutions
IPTV Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Product Prototyping Market
Digital Solutions
P2P Rental Apps Market
Digital Solutions
EHS Software Market
Digital Solutions
Load Balancer Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Transit Station Display Board Market