
 Harbor Management Software Market | 2026-2036
Harbor Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Harbor Management Software Market Outlook
IMO 2023 carbon intensity regulations are hardening the cost-of-entry calculus for harbor management platforms, forcing smaller ports to consolidate software procurement around compliant systems. Navis LLC leverages its terminal operating system heritage to anchor multi-vessel coordination workflows across major transshipment nodes. Saab Technologies sustains defense-adjacent positioning through sensor fusion capabilities that differentiate its vessel tracking layer. Kongsberg Gruppen dominates dynamic positioning integrations, extending its maritime automation footprint into port approach corridors.
Harbor management software orchestrates port operations through real-time vessel tracking, berth scheduling algorithms, and cargo documentation workflows, typically interfacing with AIS transponders and radar feeds to maintain sub-minute position accuracy for collision avoidance and queue optimization. The technology segment shows cloud-based deployment pulling ahead as port authorities outsource infrastructure maintenance, while hybrid architectures retain favor among security-sensitive military-civilian dual-use facilities. Terminal operators represent the most concentrated margin pool within end users, with freight forwarders representing the fastest-growing adoption curve as they seek direct berth visibility to compress dwell-time liabilities.
FCC maritime communication standards in the United States, EU Green Deal emissions protocols under ECHA oversight, and IMO safety management codes collectively shape product certification requirements and data interoperability mandates for harbor software vendors. The EU AI Act's risk classification framework will soon categorize autonomous berth allocation algorithms as high-risk systems, triggering conformity assessment obligations before European port deployment. Stakeholders must monitor whether emerging cyber-resilience standards for port critical infrastructure will fragment procurement specifications across national regulators or converge toward ISO 27001-derived baselines.
Market Dynamics
IMO 2023 carbon intensity regulations are compressing software procurement cycles as port authorities race to deploy emissions-compliant berth optimization before enforcement deadlines.
Growth Catalysts
- EU Green Deal mandates:The ECHA emissions monitoring framework forces European container terminals to digitize vessel turnaround documentation, creating mandatory upgrade cycles for legacy harbor systems.
- Automated cargo modules:East Asian transshipment hubs in Singapore and Rotterdam are accelerating adoption of integrated berth optimization platforms to compress dwell times.
- Cloud deployment preference:Port authorities are outsourcing infrastructure maintenance to cloud-native architectures, reducing capex barriers for mid-tier facilities.
Market Restraints
- Hybrid architecture persistence:Security-sensitive military-civilian dual-use facilities retain on-premise systems, fragmenting vendor R&D across deployment models.
- Sensor fusion complexity:Sub-minute position accuracy requirements for collision avoidance demand expensive AIS-radar integration that smaller ports cannot afford.
- EU AI Act compliance costs:Autonomous berth allocation algorithms face high-risk system classification, triggering conformity assessment obligations that delay European deployment.
Strategic Opportunities
- Freight forwarder adoption:Direct berth visibility tools represent the fastest-growing demand curve as logistics intermediaries seek to compress dwell-time liabilities.
- Dynamic positioning integration:Convergence of maritime automation with port approach corridor management creates upstream control opportunities for specialized vendors.
- Cyber-resilience standardization:Emerging ISO 27001-derived baselines for port critical infrastructure may consolidate fragmented national procurement specifications.
Industry Challenges
- Maritime-AI skill scarcity:Port authorities struggle to hire personnel capable of calibrating machine-learning berth allocation models against tidal and weather variables.
- Legacy system integration:Terminal operating system heritage platforms resist API standardization, forcing expensive middleware development for multi-vessel coordination.
- Dual-use certification timelines:Defense-adjacent positioning capabilities require separate civilian and military security clearances that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harbor Management Software Market |
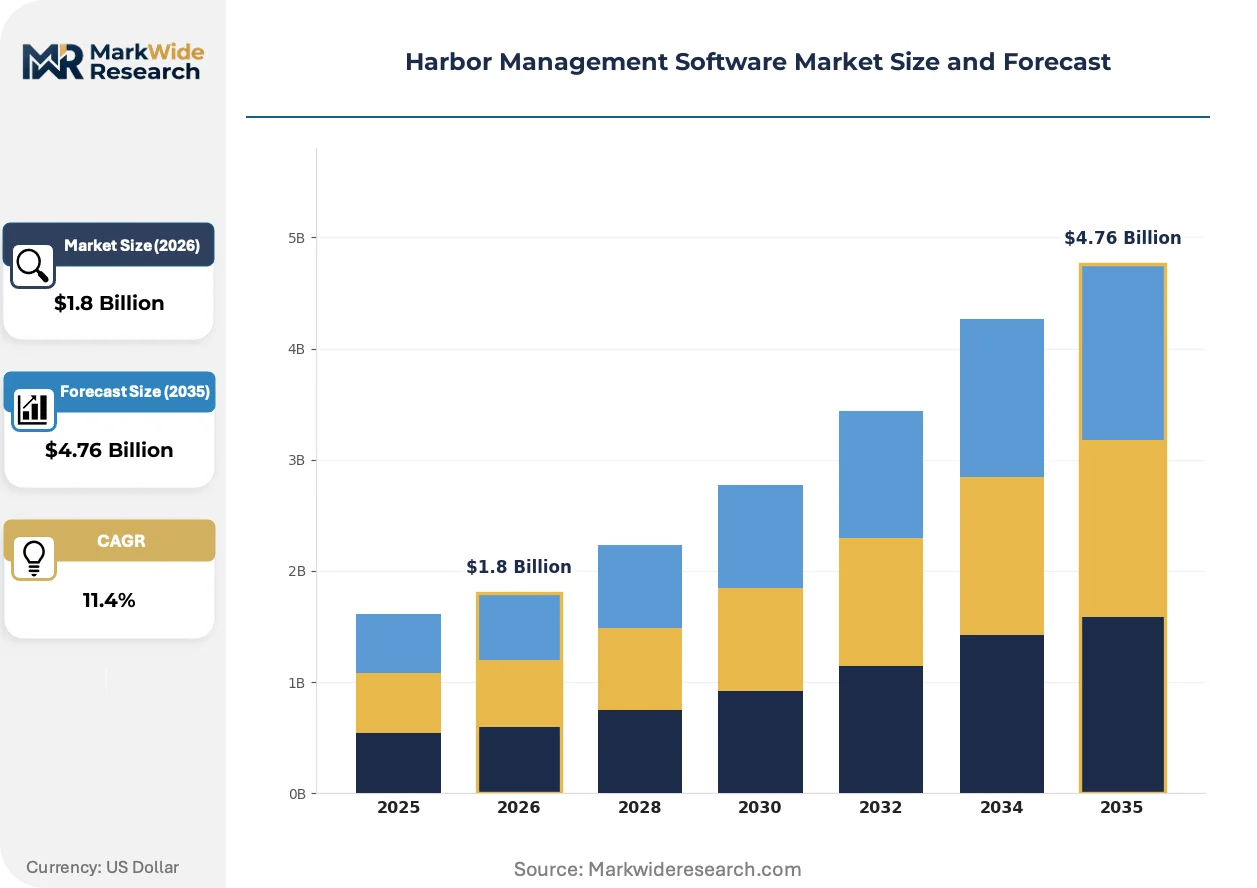
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vessel Tracking, Berth Allocation, Cargo Management, Safety Compliance Technology: Cloud-Based, On-Premise, Hybrid, Mobile Applications End User: Port Authorities, Shipping Companies, Freight Forwarders, Terminal Operators Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Site |
| Companies Covered | Navis LLC, Saab Technologies, Harba ApS, Harbour Mastery Inc., PortPro, Tideworks Technology, Trelleborg Marine Systems, Softship AG, Kongsberg Gruppen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harbor Management Software Market Strategic Shifts
Real-time data fusion architectures are displacing siloed harbor subsystems as terminal operators demand unified visibility across vessel tracking, berth scheduling, and cargo documentation workflows.
Digital twin technology for port infrastructure is unifying previously separate simulation environments for berth allocation, crane scheduling, and yard optimization. Container terminal operators in Singapore and Rotterdam are deploying these unified models to stress-test congestion scenarios before vessel arrival. The structural consequence is collapsing procurement cycles for standalone point solutions as buyers demand integrated platforms.
The EU AI Act's risk classification framework is reclassifying autonomous berth allocation algorithms as high-risk systems requiring conformity assessment before deployment. European port authorities must now document algorithmic decision trails and human oversight protocols. Container terminals in Rotterdam and Hamburg are responding by embedding compliance documentation into procurement specifications.
Freight forwarders are demanding direct API access to berth visibility data, bypassing traditional terminal operator intermediaries. This channel disintermediation compresses information asymmetries that historically protected terminal margins. The shift is most visible in East Asian transshipment hubs where forwarders operate dedicated control towers.
Harbor Management Software Market Segmentation
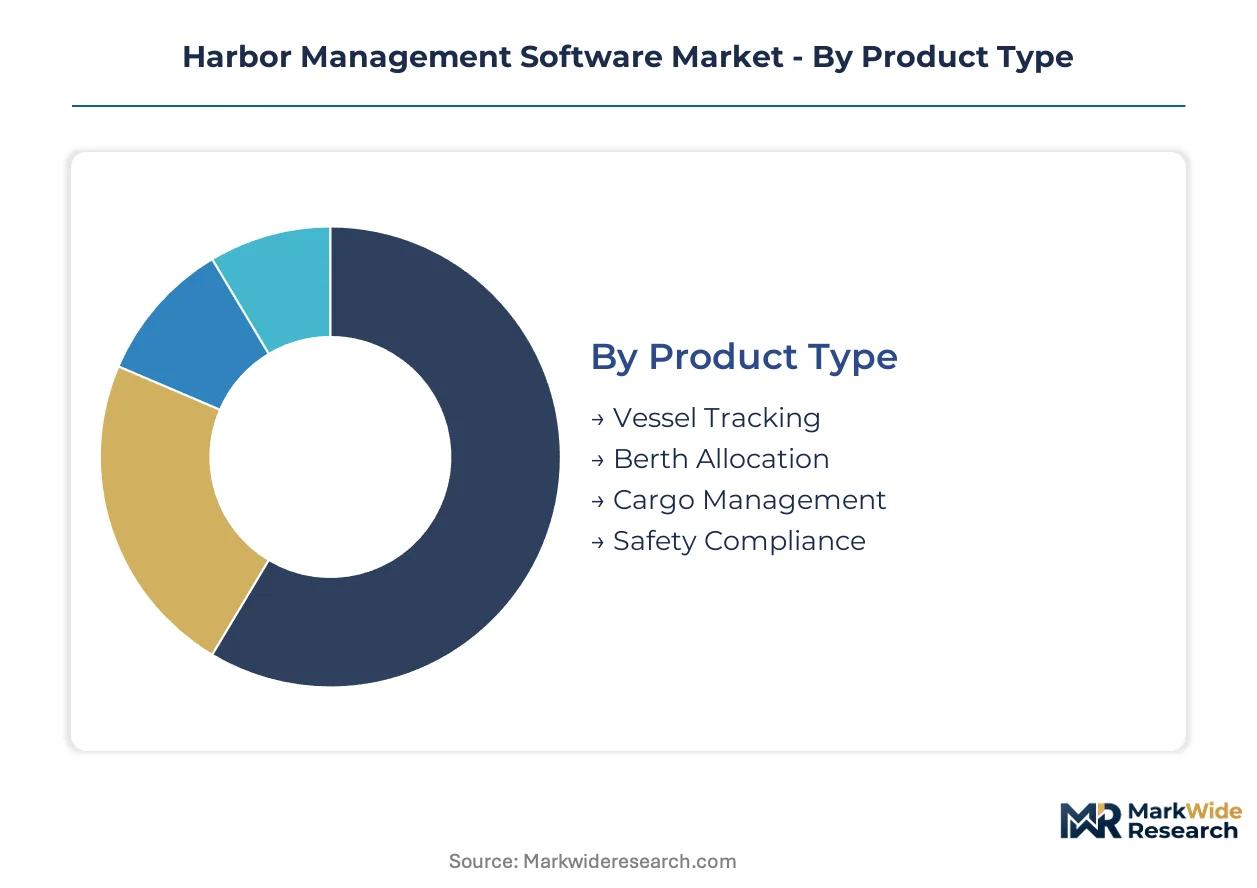
Harbor management software segments diverge sharply between high-volume commodity modules and premium integration layers. Procurement patterns reveal terminal operators consolidating around unified platforms while smaller ports retain point solutions.
Product Type:
Vessel Tracking commands the volume tier through mandatory AIS integration, while Berth Allocation captures premium pricing via algorithmic optimization.
- Vessel Tracking:Real-time position monitoring synthesizes AIS transponder feeds, radar returns, and GPS signals to maintain sub-minute accuracy for collision avoidance. Demand clusters at Singapore and Rotterdam transshipment hubs where traffic density mandates continuous surveillance.
- Berth Allocation:Algorithmic scheduling engines optimize vessel arrival sequencing against tidal windows, crane availability, and yard congestion constraints. Terminal operators in Hamburg and Antwerp deploy these systems to compress turnaround times under EU Green Deal emissions deadlines.
- Cargo Management:Documentation workflows digitize customs declarations, hazardous material manifests, and container weight verification for regulatory filing.
- Safety Compliance:Incident logging and audit trail modules satisfy IMO safety management code documentation requirements.
Today's leader: Vessel Tracking. Tomorrow's challenger: Berth Allocation.
Technology:
Cloud-Based deployment is displacing capital-intensive infrastructure models, though Hybrid architectures persist where data sovereignty intersects with operational efficiency needs.
- Cloud-Based:SaaS delivery eliminates server maintenance burdens and enables elastic scaling during peak vessel arrival periods. Mid-tier ports in Spain and Italy outsource infrastructure to compress fixed costs.
- Hybrid:Split architectures retain sensitive vessel tracking data on-premise while pushing analytics workloads to cloud environments. Military-civilian dual-use facilities in France and Germany favor this model for security clearance compliance.
- On-Premise:Dedicated server installations persist where national cybersecurity mandates prohibit external data hosting.
- Mobile Applications:Smartphone-based interfaces extend berth visibility to pilots, tug operators, and harbor masters working vessel approach corridors.
Cloud-Based systems dominate new procurement. Hybrid deployments defend the security-sensitive niche.
End User:
Terminal Operators concentrate procurement spending through integrated platform mandates, while Freight Forwarders are expanding most quickly via API-based visibility tools.
- Terminal Operators:Container handling companies demand unified control over vessel reception, crane dispatch, and yard stacking algorithms. PSA International and DP World subsidiaries drive specification standards across Singapore, Rotterdam, and Jebel Ali.
- Freight Forwarders:Logistics intermediaries bypass traditional terminal data gatekeepers through direct berth status APIs. DHL Global Forwarding and Kuehne+Nagel control towers in Shanghai and Busan compress dwell-time liabilities with real-time visibility.
- Port Authorities:Government agencies regulate traffic safety and environmental compliance through harbor-wide coordination mandates.
- Shipping Companies:Ocean carriers integrate berth window data into voyage optimization systems for fuel consumption planning.
Terminal Operators anchor current revenue. Freight Forwarders are climbing the fastest.
Deployment Model:
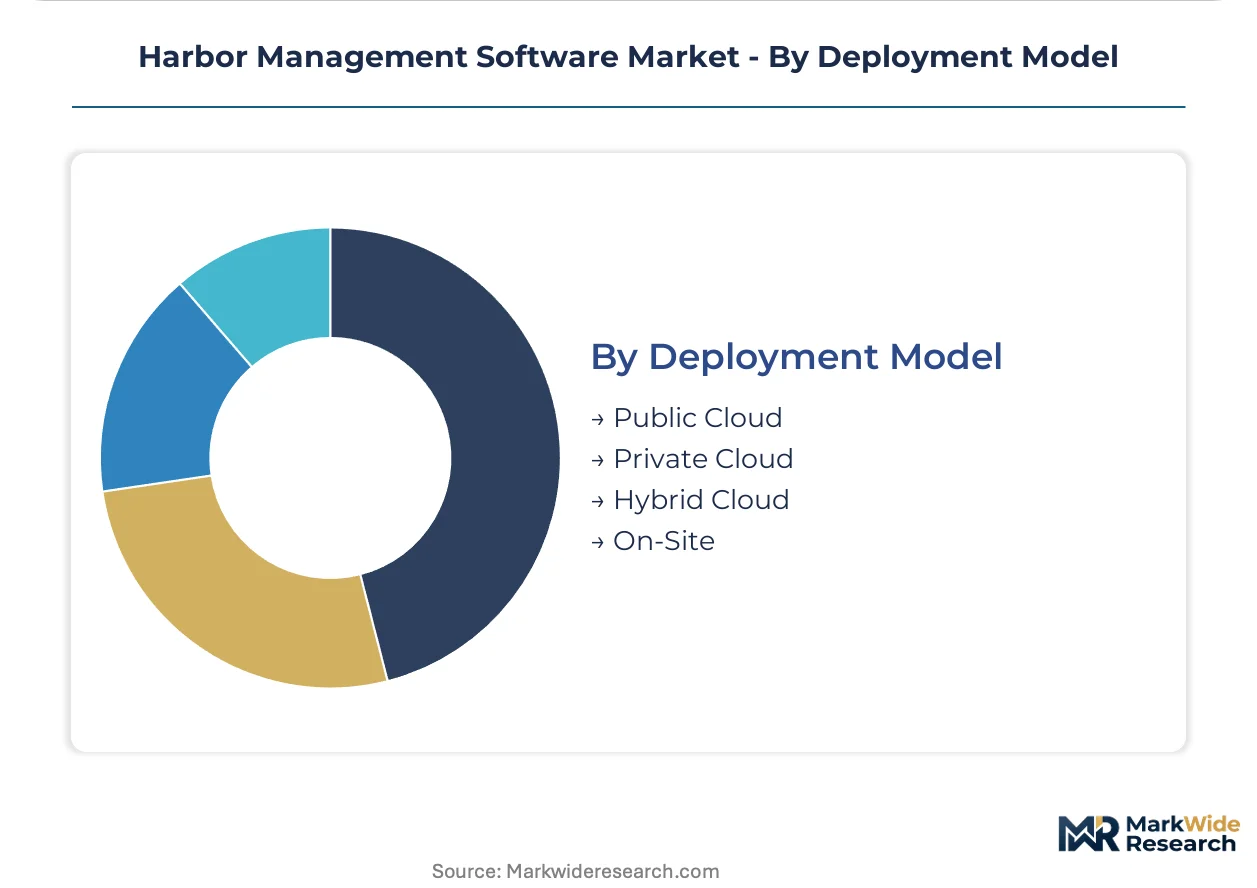
Public Cloud minimizes upfront expenditure for budget-constrained facilities, whereas Private Cloud deployments satisfy defense-adjacent security protocols.
- Public Cloud:Shared infrastructure pools reduce per-port costs through multi-tenant architectures. Greek and Portuguese regional ports adopt this model to avoid capital expenditure approval cycles.
- Private Cloud:Dedicated single-tenant environments isolate critical vessel traffic data from cohabitation risks. NATO-adjacent facilities in Norway and Denmark mandate this architecture for allied interoperability.
- Hybrid Cloud:Workload-specific routing places non-sensitive analytics in public environments while retaining operational technology on-premise.
- On-Site:Fully localized installations persist where national critical infrastructure regulations mandate air-gapped systems.
Public Cloud owns the expansion trajectory. Private Cloud holds the compliance premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maritime software engineering talent clusters in port-adjacent metropolitan zones where terminal digitization programs create specialized demand for vessel tracking and berth optimization expertise.
Singapore
PSA International and Jurong Port drive integrated platform procurement for transshipment optimization. The Maritime and Port Authority of Singapore mandates real-time emissions reporting under its Green Port Program. Container terminals at Pasir Panjang deploy algorithmic berth allocation to compress vessel turnaround windows.
Germany
Hamburg and Bremerhaven terminal operators invest in cloud-native cargo management to meet EU Green Deal documentation deadlines. The ECHA emissions monitoring framework forces digitization of vessel turnaround records. The Port of Hamburg's Elbe corridor integrates dynamic positioning systems from maritime automation suppliers.
Netherlands
Rotterdam World Gateway and APM Terminals Maasvlakte demand unified visibility across vessel tracking and yard optimization. The EU AI Act classifies autonomous berth allocation as high-risk, triggering conformity assessment obligations. The Rotterdam port authority embeds compliance documentation into procurement specifications for algorithmic scheduling engines.
United States
Los Angeles and Long Beach terminal operators accelerate cloud deployment to manage peak vessel arrival surges. FCC maritime communication standards shape AIS transponder integration requirements for collision avoidance systems. The POLA-POLB complex deploys API-based berth visibility tools for freight forwarder control towers.
United Arab Emirates
DP World Jebel Ali and Abu Dhabi Terminals consolidate around multi-vessel coordination platforms. The country's national maritime regulator enforces cyber-resilience standards for port critical infrastructure. Khalifa Port's automation corridor attracts sensor fusion capabilities from defense-adjacent technology providers.
Harbor Management Software Market Competitive Environment
The competitive structure tilts toward integrated platform specialists with terminal operating system heritage. Consolidation pressure favors vendors offering unified vessel tracking, berth allocation, and cargo documentation workflows. Two archetypes dominate: maritime automation conglomerates extending port approach capabilities, and terminal software pure-plays anchoring multi-vessel coordination. Geographic expansion and strategic partnerships represent the dominant competitive moves as vendors seek access to East Asian transshipment hub procurement cycles.
Among Nordic maritime technology conglomerates, Kongsberg Gruppen and Saab Technologies exemplify the defense-adjacent positioning archetype, leveraging sensor fusion capabilities that differentiate vessel tracking layers for dual-use facilities. Navis LLC anchors the terminal operating system heritage tier, representing the integrated platform consolidation pattern visible across Singapore and Rotterdam procurement mandates.
| Leading Market Players |
|---|
| Navis LLC |
| Saab Technologies |
| Harba ApS |
| Harbour Mastery Inc. |
| PortPro |
| Tideworks Technology |
| Trelleborg Marine Systems |
| Softship AG |
| Kongsberg Gruppen |
| Others |
Value Chain & Pricing Dynamics
Sensor fusion hardware costs cascade through harbor management software tiers, with AIS transponder integration and radar calibration expenses concentrating in premium berth allocation modules sold to Singapore and Rotterdam terminal operators while mid-tier ports absorb compressed margins through cloud-native SaaS alternatives.
Pricing Analysis
Bundled platform subscriptions encompassing vessel tracking, berth optimization, and cargo documentation command premium positioning against unbundled point solutions. Three-tier pricing structure across enterprise, professional, and basic levels reflects deployment complexity and integration depth. Pricing pressure stems from cloud infrastructure commoditization as hyperscale providers reduce hosting costs for SaaS delivery models. Freight forwarders exhibit highest price sensitivity, seeking API-only access without full platform licensing, while terminal operators accept premium tiers for unified control capabilities.
Supply Chain Analysis
Direct-to-port-authority channels handle enterprise-scale procurement for integrated platforms across Hamburg, Rotterdam, and Singapore. Software engineering talent concentrates in Norway, Sweden, and Denmark where maritime automation heritage feeds specialized vendor development. Raw material dependencies include semiconductor components for edge computing nodes, optical sensors for vessel positioning, and secure enclave hardware for dual-use facilities. Single-source vulnerability sits with specialized AIS transponder manufacturers subject to FCC and ETSI certification bottlenecks. Distribution runs through systems integrators with port-sector expertise for deployment and calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Harbor management software offers margin expansion through cloud infrastructure cost-down curves and premium-tier algorithmic optimization modules displacing legacy point solutions.
For Market Incumbents: Anchor multi-vessel coordination capabilities through API standardization investments that lock terminal operators into integrated workflows. Deepen sensor fusion partnerships with defense-adjacent technology providers to differentiate tracking layers for dual-use facilities. Consolidate procurement influence by embedding EU AI Act compliance documentation into platform architectures before competitor conformity assessments complete. For New Entrants and Emerging Players: Begin with freight forwarder API visibility tools targeting dwell-time compression use cases in Shanghai and Busan control towers. Underpenetrated mid-tier ports in Spain and Italy present white-space opportunities through public cloud SaaS models with minimal upfront capital requirements. Pursue channel partnerships with maritime systems integrators possessing established port authority relationships rather than direct enterprise sales builds. For Investors and Strategic Acquirers: Consolidation pressure builds where terminal operating system heritage platforms resist interoperability with modern berth optimization engines. Acquisition targets should display embedded compliance architectures for ECHA emissions monitoring and EU AI Act algorithmic risk classification. Monitor cloud deployment penetration rates in Mediterranean regional ports as inflection indicators for SaaS margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies vessel tracking, berth allocation, and cargo documentation workflows for terminal operators. |
| Strategic Partnership | Sensor fusion alliances with Kongsberg Gruppen and Saab Technologies differentiate dual-use tracking layers. |
| Acquisition of Specialist Firm | Berth optimization algorithm shops accelerate EU AI Act conformity assessment capabilities. |
| Geographic Expansion | East Asian transshipment hub presence captures PSA International and DP World procurement cycles. |
| Product Launch | API-first visibility tools target freight forwarder control towers compressing dwell-time liabilities. |
Study Parameters
Coverage spans Singapore, Germany, Netherlands, United States, and United Arab Emirates, with primary inputs from each market cluster through structured interviews with harbor masters, terminal operations directors, maritime IT procurement officers, and port authority regulatory compliance leads. Secondary validation draws from IMO safety management code filings, ECHA emissions monitoring submissions, FCC maritime communication standards documentation, and SEC disclosures from publicly traded terminal operators. Bottom-up demand modeling across deployment models and end-user segments triangulates against top-down market sizing from vendor revenue aggregation.
Granularity-level modeling distinguishes cloud-based, hybrid, and on-premise architectures at the technology tier while segmenting terminal operators, freight forwarders, port authorities, and shipping companies at the demand tier. Vessel tracking, berth allocation, cargo management, and safety compliance modules receive separate volume and value treatment across the projection horizon. CAGRs derive from regression analysis against port throughput forecasts and regulatory deadline schedules, with IMO carbon intensity enforcement timelines and EU Green Deal implementation phases serving as key exogenous inputs.
Several conditions sit outside the modeled scope, including classified military harbor systems, non-containerized bulk cargo terminals, and inland waterway management platforms. Forecasts reflect assumptions about cloud infrastructure cost trajectories, regulatory enforcement consistency, and maritime-AI talent availability that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Digital Check Scanning Solutions Market