
 Liquid Packaging Board Market | 2026-2036
Liquid Packaging Board Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Packaging Board Market Outlook
Project finance tied to renewable energy certificates is narrowing the capital gap between integrated pulp-to-board operators and independent converters. Stora Enso Oyj leverages its Nordic fiber base to sustain captive kraft pulp supply for liquid packaging grades. Mondi Group anchors Central European carton demand through backward integration into coated fiber production. Tetra Pak International S.A. competes by controlling aseptic filling equipment and board specification standards simultaneously.
Liquid packaging board is a multi-ply paperboard engineered with polyethylene and aluminum barrier layers, typically measuring 200–400 gsm, designed to prevent oxygen and moisture ingress in shelf-stable liquid containers. Its primary commercial purpose is to replace glass and rigid plastic in milk, juice, and broth distribution. Cartons and Tetra Pak formats dominate volume as dairy and beverage applications lead application demand, while virgin fiber grades command margin premiums over recycled paper alternatives due to stricter food-contact compliance.
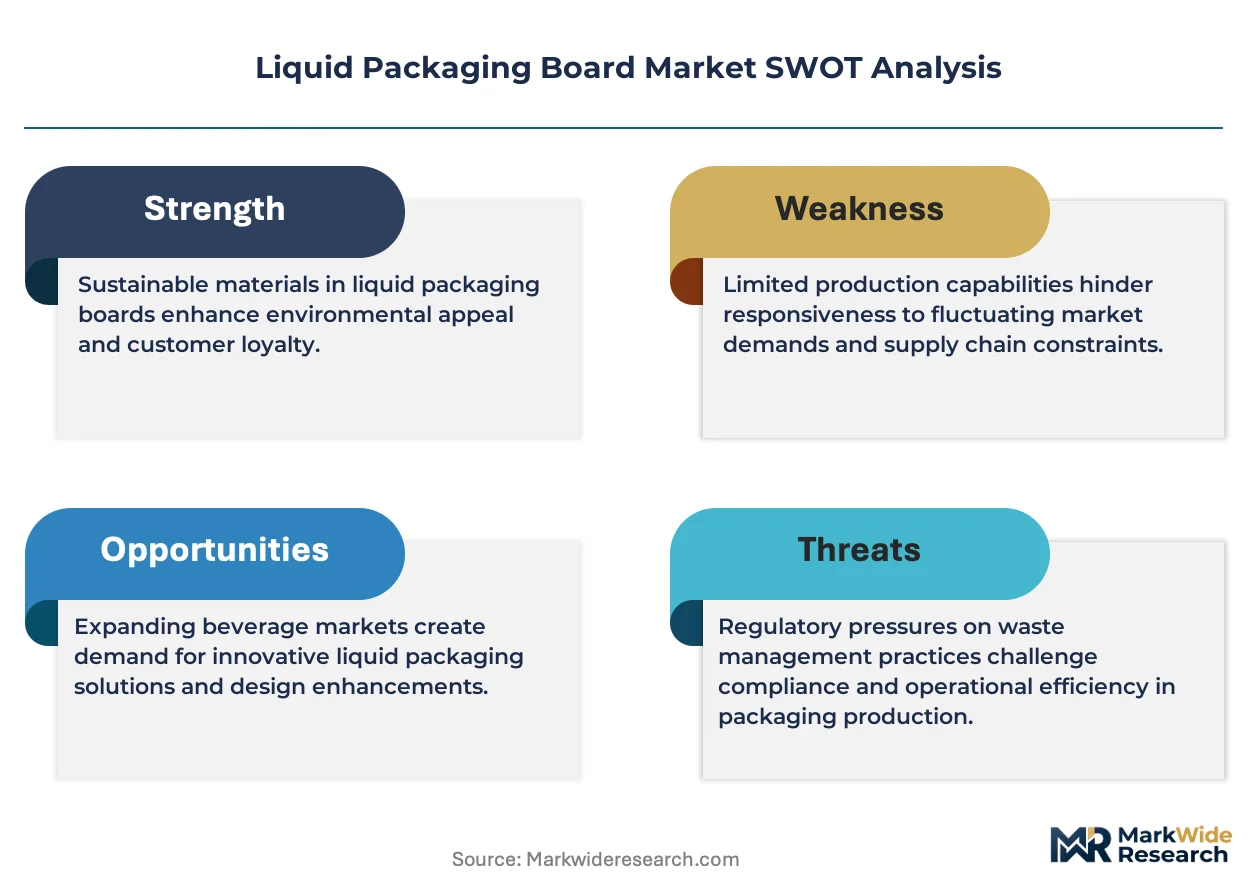
The EU Packaging and Packaging Waste Regulation, FDA food-contact substance notifications, and BIS certification requirements for imported paperboard collectively tighten material traceability and barrier performance standards. These frameworks push converters toward certified virgin fiber and coated fiber substrates while restricting post-consumer recycled content in direct food-contact layers. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in on-site extrusion coating or outsource to integrated board suppliers with existing barrier film capabilities.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins by mandating higher recycled content thresholds while simultaneously restricting post-consumer fiber in direct food-contact layers, forcing a structural pivot toward certified virgin and coated fiber grades.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Packaging and Packaging Waste Regulation tightens extended producer responsibility schemes, pushing dairy processors toward aseptic carton formats that extend shelf life without cold-chain dependency.
- Aseptic filling technology diffusion:Beverage bottlers in Germany and France are retrofitting lines to accept liquid packaging board with aluminum barrier layers, displacing rigid plastic and glass in ambient distribution.
- Food-contact compliance premiums:Virgin fiber grades command sustained margin advantages over recycled alternatives as BIS certification requirements and FDA food-contact substance notifications raise traceability barriers.
Market Restraints
- Pulp cost volatility:Softwood kraft pulp prices fluctuate with Nordic supply disruptions, squeezing integrated operators who lack captive fiber supply.
- Barrier film supply concentration:Polyethylene and aluminum extrusion coating capacity clusters among a handful of Central European converters, creating single-source dependencies for independent board producers.
- Recycled content ceiling:The EU Packaging and Packaging Waste Regulation caps post-consumer fiber in food-contact layers, structurally limiting cost reduction pathways for converters.
Strategic Opportunities
- Plant-based broth and alternative dairy:Oat milk and refrigerated soup brands in Germany seek shelf-stable formats, opening new volume channels for aseptic liquid packaging board.
- Central European converter consolidation:Independent board producers in Poland and Czechia face capital gaps that integrated pulp-to-board operators can exploit through selective facility acquisition.
- Renewable energy certificate financing:Project finance structures tied to green energy credits narrow the capital cost differential between captive pulp producers and merchant market participants.
Industry Challenges
- Extrusion coating equipment lead times:Multi-layer barrier film lines require 18-24 month installation cycles, compressing response windows to demand spikes.
- Food-contact certification latency:BIS and FDA substance notification reviews extend 12-18 months, delaying new coated fiber grade commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Packaging Board Market |
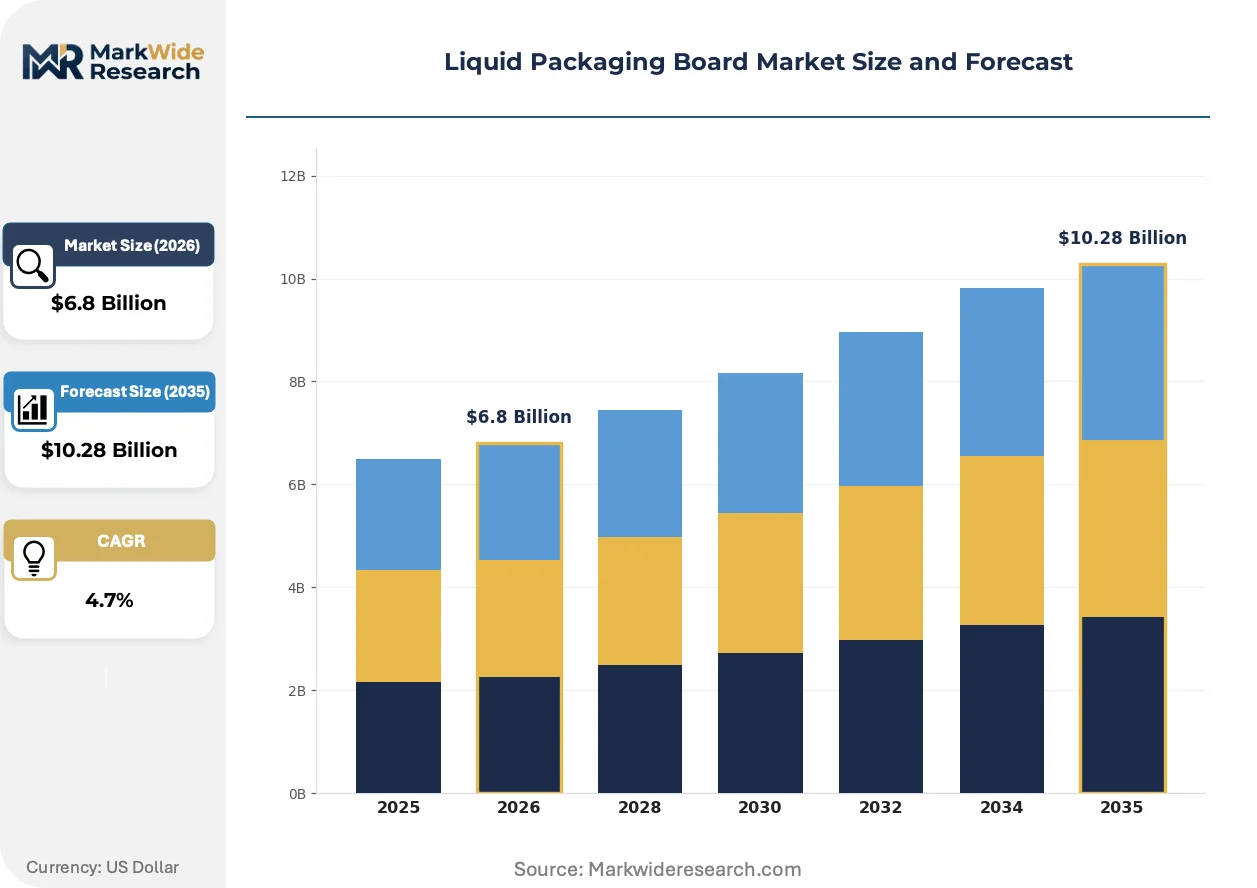
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartons, Boxes, Pouches, Tetra Pak Application: Beverages, Dairy, Food, Pharmaceuticals End User: Manufacturers, Retailers, Wholesalers, Distributors Material: Recycled Paper, Virgin Fiber, Coated Fiber, Others |
| Companies Covered | Nippon Paper Industries Co., Ltd., Smurfit Kappa Group, Stora Enso Oyj, Evergreen Packaging LLC, International Paper Company, WestRock Company, Mondi Group, Tetra Pak International S.A., Billerud AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Packaging Board Market Strategic Shifts
Digital specification platforms and virtualized barrier design are compressing the traditional sample-to-production cycle, while regulatory tightening and buyer consolidation reshape competitive positioning across fiber grades and coating technologies.
Barrier modeling software is virtualizing the traditional physical prototyping process for multi-layer liquid packaging board. Dairy cooperatives in Germany now specify carton constructions through cloud-based simulation tools that predict oxygen transmission rates without production-line trials. This compression of the development cycle is virtualizing the competitive advantage of integrated converters who previously relied on physical sample libraries.
The EU Packaging and Packaging Waste Regulation is tightening recycled content mandates while simultaneously restricting post-consumer fiber in food-contact layers. This regulatory tension forces converters toward certified virgin fiber and coated substrates that satisfy both sustainability disclosures and safety compliance. Dairy and beverage applications in France and Germany face the steepest compliance cost escalation.
Long-term supply agreements are displacing spot procurement as dairy processors seek carton supply security amid fiber grade scarcity. German dairy cooperatives now lock in three-to-five year contracts with integrated pulp-to-board operators, bypassing independent converters. This shift concentrates procurement leverage among backward-integrated suppliers in the Nordic and Central European supply base.
Liquid Packaging Board Market Segmentation
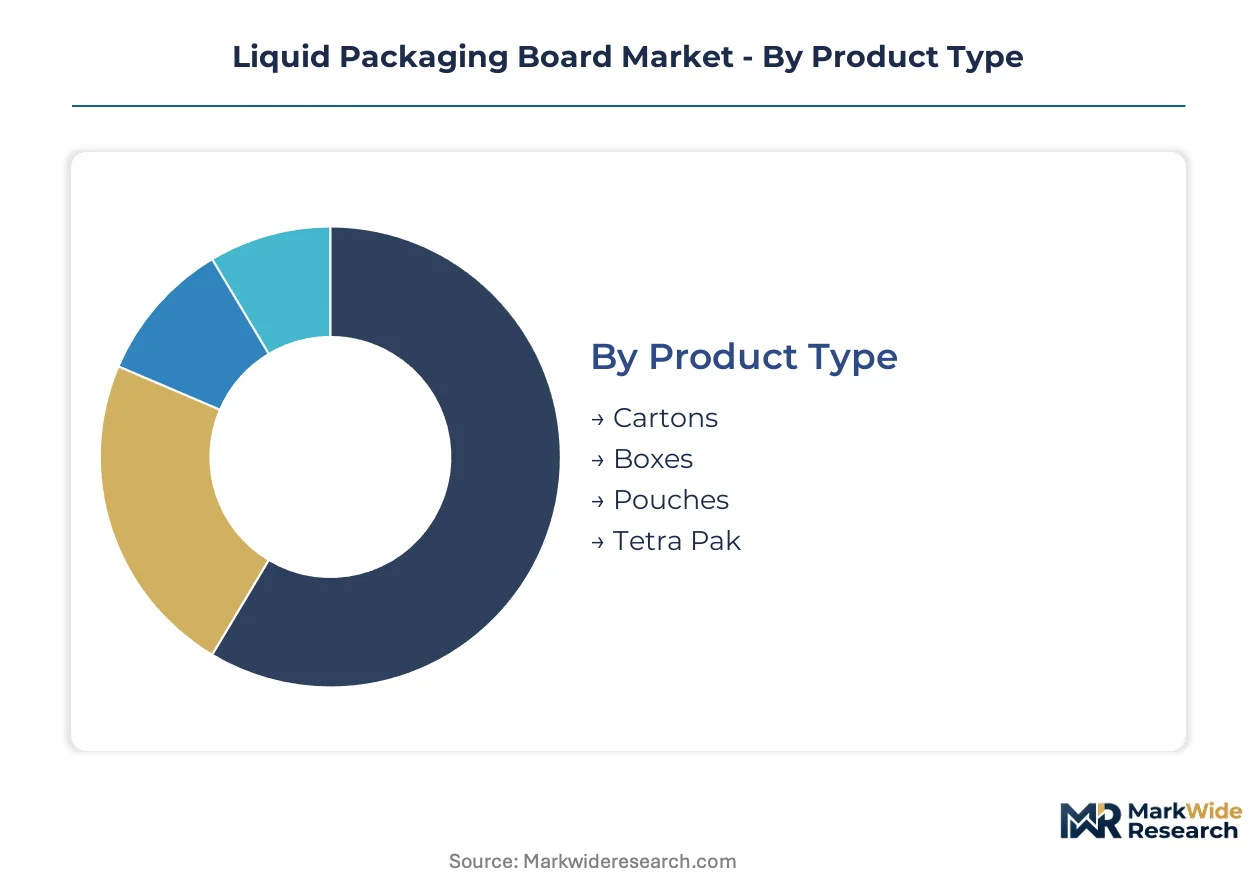
Liquid packaging board procurement patterns diverge sharply across format types, barrier requirements, and customer scale. Each segmentation dimension reveals distinct margin structures and capital intensity thresholds that determine competitive positioning among integrated suppliers and independent converters.
Product Type:
Format selection maps directly to barrier complexity and filling equipment compatibility, with cost tier determining access to premium shelf-stable applications.
- Cartons:Gable-top and rectangular carton formats combine polyethylene-coated paperboard with aluminum foil layers to achieve oxygen transmission rates below 0.5 cc/m²/day. German dairy cooperatives anchor demand for 250–350 gsm constructions as they convert from chilled to ambient distribution chains.
- Tetra Pak:Aseptic brick and wedge formats integrate six-layer barrier structures with longitudinal sealing technology that extends shelf life to 12 months without refrigeration. Beverage bottlers in France retrofit filling lines to capture ambient juice and broth volume previously held by glass bottles.
- Boxes:Corrugated liquid bulk containers serve foodservice and industrial ingredient distribution with lower barrier specifications and shorter shelf-life requirements.
- Pouches:Flexible spouted formats target single-serve beverage and condiment segments where material minimization outweighs extended shelf-life needs.
Cartons hold installed capacity. Tetra Pak is rotating up the share rankings.
Application:
End-use verticals impose divergent regulatory burdens and traceability standards that reshape fiber grade selection across the value chain.
- Dairy:Milk, cream, and alternative dairy products require virgin fiber substrates compliant with EU food-contact substance notifications and BIS certification for imported board. Oat milk brands in Germany seek shelf-stable formats to bypass cold-chain infrastructure limitations.
- Beverages:Juice, nectar, and still drinks drive aluminum barrier layer adoption as bottlers displace rigid PET in ambient distribution. French retailers specify aseptic carton formats to reduce logistics costs and extend product range.
- Food:Broth, soup, and sauce applications concentrate demand in Central European processing clusters where extended producer responsibility schemes raise compliance costs for conventional packaging.
- Pharmaceuticals:Oral liquid and diagnostic reagent packaging demands higher barrier integrity and batch-level traceability that restricts supplier qualification to integrated pulp-to-board operators with captive fiber supply.
Dairy commands margin premiums. Beverages is climbing the fastest as bottlers retrofit filling infrastructure.
Material:
Fiber provenance determines food-contact compliance pathways and recycled content disclosure thresholds under tightening EU mandates.
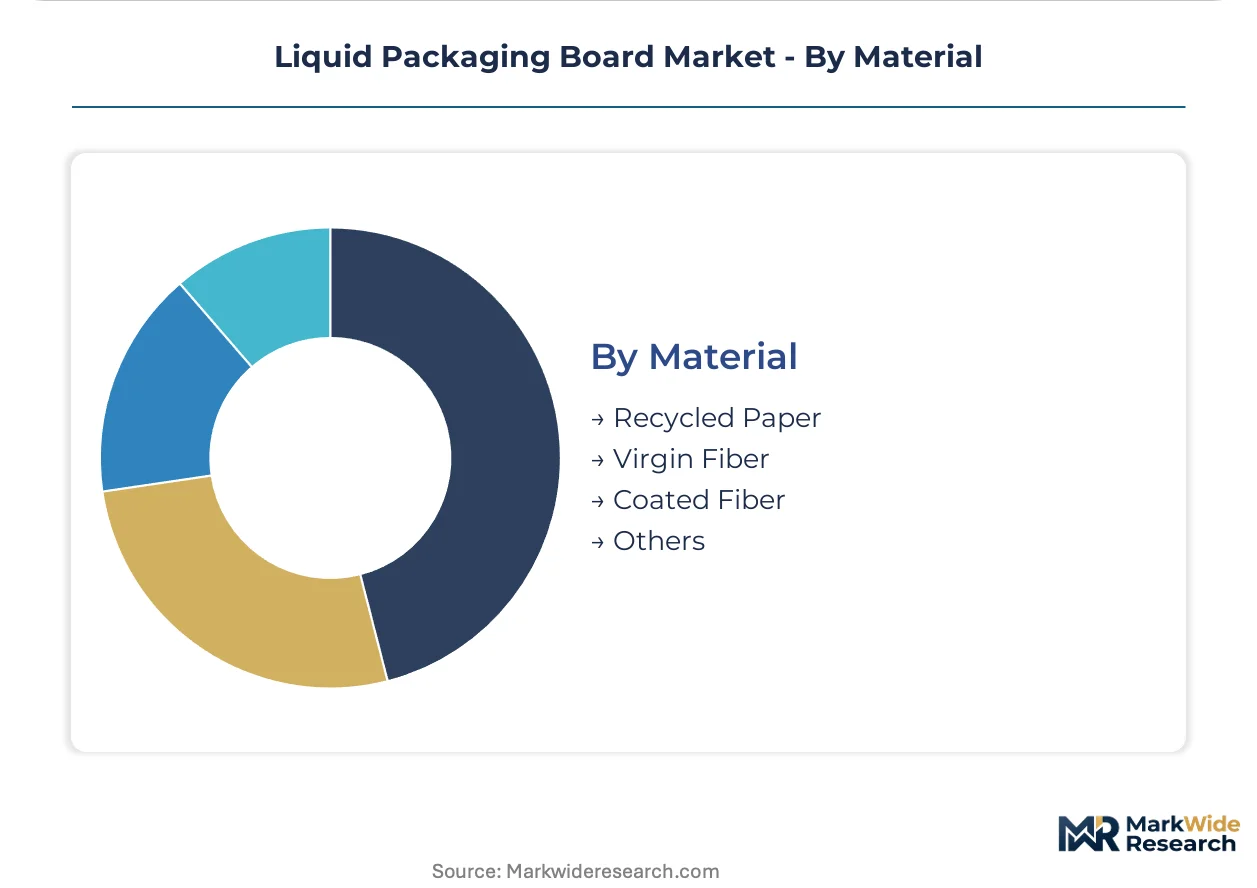
- Virgin Fiber:Unbleached and bleached softwood kraft pulp delivers consistent mechanical properties and regulatory traceability for direct food-contact layers. Nordic integrated producers sustain captive supply advantages as EU Packaging and Packaging Waste Regulation caps post-consumer fiber in food-contact applications.
- Coated Fiber:Extrusion-coated polyethylene and aluminum barrier layers enable oxygen and moisture protection without separate film lamination. Central European converters concentrate capacity for multi-layer coating that meets dairy processor specifications.
- Recycled Paper:Post-consumer fiber faces structural ceilings in food-contact layers but serves outer plies and non-food applications where sustainability disclosures prioritize recycled content percentages over barrier performance.
- Others:Emerging bio-based barrier coatings and plant-derived fiber blends occupy niche positions pending food-contact certification completion.
Virgin Fiber holds installed capacity. Coated Fiber is rotating up the share rankings.
End User:
Customer scale and procurement sophistication determine contract duration, specification control, and backward integration incentives across the supply base.
- Manufacturers:Dairy processors and beverage bottlers with captive filling lines negotiate long-term supply agreements and custom board specifications. German cooperatives lock in three-to-five year contracts with integrated Nordic suppliers to secure fiber grade access.
- Retailers:Private-label carton programs concentrate procurement leverage among backward-integrated board producers who control specification standards and barrier design.
- Wholesalers:Intermediate distributors serve smaller processors with spot-market board purchases and limited technical specification involvement.
- Distributors:Merchant converters and trading houses bridge supply gaps for independent packaging producers lacking direct mill relationships.
Manufacturers hold installed capacity. Retailers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping liquid packaging board procurement patterns as integrated Nordic producers ship surplus kraft pulp to Central European converters while German dairy cooperatives absorb premium carton volumes. Trade flows concentrate along Baltic-Atlantic corridors where captive fiber supply determines contract pricing power.
Germany
Dairy cooperatives in Bavaria and Lower Saxony anchor European demand for aseptic carton formats as oat milk processors seek shelf-stable alternatives to cold-chain distribution. The EU Packaging and Packaging Waste Regulation tightens extended producer responsibility schemes, pushing converters toward certified virgin fiber substrates. The Hamburg-Bremen port cluster handles inbound Nordic pulp shipments that supply Central European board production.
Sweden
Softwood kraft pulp exports from Norrland forests sustain captive supply advantages for integrated board producers serving German and French dairy markets. The EU Green Deal packaging mandates accelerate investment in renewable energy certificate financing for pulp-to-board operations. The Gothenburg industrial corridor concentrates extrusion coating capacity for multi-layer barrier constructions.
France
Beverage bottlers in Île-de-France retrofit filling lines to accept aluminum-barrier carton formats, displacing rigid PET in ambient juice distribution. EFSA food-contact substance notifications raise traceability requirements for imported board grades. The Lyon-Auvergne processing cluster hosts dairy and broth manufacturers seeking extended shelf-life packaging.
United States
Dairy processors in Wisconsin and California convert chilled milk lines to aseptic carton formats to reduce refrigeration infrastructure costs. FDA food-contact substance notifications restrict post-consumer fiber in direct food-contact layers, favoring virgin fiber procurement. The Pacific Northwest pulp base supplies West Coast board converters with bleached kraft for premium applications.
Finland
Integrated pulp-to-board operators leverage Nordic fiber bases to sustain captive supply for liquid packaging grades exported to Central European markets. REACH compliance requirements for barrier coatings tighten material traceability standards across export destinations. The Kotka-Hamina port region handles outbound board shipments to German and Dutch dairy processors.
Liquid Packaging Board Market Competitive Environment
On the supply side, the industry is consolidating around integrated pulp-to-board operators who control captive fiber supply and extrusion coating capacity. Nordic producers leverage softwood kraft advantages while Central European converters face structural pressure from barrier film supply concentration. Two strategic archetypes dominate: backward-integrated forest products groups with captive pulp mills, and equipment-integrated packaging system providers who control filling technology standards. Competitive moves concentrate on selective facility acquisition in Poland and Czechia, and long-term supply agreement lock-ins with German dairy cooperatives.
Within the integrated forest products tier, Stora Enso Oyj and Mondi Group exemplify operators who combine Nordic or Central European pulp bases with coated fiber production capabilities. Tetra Pak International S.A. occupies a distinct position as an equipment-integrated system provider whose filling machine installed base shapes board specification standards. These three entities represent the dominant competitive archetypes: captive fiber supply control, regional coating capacity concentration, and technology-integrated market shaping.
| Leading Market Players |
|---|
| Nippon Paper Industries Co., Ltd. |
| Smurfit Kappa Group |
| Stora Enso Oyj |
| Evergreen Packaging LLC |
| International Paper Company |
| WestRock Company |
| Mondi Group |
| Tetra Pak International S.A. |
| Billerud AB |
| Others |
Value Chain & Pricing Dynamics
Nordic softwood kraft pulp concentration in Sweden and Finland funnels margin pools toward integrated pulp-to-board operators who control captive fiber supply, while independent converters in Central Europe absorb cost volatility through merchant market exposure. The EU Packaging and Packaging Waste Regulation tightens recycled content mandates that push dairy processors toward virgin fiber premiums, amplifying price dispersion between backward-integrated suppliers and coating-dependent independents.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels in liquid packaging board procurement. Price differentiation rests on certification grade—EU food-contact compliance and BIS certification for imported grades—and volume scale, with German dairy cooperatives locking in multi-year contracts at favorable terms. Cost compression in standard-grade coated fiber is intensifying because polyethylene and aluminum barrier film supply concentrates among Central European converters. Small beverage bottlers and independent packaging producers exhibit highest price sensitivity, while integrated dairy processors with captive filling lines prioritize supply security over unit cost.
Supply Chain Analysis
Softwood kraft pulp feedstock draws from Sweden, Finland, and the Pacific Northwest United States, with Nordic integrated producers sustaining captive supply advantages for liquid packaging grades. Raw material dependencies center on bleached kraft pulp, polyethylene extrusion coatings, and aluminum foil barrier layers. Single-source vulnerability concentrates in multi-layer extrusion coating equipment, where 18-24 month installation cycles compress response windows to demand spikes. Distribution runs through Baltic-Atlantic port corridors—Gothenburg, Kotka-Hamina, and Hamburg-Bremen—linking Nordic fiber bases to Central European dairy and beverage processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid packaging board market is cycling through a recovery phase as aseptic filling technology diffusion and EU Green Deal packaging mandates restart capital expenditure pipelines among dairy and beverage processors. Pulp cost volatility and barrier film supply concentration create temporary margin dislocation that favors integrated operators with captive fiber supply.
For Market Incumbents: Entrench Nordic fiber base advantages through selective facility acquisition in Poland and Czechia, where independent converters face capital gaps and coating capacity constraints. Secure long-term supply agreements with German dairy cooperatives before renewable energy certificate financing narrows the capital cost differential for merchant market participants. Prioritize extrusion coating capacity expansion to capture barrier film premiums that independent board producers cannot replicate. For New Entrants and Emerging Players: Poland and Czechia present underpenetrated territory where independent board producers lack backward integration into pulp supply and multi-layer coating capabilities. Target oat milk and plant-based broth processors in Germany seeking shelf-stable formats, as these segments lack established supplier relationships with integrated Nordic operators. Pursue toll-coating partnerships with existing extrusion lines to bypass 18-24 month equipment lead times while building specification credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Central European converters who acquired coating capacity during prior expansion cycles but now face fiber grade scarcity and regulatory compliance cost escalation. Five-to-ten year viability hinges on successful backward integration or strategic sale to integrated pulp-to-board operators. Monitor BIS and FDA food-contact certification completion timelines as inflection indicators for coated fiber grade commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp Supply | Nordic softwood kraft ownership insulates margin pools from merchant pulp volatility. |
| Multi-Layer Extrusion Coating Capacity Expansion | Central European dairy processors demand aluminum-barrier constructions that independents cannot source. |
| Long-Term Supply Agreement Lock-Ins | German cooperatives seek carton supply security amid EU recycled content mandate tightening. |
| Renewable Energy Certificate Financing Structures | Green credit mechanisms narrow capital cost gaps between integrated and merchant producers. |
| Selective Facility Acquisition in Poland and Czechia | Independent converters face structural pressure from barrier film supply concentration and fiber grade scarcity. |
Study Parameters
Cross-validation between primary interviews with dairy procurement directors, beverage bottler technical managers, pulp mill operations heads, and extrusion coating specialists anchors the qualitative findings in operational reality. Secondary validation draws from EU Packaging and Packaging Waste Regulation filings, FDA food-contact substance notification databases, Nordic pulp export statistics, and SEC disclosures from integrated forest products groups. Bottom-up demand modeling across carton format types and top-down supply assessment across captive pulp bases triangulate volume estimates.
Calibration against historical capacity utilization rates and announced expansion timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include product format, barrier complexity tier, fiber grade provenance, end-user scale, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating aseptic filling line retrofit rates and EU extended producer responsibility scheme implementation pace. Industry-specific inputs include softwood kraft pulp price indices and extrusion coating equipment order backlogs.
Practitioners should monitor pulp supply disruptions in Norrland forests, BIS certification review delays for imported grades, and renewable energy certificate financing uptake rates for early signals of forecast revision. Cross-checking against EU dairy cooperative procurement contract disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Cushioned Mailer Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Commercial Paper Bags Market