
 Paperboard Bowl Market | 2026-2036
Paperboard Bowl Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Bowl Market Analytics
Food service buyer concentration is pivoting toward national quick-service chains and third-party delivery aggregators that standardize packaging specifications across thousands of locations. Huhtamaki Oyj leverages its European manufacturing footprint to supply coated and compostable bowl grades to pan-regional restaurant groups. Georgia-Pacific LLC anchors North American demand through integrated pulp-to-converted-product operations that control raw material cost exposure. Dart Container Corporation competes on high-volume single-wall and insulated double-wall formats for institutional catering contracts.
Paperboard bowls are rigid food containers manufactured from bleached or unbleached kraft fiber, typically weighing 200–400 gsm and formed through pressurized molding or die-cutting with rolled rims for structural integrity; they serve as primary vessels for hot soups, grain bowls, and prepared meals in away-from-home consumption settings. Compostable and microwave-safe product types command premium positioning as operators seek to eliminate plastic lid pairings and expand reheatable menu options. Double-wall constructions dominate hot-food applications where insulation drives consumer handling satisfaction, while single-wall formats occupy cost-sensitive retail and institutional segments with lower performance thresholds.
The FDA regulates food-contact substances and coating migration limits for paperboard bowls distributed in the United States, while the EU Packaging and Packaging Waste Directive establishes extended producer responsibility and recyclability targets that reshape material selection across European supply chains. China's GB standards for food packaging paper impose heavy-metal and fluorescent-whitener limits that determine import eligibility and domestic production compliance. Stakeholders must monitor evolving state-level bans on per- and polyfluoroalkyl substances in food packaging, as these restrictions are proliferating beyond initial adopter jurisdictions and will force coating technology transitions within the next regulatory cycle.
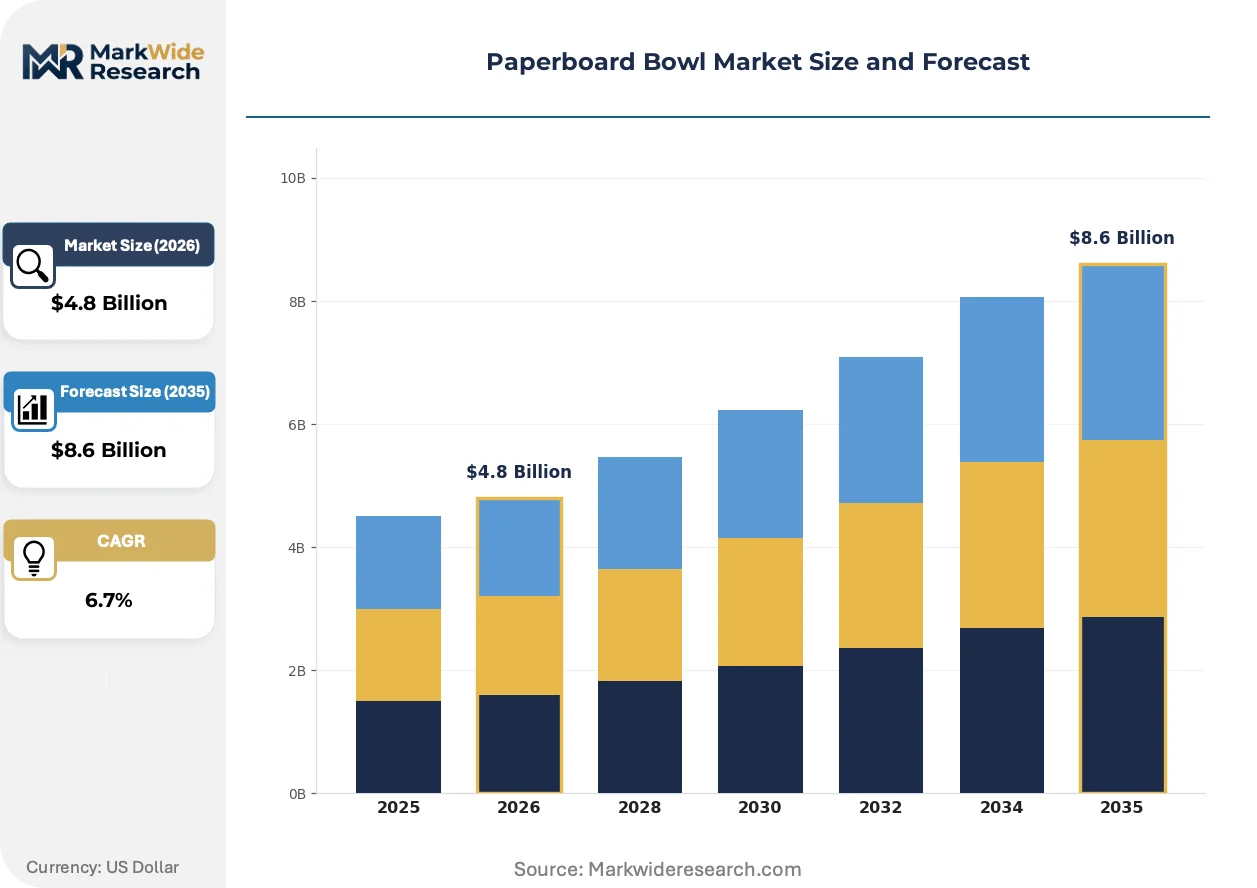
Market Dynamics
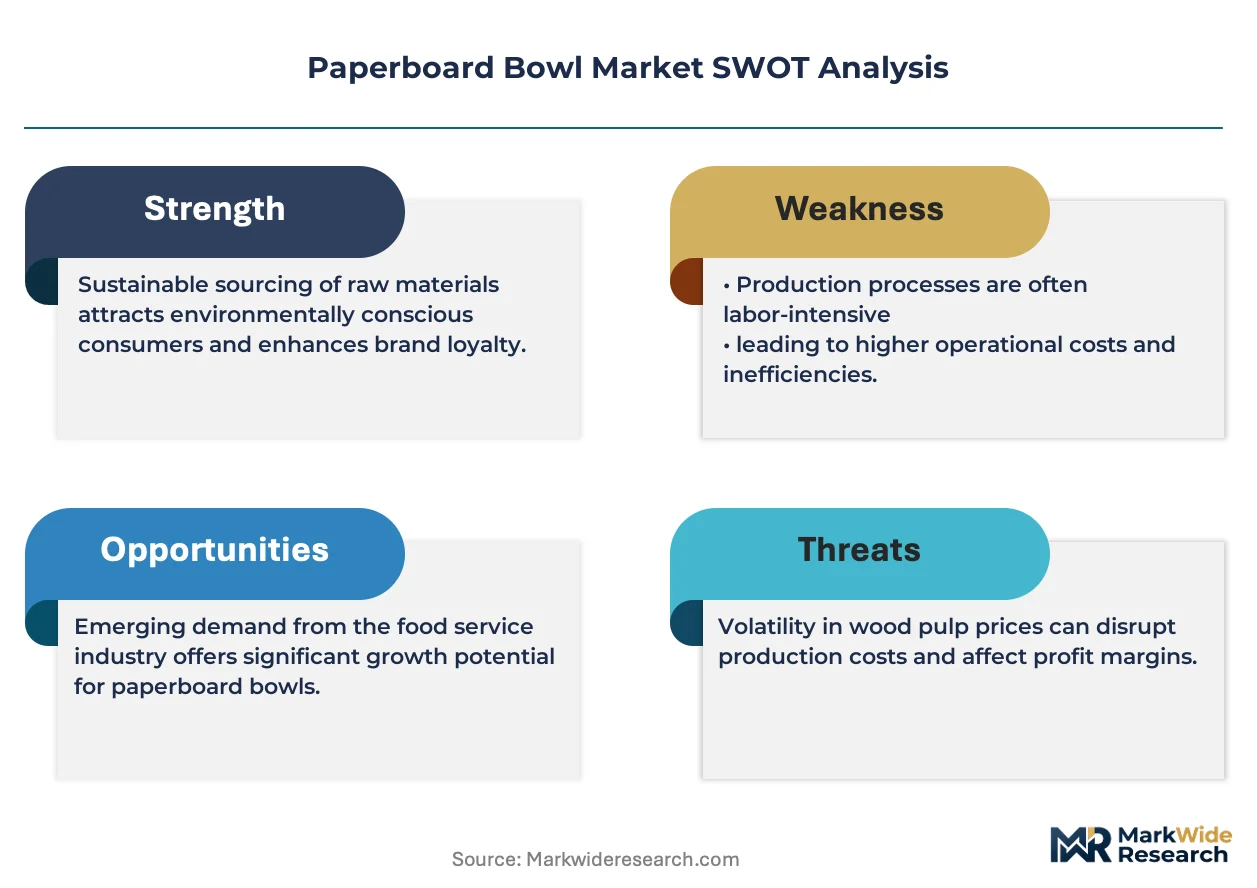
Quick-service restaurant chains and third-party delivery aggregators are consolidating procurement power, forcing bowl manufacturers to standardize specifications across multi-thousand-location networks while absorbing compliance costs from proliferating PFAS bans.
Growth Catalysts
- EU Single-Use Plastics Directive:This framework mandates plastic reduction targets across member states, accelerating substitution toward fiber-based alternatives in food service applications.
- Compostable coating chemistry:Advances in bio-based barrier technologies eliminate plastic lid requirements while enabling microwave-safe reheating for prepared meal operators.
- Germany:The country's scaling sustainable packaging infrastructure and dense food delivery network concentration create concentrated demand for certified compostable bowl grades.
Market Restraints
- Pulp fiber cost volatility:Kraft fiber prices fluctuate with energy and chemical input costs, compressing converter margins during supply tightness.
- Coating technology transition costs:PFAS-free barrier development requires capital-intensive R&D and line reconfiguration without immediate price recovery mechanisms.
- China's GB standards:Heavy-metal and fluorescent-whitener limits for food packaging paper create import eligibility friction and domestic compliance overhead.
Strategic Opportunities
- India:Underpenetrated organized food service and emerging delivery infrastructure present whitespace for coated bowl adoption as plastic restrictions tighten.
- Institutional healthcare catering:Hospital and senior living contracts seek insulated double-wall formats with tamper-evident features for patient meal programs.
- Extended producer responsibility schemes:EU Packaging and Packaging Waste Directive incentives reward recyclability investments with fee reductions and preferential procurement status.
Industry Challenges
- Food-contact chemist talent scarcity:Migration testing expertise for novel barrier coatings remains concentrated among a limited pool of specialized laboratories and regulatory consultants.
- State-level PFAS patchwork:Inconsistent per- and polyfluoroalkyl substance restrictions across US jurisdictions force product-line fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Bowl Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Microwave Safe, Compostable End Use: Food Service, Retail, Catering, Institutional Material: Recyclable, Biodegradable, Coated, Uncoated Size: Small, Medium, Large, Oversized |
| Companies Covered | Huhtamaki Oyj, Dart Container Corporation, Georgia-Pacific LLC, Graphic Packaging International, LLC, WestRock Company, International Paper Company, Pactiv Evergreen Inc., WinCup, Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Bowl Market Evolving Landscape
Barrier coating chemistry and molding automation are converging to reshape production economics while regulatory deadlines compress technology adoption timelines across converter operations.
Water-based and bio-based barrier coatings are electrifying competitive positioning in hot-food segments. Quick-service chains in the United States are specifying these grades for soup and grain bowl applications at accelerating volumes. The technology is electrifying margin compression for conventional polyethylene-coated alternatives while enabling premium pricing for compostable-certified product lines.
REACH restrictions on persistent organic pollutants are tightening acceptable substance thresholds for food-contact materials across European supply chains. Manufacturers serving EU markets must reformulate coatings and validate alternatives through ECHA notification procedures. Pan-regional restaurant groups are consolidating supplier qualification around pre-certified compliant grades to de-risk cross-border distribution.
Aggregator-driven standardization is consolidating packaging specifications across independent restaurant networks. Third-party delivery platforms in China and Germany are mandating uniform bowl dimensions and lid interchangeability across their partner bases. This specification tightening favors converters with scale economies and multi-market certification portfolios over regional specialists.
Paperboard Bowl Market Segmentation
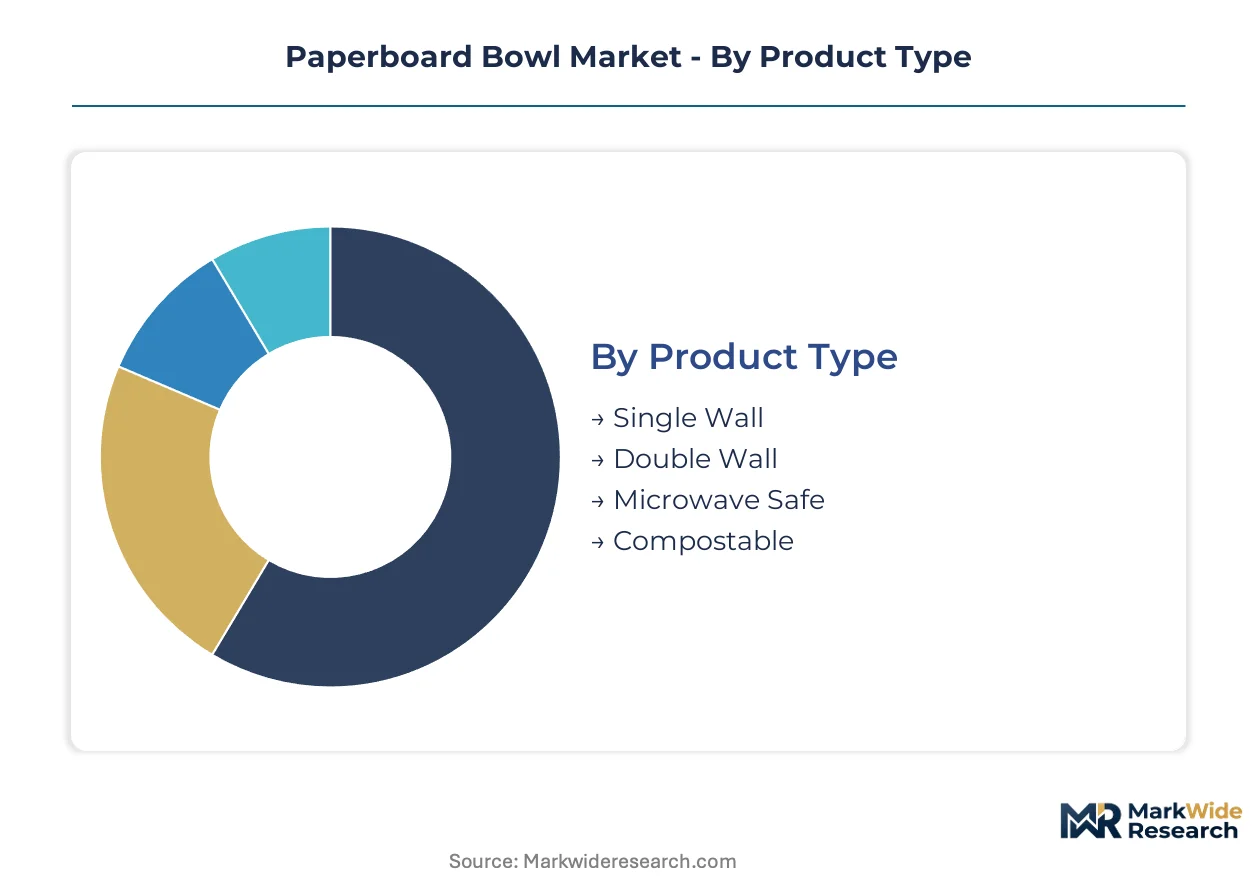
Paperboard bowl procurement decisions hinge on thermal performance requirements, disposal infrastructure availability, and menu-specific reheating protocols. Converter margins compress or expand dramatically across these segment boundaries based on coating chemistry complexity and volume scale.
Product Type:
Operators select wall construction and barrier chemistry based on food temperature at service and end-of-life disposal pathways available to consumers.
- Double Wall:Insulated constructions using two kraft fiber layers separated by an air gap maintain food temperatures above 60°C for 15+ minutes. Quick-service chains in Germany and the United States specify these formats for soup and grain bowl applications where handling comfort drives repeat purchase.
- Compostable:Bio-based barrier coatings derived from polylactic acid or aqueous dispersions eliminate plastic lid pairings and satisfy BPI or TÜV OK compost HOME certification requirements. Municipal composting infrastructure penetration in California and Vermont accelerates specification velocity for this grade.
- Single Wall:Cost-optimized 200-250 gsm constructions serve cold prepared meals and retail deli applications where insulation is unnecessary.
- Microwave Safe:Susceptor-compatible coatings withstand 800W reheating without delamination or odor transfer, expanding prepared meal operator menu flexibility.
Double Wall leads on scale; Compostable leads on momentum.
End Use:
Volume concentration and specification standardization intensity vary sharply across buyer categories, with aggregator-mediated channels imposing the tightest dimensional and performance tolerances.
- Food Service:Quick-service restaurants and third-party delivery aggregators in China, Germany, and the United States consolidate procurement across thousands of locations, mandating uniform bowl dimensions and lid interchangeability. PFAS-free coating transitions absorb compliance costs without immediate price recovery mechanisms in this channel.
- Institutional:Hospital and senior living contracts demand tamper-evident features and insulated double-wall formats for patient meal programs. Healthcare procurement committees prioritize liability reduction over unit cost minimization, sustaining premium positioning for certified food-contact grades.
- Retail:Supermarket deli and meal-kit applications favor single-wall constructions with polyethylene barriers where consumer disposal follows conventional waste streams.
- Catering:Event and corporate dining operators balance presentation requirements against transport durability, often specifying custom-printed double-wall formats at lower volumes.
Food Service commands procurement volume; Institutional sustains margin premiums.
Material:
Regulatory deadlines for per- and polyfluoroalkyl substance elimination are forcing coating technology transitions that resegment supplier capabilities.
- Coated:Polyethylene-extruded or aqueous-barrier-treated surfaces control moisture and grease migration for hot, wet, or oily foods. FDA migration limits and EU Packaging and Packaging Waste Directive recyclability targets determine coating chemistry eligibility across export markets.
- Biodegradable:Uncoated or bio-based-barrier grades engineered for industrial composting environments serve operators in jurisdictions with organics diversion mandates.
- Recyclable:Standard fiber grades compatible with mixed-paper collection streams dominate markets lacking composting infrastructure.
- Uncoated:Dry-food applications and cost-minimized retail segments use bare kraft fiber without barrier protection.
Coated maintains installed base dominance; Biodegradable climbs the fastest.
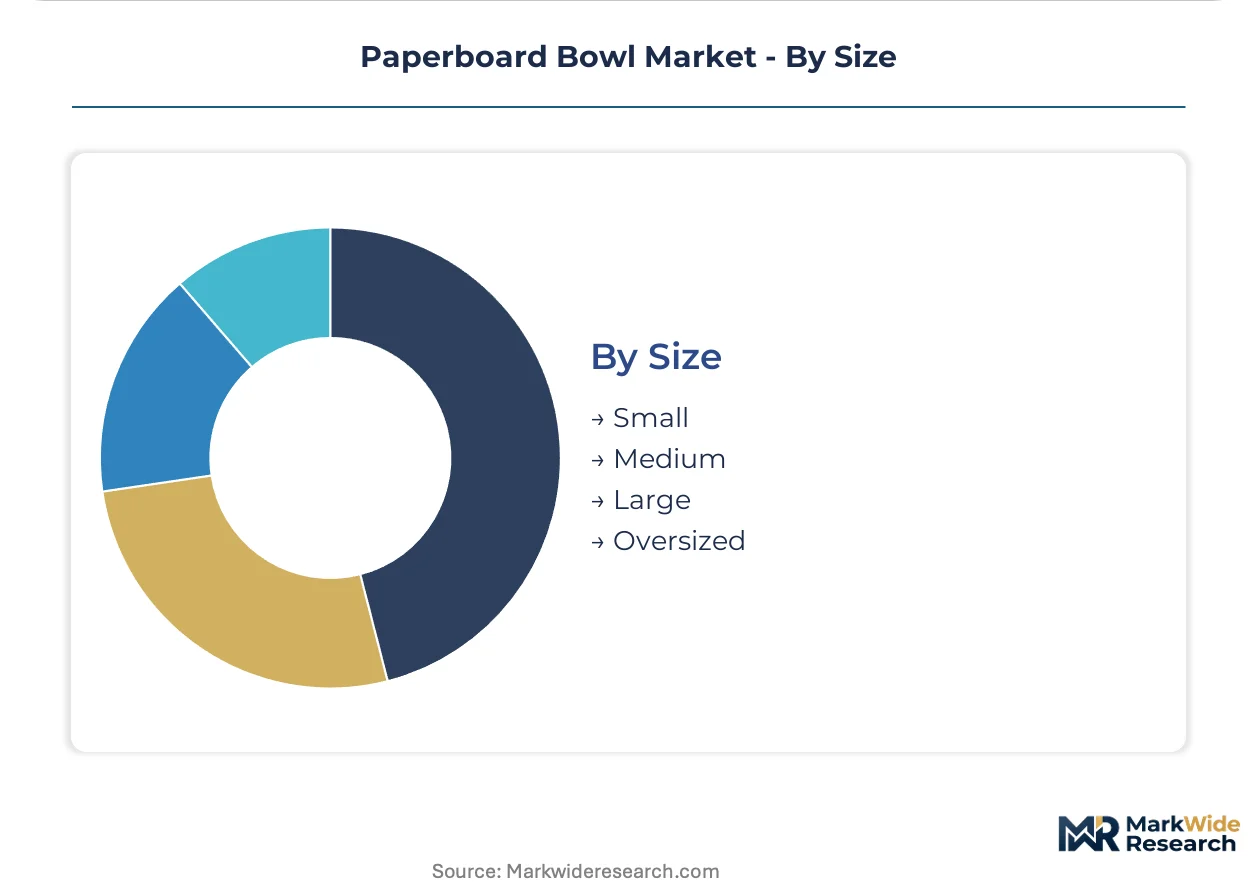
Size:
Menu engineering and delivery platform standardization are collapsing historical dimensional variety toward aggregator-preferred formats.
- Medium:450-550 ml capacities match grain bowl and soup portions across major quick-service chain specifications. Third-party delivery platforms in China mandate this format for lid interchangeability across partner restaurants.
- Large:700-900 ml constructions accommodate family-size portions and multi-component meals for catering and retail meal-kit applications.
- Small:250-350 ml formats serve dessert, side dish, and children's meal segments with lower per-unit fiber consumption.
- Oversized:1000+ ml capacities address niche catering and shared-meal applications at limited volume scale.
Medium locks in platform standardization; Large gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany scales compostable bowl infrastructure faster than the United States, while China's delivery platforms impose stricter dimensional standardization than any other market. National regulatory deadlines and aggregator procurement power are diverging regional growth trajectories.
United States
Quick-service chains and third-party delivery platforms consolidate procurement across thousands of locations, mandating PFAS-free coating transitions. FDA migration limits for food-contact substances determine coating chemistry eligibility. California and Vermont municipal composting infrastructure accelerates certified compostable bowl specification velocity.
Germany
Dense food delivery networks and pan-regional restaurant groups concentrate demand for TÜV OK compost HOME certified grades. EU Packaging and Packaging Waste Directive extended producer responsibility schemes reward recyclability investments. The Ruhr industrial corridor hosts converter operations supplying coated and compostable bowl grades across European markets.
China
Third-party delivery aggregators mandate uniform bowl dimensions and lid interchangeability across partner restaurant networks. GB standards for food packaging paper impose heavy-metal and fluorescent-whitener limits on import eligibility and domestic production. Yangtze River Delta manufacturing clusters scale pressurized molding capacity for medium-format 450-550 ml specifications.
India
Organized food service penetration and emerging delivery infrastructure create whitespace for coated bowl adoption as plastic restrictions tighten. FSSAI food safety standards govern food-contact material compliance for domestic and imported packaging. Maharashtra and Gujarat industrial corridors attract converter investments targeting institutional catering and quick-service restaurant supply.
Japan
Prepared meal and convenience store channels sustain premium positioning for microwave-safe and insulated double-wall formats. METI circular economy guidelines shape packaging material selection and end-of-life disposal requirements. Kanto region converters supply high-performance barrier coatings for hot-food applications in dense urban consumption markets.
Paperboard Bowl Market Competitive Landscape
North American producers anchor the scale-driven tier; European specialists hold the certified-compostable premium segment. The vendor base stratifies across integrated pulp-to-converted-product operators, regional molding specialists, and diversified packaging conglomerates. Three archetypes dominate: backward-integrated fiber controllers, coating technology licensors, and aggregator-qualified volume suppliers. Capacity expansion in Asia-Pacific and strategic partnerships for PFAS-free barrier development constitute the primary competitive moves.
Among Nordic-based packaging specialists, Huhtamaki Oyj exemplifies the pan-regional certification archetype serving EU quick-service networks. Georgia-Pacific LLC and Dart Container Corporation represent North American volume leadership, with the former anchoring integrated pulp operations and the latter occupying institutional catering contract positions. These three entities illustrate the geographic and capability bifurcation shaping procurement qualification requirements.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Dart Container Corporation |
| Georgia-Pacific LLC |
| Graphic Packaging International, LLC |
| WestRock Company |
| International Paper Company |
| Pactiv Evergreen Inc. |
| WinCup |
| Berry Global Group, Inc. |
| Others |
Value Network & Pricing Analysis
Barrier coating chemist concentration in the Ruhr industrial corridor and Yangtze River Delta drives labor-cost differentials that widen spreads between premium compostable grades and commodity polyethylene-coated alternatives. PFAS-free formulation expertise commands wage premiums that converters pass through to quick-service chains seeking certified product lines.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for medium-format single-wall constructions. Pricing stratifies across certified compostable, PFAS-free standard, and conventional polyethylene-coated tiers. Price differentiation hinges on BPI or TÜV OK compost certification status and volume scale across multi-thousand-location procurement contracts. Cost compression in conventional coated grades is intensifying because pulp fiber volatility and energy input spikes compress converter margins without corresponding price recovery mechanisms. Institutional healthcare buyers exhibit lowest price sensitivity as liability reduction priorities override unit cost minimization, while retail deli operators remain most cost-conscious.
Supply Chain Analysis
Kraft fiber supply rests on integrated pulp operations in the United States, Finland, and Brazil that control raw material cost exposure for major converters. Bleached and unbleached kraft fiber, aqueous barrier coatings, and bio-based polylactic acid formulations constitute critical input dependencies. Single-source vulnerability concentrates in specialty coating chemical supply from German and Japanese producers serving EU and North American markets. Distribution runs through converter-direct relationships with quick-service restaurant procurement teams and third-party delivery platform specification committees, bypassing traditional packaging distribution intermediaries for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paperboard bowl market functions as a stable compounder where regulatory-driven plastic substitution sustains predictable demand expansion across food service channels.
For Market Incumbents: Cement backward integration into kraft pulp supply to insulate margin compression from fiber cost volatility. Secure multi-year PFAS-free coating technology licenses from specialty chemical partners before regulatory deadlines force reactive procurement. Priority lever: converter consolidation around pan-regional certification portfolios that qualify supply across EU and North American quick-service networks simultaneously. For New Entrants and Emerging Players: Begin with institutional healthcare catering contracts in India's Maharashtra and Gujarat corridors where organized food service penetration remains underdeveloped and tamper-evident insulated formats command premium positioning. Target senior living and hospital patient meal programs where procurement committees prioritize liability reduction over cost minimization. Go-to-market angle: partner with regional molding specialists for double-wall format production while importing certified compostable coating chemistry under technology licensing arrangements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional molding specialists lacking pan-regional certification portfolios but possessing pressurized molding capacity and established quick-service relationships. Long-term viability frames around five-to-ten-year regulatory compliance windows where PFAS elimination mandates and extended producer responsibility schemes reward pre-certified asset bases. Signal to watch: state-level PFAS ban proliferation beyond initial adopter jurisdictions accelerating coating technology transition timelines and stranded asset risk for non-compliant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Technology Licensing | Secures ECHA-compliant barrier chemistry before REACH restrictions tighten substance thresholds. |
| Backward Integration into Kraft Pulp | Captures captive fiber supply insulating margin compression from energy and chemical input volatility. |
| Pan-Regional Certification Portfolio | Qualifies supply across FDA, EU Packaging and Packaging Waste Directive, and China's GB standards simultaneously. |
| Healthcare Catering Contract Capture | Locks in insulated double-wall volumes where liability reduction priorities sustain premium pricing. |
| Aggregator Platform Qualification | Mandates uniform bowl dimensions and lid interchangeability across third-party delivery partner networks. |
Research Methodology
Multiple input streams — converter operations data, quick-service procurement specifications, and regulatory filing documentation — were reconciled through structured primary interviews with coating technology licensors, food service packaging procurement directors, and composting facility operators. Secondary validation drew from FDA food-contact substance filings, ECHA REACH registration databases, EU Packaging and Packaging Waste Directive implementation reports, and China's GB standards compliance records. Bottom-up volume modeling across product type, end use, material, and size segments was triangulated against top-down market sizing derived from pulp-to-converted-product capacity analysis.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included wall construction type, barrier chemistry grade, end-use channel intensity, and regional regulatory cluster. CAGRs were derived from curve-fitting historical procurement volume trajectories against plastic substitution elasticity estimates and food delivery platform expansion rates. Industry-specific forecast inputs incorporated municipal composting infrastructure penetration curves and state-level PFAS ban adoption timelines.
Caveats apply where pulp fiber cost spikes, coating technology transition delays, or municipal composting infrastructure shortfalls could materially shift the outlook. Forecasts reflect assumptions around regulatory deadline adherence and quick-service chain specification standardization velocity. A small set of named triggers — EU extended producer responsibility fee structures, US state-level PFAS prohibition proliferation, and China's delivery platform dimensional mandates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Coated Duplex Board Market