
 Gardening Tools Market | 2026-2036
Gardening Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Gardening Tools Market Analysis
Modular battery-platform bundling is rebalancing buyer choice across the gardening tools landscape, as consumers favor interchangeable power systems that reduce total cost of ownership across multiple implements. Husqvarna Group leverages its proprietary battery ecosystem to sustain repeat purchases and lock in residential loyalty. Stanley Black & Decker anchors its position through deep retail penetration and professional-grade sub-brands. Deere & Company competes by extending its commercial landscaping heritage into compact residential equipment lines.
Gardening tools encompass hand-operated and motorized implements designed for soil cultivation, plant maintenance, and landscape management, typically fabricated from hardened stainless steel or aluminum alloys with ergonomic polymer grips to reduce repetitive strain during extended use. Power tools in this category incorporate brushless electric motors or two-stroke combustion engines generating between 20V and 56V equivalent output for cutting, trimming, and cultivation tasks. Hand tools maintain the largest volume base due to universal accessibility and minimal maintenance requirements, while power tools capture disproportionate value as lithium-ion battery platforms command premium positioning. Professional gardeners and landscape contractors drive replacement cycles for high-durability pruning tools, where margin pools concentrate around carbide-tipped cutting edges and telescoping handle mechanisms.
The EPA regulates emissions from gasoline-powered outdoor equipment under Phase 3 standards, compelling manufacturers toward electrified product architectures, while the EU F-Gas Regulation and REACH directives constrain material choices and refrigerant-based maintenance systems in commercial-grade machinery. OSHA ergonomic guidelines influence handle design and vibration-dampening specifications for professional-use tools in the United States. Stakeholders must monitor battery-platform interoperability standards and regional decarbonization timelines to align R&D roadmaps with shifting compliance thresholds and procurement preferences.
Market Dynamics
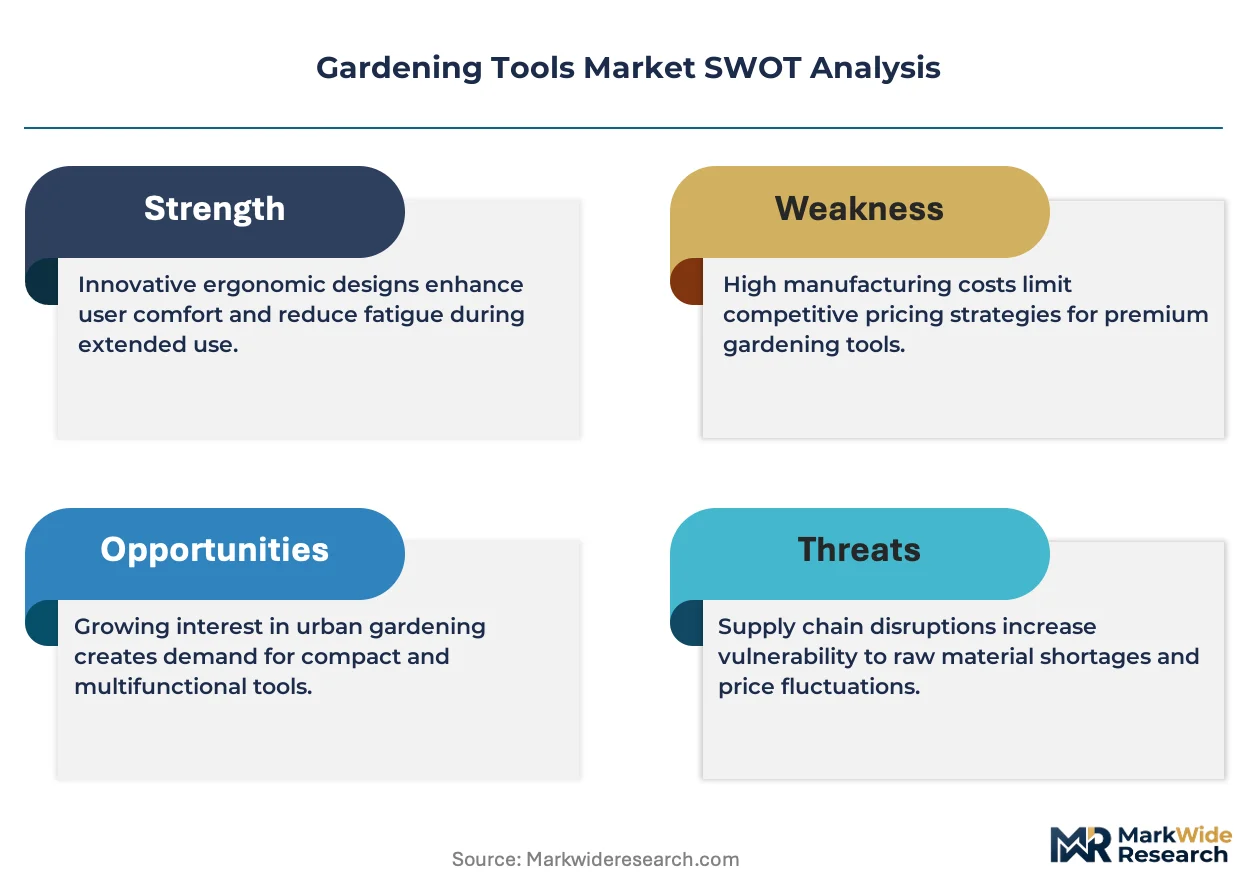
Battery-platform standardization is compressing replacement cycles and locking residential buyers into proprietary ecosystems, while EPA Phase 3 emissions standards accelerate gasoline engine phase-out in handheld equipment.
Growth Catalysts
- EPA Phase 3 Standards:The EPA's tightened emissions regulations for small spark-ignition engines are compelling manufacturers to electrify product lines, opening replacement demand across gasoline-dependent categories.
- Urban Gardening Participation:Residential homeowners in dense metropolitan areas are adopting compact battery-powered tools as balcony and community gardening participation expands.
- Lithium-Ion Energy Density Gains:Advances in cell chemistry are extending runtime per charge, reducing the performance gap between cordless and gasoline-powered equipment for professional users.
Market Restraints
- Battery Raw Material Concentration:Cobalt and lithium processing capacity concentrates in China, creating supply vulnerability for manufacturers outside that supply base.
- EU F-Gas Regulation:The regulation constrains refrigerant-based maintenance systems in commercial-grade machinery, limiting service revenue models for landscape contractors.
- Manual Tool Substitution:Hand-operated implements retain cost and reliability advantages for occasional residential users, capping power tool penetration in price-sensitive segments.
Strategic Opportunities
- German Landscaping Service Expansion:Professional grounds maintenance contractors in Germany are consolidating, creating concentrated procurement channels for durable equipment bundles.
- OSHA Ergonomic Guidelines:The guidelines are creating specification advantages for vibration-dampening and handle-design innovations in professional-use categories.
- Brushless Motor Convergence:Integration of brushless motors with smart battery management is enabling predictive maintenance services and usage-based pricing models.
Industry Challenges
- REACH Compliance Timeline:The EU's chemical registration requirements are extending material qualification cycles, delaying product launches for polymer grip and coating innovations.
- Interoperability Standardization Delays:Absence of cross-brand battery compatibility standards fragments platform investments and complicates fleet management for landscape contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gardening Tools Market |
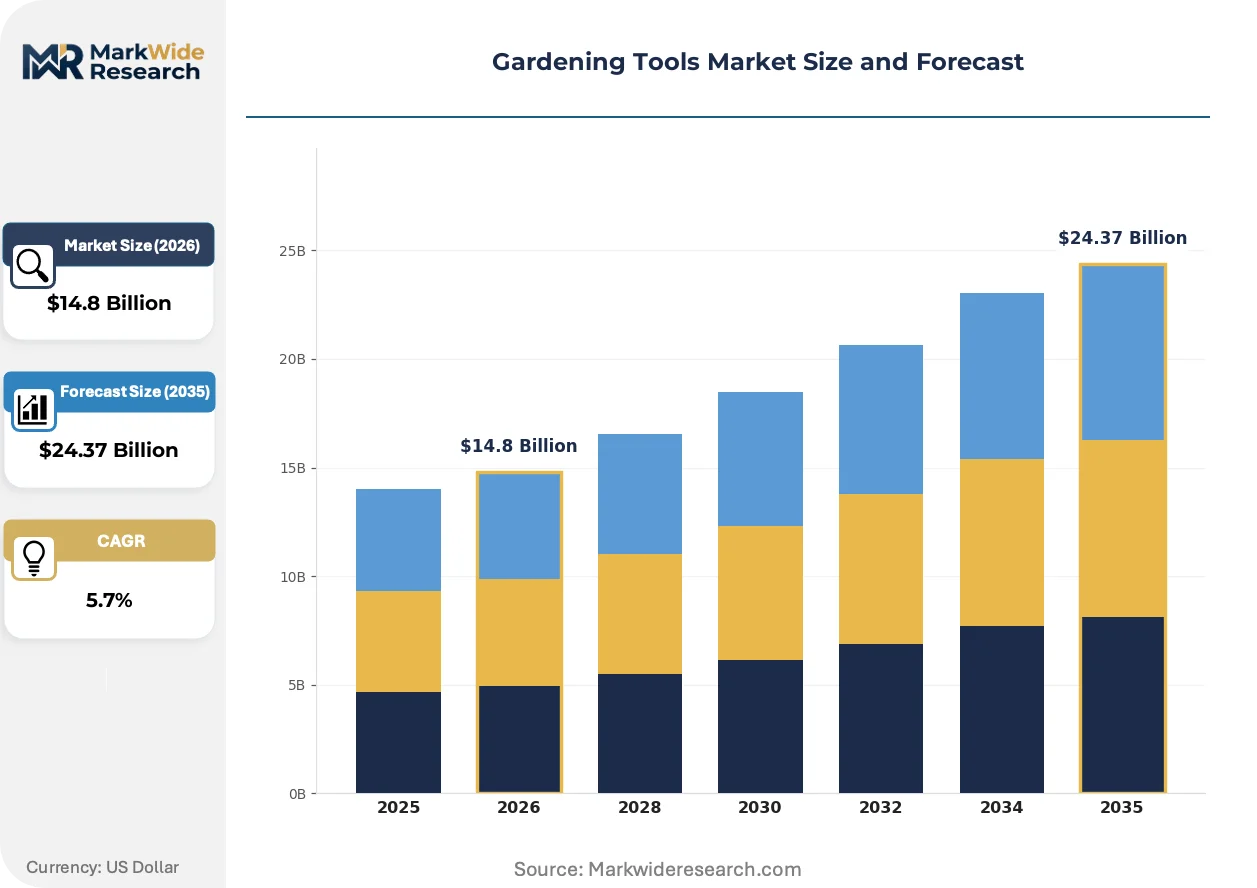
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Hand Tools, Power Tools, Pruning Tools, Soil Tools Material: Stainless Steel, Plastic, Aluminum, Wood End User: Residential Users, Professional Gardeners, Landscape Contractors, Institutional Buyers Distribution Channel: Online Sales, Retail Stores, Wholesale Distributors, Garden Centers |
| Companies Covered | Fiskars Group, Husqvarna Group, Stanley Black & Decker, The Toro Company, Robert Bosch GmbH, Deere & Company, American Honda Motor Co., MTD Products, Briggs & Stratton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gardening Tools Market Emerging Trajectories
Electrification is restructuring competitive advantage around software-defined battery platforms rather than mechanical engineering, compressing traditional equipment differentiation and opening service-based revenue models.
Modular battery ecosystems are unifying power delivery across multiple implement categories. Residential buyers are consolidating purchases around single-platform households to reduce charger redundancy and battery inventory costs. This unification is compressing brand-switching flexibility and elevating ecosystem breadth as a primary purchase criterion over individual tool performance metrics.
The EU F-Gas Regulation is eliminating hydrofluorocarbon-based maintenance systems from commercial-grade equipment specifications. Manufacturers are redesigning thermal management around solid-state alternatives, extending development timelines for professional product lines. German landscape contractors are accelerating fleet refresh cycles to preempt serviceability constraints.
Subscription-based equipment access is displacing outright ownership among municipal grounds maintenance departments. These buyers are prioritizing uptime guarantees and inclusive maintenance over capital expenditure control. The shift is most visible in United States state park systems and university campus operations, where budget predictability outweighs long-term cost optimization.
Gardening Tools Market Segmentation
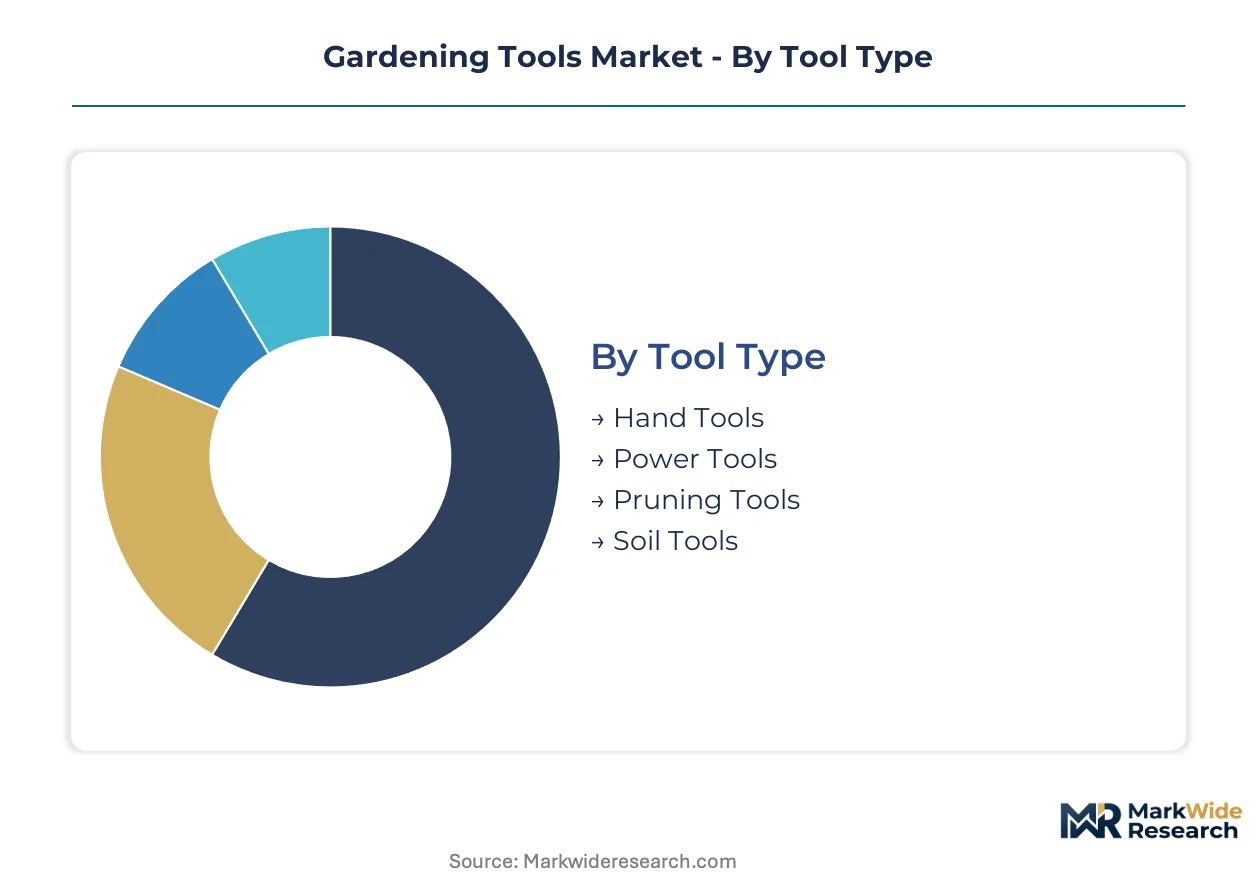
Gardening tools fragment across four structural dimensions that shape procurement patterns and margin capture. Tool type and material composition determine manufacturing intensity, while end-user identity and distribution channel govern pricing power and brand loyalty mechanics.
Tool Type:
Standardization dominates at the commodity end of this spectrum, with customization concentrated in professional-grade power equipment where battery-platform ecosystems create proprietary lock-in.
- Hand Tools:Implements fabricated from hardened stainless steel or aluminum alloys with ergonomic polymer grips require minimal maintenance and command universal accessibility across price tiers. Demand concentrates among occasional residential users in Germany and the United States, where reliability expectations and tool longevity drive replacement cycles measured in decades rather than seasons.
- Power Tools:Brushless electric motors and two-stroke combustion engines generating 20V to 56V equivalent output define this segment's technical architecture. Landscape contractors in China are consolidating purchases around lithium-ion battery platforms that reduce fuel costs and satisfy tightening EPA Phase 3 emissions standards for handheld equipment.
- Pruning Tools:Carbide-tipped cutting edges and telescoping handle mechanisms address professional durability requirements.
- Soil Tools:Cultivation implements span manual spades to motorized tillers across residential and commercial applications.
Most installed capacity flows through Hand Tools. Expansion is steepest in Power Tools.
Material:
Cost tier stratification separates premium metallurgy from commodity polymers, with mid-range aluminum capturing volume in weight-sensitive applications.
- Stainless Steel:Hardened grades resist corrosion in soil-contact applications and maintain edge retention for cutting implements. Professional gardeners in the United States specify stainless for pruning tools where sterilization between uses prevents disease transmission across commercial nursery operations.
- Aluminum:Lightweight alloys reduce operator fatigue in extended-use scenarios and resist oxidation without surface treatments. Residential buyers in Germany favor aluminum-shafted long-handle tools for balcony gardening where storage constraints demand compact, multi-function implements.
- Plastic:Glass-reinforced polymers dominate ergonomic grip components and housing enclosures.
- Wood:Traditional ash and hickory handles persist in heritage-positioned product lines.
Volume leadership belongs to Stainless Steel. Aluminum is gaining share fastest among weight-conscious segments.
End User:
Customer type determines specification intensity, with institutional procurement emphasizing total cost of ownership and residential buyers prioritizing upfront accessibility.
- Residential Users:Urban gardening participation in dense metropolitan areas drives compact battery-powered tool adoption for balcony and community cultivation spaces. EPA Phase 3 standards are accelerating gasoline engine displacement among this segment as emissions compliance costs erode small-engine economics.
- Landscape Contractors:Fleet management requirements and uptime guarantees dominate procurement criteria for commercial grounds maintenance operations. German landscaping service consolidation is creating concentrated procurement channels where durable equipment bundles and predictive maintenance services command premium positioning.
- Professional Gardeners:Individual practitioners balance tool performance against capital constraints.
- Institutional Buyers:Municipal grounds maintenance departments and university campus operations are shifting toward subscription-based equipment access models.
Residential Users account for the largest unit volume. Landscape Contractors show the steepest expansion trajectory as service sector professionalization accelerates.
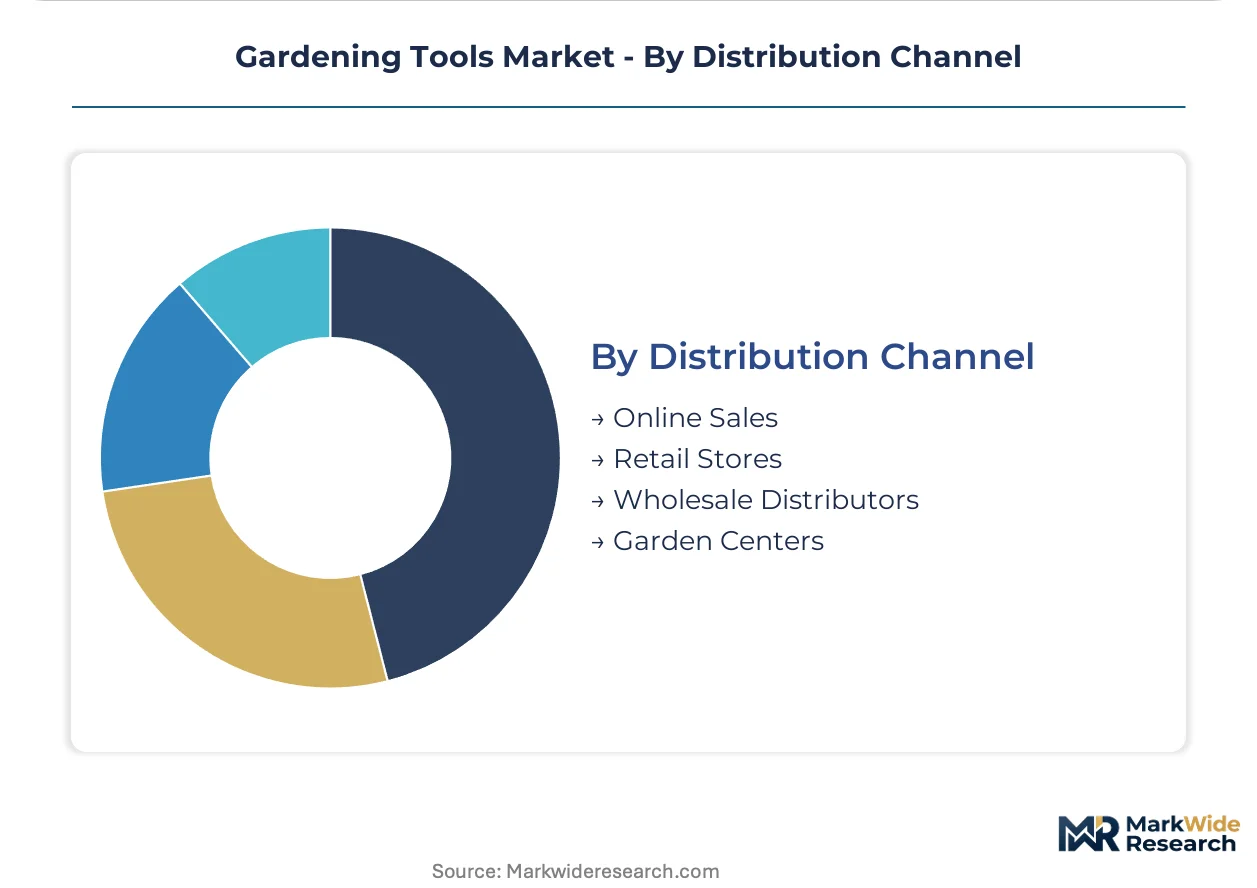
Distribution Channel:
Geography shapes channel effectiveness, with urban density favoring direct digital access and rural markets sustaining wholesale intermediation.
- Online Sales:Direct-to-consumer platforms and marketplace aggregators capture research-intensive purchases where specification comparison and battery-platform compatibility verification precede transaction. United States residential buyers increasingly initiate purchase journeys through digital channels before completing transactions at retail for immediate product availability.
- Retail Stores:Mass merchants and home improvement chains anchor brand visibility and enable tactile evaluation for first-time buyers. Deep retail penetration strategies from major manufacturers concentrate shelf space allocation in United States and German markets where seasonal demand surges require responsive inventory positioning.
- Wholesale Distributors:Landscape supply houses and agricultural cooperatives serve professional contractor fleets.
- Garden Centers:Specialty retailers provide expert consultation and localized product curation.
Retail Stores maintain the broadest installed base. Online Sales are climbing the fastest as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern gardening tools industry traces its mechanized origins to nineteenth-century English manufacturing centers, where Sheffield's steelworks supplied hardened implements to colonial agricultural markets and established quality benchmarks still referenced in contemporary metallurgy.
United States
Residential homeowners in dense metropolitan corridors drive compact battery-powered tool procurement for balcony and community cultivation spaces. EPA Phase 3 emissions standards compel manufacturers toward electrified handheld equipment architectures, accelerating gasoline engine displacement. Landscape contractors in California's Central Valley and Florida's nursery belts consolidate fleet purchases around lithium-ion platforms.
Germany
Professional grounds maintenance contractors in metropolitan regions consolidate procurement channels for durable equipment bundles. The EU F-Gas Regulation constrains refrigerant-based maintenance systems in commercial-grade machinery, prompting fleet refresh cycles. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate precision manufacturing for carbide-tipped cutting implements.
China
Urban gardening participation in tier-one cities propels demand for lightweight aluminum-shafted implements suited to compact storage constraints. The country's national environmental regulator enforces dual carbon goals that favor battery-powered motor adoption over two-stroke combustion engines. Manufacturing gravity concentrates in Zhejiang and Guangdong provinces, where OEMs supply global private-label programs.
Japan
Professional gardeners balance tool performance against capital constraints in precision-oriented nursery operations. METI efficiency guidelines influence brushless motor integration and smart battery management specifications. Industrial districts in Niigata and Mie prefectures maintain heritage-positioned forging traditions for premium hand tool exports.
United Kingdom
Institutional buyers in municipal grounds maintenance departments shift toward subscription-based equipment access models prioritizing uptime guarantees. REACH compliance timelines extend material qualification cycles for polymer grip innovations. Specialist retailers in the Southeast and Midlands regions curate localized product assortments for heritage garden restoration projects.
Gardening Tools Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with deep retail penetration and proprietary battery ecosystem control. Tier-one positioning concentrates around manufacturers commanding shelf space allocation in United States and German seasonal demand surges. Three archetypes dominate: battery-platform ecosystem builders, heritage-brand metalworkers, and diversified power equipment conglomerates. Strategic moves center on M&A for complementary technology assets and vertical integration into cell chemistry supply.
Within the diversified conglomerate tier, Husqvarna Group and Stanley Black & Decker exemplify platform-centric strategies that lock residential buyers into proprietary battery ecosystems. Deere & Company anchors the commercial landscaping heritage segment, extending compact residential equipment lines from its agricultural machinery expertise. These three entities occupy positions where ecosystem breadth supersedes individual tool performance metrics in purchase decisions.
| Leading Market Players |
|---|
| Fiskars Group |
| Husqvarna Group |
| Stanley Black & Decker |
| The Toro Company |
| Robert Bosch GmbH |
| Deere & Company |
| American Honda Motor Co. |
| MTD Products |
| Briggs & Stratton Corporation |
| Others |
Supply Flow & Price Mechanics
Captive battery cell production in Zhejiang and Guangdong provinces anchors both supply security and pricing power for gardening tool manufacturers, as in-house lithium-ion capacity insulates against cobalt and lithium processing bottlenecks while enabling platform-locked premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the gardening tools landscape, with differentiation hinging on battery-platform ecosystem breadth and brushless motor integration. Premium tiers capture professional landscape contractors through predictive maintenance bundling and extended runtime guarantees. Cost compression in economy hand tools is intensifying because Chinese OEMs flood private-label channels with aluminum-shafted implements. Occasional residential users in price-sensitive segments exhibit highest price sensitivity, while fleet-buying German contractors prioritize total cost of ownership over upfront expenditure.
Supply Chain Analysis
Trans-Pacific container rates and intra-Asian trucking costs exert outsized influence on landed costs for gardening tool distributors, compressing margins on bulky motorized equipment more severely than compact hand implements. Manufacturing gravity centers on China, Germany, and the United States, with Zhejiang province feeding global private-label demand and Baden-Württemberg precision-machining carbide-tipped cutting edges. Supply chains draw from lithium carbonate, rare-earth magnets, and hardened stainless steel feedstocks. Single-source vulnerability concentrates in cobalt hydroxide processing. Distribution runs through mass merchant retail chains in seasonal demand corridors, supplemented by direct-to-consumer platforms for battery-platform compatibility verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gardening tools function as a regulatory compounder, with EPA Phase 3 emissions standards forcing gasoline engine displacement and accelerating replacement cycles across handheld equipment categories.
For Market Incumbents: Anchor ecosystem defensibility by deepening proprietary battery-platform interoperability and preempting cross-brand standardization efforts. Expand captive lithium processing partnerships to offset raw material concentration in Chinese refining capacity. Defend against emerging direct-to-consumer entrants by tightening retail shelf space allocation ahead of seasonal demand surges.
For New Entrants and Emerging Players: Capture white-space in subscription-based equipment access models targeting municipal grounds maintenance departments and university campus operations. Penetrate United States state park systems with uptime-guarantee service bundles. Pursue white-label partnerships with Zhejiang-based OEMs to bypass capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Roll-up economics work for regional landscaping service consolidators because German contractor procurement channel concentration creates captive equipment demand pools. Five-to-ten year viability hinges on electrification transition completion and battery-platform winner-take-most dynamics. Monitor OSHA ergonomic guideline adoption velocity as the inflection signal for vibration-dampening technology premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Proprietary ecosystems from Husqvarna and Stanley Black & Decker lock residential buyers into repeat purchase cycles. |
| Backward Integration into Cell Chemistry | Captive lithium processing insulates manufacturers from Chinese cobalt refining bottlenecks and price volatility. |
| Subscription Service Launch | Municipal grounds maintenance departments in United States state park systems prioritize budget predictability over ownership. |
| Ergonomic Certification Investment | OSHA guideline compliance creates specification advantages for vibration-dampening handle designs in professional categories. |
| Geographic Manufacturing Expansion | Baden-Württemberg and North Rhine-Westphalia clusters serve German landscaping contractor consolidation with localized production. |
Methodological Framework
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each market informing demand calibration and regulatory impact assessment. The research combines structured interviews with product development executives at battery-platform manufacturers, procurement leads at German landscaping service consolidators, retail category managers at United States mass merchants, and aftermarket service heads at commercial equipment distributors. Secondary validation draws from EPA enforcement databases, EU REACH substance registrations, United States customs import records, and SEC 10-K filings from diversified industrial conglomerates. Bottom-up demand modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon, isolating battery-platform premiumization effects from commodity hand tool replacement cycles. The analytical framework models tool type, material composition, end-user archetype, and distribution channel dimensions. CAGRs derive from segment-level growth rate blending weighted by base-year value shares. Forecast inputs incorporate lithium-ion energy density improvement curves and EPA Phase 3 compliance cost pass-through assumptions.
Raw material price spikes, regulatory timeline delays, and battery-platform interoperability standardization failures are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about substitution elasticities and fleet refresh cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Tree Transplanters Market