
 Billhook Market | 2026-2036
Billhook Market Size, Share, and Industry Trends Forecast 2026-2036
Billhook Market Analytics
Buyer concentration in professional landscaping is decoupling from traditional agricultural distributors as independent groundskeeping contractors multiply across Western Europe. Fiskars leverages its Nordic manufacturing footprint to serve this fragmented channel with standardized blade geometries. Condor Tool & Knife anchors its position through El Salvador-forged carbon steel supply to Central American agroforestry cooperatives. Gränsfors Bruk differentiates via hand-forged premium positioning among Swedish conservation authorities.
A billhook is a curved cutting tool with a hooked blade and ergonomic handle, traditionally forged from high-carbon steel with Rockwell hardness between 50 and 55 HRC, designed for severing woody vegetation through a pulling stroke. The implement serves agriculture, forestry, and land management professionals requiring precise coppicing and hedge-laying capabilities. Traditional billhooks retain dominance in heritage conservation and manual hedge-laying applications where blade profile authenticity commands premium positioning. Modern billhooks incorporating stainless steel compositions capture demand from municipal landscaping fleets prioritizing corrosion resistance and reduced maintenance cycles. Specialty billhooks with customized bevel angles concentrate margin pools among professional forestry trainers certifying apprentices in traditional woodland crafts.
EU F-Gas Regulation and REACH compliance frameworks govern chemical treatments in blade coatings and handle preservatives, elevating material documentation burdens for exporters into the European Economic Area. Germany's KBA-equivalent agricultural equipment safety protocols and France's CNIL-adjacent workplace tool traceability requirements shape procurement specifications for public-sector landscaping tenders. Stakeholders must monitor evolving blade steel alloy restrictions under ECHA substance evaluation protocols while assessing captive forging capacity against outsourced Asian supply alternatives.
Market Dynamics
EU Green Deal restoration mandates are accelerating tool replacement cycles among European landscaping contractors, compressing procurement timelines from seasonal purchasing to continuous replenishment models tied to project-based conservation funding.
Growth Catalysts
- EU Green Deal mandates:Restoration targets across member states require specialized vegetation management tools, expanding addressable demand for heritage-compatible cutting implements in coppicing and hedge-laying applications.
- Carbon steel durability standards:Professional forestry crews in Nordic jurisdictions specify Rockwell 50-55 HRC blade specifications, sustaining premium positioning for forged implements over stamped alternatives.
- Heritage conservation funding:National historic landscape preservation programs in England, Wales, and Scotland subsidize traditional tool acquisition, insulating manual hedge-laying practitioners from price-driven substitution.
Market Restraints
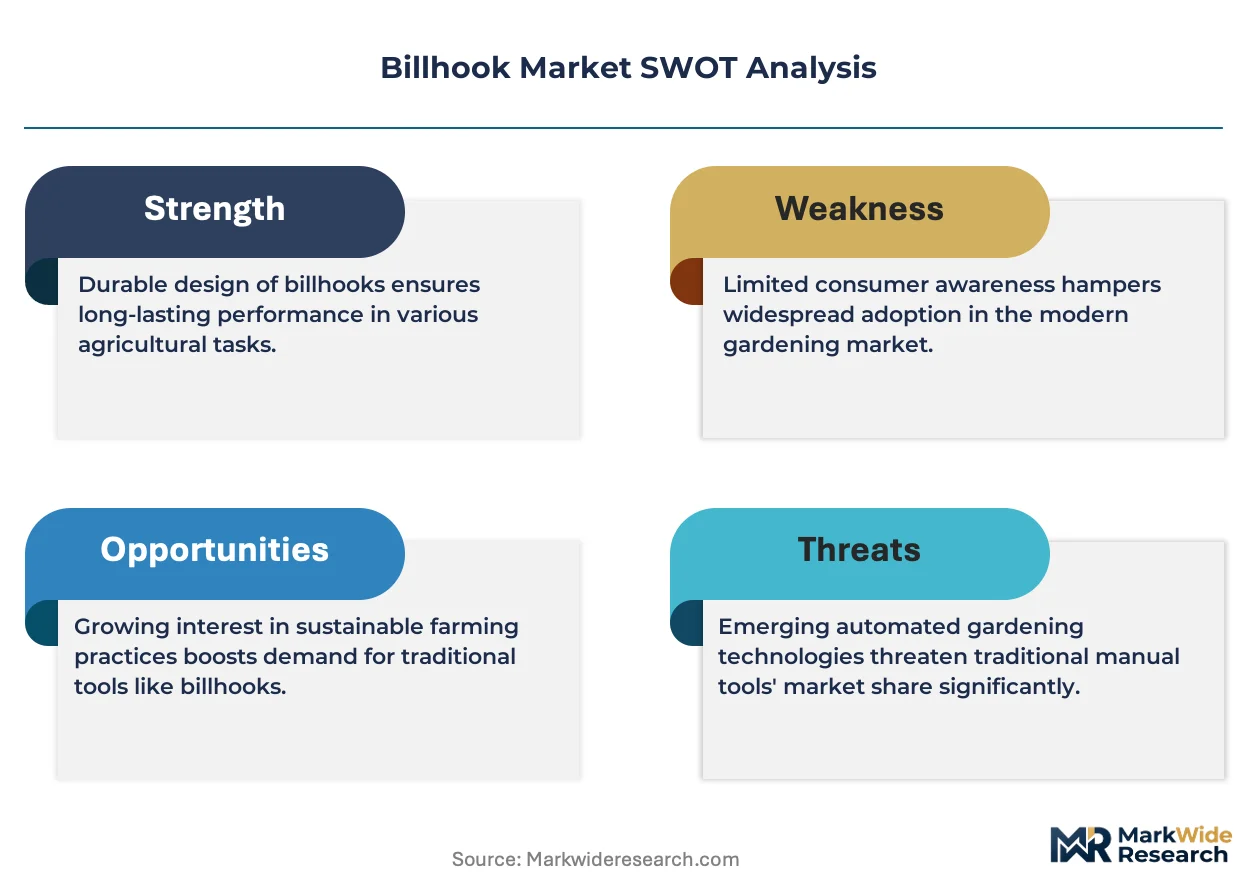
- High-carbon steel input volatility:Scrap steel pricing fluctuations and energy-intensive forging requirements compress margins for European manufacturers dependent on electric arc furnace supply.
- REACH documentation burdens:ECHA substance evaluation protocols for blade coatings and handle preservatives create compliance costs that disproportionately burden small-batch forgers against mass-market competitors.
- Mechanized vegetation management substitution:Brush cutters and hydraulic mulchers displace manual tools in commercial forestry operations, constraining volume growth in professional-grade billhook segments.
Strategic Opportunities
- Portuguese cork handle sourcing:Sustainable Mediterranean material integration addresses ESG procurement criteria for municipal landscaping fleets seeking verifiable supply chain credentials.
- Apprenticeship certification programs:Traditional woodland craft training mandates in England and Scotland create institutional demand for standardized blade geometries among forestry colleges.
- Stainless steel corrosion resistance:Coastal maintenance contracts in Normandy and Brittany specify reduced-maintenance compositions, opening premium positioning for alloy variants in salt-exposure environments.
Industry Challenges
- Master forger skill scarcity:Hand-forging expertise concentration among aging European artisans limits production scaling for premium heritage-authentic product lines.
- CE marking certification timelines:Agricultural equipment safety protocol compliance delays product launches for innovative blade profile designs targeting professional groundskeeping contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Billhook Market |
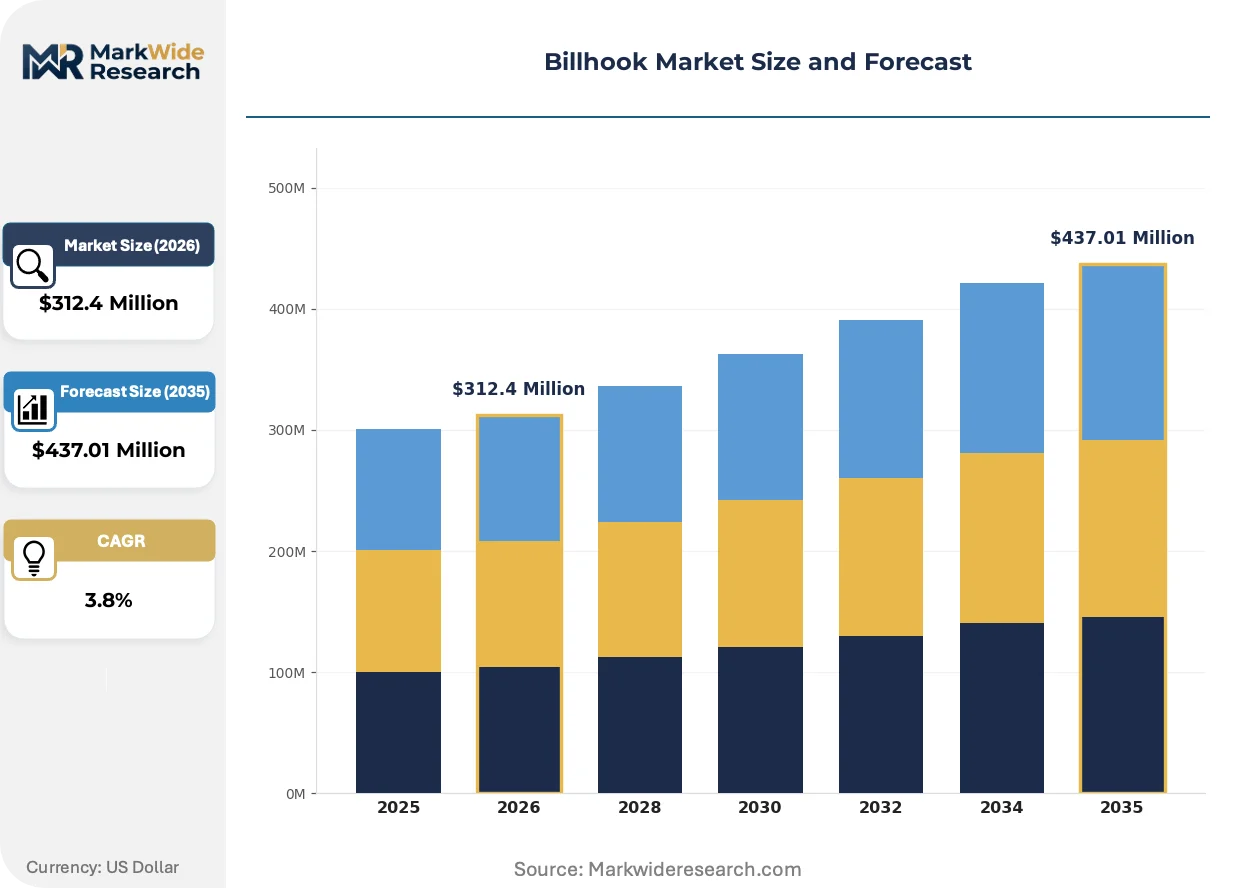
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Billhooks, Modern Billhooks, Specialty Billhooks, Foldable Billhooks Material: Carbon Steel, Stainless Steel, Alloy Steel, Wood End User: Agriculture, Landscaping, Forestry, Gardening Size: Small, Medium, Large, Extra Large |
| Companies Covered | Gerber Gear, Condor Tool & Knife, Fiskars, Tramontina, Collins Tool Company, Härmän Työkalut, Bob Burgess Billhooks, Opinel, Gränsfors Bruk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Billhook Market Evolving Landscape
Material science advances and regulatory disclosure requirements are reconfiguring how blade manufacturers validate performance claims and differentiate across professional, municipal, and heritage market tiers.
Stainless steel blade compositions are converging with laser surface hardening treatments to achieve corrosion resistance without sacrificing edge retention. Municipal landscaping fleets in coastal France and the Netherlands specify these hybrid constructions to reduce replacement frequency in salt-air environments. The convergence is compressing the performance gap between traditional carbon steel and maintenance-reduced alternatives.
REACH substance evaluation protocols now require granular documentation of chemical treatments in anti-corrosion coatings and wood preservatives. German agricultural equipment safety regulators and French workplace traceability authorities coordinate enforcement timelines, creating synchronized compliance windows for exporters. Small-batch forgers face disproportionate testing cost burdens relative to mass-market competitors with dedicated regulatory affairs capacity.
Independent groundskeeping contractors are consolidating procurement authority previously dispersed through agricultural distributor networks. Direct manufacturer relationships now capture specification influence for blade geometry standardization, particularly in hedge-laying and coppicing applications. This channel disintermediation concentrates most visibly in England's commercial estate management sector, where contractor self-identification as craftspeople drives preference for traceable forging provenance.
Billhook Market Segmentation
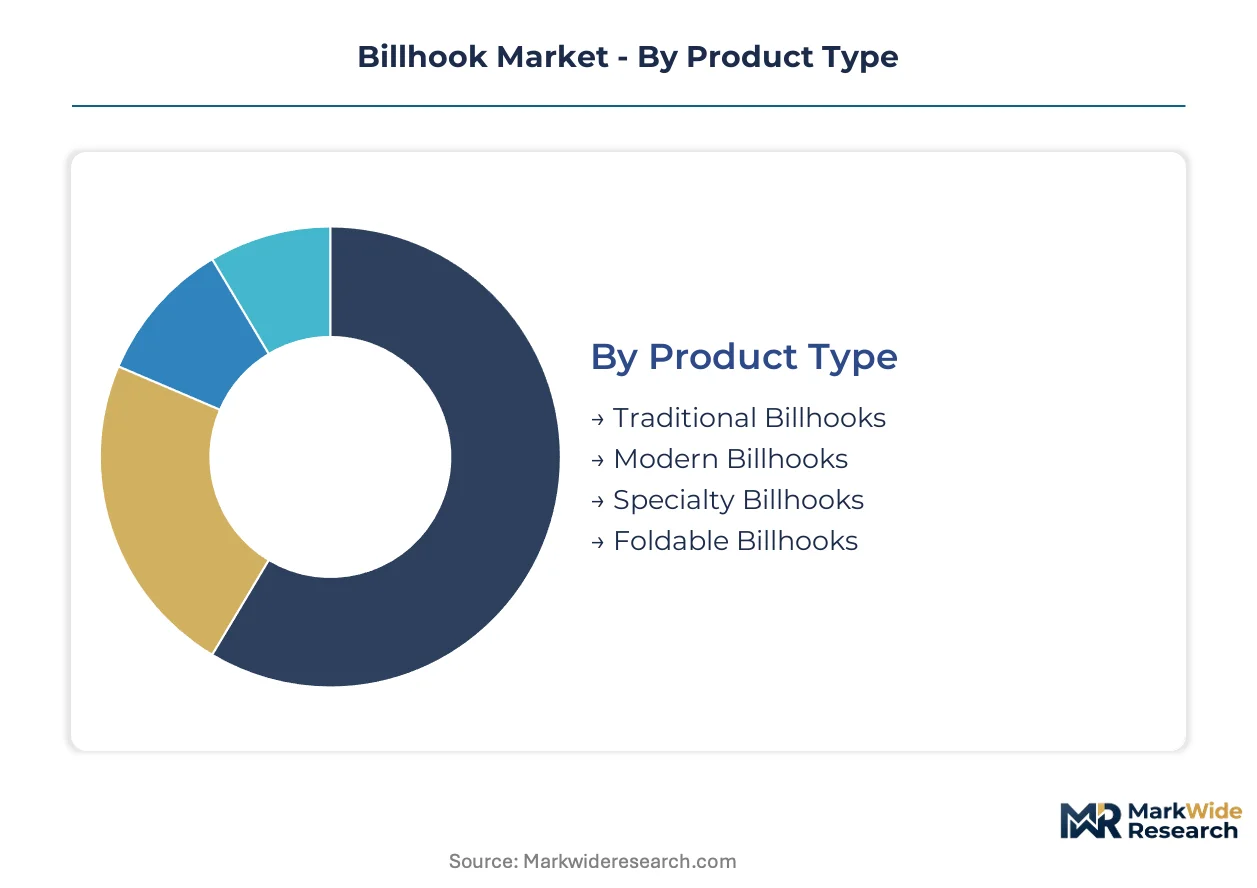
Billhook procurement patterns diverge sharply across tool categories, with heritage-authentic designs commanding premium positioning in conservation-funded applications while corrosion-resistant variants capture municipal fleet contracts. Material composition and end-use specialization create distinct margin pools that manufacturers navigate through targeted forging investments and coating technology choices.
Product Type:
Standalone heritage tools dominate premium positioning, while embedded-system-compatible designs integrate with contractor fleet standardization programs.
- Traditional Billhooks:Hand-forged implements with authentic blade profiles specified at Rockwell 50-55 HRC hardness for heritage hedge-laying and coppicing applications. Swedish conservation authorities and English National Landscape programs subsidize acquisition, insulating this segment from price-driven substitution despite longer production cycles.
- Modern Billhooks:Stainless steel and surface-hardened constructions incorporating laser treatment protocols for corrosion resistance in coastal Normandy and Brittany maintenance contracts. Municipal landscaping fleets prioritize reduced-maintenance cycles over edge retention maximization.
- Specialty Billhooks:Customized bevel angles and ergonomic modifications for professional forestry trainers certifying apprentices in traditional woodland crafts.
- Foldable Billhooks:Compact designs targeting independent groundskeeping contractors requiring transport efficiency across dispersed estate management sites.
Volume placements concentrate in Modern Billhooks; the faster expansion belongs to Specialty Billhooks.
Material:
Cost tier stratification separates premium forged inputs from standardized alloy alternatives, with supply chain documentation requirements reshaping procurement authority.
- Carbon Steel:High-carbon compositions preferred by professional forestry crews in Finland for blade durability under sustained hardwood cutting stress. REACH documentation burdens for surface treatments and anti-corrosion coatings disproportionately burden small-batch forgers dependent on electric arc furnace supply chains.
- Stainless Steel:Corrosion-resistant grades specified by Dutch and French coastal municipalities for salt-air exposure environments, converging with laser surface hardening to narrow performance gaps with traditional carbon steel.
- Alloy Steel:Hybrid compositions balancing edge retention with maintenance reduction for commercial landscaping contractors operating mixed vegetation management portfolios.
- Wood:Portuguese cork and sustainably harvested hardwoods integrated into handle construction for ESG-verifiable supply chain credentials in public-sector tenders.
Carbon Steel retains the largest volume footprint; Stainless Steel is climbing the fastest on coastal infrastructure spending.
End User:
Application maturity separates established agricultural distribution from emerging direct procurement channels among fragmented professional contractors.
- Agriculture:Traditional coppicing and hedge maintenance in mixed farming systems, with procurement authority consolidating from distributor networks toward direct manufacturer relationships.
- Landscaping:Independent groundskeeping contractors across England's commercial estate management sector driving specification influence for blade geometry standardization through self-identification as craftspeople.
- Forestry:Professional crews in Nordic jurisdictions and Central American agroforestry cooperatives prioritizing Rockwell hardness specifications and forging provenance traceability.
- Gardening:Hobbyist and small-scale maintenance applications with price sensitivity and retail channel dependence.
Agriculture maintains established volume leadership; Landscaping posts the steepest expansion trajectory on EU Green Deal project acceleration.
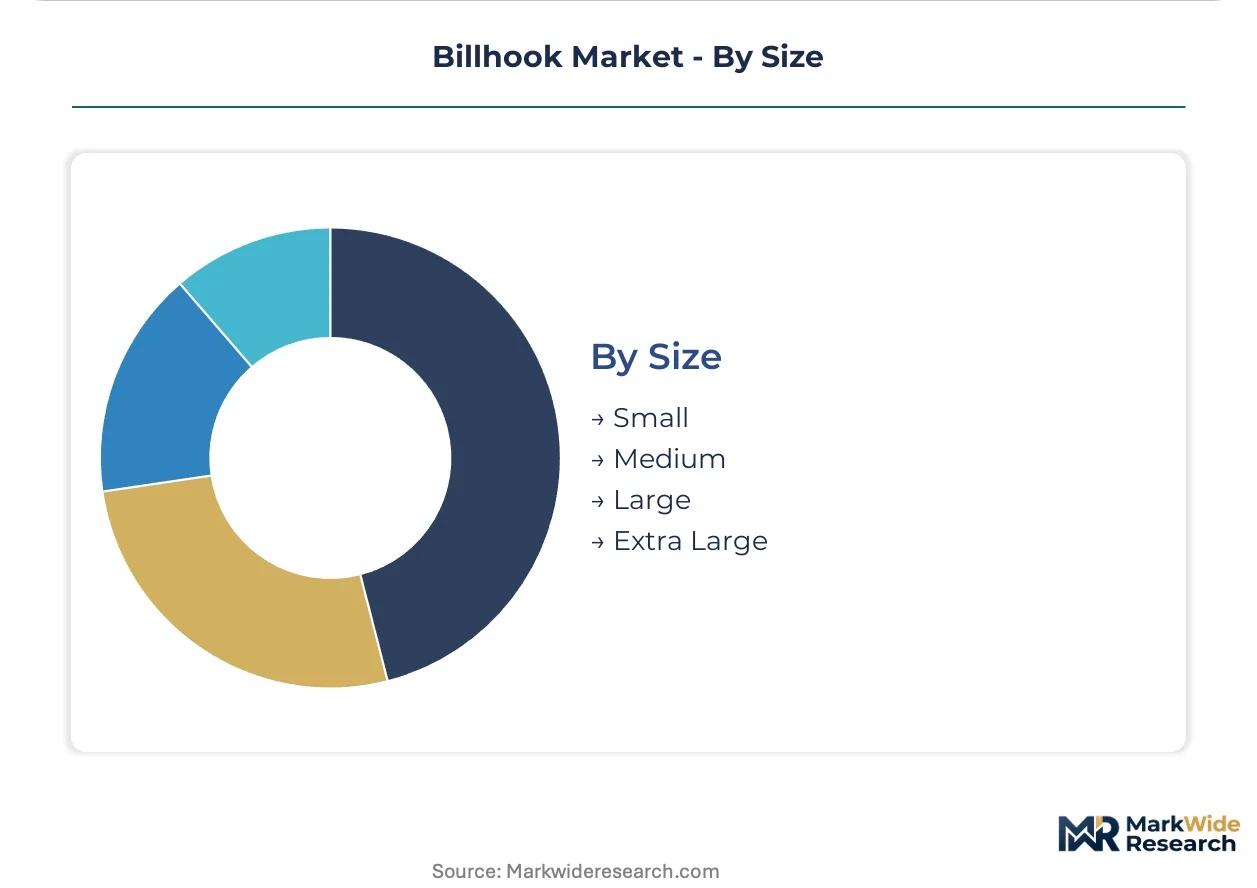
Size:
Customer type and task specialization determine dimensional requirements, with professional segments consolidating around medium specifications for versatility.
- Small:Precision coppicing and detailed hedge-laying work in heritage conservation contexts where maneuverability supersedes cutting capacity.
- Medium:Standardized dimensions dominating professional contractor procurement for balanced reach and control across vegetation types.
- Large:Extended blade profiles for mature woodland management and commercial forestry operations requiring single-stroke severing capacity.
- Extra Large:Specialized implements for industrial-scale vegetation clearance where manual tool substitution persists against mechanized alternatives.
Medium sizes capture the dominant placement share; Large formats gain share fastest on commercial estate management contract scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish iron ore deposits and Finnish forest cover anchor European billhook manufacturing, with Nordic blade forging traditions supplying professional forestry crews across the Baltic rim. German distributor networks and French municipal procurement systems shape continental demand patterns.
Germany
Landscaping contractors in Bavaria and North Rhine-Westphalia are accelerating tool replacement cycles under EU Green Deal restoration mandates. The KBA-equivalent agricultural equipment safety protocols govern public-sector tender specifications. Solingen's blade manufacturing cluster supplies standardized geometries to fragmented groundskeeping channels.
France
Municipal fleets in Normandy and Brittany specify stainless steel constructions for salt-air corrosion resistance. CNIL-adjacent workplace tool traceability requirements shape procurement documentation for conservation-funded hedge-laying projects. The Auvergne-Rhône-Alpes region concentrates heritage-authentic forging for traditional woodland craft certification.
United Kingdom
English National Landscape programs and Scottish forestry colleges subsidize traditional billhook acquisition for manual hedge-laying practitioners. Historic landscape preservation funding insulates heritage-authentic segments from price-driven substitution. The Midlands and Wales host specialized forgers serving commercial estate management contractors.
Finland
Professional forestry crews specify Rockwell 50-55 HRC carbon steel blades for sustained hardwood cutting stress. National blade durability standards sustain premium positioning for forged implements over stamped alternatives. Tampere's metalworking cluster supplies Nordic conservation authorities with traceable forging provenance.
Sweden
Hand-forged premium positioning commands institutional demand from conservation authorities and heritage landscape programs. Gränsfors Bruk anchors domestic supply for traditional coppicing and hedge-laying applications. The Bergslagen mining region provides high-carbon steel feedstock to artisan forgers serving Swedish and export markets.
Billhook Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized heritage-authentic positioning. The vendor base stratifies across mass-market stamped blades, mid-tier forged implements, and premium hand-forged offerings. Nordic manufacturers leverage regional iron ore access and forest industry proximity. Competitive moves concentrate on direct channel cultivation among fragmented landscaping contractors and certification program partnerships with forestry colleges.
Within the Nordic manufacturing tier, Fiskars leverages its regional production footprint to serve standardized procurement channels, while Gränsfors Bruk occupies premium heritage positioning through hand-forged authenticity. Condor Tool & Knife represents Central American supply chain integration, sourcing forged carbon steel to agroforestry cooperatives. These three anchors exemplify geographic specialization strategies—Nordic scale efficiency, Scandinavian artisan premium, and Central American cost-optimized supply—rather than competing directly across identical customer segments.
| Leading Market Players |
|---|
| Gerber Gear |
| Condor Tool & Knife |
| Fiskars |
| Tramontina |
| Collins Tool Company |
| Härmän Työkalut |
| Bob Burgess Billhooks |
| Opinel |
| Gränsfors Bruk |
| Others |
Value Network & Pricing Analysis
Scrap steel price indices cascading from Nordic electric arc furnace suppliers compress margin pools for European forgers while elevating procurement premiums for heritage-authentic implements. Carbon steel input volatility feeds directly into three-tier pricing stratification across premium hand-forged, mid-tier standardized, and economy stamped alternatives.
Pricing Analysis
Warranty and forging-provenance documentation unbundle at the premium tier while municipal fleet contracts absorb maintenance-service bundles into per-unit pricing. Three-tier pricing structure across premium, standard, and economy levels separates conservation-funded heritage tools from corrosion-resistant municipal specifications and disposable retail alternatives. Cost compression in the economy tier intensifies because Asian stamped-blade imports displace European forged alternatives. Municipal landscaping contractors exhibit lowest price sensitivity due to ESG-mandated procurement criteria; hobbyist retail channels face acute substitution pressure from mass-market garden tools.
Supply Chain Analysis
Master forger scarcity across Solingen, Tampere, and Sheffield constrains production scaling for premium heritage-authentic product lines. High-carbon steel feedstock draws from Swedish Bergslagen ore deposits and German Ruhr processing clusters, with Portuguese cork handle materials sourcing from Alentejo cooperatives. Single-source vulnerability concentrates in aging artisan labor pools with limited apprentice pipeline replenishment. Distribution runs through direct manufacturer relationships with fragmented landscaping contractors, bypassing traditional agricultural distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH documentation burdens and mechanized vegetation management substitution are forcing consolidation among small-batch forgers unable to sustain regulatory compliance investments. Market survivors will command specification influence through certification program partnerships and direct channel control.
For Market Incumbents: Extend forging provenance traceability systems to capture institutional procurement mandates from English National Landscape programs and Scottish forestry colleges. Invest in captive laser surface hardening capacity to narrow performance gaps between carbon steel durability and stainless steel corrosion resistance. Brush cutter substitution in commercial forestry and CE marking certification delays for innovative blade profiles demand defensive R&D prioritization. For New Entrants and Emerging Players: Laser surface hardening technology offers a technology-first wedge into coastal municipal fleet contracts in Normandy and Brittany where salt-air corrosion resistance commands premium positioning. Target foldable billhook designs for independent groundskeeping contractors across England's commercial estate management sector, where transport efficiency and self-identification as craftspeople create specification influence. Pursue apprenticeship certification program partnerships with forestry colleges as the primary go-to-market channel. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier forged implement specialists with established CE marking compliance and direct contractor channel relationships in Germany and France. Five-to-ten-year viability hinges on EU Green Deal restoration mandate continuity and heritage conservation funding durability. Monitor ECHA substance evaluation protocol enforcement timelines as the critical inflection signal for compliance cost burden redistribution between mass-market and artisan competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Certification Partnership | English National Landscape program alignment secures subsidized procurement pipelines for manual hedge-laying practitioners. |
| Laser Surface Hardening Investment | Nordic municipal fleet specifications for Rockwell 50-55 HRC corrosion-resistant blades open coastal maintenance contracts. |
| Direct Channel Cultivation | Independent groundskeeping contractor relationships in England bypass agricultural distributor margin extraction. |
| Portuguese Cork Integration | Alentejo-sourced sustainable handle materials satisfy ESG procurement criteria for public-sector landscaping tenders. |
| Apprenticeship Program Anchor | Scottish forestry college standardization mandates create institutional demand for traceable forging provenance. |
Research Methodology
Document review covered trade customs records, ECHA substance evaluation protocols, and EU Green Deal restoration mandate documentation, complemented by interviews with heritage conservation procurement officers, municipal landscaping fleet managers, master forgers in Nordic manufacturing clusters, and agricultural equipment safety regulators. Secondary validation drew from SEC filings of listed tool manufacturers, Nordic iron ore export statistics, and Portuguese cork industry association reports. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from forged implement production capacity estimates.
Segment-level projections incorporated product type stratification across traditional, modern, specialty, and foldable billhooks; material composition tiers spanning carbon steel, stainless steel, alloy steel, and wood; end-user segmentation across agriculture, landscaping, forestry, and gardening; and dimensional specifications from small precision tools to extra-large industrial implements. CAGRs derived from regression analysis against EU conservation funding disbursement trajectories and professional forestry crew tool replacement cycle compression.
Several conditions sit outside the modeled scope, including abrupt termination of heritage conservation subsidies, breakthrough advances in battery-powered brush cutter performance, and trade policy disruptions affecting Swedish iron ore or Portuguese cork supply chains. Forecasts reflect documented assumptions regarding EU regulatory enforcement continuity and artisan labor pool stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Sheep Shearing Equipment Market