
 Pump Feeder Market | 2026-2036
Pump Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Pump Feeder Market Insights
A shortage of certified fluid systems technicians is redrawing competitive boundaries across the pump feeder supply chain. Grundfos Holding A/S leverages its global service academy network to lock in municipal retrofit contracts. SPX FLOW Inc. anchors its position through backward integration into precision dosing controller manufacturing. Watson-Marlow Fluid Technology Group differentiates via peristaltic pump specialization for shear-sensitive pharmaceutical formulations.
A pump feeder is a precision fluid handling device that meters, doses, or transfers liquids and slurries through positive displacement, centrifugal, or peristaltic action at controlled flow rates and pressures, typically constructed from stainless steel, PTFE, or specialized alloys to resist chemical attack and wear. Its primary industrial purpose is to deliver accurate, repeatable volumes of process chemicals, additives, or treatment agents into continuous or batch manufacturing systems. Electric pump feeders command the dominant share across water treatment and chemical processing applications due to their programmability and lower total cost of ownership compared to pneumatic alternatives. The pharmaceutical end user industry generates premium margin pools, as FDA validation requirements and cGMP documentation demands favor suppliers with embedded compliance engineering capabilities.
EPA effluent limitation guidelines and OSHA process safety management standards shape product specifications for US chemical manufacturing installations, while REACH substance restrictions and CE machinery directives govern material selection and safety integration for European market access. The EU F-Gas Regulation accelerates displacement of pneumatic actuation in favor of electric drive architectures, particularly in climate-sensitive industrial zones. Stakeholders must monitor how evolving PFAS restrictions under state-level frameworks and emerging EU drinking water directives recalibrate material compatibility requirements for sealing and diaphragm components.
Market Dynamics
The EU F-Gas Regulation is forcing chemical processors across Germany, France, and the Netherlands to retire pneumatic actuation in favor of electric pump feeder architectures, compressing retrofit timelines and redrawing supplier qualification criteria.
Growth Catalysts
- REACH compliance deadlines:ECHA substance restrictions on legacy sealing materials are compelling European chemical manufacturers to upgrade to PTFE and specialized alloy pump feeders with full material traceability.
- Water treatment automation:Municipal utilities in the US are deploying programmable electric dosing systems to meet tightened EPA effluent limitation guidelines for phosphorus and nitrogen removal.
- Shear-sensitive biologics manufacturing:Peristaltic pump architectures are capturing share in pharmaceutical aseptic processing where diaphragm pumps risk protein denaturation.
Market Restraints
- Specialized alloy input costs:Hastelloy and titanium price volatility constrains margin expansion for corrosion-resistant pump feeder manufacturers serving sulfuric acid and chlorine dioxide applications.
- Certified technician scarcity:Germany's industrial corridor faces acute shortages of fluid systems engineers capable of commissioning integrated metering packages with embedded safety controllers.
- Pneumatic system stranded assets:Facilities with recent pneumatic infrastructure investments face accelerated obsolescence risk under F-Gas phase-down schedules.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with ICH Q7 guidelines creates demand for cGMP-validated dosing systems in active pharmaceutical ingredient production clusters near Hyderabad and Ahmedabad.
- PFAS-free material transition:Emerging state-level restrictions on fluorinated sealing compounds in the US open substitution windows for advanced elastomer and ceramic diaphragm technologies.
- Digital twin integration:Convergence of pump feeder telemetry with predictive maintenance platforms enables outcome-based service models for continuous chemical processing operations.
Industry Challenges
- FDA validation documentation:Pharmaceutical OEMs face 12-18 month certification timelines for new pump feeder installations, compressing product development cycles and freezing specification decisions.
- Legacy control system integration:Brownfield chemical plants struggle to interface modern electric pump feeders with existing SCADA architectures without full distributed control system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pump Feeder Market |
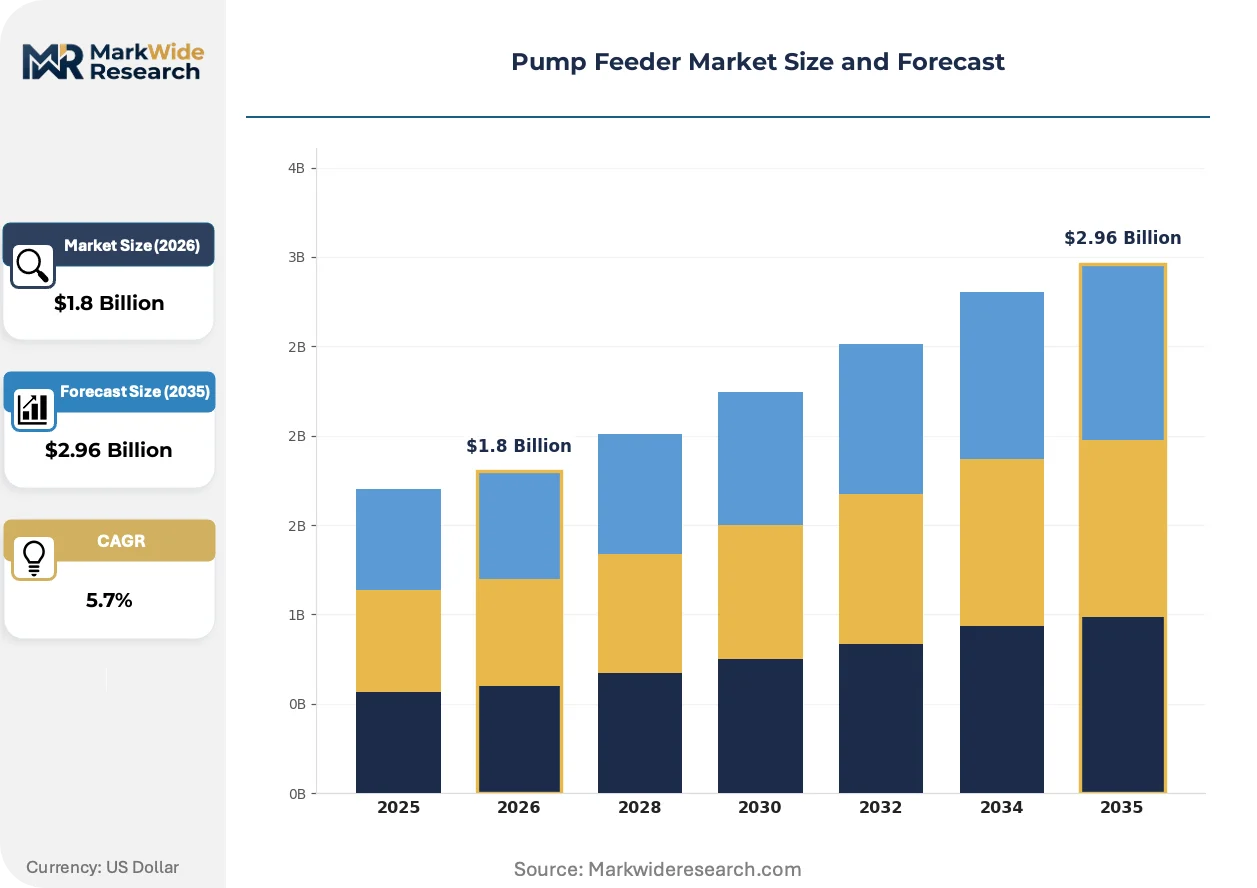
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Hydraulic, Mechanical, Solar Application: Water Treatment, Chemical Processing, Food & Beverage, Pharmaceuticals, Agriculture End User Industry: Municipal Services, Chemical Manufacturing, Food Production, Crop Cultivation, Pharmaceutical Companies Installation Type: Fixed, Portable, Submersible, Magnetic Drive, Diaphragm |
| Companies Covered | SPX FLOW Inc., Grundfos Holding A/S, Watson-Marlow Fluid Technology Group, Dover Corporation, IDEX Corporation, ProMinent GmbH, Graco Inc, Verder Group, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pump Feeder Market Trends and Innovations
Electrification of fluid handling systems is intersecting with predictive analytics and material science advances to redefine how process industries specify, procure, and maintain precision dosing equipment.
Advanced ceramic diaphragm technology is decomposing the traditional elastomer-dominated sealing landscape in aggressive chemical service. Semiconductor-grade alumina and silicon carbide formulations now withstand hydrofluoric acid and hot concentrated caustic environments that destroy PTFE and Viton alternatives. Specialty chemical manufacturers in Germany's Rhine-Neckar region are specifying ceramic-diaphragm pump feeders for chlorine dioxide generation, eliminating the 6-12 month replacement cycles of conventional elastomer seals.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are recalibrating material selection protocols for pump feeder wetted components. ECHA's 2023 proposal to classify additional PFAS as substances of very high concern threatens fluoropolymer lining and seal inventories across European water treatment and chemical processing installations. End users in the Netherlands and Belgium are accelerating qualification of alternative barrier materials including PEEK and ultra-high molecular weight polyethylene for diaphragm and tubing applications.
After-sales service unbundling is fragmenting traditional bundled procurement patterns in municipal water treatment. US utilities are separating pump feeder hardware acquisition from commissioning, calibration, and maintenance contracts, enabling specialized service providers to capture recurring revenue streams. California's regional water quality control boards are driving this shift through performance-based contracting mandates that tie vendor payments to verified dosing accuracy over multi-year operating periods.
Pump Feeder Market Segmentation
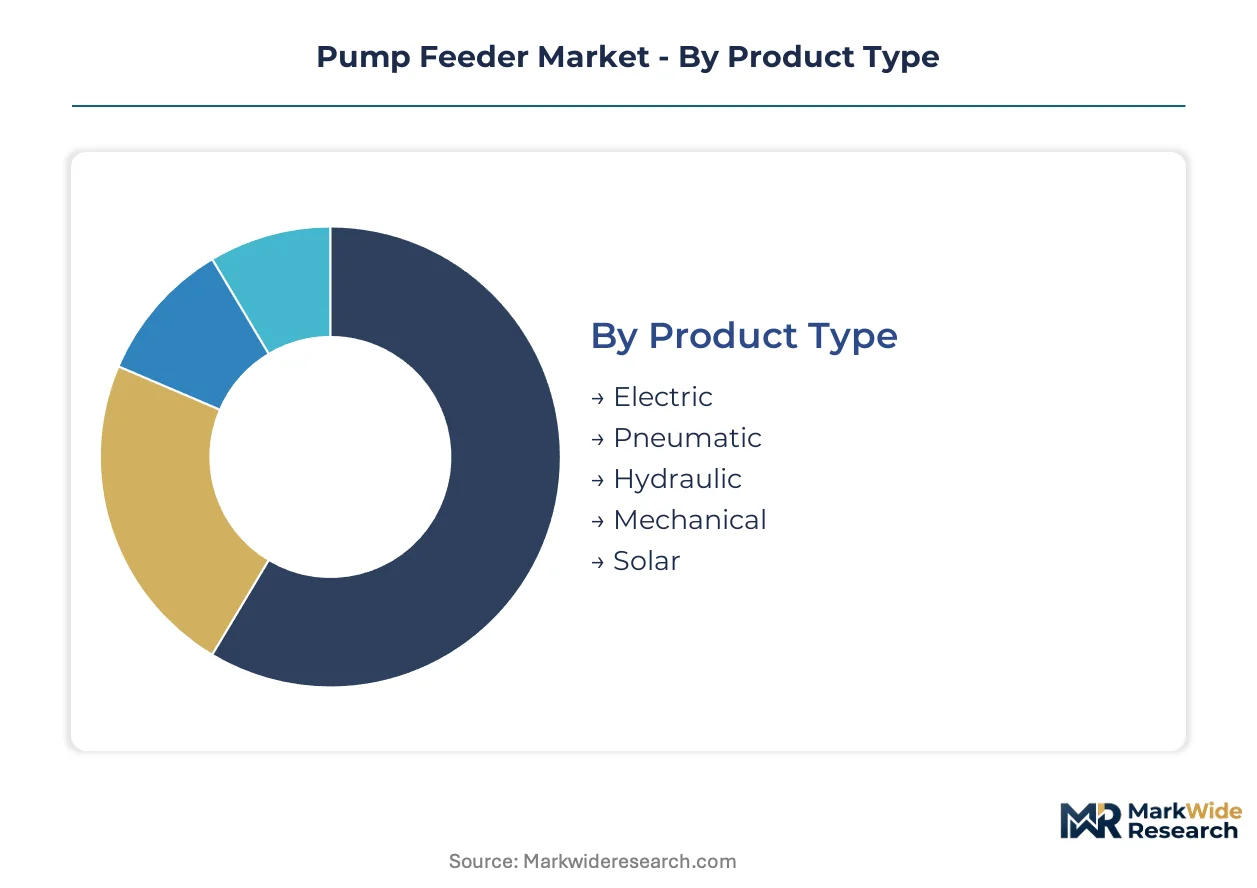
Pump feeder procurement patterns diverge sharply across product architectures and installation contexts. Regulatory compliance tiers and process criticality determine specification choices more than upfront capital cost.
Product Type:
Electric architectures dominate where EPA effluent guidelines and EU F-Gas Regulation mandate programmable dosing precision and phase out pneumatic actuation.
- Electric:Brushless DC and servo-driven metering pumps integrate with SCADA for automated chemical dosing. Municipal utilities across Germany's industrial corridor specify electric feeders to meet tightened phosphorus removal standards under the EU Urban Wastewater Treatment Directive.
- Pneumatic:Compressed-air diaphragm pumps retain installed base in legacy chemical plants but face accelerated obsolescence under F-Gas phase-down schedules. Facilities in the Netherlands and Belgium confront stranded asset risk where recent pneumatic infrastructure investments conflict with REACH compliance timelines.
- Hydraulic:High-pressure piston pumps serve oilfield chemical injection and hydraulic fracturing applications.
- Mechanical:Cam-driven and gear pumps persist in low-precision agriculture and basic water treatment.
- Solar:Photovoltaic-powered diaphragm pumps gain traction in remote irrigation and off-grid water treatment installations.
Established volume favors electric feeders; emerging adoption favors solar architectures in distributed applications.
Application:
Process criticality and contamination risk stratify demand across end-use environments.
- Water Treatment:Coagulation, disinfection, and pH adjustment operations depend on corrosion-resistant metering for chlorine, alum, and caustic soda. US municipal utilities deploy programmable electric systems to satisfy EPA effluent limitation guidelines for nutrient removal.
- Chemical Processing:Sulfuric acid, chlorine dioxide, and specialty reagent dosing demands Hastelloy and titanium wetted components. Germany's Rhine-Neckar chemical cluster specifies ceramic-diaphragm architectures to eliminate elastomer replacement cycles.
- Food & Beverage:Sanitary 3A-certified pumps handle CIP chemicals and ingredient addition.
- Pharmaceuticals:Peristaltic and quaternary diaphragm pumps serve aseptic biologics processing where shear sensitivity governs selection.
- Agriculture:Fertigation and livestock medication systems prioritize cost efficiency over precision.
Water treatment anchors current procurement volume; pharmaceutical applications command steepest expansion trajectory.
End User Industry:
Contracting authority and validation burden reshape supplier qualification requirements.
- Municipal Services:Public procurement frameworks separate hardware acquisition from performance-based service contracts. California's regional water quality control boards mandate verified dosing accuracy over multi-year operating periods.
- Chemical Manufacturing:OSHA process safety management standards and REACH substance restrictions govern material traceability for sealing and diaphragm components.
- Food Production:FDA food contact notifications and 3A sanitary standards determine pump surface finish and cleanability specifications.
- Crop Cultivation:Large-scale irrigation districts and greenhouse operations drive seasonal demand patterns.
- Pharmaceutical Companies:CDSCO alignment with ICH Q7 guidelines and FDA validation documentation requirements compress specification timelines.
Municipal services concentrate procurement scale; pharmaceutical companies generate premium margin pools.
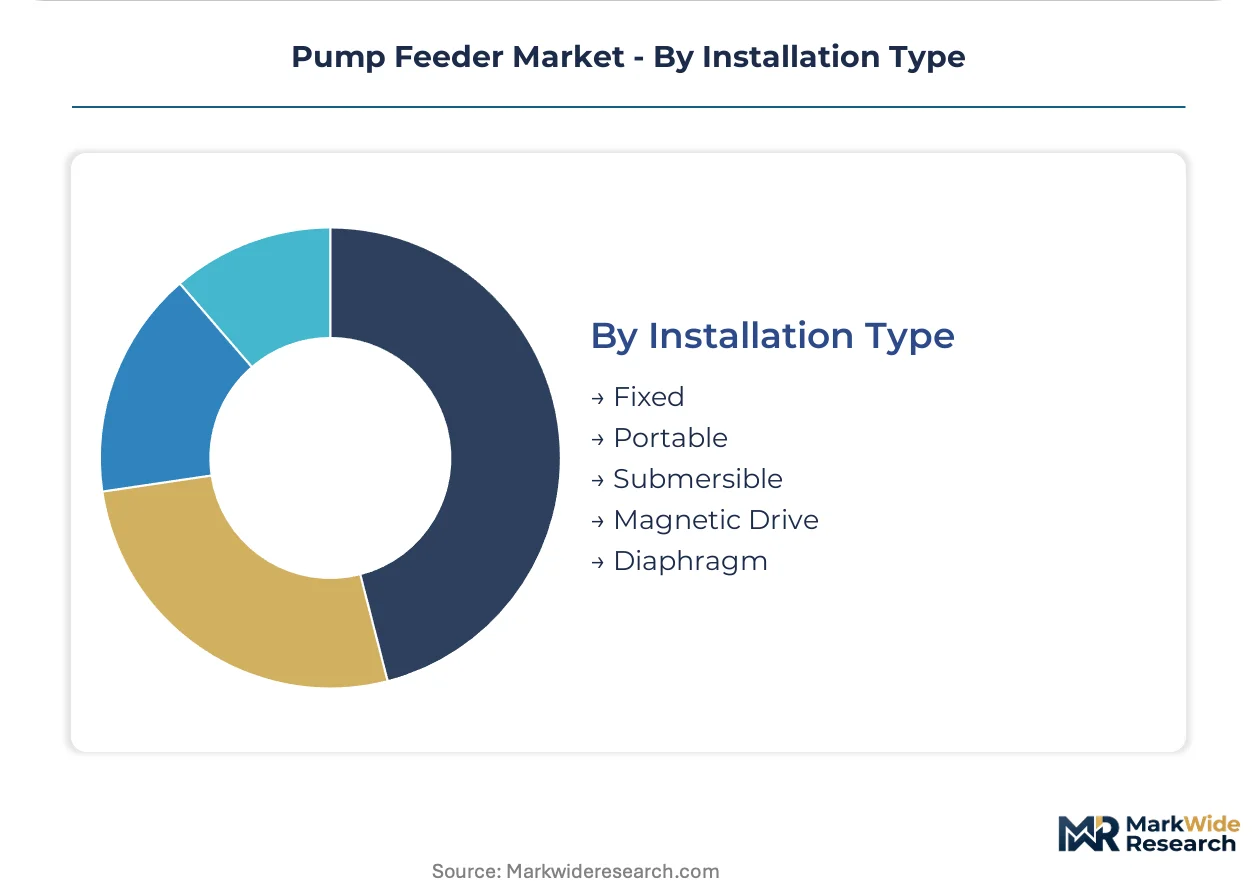
Installation Type:
Mounting configuration and sealing technology respond to site constraints and maintenance accessibility.
- Fixed:Permanent skid-mounted or inline installations dominate continuous chemical processing. Brownfield plants struggle to interface modern electric feeders with legacy SCADA without full distributed control system replacement.
- Portable:Mobile cart-mounted units serve temporary treatment and emergency response applications.
- Submersible:Encapsulated motor designs handle sump and tank-bottom dosing in wastewater facilities.
- Magnetic Drive:Sealless configurations eliminate mechanical seal leakage for volatile or toxic chemistries.
- Diaphragm:Hydraulically balanced and mechanically actuated diaphragm pumps isolate process fluid from drive components.
Fixed installations retain dominant share; magnetic drive architectures gain share fastest in hazardous chemical service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing premiums for integrated metering packages while India's pharmaceutical clusters compete on cost efficiency for cGMP-validated systems. This asymmetry reflects divergent regulatory burdens and technician scarcity patterns across manufacturing geographies.
Germany
Rhine-Neckar chemical processors specify ceramic-diaphragm pump feeders for chlorine dioxide generation to eliminate elastomer replacement cycles. The EU F-Gas Regulation accelerates pneumatic-to-electric retrofit mandates across Baden-Württemberg process OEMs. Munich-area municipal utilities deploy programmable electric dosing systems to satisfy tightened phosphorus removal standards.
United States
California regional water quality control boards mandate performance-based contracting with verified dosing accuracy over multi-year operating periods. EPA effluent limitation guidelines for nutrient removal drive municipal utility automation investments. Gulf Coast chemical manufacturers face OSHA process safety management compliance deadlines for sulfuric acid handling systems.
India
Hyderabad and Ahmedabad API production clusters generate demand for CDSCO-aligned cGMP-validated dosing systems. The country's national pharmaceutical regulator harmonization with ICH Q7 guidelines compresses equipment qualification timelines. Maharashtra's bulk drug manufacturers prioritize cost-optimized electric architectures over premium European imports.
Netherlands
Rotterdam chemical terminals confront stranded pneumatic infrastructure risk under REACH substance restriction phase-down schedules. ECHA's PFAS classification proposals threaten fluoropolymer seal inventories across water treatment installations. Eindhoven-region semiconductor fabs specify advanced ceramic barrier materials for aggressive chemistries.
China
Yangtze River Delta specialty chemical producers scale dosing automation to meet tightened effluent discharge standards under MEE enforcement. The country's dual carbon goals accelerate electric pump feeder adoption in climate-sensitive industrial zones. Shandong Province chlorine dioxide generators trial ceramic-diaphragm architectures for hot concentrated caustic service.
Pump Feeder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pump feeder supply chain. The market structures around three tiers: integrated multinational fluid handling conglomerates, specialized precision dosing engineering houses, and regional fabrication specialists serving cost-sensitive process industries. Dominant competitive moves include backward integration into precision controller manufacturing and geographic expansion through municipal retrofit contract capture.
Among Denmark-based pump technology groups, Grundfos Holding A/S exemplifies the service-academy archetype locking in recurring municipal revenue. SPX FLOW Inc. and Watson-Marlow Fluid Technology Group occupy positions within the precision-engineering tier, with the latter representing peristaltic specialization for shear-sensitive pharmaceutical applications. These three anchors illustrate how compliance engineering capabilities and embedded service networks separate premium positioning from commodity fabrication.
| Leading Market Players |
|---|
| SPX FLOW Inc. |
| Grundfos Holding A/S |
| Watson-Marlow Fluid Technology Group |
| Dover Corporation |
| IDEX Corporation |
| ProMinent GmbH |
| Graco Inc |
| Verder Group |
| Xylem Inc. |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-sixteen-week lead times for Hastelloy and titanium wetted components concentrate pricing power among German and Danish pump feeder OEMs with captive alloy sourcing, while municipal utilities in California and Texas face cost compression from unbundled procurement mandates that separate hardware from service contracts.
Pricing Analysis
Configured-to-order electric pump feeders with embedded SCADA integration command 35-50% premiums over standard pneumatic architectures, with price differentiation anchored in FDA validation documentation depth and REACH material traceability certification. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance engineering burden: pharmaceutical OEMs absorb premium tiers for cGMP-validated systems, while agricultural fertigation operators drive price erosion through volume procurement of mechanical pump feeders. Pricing pressure stems from certified technician scarcity inflating commissioning costs across Germany's industrial corridor.
Supply Chain Analysis
Ruhr Valley specialty steel mills and Shanghai rare earth processing nodes constitute dual chokepoints for corrosion-resistant alloy pump feeder manufacturing, with Hastelloy billet availability hinging on nickel-cobalt supply from Indonesian and Philippine mining concessions. Ceramic diaphragm production draws from semiconductor-grade alumina foundries in Japan and Germany, creating single-source vulnerability for chlorine dioxide generator OEMs. Distribution runs through authorized service networks rather than direct OEM-to-end-user channels, with ProMinent GmbH and Verder Group maintaining captive installation and calibration capabilities across Benelux chemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pump feeder incumbents face substitution pressure from integrated skid manufacturers bundling dosing hardware with membrane filtration systems, requiring defensive repositioning around compliance engineering and aftermarket service capture.
For Market Incumbents: Fortify installed base retention through backward integration into precision controller manufacturing and embedded safety system engineering, countering the threat from Chinese pump-skid integrators offering commodity dosing hardware at distressed pricing. Prioritize municipal retrofit contract capture in California and Germany where F-Gas Regulation compliance deadlines compress replacement timelines and lock in multi-year service revenue. For New Entrants and Emerging Players: Aftermarket calibration and predictive maintenance service gaps in India's pharmaceutical clusters present white-space entry points where European incumbents lack localized technician networks. Target CDSCO-aligned cGMP validation support for Hyderabad and Ahmedabad API manufacturers, leveraging remote diagnostics platforms to circumvent the certified engineer shortage constraining established competitors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA effluent guidelines and REACH substance restrictions structurally expand the addressable market for validated electric architectures regardless of underlying chemical processing volume cycles. Acquisition focus should center on peristaltic pump specialists with pharmaceutical biologics positioning and embedded FDA documentation capabilities. Monitor ECHA PFAS classification rulings as the inflection signal accelerating fluoropolymer seal replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controller Manufacturing | SPX FLOW Inc. and ProMinent GmbH capture margin from precision dosing electronics previously outsourced to Siemens and Schneider Electric. |
| Ceramic Diaphragm Technology Licensing | German Rhine-Neckar chemical processors eliminate 6-12 month elastomer replacement cycles through alumina and silicon carbide barrier adoption. |
| Service Academy Network Expansion | Grundfos Holding A/S locks municipal retrofit contracts by certifying fluid systems technicians in California and Baden-Württemberg. |
| PFAS-Free Material Qualification | Dutch and Belgian water treatment operators accelerate PEEK and UHMWPE diaphragm substitution ahead of ECHA restriction enforcement. |
| Digital Twin Integration Partnerships | Predictive maintenance platform convergence enables outcome-based contracting tied to verified dosing accuracy metrics. |
Research Methodology
Operator-level perspectives from municipal utility maintenance directors, chemical plant process engineers, pharmaceutical OEM procurement managers, and aftermarket service technicians anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA effluent guideline filings, ECHA REACH substance restriction databases, SEC 10-K disclosures from listed pump technology groups, and customs trade data for Hastelloy and titanium alloy imports. Bottom-up demand modeling triangulated against top-down market sizing across electric, pneumatic, hydraulic, and peristaltic product architectures.
Sensitivity analysis tested forecast robustness against raw material price volatility, regulatory phase-down acceleration, and technician availability constraints across the projection horizon. Segmentation modeling incorporated product type, application criticality, end-user industry validation burden, and installation configuration complexity. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, with specific inputs including F-Gas Regulation compliance deadline schedules and CDSCO-ICH Q7 harmonization timelines for pharmaceutical equipment qualification.
Forecasts assume regulatory continuity in EPA effluent limitation guidelines and EU F-Gas phase-down schedules; material policy shifts including accelerated PFAS restrictions or OSHA process safety management revisions would require re-modeling. Practitioners should keep alternative scenarios live as ECHA substance classification proposals and state-level fluorinated compound restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Livestock Grow Lights Market