
 Agriculture Seeder Market | 2026-2036
Agriculture Seeder Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Seeder Market Analysis
The gap between GPS-guided variable-rate seeding and legacy mechanical drop-tube systems is narrowing as sensor costs fall and ISOBUS compatibility becomes standard across tractor lines. Deere & Company leverages its integrated precision agriculture platform to control aftermarket software revenue streams. AGCO Corporation anchors its position through Fendt-branded high-speed planting systems optimized for European field conditions. Kubota Corporation competes aggressively in compact precision seeders for rice and vegetable operations across East and Southeast Asian markets.
An agriculture seeder is a mechanized planting device engineered to meter, deposit, and cover seeds at controlled depths and spacing intervals, typically operating at ground speeds of 8–16 km/h with row spacing accuracy within 2.5 cm. The equipment serves the primary commercial purpose of establishing uniform crop stands while minimizing seed waste and optimizing plant population density for yield maximization. Pneumatic seeders now dominate volume in broad-acre cereal and oilseed applications due to their ability to handle irregular seed shapes without mechanical damage. Smart technology represents the fastest-expanding margin pool, though conventional technology still sustains the installed base across developing agricultural economies where capital replacement cycles extend beyond twelve years. Precision seeders occupy the premium tier in vegetable crop systems where singulation accuracy directly determines marketable yield.
The US EPA enforces emissions standards under Tier 4 Final regulations that shape engine architecture and drivetrain design for self-propelled and towed seeding equipment. The EU Green Deal and associated Farm to Fork strategy pressure manufacturers to demonstrate carbon footprint reductions across equipment life cycles, while REACH compliance governs material composition in polymer seed tubes and coatings. Brazil's federal environmental licensing framework through IBAMA influences no-till seeder specifications in the Cerrado and Matopiba regions. Stakeholders must weigh capital allocation between smart technology R&D and conventional product line maintenance as farm profitability volatility and regulatory stringency tighten in parallel across major demand centers.
Market Dynamics
Precision seeding hardware is converging with cloud-based agronomy platforms, compressing equipment replacement cycles and forcing manufacturers to monetize recurring software revenue rather than one-time machinery sales.
Growth Catalysts
- IBAMA environmental licensing:Brazil's federal framework mandates no-till planting practices across Cerrado expansion zones, compelling soybean and corn producers to upgrade to pneumatic precision seeders that minimize soil disturbance.
- Variable-rate seeding technology:GPS-guided systems with real-time soil sensor integration enable farmers to optimize seed density by management zone, reducing input waste while maximizing yield potential.
- ISOBUS standardization:Universal tractor-implement communication protocols eliminate proprietary compatibility barriers, accelerating retrofit demand across mixed-fleet operations in Eastern Europe.
Market Restraints
- Steel and aluminum input volatility:Chassis and frame manufacturing costs fluctuate with commodity metal pricing, compressing margin predictability for equipment producers during extended order backlogs.
- High-voltage electronics supply concentration:Motor controllers and sensor arrays for electric-drive seeders depend on Asian semiconductor fabrication capacity, creating vulnerability to trade flow disruptions.
- Tier 4 Final compliance friction:US EPA emissions standards add engineering complexity and aftertreatment hardware costs to self-propelled planting platforms, extending development timelines.
Strategic Opportunities
- Smallholder mechanization in Southeast Asia:Compact precision seeders for rice transplanting and vegetable operations address labor shortage pressures in Vietnam and Indonesia where manual planting dominates.
- EU Green Deal carbon accounting:Equipment lifecycle emissions disclosure requirements create demand for manufacturer-certified carbon footprint data, enabling premium positioning for low-impact production methods.
- Telematics-agronomy convergence:Integration of seeder performance data with prescription planting software creates recurring revenue streams through subscription agronomy services.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time seed singulation control requires specialized mechatronics talent that agricultural equipment manufacturers compete for against automotive and robotics sectors.
- Legacy hydraulic fleet integration:Retrofitting ISOBUS-enabled seeders onto pre-2010 tractors without native compatibility creates installation complexity and dealer service burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Seeder Market |
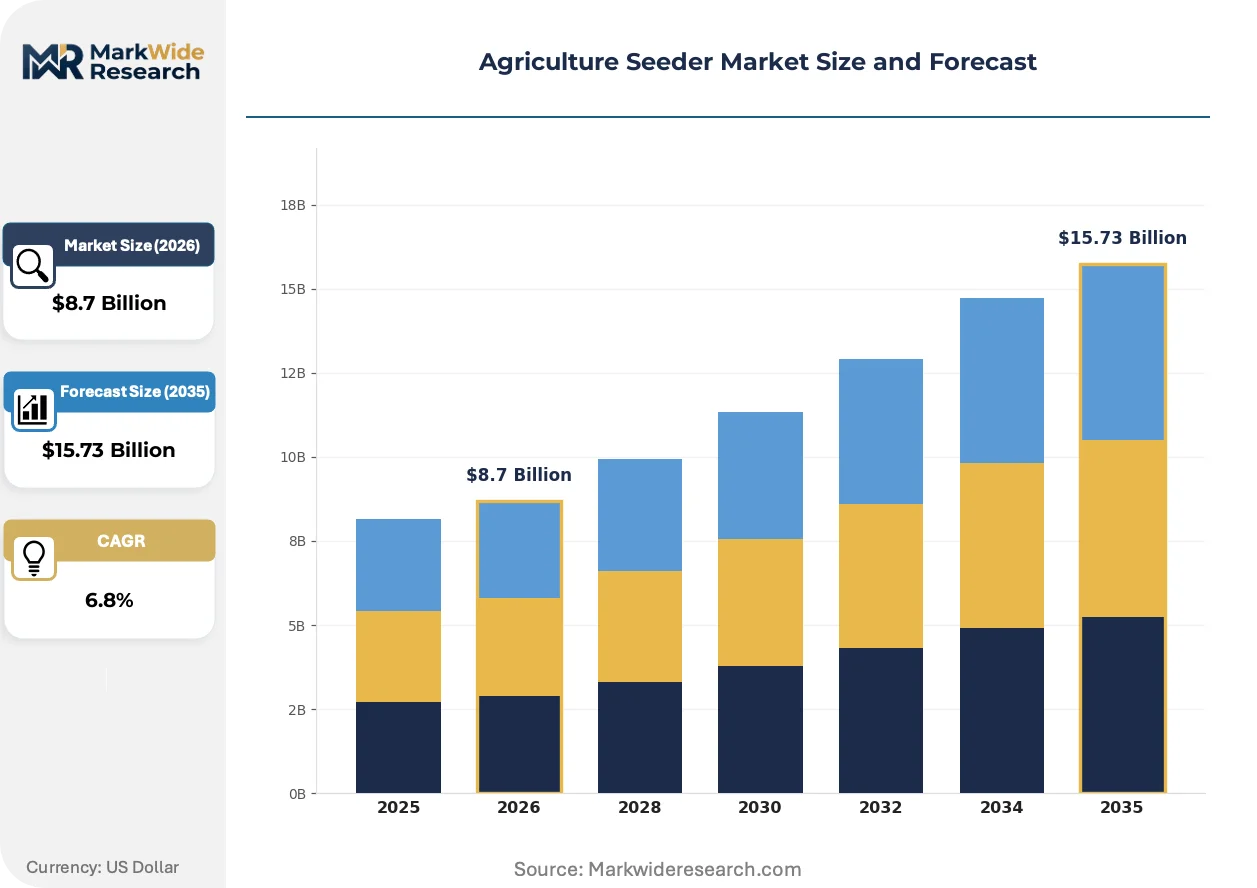
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Seeders, Pneumatic Seeders, Planters, Precision Seeders End Use Industry: Cereal Crops, Pulse Crops, Oilseed Crops, Vegetable Crops Distribution Channel: Online Retail, Direct Sales, Distributors, Agriculture Expos Technology: Conventional Technology, Smart Technology, Automated Systems, Hybrid Technology |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, CLAAS, Kubota Corporation, Kuhn Group, Yanmar Company, LEMKEN GmbH & Co. KG, Amity Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Seeder Market Emerging Trajectories
Seeding equipment is transitioning from mechanical precision to algorithmic optimization, with sensor networks and machine learning models now governing planting decisions previously managed by operator judgment.
High-speed planting systems utilizing active downforce control and individual row hydraulic metering are collapsing the throughput gap between conventional tillage-based equipment and no-till precision platforms. Large-scale corn and soybean operations in the US Corn Belt and Brazilian Matopiba region are adopting these systems to compress planting windows during weather-limited spring seasons. The technology is collapsing capital allocation trade-offs between speed and accuracy, enabling single-pass operations at ground speeds exceeding 20 km/h without sacrificing emergence uniformity.
EU Green Deal Farm to Fork strategy mandates 50% pesticide reduction targets by 2030, forcing seeder manufacturers to engineer integrated fertilizer placement systems that reduce starter fertilizer requirements through precise proximity planting. European equipment producers are responding with twin-row configurations and banded nutrient delivery modules that maintain yield potential under input constraint regimes. German and French regulatory pressure is accelerating development of electrified seeding platforms to demonstrate lifecycle carbon reductions required for public procurement eligibility.
Equipment-as-a-service contracting is displacing traditional ownership models among mid-scale North American grain operations facing working capital constraints and volatile commodity margins. Dealer networks and manufacturer captive finance arms are structuring per-acre planting service agreements that bundle machinery, maintenance, and agronomic optimization software. This shift concentrates most visibly in the US Northern Plains and Canadian Prairie provinces where farm consolidation has created demand for operational flexibility without balance sheet expansion.
Agriculture Seeder Market Segmentation
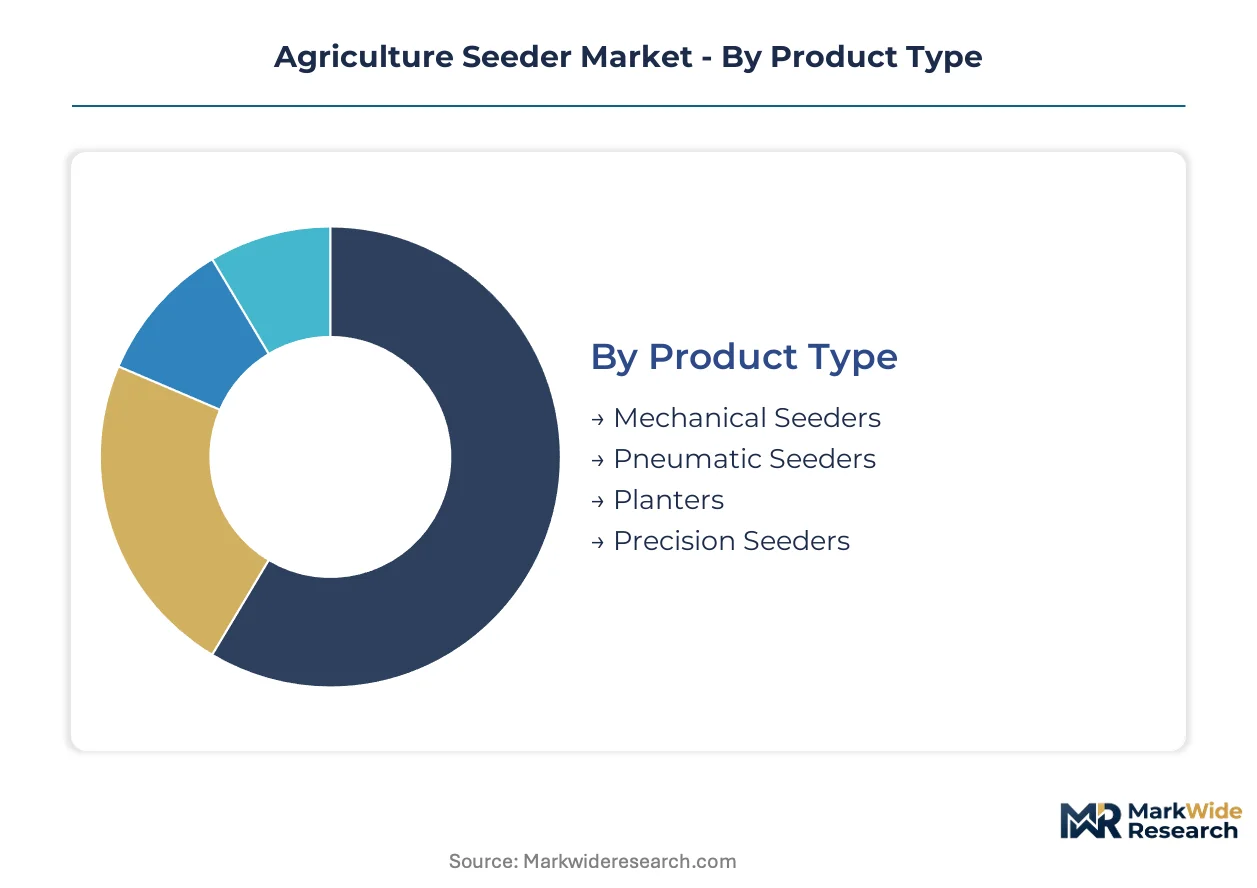
Equipment replacement cycles vary dramatically across seeder categories, with precision technology refreshing every 4-6 years while mechanical systems persist for 15+ years in developing markets. Understanding these divergent turnover rhythms enables manufacturers to balance R&D allocation between premium innovation and installed-base maintenance.
Product Type:
Pneumatic and precision systems command the shortest replacement cycles as sensor costs fall and software obsolescence accelerates, while mechanical seeders turn over slowest due to capital constraints in price-sensitive markets.
- Mechanical Seeders:Gravity-fed drop-tube mechanisms meter seeds through fluted wheels or plate systems without pneumatic assistance. Demand concentrates across smallholder operations in India and sub-Saharan Africa where capital scarcity extends equipment lifecycles beyond fifteen years and repair networks substitute for replacement.
- Pneumatic Seeders:Vacuum or pressure-based seed transport handles irregular seed shapes without mechanical damage while enabling higher ground speeds. Brazilian soybean and corn producers in the Cerrado and Matopiba regions dominate procurement as IBAMA environmental licensing mandates no-till compliance and input optimization.
- Planters:Row-crop specific equipment with individual seed metering and depth control for maize, soybean, and cotton.
- Precision Seeders:Singulation-accurate systems achieving 99%+ seed spacing uniformity for vegetable and high-value specialty crops.
Mechanical seeders anchor the volume base across developing agricultural economies while precision seeders gain share at the steepest rate in vegetable production systems.
End Use Industry:
Margin profiles diverge sharply by crop economics, with vegetable operations justifying premium equipment spend per hectare while cereal applications prioritize throughput maximization over singulation accuracy.
- Cereal Crops:Wheat, rice, and maize establishment at high speeds with broadcast or narrow-row drilling methods. North American and Eastern European grain operations drive specification requirements for 12-meter-plus working widths and ISOBUS compatibility across mixed-fleet environments.
- Oilseed Crops:Canola, sunflower, and soybean planting with specific depth and population requirements. Brazilian producers retrofitting fleets for compliance with federal environmental licensing frameworks represent the dominant demand concentration as no-till specifications become mandatory in expansion zones.
- Pulse Crops:Lentil, chickpea, and pea planting with sensitivity to seed coat damage during handling.
- Vegetable Crops:High-value produce requiring precise singulation for marketable yield optimization.
Cereal applications generate the largest equipment volume while vegetable crop systems command the highest unit margins and fastest technology refresh rates.
Distribution Channel:
Channel economics reflect equipment complexity and service intensity, with precision systems demanding dealer technical support while commoditized products migrate toward direct procurement.
- Direct Sales:Manufacturer-to-farmer transactions for large fleet orders and custom specifications. North American grain operations in the US Northern Plains and Canadian Prairie provinces concentrate here as equipment-as-a-service contracting bundles machinery, maintenance, and agronomic software subscriptions.
- Distributors:Independent dealer networks providing local service, parts inventory, and trade-in facilitation. Eastern European mixed-fleet operations depend on distributor technical capacity for ISOBUS retrofit installation and legacy hydraulic system integration.
- Online Retail:E-commerce platforms for spare parts, consumables, and compact equipment.
- Agriculture Expos:Trade show demonstrations and order placement for premium system introductions.
Distributor networks handle the majority of precision equipment transactions while direct sales channels capture the steepest expansion in bundled service contracting.
Technology:
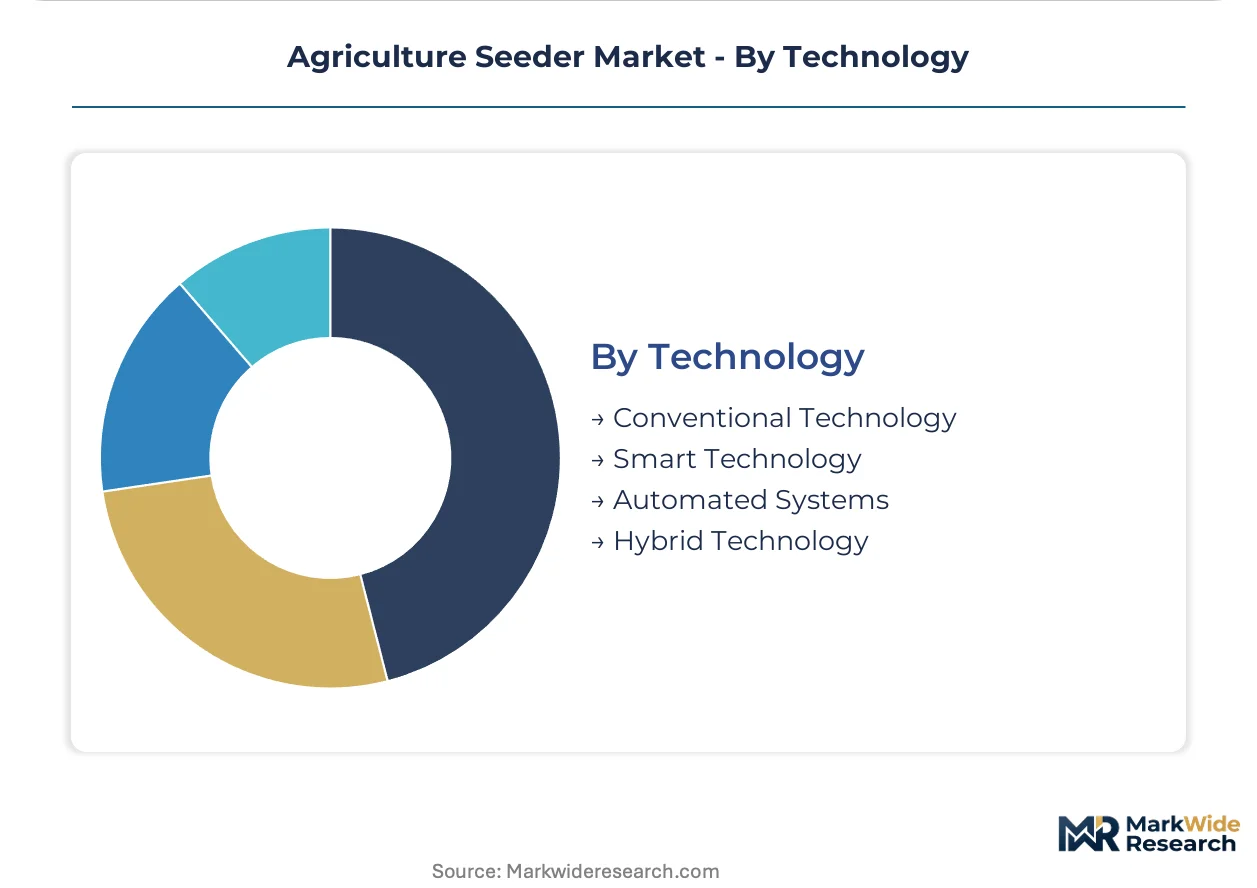
Technology tiering determines both upfront capital requirements and ongoing revenue potential, with smart systems enabling recurring software monetization against conventional hardware-only economics.
- Smart Technology:GPS-guided variable-rate seeding with real-time soil sensor integration and cloud-based prescription planting. US Corn Belt operations compressing planting windows during weather-limited spring seasons drive adoption of high-speed systems exceeding 20 km/h with active downforce control.
- Automated Systems:Fully autonomous or semi-autonomous platforms with minimal operator intervention requirements. German and French regulatory pressure under EU Green Deal Farm to Fork strategy accelerates electrified platform development for lifecycle carbon disclosure compliance.
- Conventional Technology:Operator-dependent mechanical or basic hydraulic control without sensor feedback.
- Hybrid Technology:Partial automation with operator override and selective sensor integration.
Conventional technology sustains the installed base across capital-constrained developing markets while smart technology platforms are expanding most quickly in large-scale commercial operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian equipment exports flow primarily to Argentine and Paraguayan farming operations seeking no-till seeding compliance, while German manufacturers supply precision systems across Eastern European accession markets.
United States
Corn Belt operations drive demand for high-speed planting systems exceeding 20 km/h with active downforce control. EPA Tier 4 Final emissions standards shape engine architecture for self-propelled platforms. Equipment-as-a-service contracting concentrates in the Northern Plains and Prairie provinces where farm consolidation creates working capital constraints.
Brazil
Soybean and corn producers in the Cerrado and Matopiba regions retrofit fleets with pneumatic precision seeders. IBAMA federal environmental licensing mandates no-till compliance across expansion zones. Mato Grosso and Goiás states anchor procurement volumes as input optimization pressures intensify.
Germany
EU Green Deal Farm to Fork strategy accelerates electrified platform development for lifecycle carbon disclosure. REACH compliance governs polymer seed tube material composition. Baden-Württemberg and Lower Saxony industrial clusters engineer integrated fertilizer placement systems for pesticide reduction targets.
China
Domestic grain operations prioritize throughput maximization over singulation accuracy in wheat and maize establishment. National dual carbon goals pressure manufacturers toward electrified drivetrain development. Shandong Province fabrication centers supply compact mechanical seeders across Belt and Road agricultural markets.
India
Smallholder operations in Punjab and Haryana extend mechanical seeder lifecycles beyond fifteen years due to capital scarcity. BIS certification requirements shape equipment safety and interoperability standards. Gujarat and Maharashtra dealer networks substitute repair capacity for replacement demand across fragmented landholdings.
Agriculture Seeder Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated agriculture platforms face focused implement manufacturers. The vendor base concentrates around three strategic archetypes: full-line tractor OEMs with captive seeder offerings, standalone implement specialists with ISOBUS-native designs, and regional fabricators serving price-sensitive replacement markets. Competitive moves center on precision technology licensing partnerships and backward integration into sensor and controller supply.
Among the full-line platform operators, Deere & Company and AGCO Corporation exemplify the integrated precision agriculture archetype, while Kubota Corporation occupies a position bridging compact equipment specialization with smart technology adoption. These three anchors represent divergent geographic emphases—North American platform control, European high-speed system optimization, and East Asian smallholder mechanization respectively.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| CLAAS |
| Kubota Corporation |
| Kuhn Group |
| Yanmar Company |
| LEMKEN GmbH & Co. KG |
| Amity Technology |
| Others |
Supply Flow & Price Mechanics
Chinese steel and aluminum fabrication clusters concentrate chassis manufacturing for mid-range pneumatic seeders, compressing margin pools for European and North American OEMs competing on precision technology premiums. Tier 4 Final aftertreatment hardware and ISOBUS-enabled sensor arrays concentrate value capture in the smart technology tier, while mechanical seeder producers compete on replacement part economics across capital-scarce developing markets.
Pricing Analysis
Next-generation GPS-guided variable-rate seeders command 40-60% premiums over prior-generation hydraulic metering systems, while mechanical drop-tube equipment occupies a collapsing economy tier. Three-tier pricing structure across premium smart technology, standard automated systems, and economy conventional equipment reflects divergence in software monetization potential. Pricing pressure stems from Brazilian and Indian procurement consolidation around pneumatic mid-range specifications that sacrifice singulation accuracy for throughput. Smallholder operations in sub-Saharan Africa and South Asia exhibit extreme price sensitivity with fifteen-year replacement cycles, while US Corn Belt commercial farms prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Tariff exposure between China and major Western agricultural equipment markets dominates supply chain risk planning for motor controller and sensor array procurement. Manufacturing concentration in Germany, China, and Brazil shapes component sourcing strategies for chassis fabrication, hydraulic systems, and precision metering hardware. High-voltage electronics and semiconductor-dependent seed singulation controllers draw from Asian fabrication capacity, creating single-source vulnerability for electric-drive platform development. Distribution runs through captive dealer networks in North America and Europe, while independent distributors handle aftermarket parts and retrofit installation across mixed-fleet operations in Eastern Europe and South America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agriculture seeder demand follows a cyclical recovery pattern tied to Brazilian soybean planting expansion and US Corn Belt fleet replacement timing. Equipment procurement accelerates when commodity margins stabilize and environmental licensing deadlines compress.
For Market Incumbents: Insulate precision technology margins through captive software subscription architectures that lock in recurring revenue beyond hardware replacement cycles. Defend against ISOBUS-native implement specialists by deepening backward integration into sensor and controller supply chains. Prioritize certification investment for EU Green Deal lifecycle carbon disclosure compliance to maintain public procurement eligibility in German and French markets.
For New Entrants and Emerging Players: Compact precision seeders for rice transplanting and vegetable operations in Vietnam and Indonesia represent the most penetrable entry point given labor shortage pressures and minimal incumbent smart technology penetration. Mid-scale grain operations in Eastern Europe seeking ISOBUS retrofit compatibility without full fleet replacement offer a secondary white-space target. A dealer-partnership go-to-market angle leveraging existing distributor technical capacity for installation and service bypasses captive network disadvantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture software platforms seeking hardware integration to complete full-stack offerings. Long-term viability over a five-to-ten-year horizon rests on recurring revenue share expansion versus transactional equipment sales. Monitor IBAMA licensing enforcement intensity in Brazilian expansion zones as the inflection signal for pneumatic seeder procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive control over seed singulation controllers reduces exposure to Asian semiconductor fabrication bottlenecks. |
| Equipment-as-a-Service Contracting | Per-acre planting agreements bundle machinery, maintenance, and agronomic software across US Northern Plains operations. |
| EU Green Deal Certification Investment | Lifecycle carbon disclosure compliance enables premium positioning in German and French public procurement channels. |
| Southeast Asia Compact Seeder Launch | Rice and vegetable precision systems address labor shortage pressures in Vietnam and Indonesia replacement markets. |
| ISOBUS Retrofit Platform Development | Compatibility solutions for pre-2010 hydraulic tractors unlock Eastern European mixed-fleet demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with farm operations managers, agricultural equipment dealer principals, OEM product development directors, and precision agriculture software engineers. Secondary validation drew from EPA Tier 4 Final compliance filings, EU ECHA REACH substance registrations, IBAMA environmental licensing databases, and Brazilian agricultural machinery import records. Bottom-up equipment shipment analysis and top-down agricultural mechanization rate modeling were triangulated to cross-verify volume estimates.
Calibration against historical replacement cycle patterns and commodity margin correlation analysis anchored the projection framework across the modeling period. Segmentation dimensions included product type tier, crop application, technology generation, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for capital expenditure cyclicality and environmental policy implementation timelines. Forecast inputs incorporated tractor fleet age distributions, no-till adoption trajectories, and precision agriculture software penetration rates.
Macroeconomic conditions sit as an overlay; deviation in grain commodity prices, Brazilian real exchange rates, or Chinese steel export pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology cost decline curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Automatic Composter Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Planter Market