
 Battery Powered Sprayer Market | 2026-2036
Battery Powered Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Powered Sprayer Market Insights
The capital-intensity gap between integrated manufacturers and component assemblers is collapsing as battery pack costs fall and motor-controller supply broadens. Husqvarna leverages captive lithium-cell procurement and in-house brushless motor design to sustain margin structure across European garden centers. STIHL anchors its position through dealer-network exclusivity that controls service revenue streams in German-speaking markets. Chapin International competes on polyethylene tank molding scale and North American retail shelf placement.
A battery powered sprayer is a portable liquid-dispersion device employing rechargeable electrochemical cells to drive a diaphragm or centrifugal pump, typically operating at 12–40 volts with tank capacities from one to fifteen gallons for chemical application in agriculture, sanitation, and turf maintenance. Backpack sprayers dominate unit volume in developing markets where operator mobility constraints favor lighter loads, while tractor-mounted configurations capture value concentration on commercial row-crop operations. Wheel-mounted units are gaining traction in municipal pest control fleets seeking to replace ride-on gasoline equipment. Spray Technologies and Battery Technology segments are where margin pools concentrate, as nozzle precision and cell chemistry differentiation command pricing premiums over commoditized tank and frame assemblies.
EPA small off-road engine emission standards and EU F-Gas Regulation are tightening compliance thresholds for conventional combustion sprayers, redirecting procurement budgets toward electric alternatives in both jurisdictions. OSHA pesticide exposure limits and REACH chemical registration requirements further shape product design, mandating sealed tank systems and precision flow controls that battery-electric architectures accommodate more readily than legacy equipment. Stakeholders must monitor cell supply agreements and regional service infrastructure buildout as the primary determinants of competitive durability.
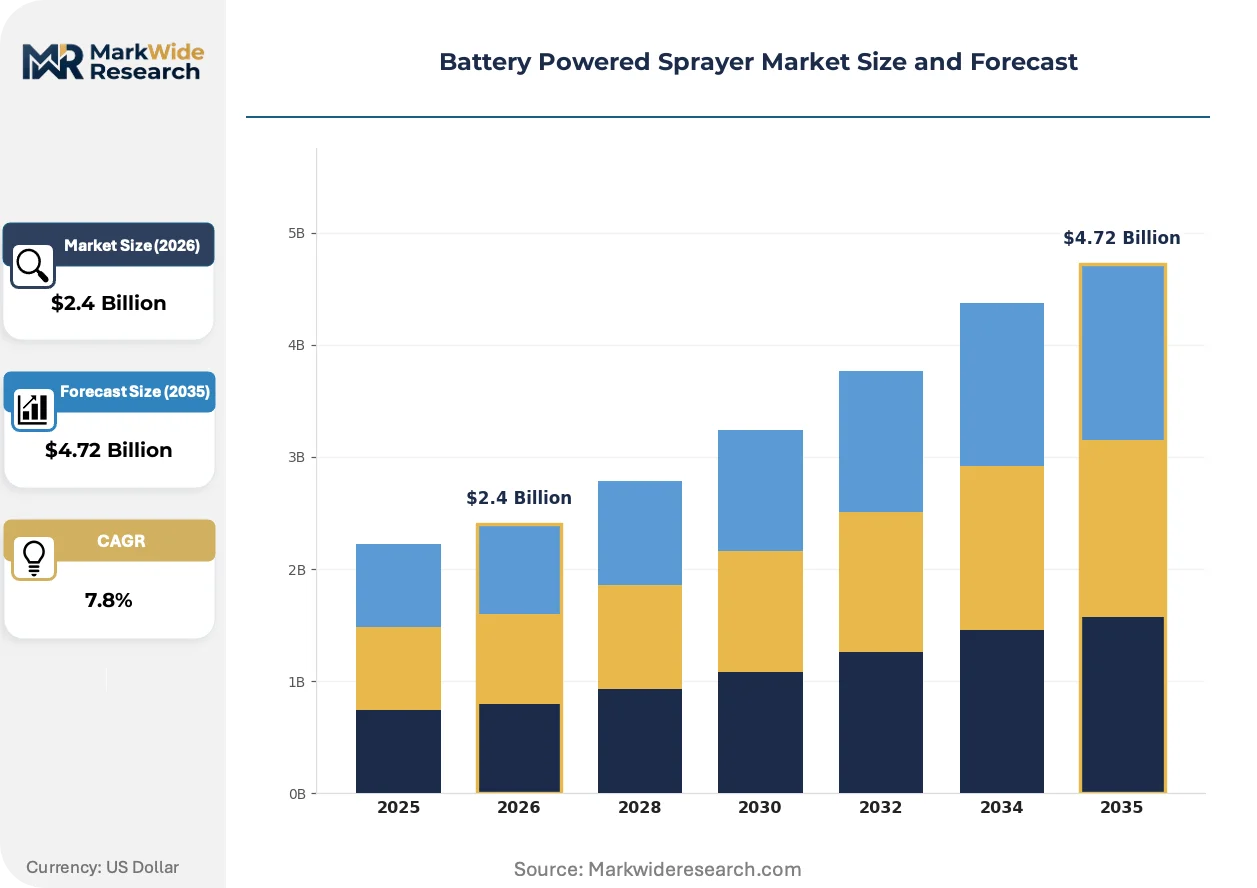
Market Dynamics
EPA emission exemptions for small off-road equipment are accelerating the phase-out of two-stroke gasoline engines in North American landscaping fleets, collapsing the capital-intensity gap between integrated manufacturers and component assemblers as battery pack costs fall.
Growth Catalysts
- EU F-Gas Regulation:Tightening compliance thresholds for conventional combustion sprayers redirect procurement budgets toward electric alternatives across European jurisdictions.
- Lithium-ion cell chemistry:Falling battery pack costs enable agricultural cooperatives in Brazil to electrify equipment pools previously constrained by diesel engine maintenance overhead.
- Contract spraying services:China's Shandong Province electrification mandates concentrate demand as service providers replace manual knapsack sprayers to meet provincial air quality targets.
Market Restraints
- Lithium supply concentration:Cell supply agreements cluster around limited cathode material processors, exposing assemblers to input cost volatility and geographic supply risk.
- Brushless motor controller sourcing:Semiconductor fabrication capacity constraints in East Asian foundries throttle motor-controller availability for mid-tier manufacturers.
- Manual knapsack persistence:Low-cost hand-pump alternatives retain volume share in developing markets where capital constraints outweigh operator fatigue concerns.
Strategic Opportunities
- Wheel-mounted municipal fleets:Municipal pest control operations seek to replace ride-on gasoline equipment, opening white space for battery-electric ride-on configurations.
- OSHA pesticide exposure alignment:Sealed tank system mandates create regulatory tailwind for battery architectures that accommodate precision flow controls more readily than legacy equipment.
- Dealer-network service revenue:Exclusive distribution channels in German-speaking markets enable margin capture through maintenance contract bundling rather than hardware margin alone.
Industry Challenges
- REACH chemical registration timelines:Sealed system certification delays compress product launch windows for tank and nozzle assemblies requiring material compatibility validation.
- Brushless motor design talent:In-house motor-controller engineering capability scarcity constrains speed-to-market for assemblers lacking captive electromagnetic design functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Powered Sprayer Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Sprayers, Backpack Sprayers, Wheel-mounted Sprayers, Tractor-mounted Sprayers End User: Agricultural Sector, Pest Control Services, Horticulture, Residential Users Application: Weed Control, Fertilization, Pest Management, Disinfection Technology: Spray Technologies, Battery Technology, Sensors, Applicator Designs |
| Companies Covered | Husqvarna, STIHL, Chapin International, Solo, John Deere, Greenworks, Ryobi, Echo, Toro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Powered Sprayer Market Trends and Innovations
Spray nozzle precision engineering and cell chemistry differentiation are commanding pricing premiums over commoditized tank and frame assemblies, reshaping where margin pools concentrate across the value chain.
Brushless DC motor technology is bifurcating pump drive architectures between diaphragm and centrifugal configurations. Commercial row-crop operations adopt high-pressure centrifugal systems for boom-spray uniformity, while municipal fleets prioritize diaphragm reliability for intermittent duty cycles. This technical split is bifurcating supplier qualification requirements and fragmenting procurement specifications across end-use verticals.
REACH chemical registration requirements mandate sealed tank systems and precision flow controls that battery-electric architectures accommodate more readily than legacy equipment. Industrial consequence includes accelerated R&D redirection toward electrochemical pump integration and away from small combustion engine optimization. Commercial agriculture segments in Germany and France face compressed compliance timelines, driving faster equipment replacement cycles than turf maintenance applications.
Service revenue unbundling from hardware sales is restructuring dealer economics in European garden centers. Buyers increasingly separate equipment purchase from maintenance contract negotiation, pressuring traditional bundled pricing models. This behavioral shift concentrates in German-speaking markets where STIHL and Husqvarna dealer networks historically anchored margin through exclusive service arrangements.
Battery Powered Sprayer Market Segmentation
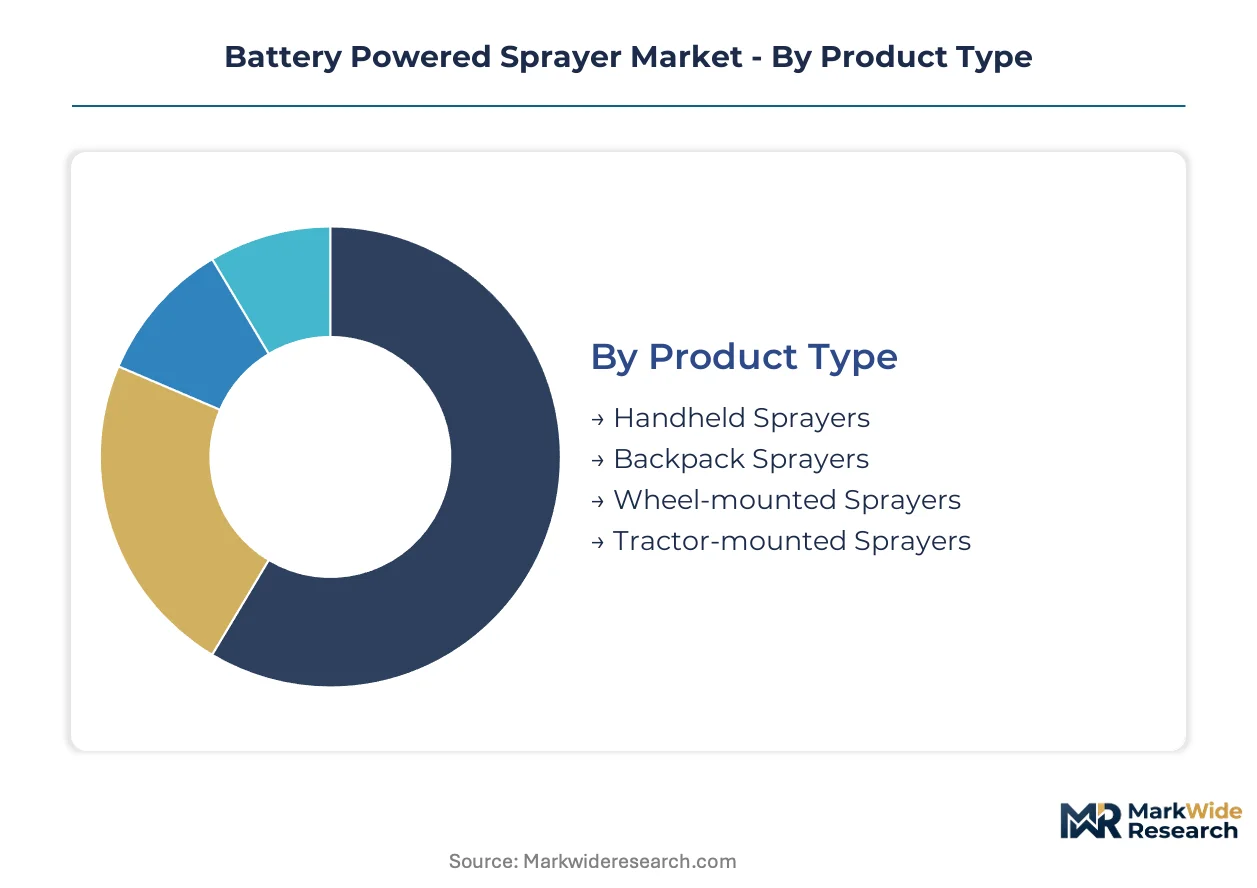
Channel mix varies sharply across battery powered sprayer configurations. Backpack units flow through agricultural cooperatives and municipal procurement in developing economies, while tractor-mounted systems anchor dealer-direct sales to commercial row-crop operations. Understanding segment-channel alignment determines where margin pools concentrate and which service infrastructure investments yield durable returns.
Product Type:
Channel concentration tracks mobility requirements and tank scale, with lighter configurations favoring retail and cooperative distribution while heavier units demand specialized dealer networks.
- Backpack Sprayers:Lithium-ion units at 12-20 volts with 3-4 gallon polyethylene tanks dominate procurement by Brazilian agricultural cooperatives replacing manual knapsack equipment. Demand concentrates in contract spraying services across China's Shandong Province where provincial air quality mandates accelerate fleet electrification.
- Handheld Sprayers:Compact 1-2 gallon units with integrated battery packs serve residential turf maintenance and spot-treatment applications. European garden centers move significant volume through seasonal retail placement, though margin compression limits dedicated service bundling.
- Wheel-mounted Sprayers:Municipal pest control fleets in North American jurisdictions seek these configurations to replace ride-on gasoline equipment under EPA small off-road engine emission exemptions.
- Tractor-mounted Sprayers:High-voltage systems with boom attachments capture value concentration on commercial row-crop operations requiring spray uniformity across extended swaths.
By volume, handheld and backpack configurations lead. By growth pace, wheel-mounted municipal applications are expanding most quickly.
End User:
Cost tier stratification separates capital-constrained operators from integrated service providers with maintenance contract capabilities.
- Agricultural Sector:Commercial row-crop operations and cooperative farming enterprises specify high-capacity systems with precision flow controls. German and French commercial agriculture segments face compressed REACH compliance timelines that accelerate equipment replacement cycles.
- Pest Control Services:Contract operators prioritize fleet standardization and sealed tank systems to meet OSHA pesticide exposure limits. Procurement concentrates in integrated service providers capable of negotiating volume cell supply agreements.
- Horticulture:Nursery and greenhouse operations favor mid-capacity diaphragm pumps for intermittent duty cycles and chemical compatibility flexibility.
- Residential Users:Price-sensitive demand for seasonal turf maintenance equipment flows through mass retail channels with minimal service attachment.
Agricultural sector procurement anchors absolute revenue. Pest control services are gaining share fastest as contract spraying models expand.
Application:
Margin pools concentrate where precision requirements and regulatory exposure intersect, favoring sealed system architectures.
- Pest Management:Professional applications mandate precision nozzle engineering and flow calibration to minimize chemical waste and operator exposure. EPA and OSHA regulatory alignment creates procurement tailwind for battery architectures accommodating sealed tank systems.
- Disinfection:Post-pandemic municipal and institutional demand for surface treatment applications favors portable battery systems over fixed infrastructure. Volume concentration in contract sanitation services with fleet-scale procurement authority.
- Weed Control:Agricultural and municipal rights-of-way maintenance drives demand for high-pressure centrifugal configurations with extended spray reach.
- Fertilization:Precision agriculture adoption correlates with variable-rate application technology integration in commercial row-crop segments.
Pest management leads by installed base value. Disinfection applications are climbing the fastest as municipal procurement diversifies beyond traditional vector control.
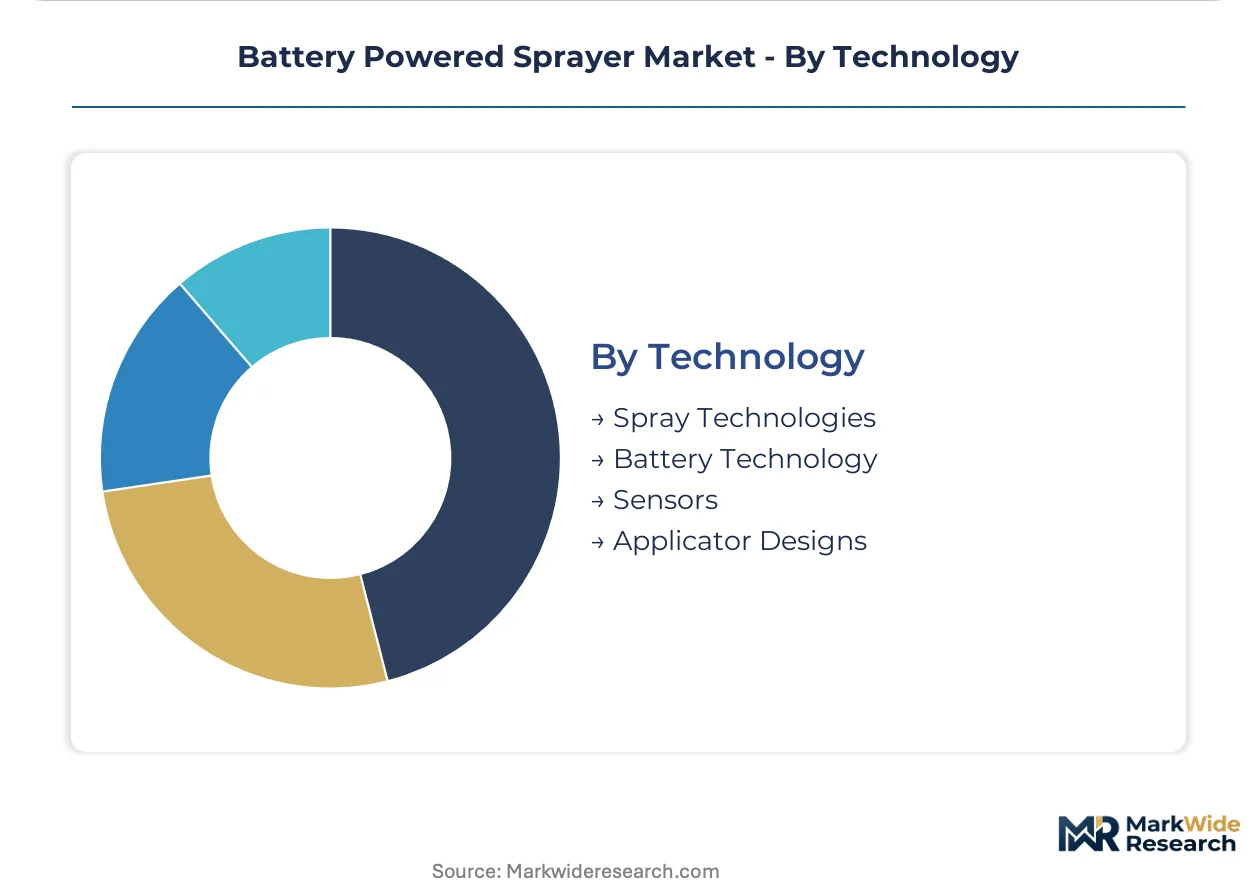
Technology:
Supply concentration in cell chemistry and motor controllers determines competitive durability for assemblers lacking captive design capabilities.
- Battery Technology:Lithium-ion cell chemistry differentiation and battery management system integration command pricing premiums over commoditized pack assembly. Cathode material supply concentration around limited processors exposes mid-tier manufacturers to input cost volatility.
- Spray Technologies:Nozzle precision engineering and flow control calibration separate professional-grade equipment from consumer alternatives. Demand concentrates where REACH chemical registration mandates sealed system certification.
- Applicator Designs:Ergonomic frame and tank configurations differentiate at retail but rarely sustain margin without service revenue attachment.
- Sensors:Flow monitoring and GPS-enabled application tracking remain nascent, with adoption concentrated in large-scale agricultural operations with precision agriculture infrastructure.
Battery technology captures the dominant margin share. Sensor integration is gaining share fastest as precision agriculture requirements diffuse downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German-speaking markets where dealer-network exclusivity sustains service bundling premiums, while Brazilian agricultural cooperatives capture cost advantages through volume procurement of lithium-ion backpack units.
United States
Landscaping fleets in California and Florida are electrifying equipment pools under EPA small off-road engine emission exemptions that accelerate two-stroke gasoline phase-outs. OSHA pesticide exposure limits mandate sealed tank systems that battery architectures accommodate more readily. Municipal procurement in Texas concentrates demand for wheel-mounted configurations replacing ride-on gasoline equipment.
Germany
Commercial agriculture segments in Bavaria and North Rhine-Westphalia face compressed REACH chemical registration timelines that accelerate equipment replacement cycles. The EU F-Gas Regulation tightens compliance thresholds for conventional combustion sprayers across German-speaking markets. Dealer-network exclusivity in Baden-Württemberg controls service revenue streams through maintenance contract bundling.
Brazil
Agricultural cooperatives in São Paulo and Minas Gerais are expanding procurement of lithium-ion backpack units to replace manual knapsack sprayers. Falling battery pack costs enable electrification of equipment pools previously constrained by diesel engine maintenance overhead. Contract spraying services in Rio Grande do Sul concentrate demand as operators modernize fleets.
China
Shandong Province contract spraying services are electrifying equipment pools to meet provincial air quality targets set by MEE. Lithium supply concentration around limited cathode material processors exposes assemblers to input cost volatility. Manufacturing clusters in Jiangsu and Zhejiang dominate brushless motor controller production for domestic and export markets.
France
Commercial agriculture in Île-de-France and Auvergne-Rhône-Alpes faces REACH compliance timelines compressing product launch windows for tank assemblies. The EU F-Gas Regulation redirects procurement budgets toward electric alternatives in professional pest control applications. Nursery operations in Provence-Alpes-Côte d'Azur favor mid-capacity diaphragm pumps for chemical compatibility flexibility.
Battery Powered Sprayer Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive lithium-cell procurement and in-house electromagnetic design capabilities. The capital-intensity gap between these players and component assemblers is collapsing as battery pack costs fall and motor-controller supply broadens. Two strategic archetypes dominate: vertically integrated garden equipment specialists leveraging dealer-network exclusivity, and polyethylene tank molders competing on North American retail shelf placement. Competitive moves center on cell supply agreement securing and regional service infrastructure buildout.
Among European garden equipment specialists, Husqvarna and STIHL exemplify the integrated archetype through captive supply chain positioning and controlled distribution channels. Chapin International occupies a position representing the molding-scale competitive vector. These three anchors illustrate how margin capture diverges between service-revenue bundling and retail placement strategies.
| Leading Market Players |
|---|
| Husqvarna |
| STIHL |
| Chapin International |
| Solo |
| John Deere |
| Greenworks |
| Ryobi |
| Echo |
| Toro |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day cathode material lead times from Jiangsu and Zhejiang processors compress pricing flexibility for mid-tier assemblers lacking long-term offtake agreements, concentrating margin capture with integrated manufacturers holding captive lithium-cell procurement.
Pricing Analysis
Configured-to-order pricing for precision nozzle systems and sealed tank assemblies commands spreads of 35-50 percent above standard backpack configurations. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade equipment with REACH certification from consumer retail alternatives. Cost compression in standard lithium-ion packs is intensifying because cathode material supply broadens and battery management system integration commoditizes. Agricultural cooperatives in Brazil exhibit highest price sensitivity, while German-speaking municipal fleets demonstrate lowest sensitivity due to maintenance contract bundling.
Supply Chain Analysis
Just-in-time inventory strategies dominate among European garden equipment specialists, while North American polyethylene tank molders maintain strategic stockpiles of lithium-ion cells to hedge against semiconductor fabrication constraints in East Asian foundries. Manufacturing gravity centers on China, South Korea, and Germany for cell chemistry, motor controllers, and precision nozzle engineering respectively. The supply chain draws from lithium carbonate, neodymium magnets, and high-density polyethylene as critical inputs. Single-source vulnerability in brushless motor controller sourcing exposes mid-tier assemblers to allocation throttling. Distribution runs through exclusive dealer networks in German-speaking markets and agricultural cooperatives in developing economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emission exemptions for small off-road equipment and EU F-Gas Regulation tightening constitute dual regulatory inflections accelerating displacement of two-stroke gasoline engines, positioning battery-electric architectures for sustained expansion.
For Market Incumbents: Consolidate captive lithium-cell procurement agreements and in-house brushless motor design capabilities to defend against margin erosion from component assemblers. Secure exclusive dealer-network arrangements in German-speaking markets to maintain service revenue bundling premiums. Prioritize sealed tank system certification ahead of compressed REACH compliance timelines in commercial agriculture segments. For New Entrants and Emerging Players: Lead with wheel-mounted municipal fleet configurations in North American jurisdictions replacing ride-on gasoline equipment under EPA exemptions. Target contract spraying services in China's Shandong Province where provincial air quality mandates concentrate electrification demand. Pursue direct procurement relationships with lithium cathode material processors to bypass semiconductor fabrication bottlenecks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized polyethylene tank molding capacity and dormant electromagnetic engineering functions. Five-to-ten-year viability hinges on cell supply agreement security and regional service infrastructure density. Monitor brushless motor controller allocation announcements from East Asian foundries as the primary inflection indicator for assembler margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Lithium Supply Agreement | Secures cathode material offtake from Jiangsu processors, insulating against input cost volatility. |
| Dealer Network Exclusivity Expansion | Captures maintenance contract bundling premiums in Baden-Württemberg and Bavaria agricultural markets. |
| Sealed Tank System Certification | Accelerates REACH compliance positioning ahead of compressed timelines in French and German commercial agriculture. |
| Brushless Motor Controller In-sourcing | Reduces allocation risk from East Asian foundry capacity constraints for mid-tier manufacturers. |
| Municipal Fleet Electrification Partnership | Opens white space for wheel-mounted configurations replacing ride-on gasoline equipment in Texas and California. |
Research Methodology
A spread of perspectives from agricultural cooperative procurement managers, municipal fleet maintenance directors, brushless motor design engineers, and lithium-cell supply chain specialists converged on the working assumptions. Primary fieldwork combined with secondary validation against EPA emission filings, EU F-Gas Regulation implementation notices, and customs trade data for lithium-ion cell imports. Bottom-up equipment shipment tracking and top-down agricultural machinery expenditure analysis provided triangulation across the analysis window.
Segmentation dimensions modeled include product type mobility configuration, end-user capital tier stratification, application precision requirements, and battery technology chemistry differentiation. CAGRs derived from equipment replacement cycle analysis and electrification mandate compliance pacing. Forecast inputs incorporated provincial air quality target enforcement intensity in China and REACH chemical registration timeline compression in Germany and France.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate price stability and semiconductor fabrication capacity expansion would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement pacing and cell chemistry cost curves. Practitioners should keep alternative scenarios live as EPA exemption scope revisions and EU F-Gas threshold adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Rotavator Market