
 Sheep Shearing Equipment Market | 2026-2036
Sheep Shearing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sheep Shearing Equipment Market Analytics
Australian shearing contractors is recalibrating fleet composition toward battery-powered units to reduce generator dependency in outback stations. Heiniger leverages Swiss precision engineering to dominate high-end electric shear segments across Oceania. Horner Shearing anchors its position through deep distribution networks in the British Isles and Commonwealth markets. Lister Shearing Equipment Ltd differentiates via specialized blades and combs that extend equipment lifespan under heavy commercial use.
Sheep shearing equipment encompasses motorized and hand-operated devices engineered to remove wool fleece from ovine animals, with electric shears typically operating at 2,400–3,000 blade strokes per minute to balance speed and animal welfare. These systems serve commercial wool harvesting, show preparation, and veterinary hygiene applications across temperate and semi-arid grazing regions. Electric shears command the dominant revenue share due to throughput advantages in large flock operations, while cordless battery-powered technology is displacing legacy pneumatic systems where compressed air infrastructure remains absent. The sheep farms application segment sustains the deepest equipment replacement cycles, whereas agricultural equipment rental channels are expanding fastest as smaller producers avoid capital ownership.
Biosecurity protocols from Australia's Department of Agriculture, Water and the Environment mandate shearing equipment sanitation standards to prevent disease transmission between properties, directly influencing product design toward easier disassembly and cleaning. New Zealand's Animal Welfare Act shapes blade geometry specifications to minimize skin abrasion during commercial operations. Stakeholders must monitor evolving cordless motor efficiency benchmarks and regional veterinary compliance requirements as technology and welfare standards continue to advance.
Market Dynamics
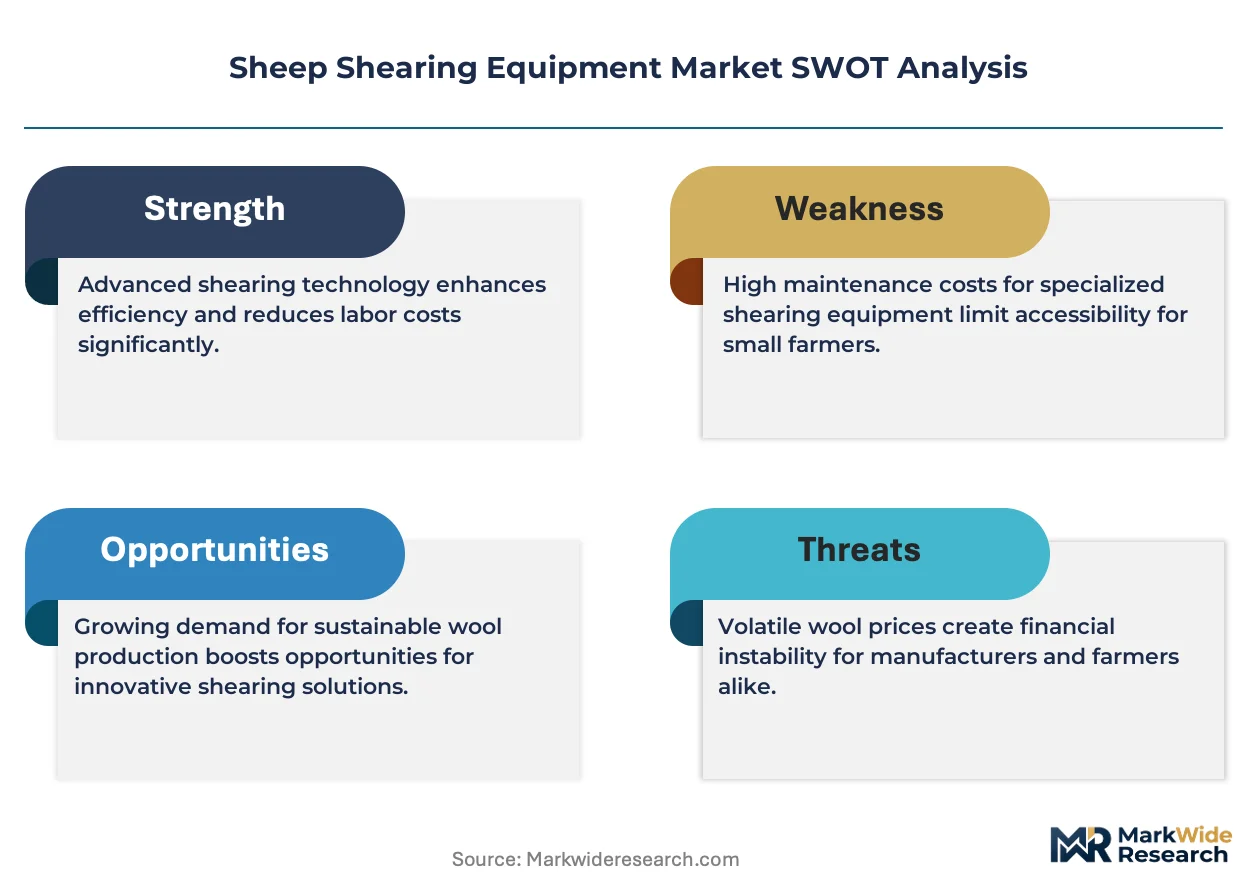
Battery-powered cordless shearing systems are decentralizing power infrastructure requirements across remote pastoral operations, forcing equipment manufacturers to reengineer motor efficiency and thermal management for field durability.
Growth Catalysts
- New Zealand's Animal Welfare Act:Mandates on blade geometry specifications accelerate replacement cycles for non-compliant legacy equipment among South Island merino producers.
- Lithium-ion energy density improvements:Enable full-day shearing operations without generator dependency, expanding viable deployment zones for contractors in Australia's Northern Territory.
- Textile sector wool demand:Commercial processors in Victoria and New South Wales scale mechanized harvesting capacity to secure fiber supply contracts.
Market Restraints
- Copper motor winding costs:Raw material price volatility compresses margins for electric shear manufacturers serving price-sensitive agricultural cooperatives.
- Swiss-German supply concentration:Precision blade and cutter manufacturing clusters in Solingen and Thun create single-source vulnerability for premium component procurement.
- Pneumatic system stranded assets:Existing compressed air infrastructure investments in Queensland feedlots delay conversion timelines despite cordless performance parity.
Strategic Opportunities
- Uruguayan wool sector modernization:Underpenetrated South American markets present first-mover advantages for battery-powered equipment distributors establishing regional service networks.
- Australian biosecurity sanitation mandates:Equipment disassembly and cleaning requirements create aftermarket revenue streams for specialized maintenance tooling and consumables.
- Brushless motor and solid-state battery convergence:Next-generation powertrain architectures promise 40% weight reduction and extended duty cycles for high-volume commercial contractors.
Industry Challenges
- Veterinary hygiene certification timelines:Australia's Department of Agriculture, Water and the Environment approval processes for sanitizable equipment designs extend product development cycles by 8-14 months.
- Shearer technician skill shortages:Declining apprenticeship completion rates in New Zealand's wool harvesting workforce constrain equipment utilization rates and aftermarket parts demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheep Shearing Equipment Market |
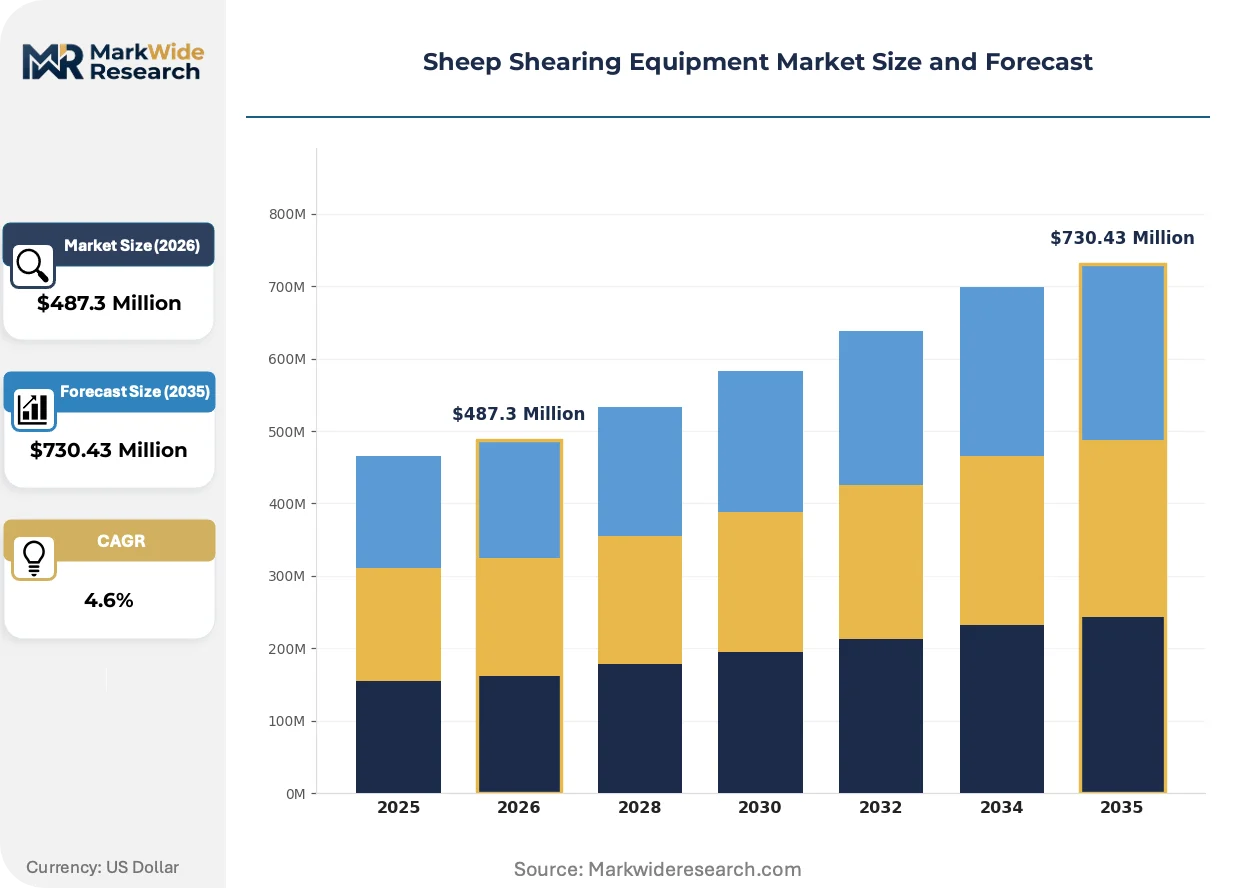
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Shears, Hand Shears, Walk-Behind Shearers, Accessories Application: Sheep Farms, Wool Processing, Agricultural Equipment Rental, Veterinary Services End User: Farmers, Cooperatives, Veterinary Clinics, Agricultural Companies Technology: Cordless, Battery-Powered, Pneumatic, Manual |
| Companies Covered | Heiniger, Horner Shearing, Lister Shearing Equipment Ltd, Welsh Shearing Equipment, Oster, Wahl Clipper Corporation, Kerbl GmbH, National Meditek, Andis Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheep Shearing Equipment Market Evolving Landscape
Powertrain electrification and connected equipment diagnostics are converging to reshape how shearing contractors manage fleet performance and maintenance scheduling across dispersed pastoral operations.
Brushless DC motor architectures are decentralizing maintenance capabilities across Australia's outback station networks. Contractors in Western Australia and South Australia now perform field-level motor replacements without factory technician dispatch. This capability compression reduces equipment downtime from 72 hours to under 4 hours in regions previously dependent on coastal service centers.
Australia's Department of Agriculture, Water and the Environment biosecurity protocols now require documented sanitation between properties. Equipment manufacturers must engineer tool-less disassembly features to comply with field decontamination mandates. Commercial wool processors in Victoria face the steepest compliance burden, driving preference toward equipment with ISO 14159 hygiene design certification.
Rental and lease-to-own arrangements displace outright equipment purchases among smaller flock operators in New Zealand's North Island. Agricultural equipment cooperatives now aggregate demand for seasonal shearing fleets, unbundling capital risk from operational control. This channel shift concentrates procurement authority with regional machinery pools rather than individual farm decision-makers.
Sheep Shearing Equipment Market Segmentation
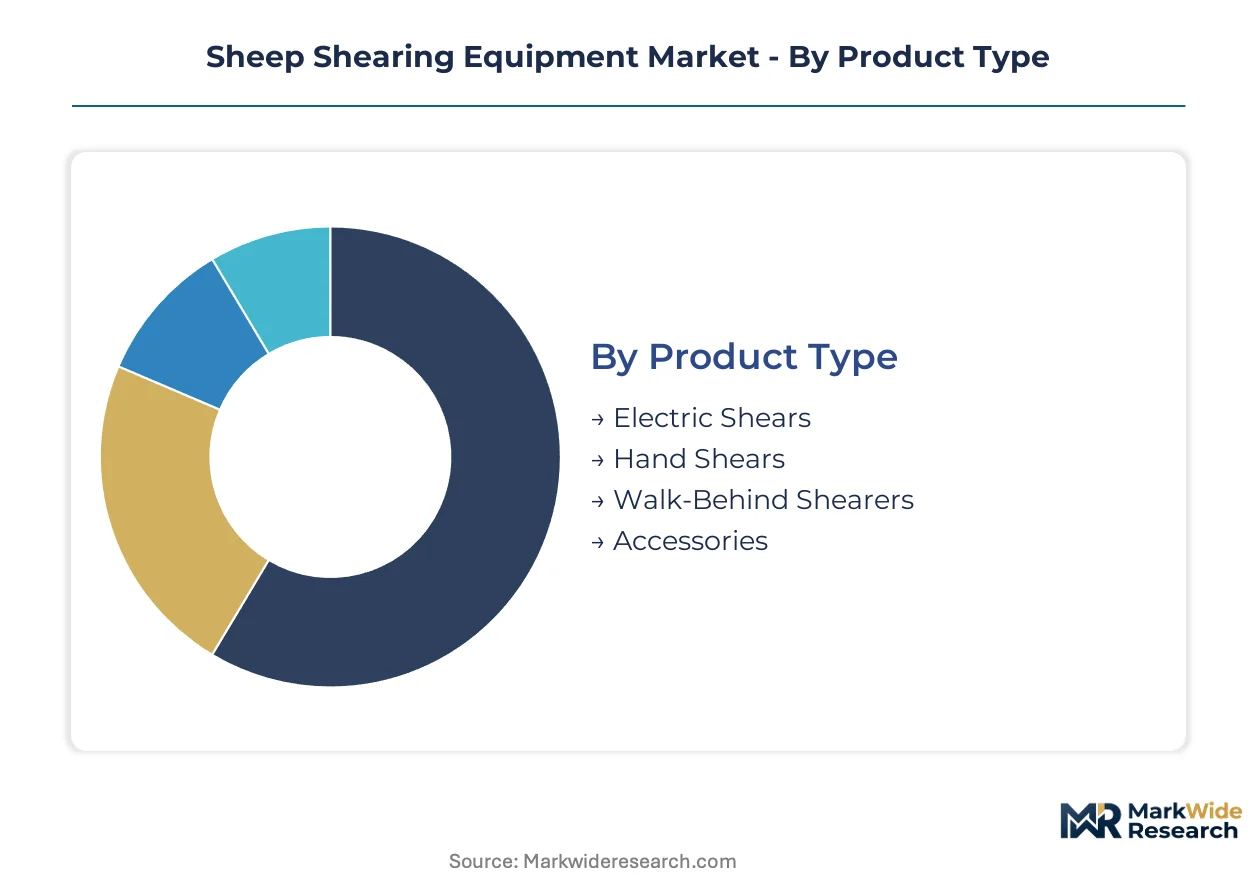
Sheep shearing equipment procurement patterns diverge sharply across operational scales and power infrastructure availability. Contractors operating Australia's remote stations prioritize cordless mobility, while high-volume wool processors optimize for throughput over portability.
Product Type:
Manufacturing capacity clusters around precision-engineered cutting systems, with component sourcing concentrated in Swiss and German industrial centers.
- Electric Shears:Motorized handheld units operating at 2,400–3,000 blade strokes per minute dominate commercial wool harvesting. Victoria's large-scale processors specify these for throughput maximization under Australia's Animal Welfare Act blade geometry mandates.
- Hand Shears:Manual blade systems persist in show preparation and small-flock operations where animal handling precision outweighs speed requirements. New Zealand's South Island merino specialists retain these for premium fleece finishing where fiber quality premiums justify slower processing.
- Walk-Behind Shearers:Stationary mechanized platforms serve feedlot and barn-confinement operations in Queensland.
- Accessories:Replacement blades, combs, and maintenance consumables generate recurring revenue through OEM-locked specifications.
Today's leader: Electric Shears. Tomorrow's challenger: Hand Shears as welfare-certified premium wool commands price premiums.
Application:
End-use concentration determines equipment replacement cycles and aftermarket service intensity across the value chain.
- Sheep Farms:Direct ownership models sustain the deepest replacement cycles, with individual producers operating equipment across 8–12 year lifespans. Australia's outback stations drive demand for field-serviceable cordless systems where technician dispatch costs exceed equipment capital.
- Agricultural Equipment Rental:Seasonal fleet aggregation by machinery pools is expanding fastest among New Zealand's North Island smaller flock operators seeking capital risk unbundling.
- Wool Processing:Commercial fiber processors in Victoria and New South Wales specify industrial-grade electric shears for contract harvesting volume guarantees.
- Veterinary Services:Hygiene-critical applications require ISO 14159-certified disassembly features for biosecurity compliance between properties.
Rental channels are climbing the fastest as capital-light models penetrate smaller producer segments.
End User:
Purchasing authority concentrates differently across organizational structures, shaping distribution channel requirements.
- Farmers:Individual owner-operators in Australia's Northern Territory prioritize battery-powered independence from generator logistics.
- Cooperatives:Aggregated procurement by New Zealand's South Island wool pools concentrates volume discounts and standardizes equipment specifications across member properties.
- Veterinary Clinics:Mobile animal health services specify lightweight cordless units for property-to-property transport under sanitation protocols.
- Agricultural Companies:Corporate wool harvesting contractors in Western Australia maintain captive maintenance capabilities for fleet uptime optimization.
Cooperatives currently anchor procurement volume. Veterinary clinics are gaining share fastest as mobile service models expand.
Technology:
Powertrain architecture selection directly constrains operational geography and infrastructure investment requirements.
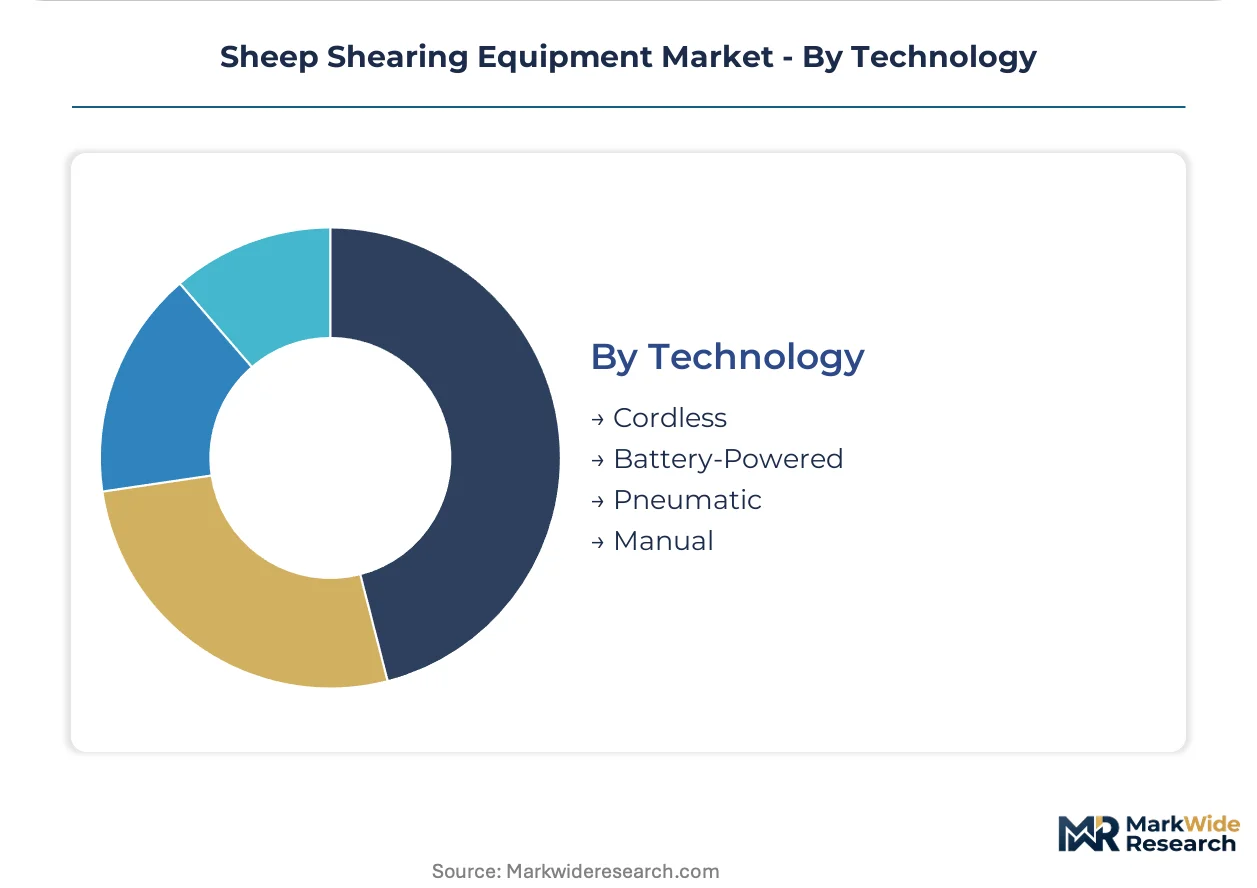
- Cordless:Lithium-ion battery systems with brushless DC motors are displacing legacy pneumatic infrastructure across Australia's remote pastoral zones. Full-day operational capacity without generator dependency now enables contractor deployment to previously inaccessible Northern Territory stations.
- Battery-Powered:Removable pack systems allow field-level power swapping, reducing downtime from 72 hours to under 4 hours in Western Australia's coastal service center-dependent regions.
- Pneumatic:Compressed air systems face stranded asset risk in Queensland feedlots where existing infrastructure delays conversion despite cordless performance parity.
- Manual:Zero-power systems persist in welfare-certified premium segments and developing market entry points where capital constraints dominate.
Cordless systems hold current dominance. Solid-state battery convergence promises next-generation weight and thermal advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands deeper equipment replacement cycles than New Zealand, where rental channel expansion accelerates faster among smaller flock operators seeking capital risk unbundling.
Australia
Victoria's commercial wool processors and Queensland's feedlot operators drive divergent technology preferences. TGA biosecurity protocols mandate documented sanitation between properties under Department of Agriculture, Water and the Environment oversight. Perth anchors Western Australia's service infrastructure, where contractors now perform field-level motor replacements without coastal technician dispatch.
New Zealand
South Island merino specialists sustain premium equipment procurement for welfare-certified fleece finishing. The Animal Welfare Act shapes blade geometry specifications that accelerate replacement cycles for non-compliant legacy systems. Canterbury's agricultural machinery pools concentrate seasonal fleet procurement authority away from individual farm decision-makers.
United States
USDA wool grading standards influence equipment specifications for export-oriented fiber producers in Texas and Wyoming. OSHA workplace safety regulations govern shearer exposure limits in commercial harvesting operations. California's Central Valley hosts specialized veterinary equipment distributors serving mobile animal health services.
United Kingdom
Sheep farming cooperatives in Wales and Scotland aggregate demand for seasonal shearing fleets under Defra agricultural support frameworks. CE marking requirements apply to electric shear imports from Swiss and German manufacturing clusters. Yorkshire's metalworking heritage supports precision blade fabrication for heritage breed specialists.
Uruguay
Underpenetrated South American wool sector modernization creates first-mover opportunities for battery-powered equipment establishing regional service networks. The country's national agricultural regulator oversees import certification for veterinary hygiene equipment. Montevideo's port infrastructure positions the capital as distribution hub for Mercosur market expansion.
Sheep Shearing Equipment Market Competitive Landscape
Swiss-German producers anchor the premium tier; British Commonwealth specialists hold distribution density advantages across former colonial markets. Market structure concentrates around precision-engineered cutting systems with component sourcing vulnerability in Solingen and Thun manufacturing clusters. Three archetypes dominate: Swiss precision engineering houses, British Isles distribution-anchored fabricators, and diversified grooming equipment conglomerates. Competitive moves center on cordless powertrain reengineering and biosecurity-compliant tool-less disassembly features.
Within the Swiss precision tier, Heiniger exemplifies engineering-led positioning through its Thun manufacturing base. Horner Shearing and Lister Shearing Equipment Ltd occupy complementary positions across British Isles and Commonwealth distribution networks, with the latter representing specialized blade and comb fabrication expertise. These three anchors illustrate how geographic origin and corporate structure suffixes signal divergent strategic postures within a market where OEM-locked consumables generate recurring revenue attachment.
| Leading Market Players |
|---|
| Heiniger |
| Horner Shearing |
| Lister Shearing Equipment Ltd |
| Welsh Shearing Equipment |
| Oster |
| Wahl Clipper Corporation |
| Kerbl GmbH |
| National Meditek |
| Andis Company |
| Others |
Value Network & Pricing Analysis
Swiss-German precision engineering tiering separates premium electric shear systems from commoditized pneumatic alternatives, with this bifurcation manifesting in OEM-locked consumable pricing and concentrated component sourcing from Solingen and Thun manufacturing clusters. Australian biosecurity mandates and New Zealand welfare certifications amplify price spreads by embedding compliance costs into premium product architectures while forcing supply chain redundancy around sanitizable design specifications.
Pricing Analysis
Distributor margins of 25-35% separate factory gate pricing from farm-level procurement across Australian and New Zealand channels. Pricing stratifies across premium electric, standard pneumatic, and economy manual tiers, with brushless motor certification and ISO 14159 hygiene design commanding 40-60% premiums. Cost compression in mid-tier pneumatic equipment intensifies as lithium-ion parity erodes legacy system residual value. Agricultural cooperatives in New Zealand's North Island exhibit highest price sensitivity, while Victorian commercial wool processors prioritize throughput over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Australian agricultural equipment distributors mandate qualified secondary suppliers for precision blades and cutter assemblies, compressing sole-source dependency on Swiss-German manufacturing clusters. Component fabrication concentrates in Germany, Switzerland, and China's Yangtze River Delta electronics corridor. Copper motor windings, lithium-ion battery cells, and hardened tool steel represent critical input dependencies. Single-source vulnerability in Solingen blade forging creates tariff exposure under evolving EU-Australia trade frameworks. Distribution runs through agricultural machinery cooperatives and specialized veterinary equipment channels rather than generalist industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Australia's Department of Agriculture biosecurity sanitation mandates and New Zealand's Animal Welfare Act blade geometry specifications continuously refresh equipment replacement demand through compliance-driven obsolescence.
For Market Incumbents: Anticipate cordless technology substitution accelerating pneumatic system stranded asset recognition across Queensland feedlots. Defensive positioning requires captive blade manufacturing capacity in Thun or Solingen clusters to secure supply continuity against Swiss-German concentration risk. Certification investment in ISO 14159 hygiene design creates switching costs against emerging Asian competitors lacking veterinary regulatory relationships. For New Entrants and Emerging Players: Solid-state battery powertrain architectures offer technology-first wedge positioning against incumbent lithium-ion platforms. Uruguayan wool sector modernization presents most penetrable geography, with Montevideo port infrastructure enabling Mercosur regional expansion. Service network density rather than product specification determines winning go-to-market approach among Australian outback contractors. For Investors and Strategic Acquirers: Consolidation pressure builds where veterinary hygiene certification timelines extend product development cycles beyond 8-14 months, favoring acquirers with existing regulatory approval infrastructure. Long-term viability centers on aftermarket consumable attachment rates rather than equipment shipment volumes. Watch brushless motor field-replacement capability penetration as inflection signal for maintenance revenue model durability.| Strategic Initiative | Industry Significance |
|---|---|
| Cordless Powertrain Reengineering | Lithium-ion density gains enable Northern Territory contractor deployment without generator logistics. |
| Biosecurity-Compliant Design Certification | ISO 14159 hygiene features satisfy Australian Department of Agriculture sanitation mandates. |
| Regional Service Network Expansion | Field-level motor replacement capability reduces Western Australia downtime from 72 hours to 4 hours. |
| Aftermarket Consumables Lock-In | OEM-locked blade and comb specifications generate recurring revenue from wool processors. |
| Brushless Motor Architecture Adoption | Solid-state battery convergence promises 40% weight reduction for high-volume contractors. |
Research Methodology
Bottom-up sheep farm and wool processor modeling reconciled against top-down electric shear manufacturing capacity tracking forms the analytical core of this study. Primary interviews with shearing contractors, agricultural equipment cooperative procurement managers, veterinary clinic operators, and OEM aftermarket service heads combined with secondary validation from Australian Bureau of Agricultural and Resource Economics wool production statistics, New Zealand Meat and Wool industry reports, Swiss and German customs export data for precision cutting tools, and SEC filings from diversified grooming equipment conglomerates. Triangulation across these sources ensures demand-side consumption patterns align with supply-side shipment disclosures.
Input-output matrices map lithium-ion battery energy density improvements, brushless motor efficiency benchmarks, and regional veterinary compliance requirements against projected equipment replacement cycles across the modeling period. Segmentation dimensions include product type architecture, application end-use, powertrain technology, and geographic regulatory cluster. CAGRs derive from fitted trend extrapolation moderated by technology substitution elasticity estimates and biosecurity mandate implementation schedules. Wool textile demand forecasts from Victoria and New South Wales commercial processors inform volume assumptions.
The model holds under steady regulatory enforcement intensity and lithium-ion cost decline continuity; deviation in Australian biosecurity protocol expansion pace or solid-state battery commercialization timing would shift equipment replacement cycle assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Farm Tire Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Stock Tanks Market