
 Europe Tea Market | 2026-2036
Europe Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tea Market Analysis
Multi-origin sourcing is hardening as the dominant procurement model across European tea importers. Unilever PLC sustains vast blending and distribution infrastructure spanning multiple continents. Bettys & Taylors of Harrogate Ltd anchors its position through Yorkshire-centric brand heritage and direct-trade relationships with estate gardens. Tata Consumer Products Limited leverages its vertical integration from Indian plantations to European retail shelves, competing on cost discipline and origin traceability.
Europe tea comprises processed leaves of Camellia sinensis and botanical infusions, typically dried and graded by particle size, oxidation level, and volatile oil content for beverage extraction. Black tea undergoes full enzymatic oxidation, producing theaflavins and thearubigins that deliver characteristic color and astringency for breakfast blends and afternoon service. Green tea commands accelerating shelf space expansion as antioxidant positioning and matcha integration reshape HoReCa and specialty store assortments. Herbal tea occupies mature volume pools in supermarkets, while loose-leaf formats capture margin concentration through premium pricing in direct-to-consumer channels.
EFSA pesticide residue thresholds and EU organic certification under Regulation 2018/848 constrain import eligibility and elevate compliance costs for non-EU suppliers. The EU Green Deal's deforestation-free supply chain mandates will force traceability investments across procurement networks. REACH and F-Gas Regulation indirectly shape processing equipment standards for drying and packaging operations. Stakeholders must monitor evolving sustainability disclosure rules under CSRD and prepare for tightened due diligence on labor practices in origin countries.
Market Dynamics
EU Green Deal deforestation-free mandates and Farm to Fork pesticide residue tightening are forcing traceability infrastructure investments across European tea procurement networks, compressing margins for importers lacking direct estate relationships.
Growth Catalysts
- Regulation 2018/848 organic certification:Premium shelf-space allocation in German and French retail channels rewards compliant suppliers with price premiums and listing priority.
- Matcha integration:HoReCa beverage programs and specialty coffee chains are expanding green tea powder procurement for latte formulations and dessert applications.
- Wellness-oriented consumption:United Kingdom consumers are displacing traditional black tea volumes with functional botanical infusions positioned for sleep, digestion, and immunity benefits.
Market Restraints
- Input cost volatility:Kenyan and Sri Lankan auction price swings expose blenders to margin compression during drought or labor disruption cycles.
- Supply concentration risk:East African black tea dominance creates single-origin dependency for breakfast blend formulations.
- EFSA residue thresholds:Maximum residue limit tightening for neonicotinoids and pyrethroids disqualifies conventional Indian and Chinese smallholder lots from EU eligibility.
Strategic Opportunities
- CSRD sustainability disclosure:Mandatory scope 3 emissions reporting creates first-mover advantage for importers with blockchain-traceable estate partnerships.
- Eastern European underpenetration:Poland and Romania retail channels offer volume expansion potential for bagged black tea and fruit infusion entry-price tiers.
- Direct-to-consumer subscription:Loose-leaf curation services bypass supermarket slotting fees and capture recurring revenue from wellness-focused urban households.
Industry Challenges
- Certification timeline compression:EU organic conversion periods and deforestation due diligence documentation are extending new supplier onboarding to 18-24 months.
- Legacy blending infrastructure:Conventional packet lines require capital retrofit for nitrogen-flush packaging that preserves volatile oil integrity in premium green tea.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tea Market |
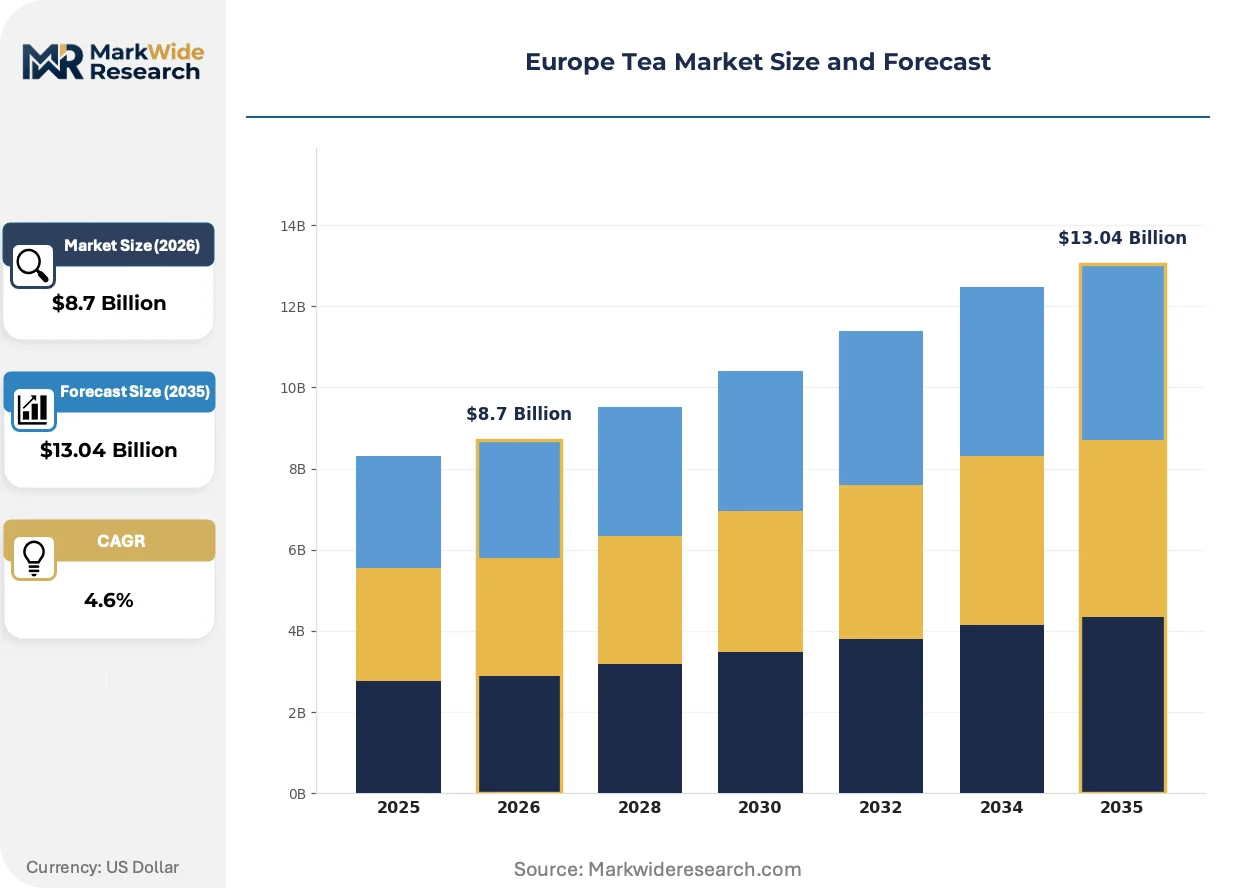
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Oolong Tea Sales Channel: Supermarkets, Online Retail, Specialty Stores, HoReCa Customer Type: Individual Consumers, Businesses, F&B Industry, Retailers Packaging Type: Loose Leaf, Tea Bags, Pouches, Bottled |
| Companies Covered | Tata Consumer Products Limited, Bettys & Taylors of Harrogate Ltd, Unilever PLC, Clipper Teas, Dilmah Ceylon Tea Company PLC, Associated British Foods PLC, Nestlé S.A., Typhoo Tea Ltd, Teekanne GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tea Market Emerging Trajectories
Processing technology, regulatory compliance architecture, and channel configuration are simultaneously restructuring how tea moves from plantation to European consumer cups.
Cold-brew optimized leaf grading is overtaking conventional particle-size specifications in specialty procurement. HoReCa operators and ready-to-drink bottlers are demanding larger leaf surface area and modified oxidation profiles that extract flavor at low temperatures without astringency. This specification shift is compressing demand for traditional dust and fannings grades.
EU Green Deal deforestation-free supply chain mandates are triggering traceability platform investments. Importers must geolocate and document every production plot back to 2020, forcing supplier consolidation around estate-direct relationships. German and Dutch traders with existing plantation equity are absorbing compliance costs that fragment smaller competitors.
Specialty tea shops are displacing supermarket volume as the primary discovery channel for premium origin teas. United Kingdom and French consumers are paying 3-4x multiples for single-estate lots with harvest date transparency, bypassing branded blend intermediaries. This channel rotation is concentrating margin capture with direct-trade importers and eroding traditional wholesaler roles.
Europe Tea Market Segmentation
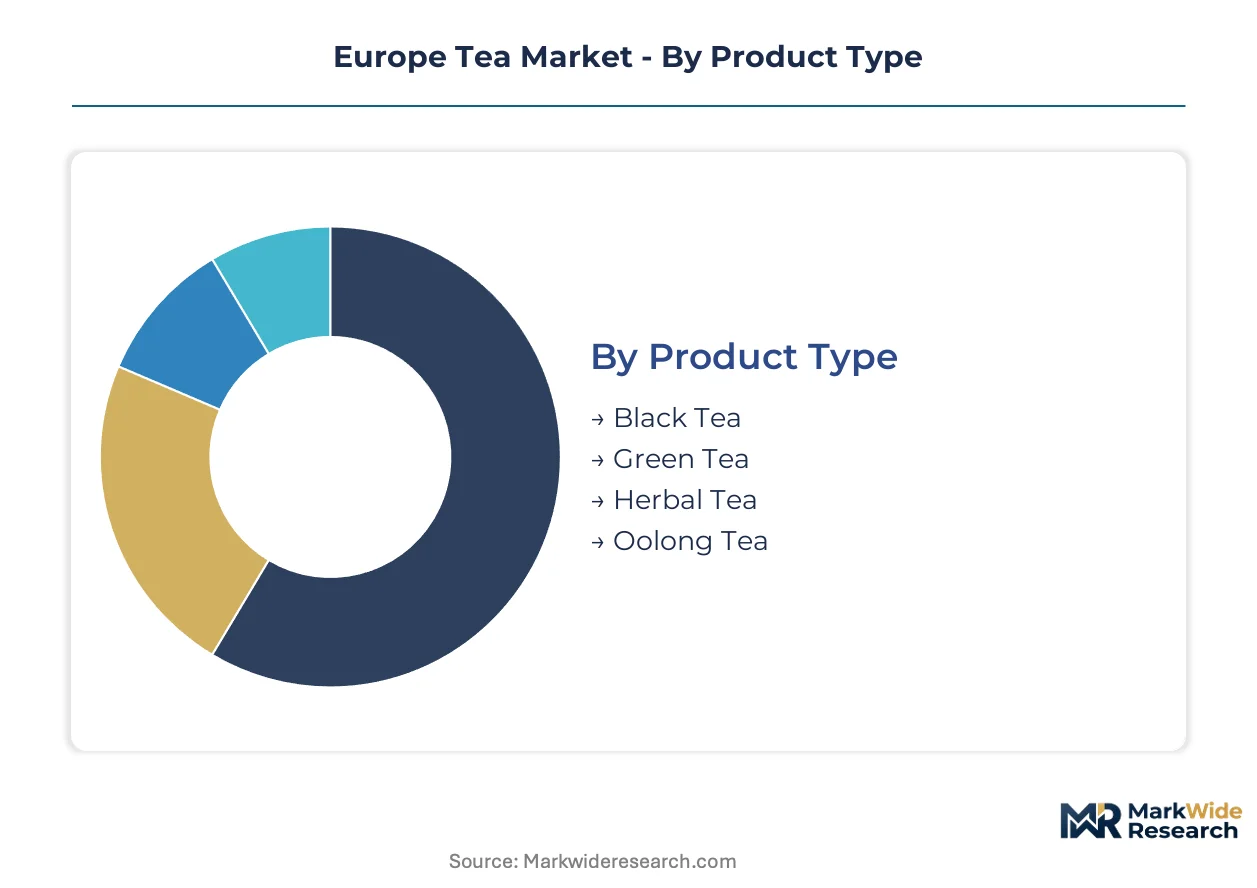
European tea procurement patterns diverge sharply between commodity-grade volume plays and premium origin differentiation. Segmentation reveals where regulatory compliance costs, channel slotting fees, and traceability investments reshape competitive viability across product tiers and customer interfaces.
Product Type:
Black tea dominates volume throughput while green tea commands accelerating premium shelf space and margin capture.
- Black Tea:Fully oxidized leaves producing theaflavins and thearubigins deliver the astringent backbone for breakfast blends across Germany and the United Kingdom. EFSA pesticide residue tightening disqualifies conventional Kenyan auction lots from EU eligibility, forcing blenders toward estate-direct procurement with documented conversion periods.
- Green Tea:Unoxidized leaves preserved through steaming or pan-firing retain catechins and volatile oils prized for antioxidant positioning. Matcha powder integration into French and UK HoReCa latte programs and dessert applications is displacing traditional bagged formats in urban specialty channels.
- Herbal Tea:Botanical infusions excluding Camellia sinensis occupy mature supermarket volume pools in German and French retail, with functional sleep and digestion claims capturing wellness-oriented household displacement from black tea.
- Oolong Tea:Semi-oxidized processing spanning 10-80% oxidation delivers complex aromatic profiles for specialty shop curation and direct-to-consumer subscription services in UK and French urban markets.
Mature deployment sits with Black Tea. Newer deployment is concentrated in Green Tea.
Sales Channel:
Channel selection determines whether suppliers absorb supermarket slotting fees or capture direct margin through relationship-based recurring revenue.
- Supermarkets:Mass retail chains in Germany, France, and the United Kingdom extract listing fees and demand promotional support, compressing margins for branded blenders while guaranteeing volume throughput for compliant organic lines.
- Online Retail:Direct-to-consumer platforms bypass physical shelf constraints and enable harvest-date transparency and estate storytelling for premium origin teas, with UK and German urban households driving subscription curation growth.
- Specialty Stores:Independent tea merchants and loose-leaf boutiques in Paris, London, and Berlin capture 3-4x pricing multiples through single-estate lots and in-house blending, eroding traditional wholesaler intermediary roles.
- HoReCa:Hotels, restaurants, and cafés in premium UK and French hospitality venues are expanding loose-leaf and organic procurement for afternoon service and wellness-oriented beverage programs.
Volume concentration remains with Supermarkets. Margin expansion is accelerating fastest in Specialty Stores.
Customer Type:
Procurement sophistication varies from individual pantry replenishment to institutional tender compliance and traceability documentation.
- Individual Consumers:Household purchasing in Germany, the UK, and France is fragmenting between commodity bagged tea for daily consumption and premium loose-leaf for wellness-oriented ritual occasions.
- Businesses:Corporate catering and office beverage services in UK and German metropolitan areas are specifying organic certification and nitrogen-flush packaging for volatile oil preservation.
- F&B Industry:Ready-to-drink bottlers and cold-brew operators are demanding modified leaf grading specifications optimized for low-temperature extraction without astringency.
- Retailers:Supermarket chains and specialty merchants are consolidating supplier bases around estate-direct relationships capable of delivering EU Green Deal deforestation-free documentation back to 2020.
Established procurement patterns define Individual Consumers. Emerging specification complexity is concentrated in F&B Industry.
Packaging Type:
Format selection signals price tier positioning and determines processing equipment investment for volatile oil preservation.
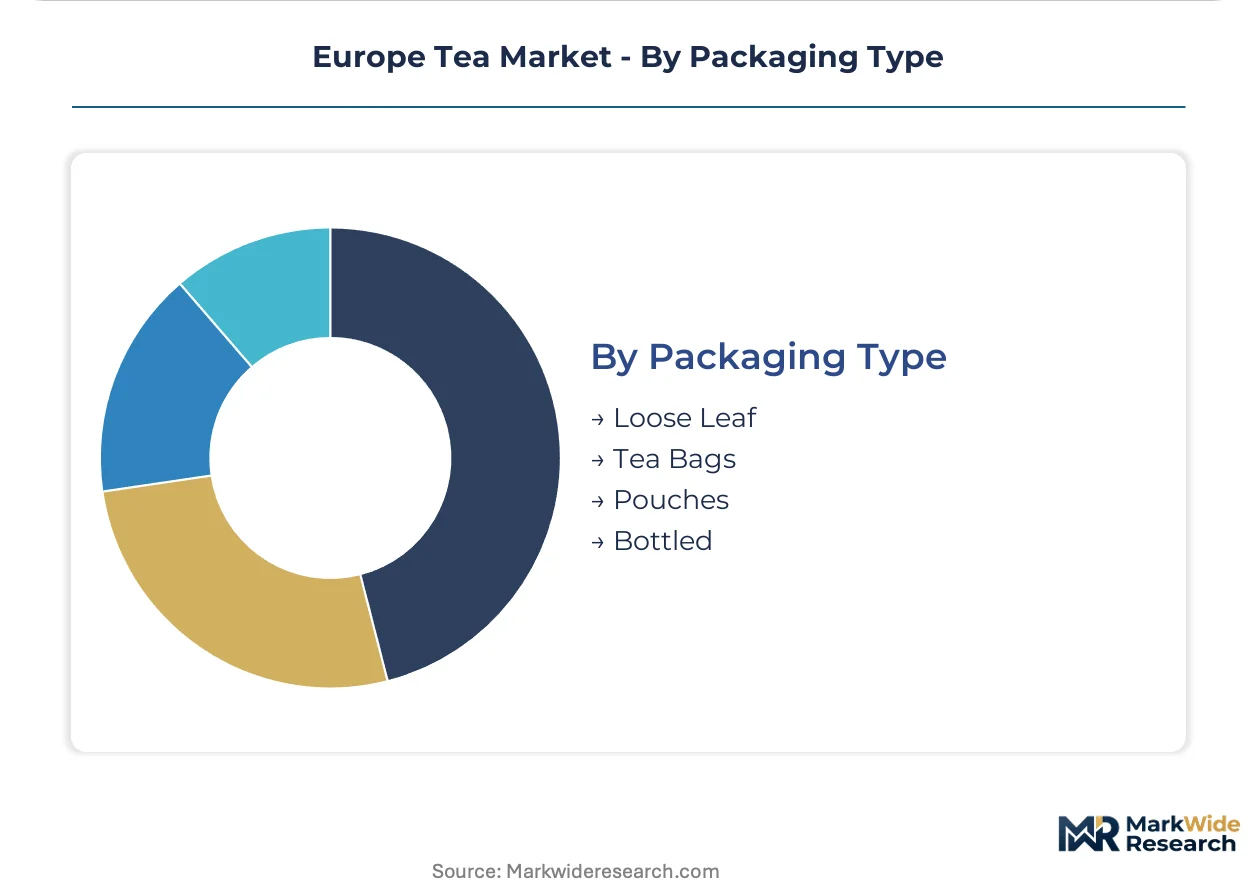
- Loose Leaf:Unrestricted leaf presentation enables origin transparency and premium pricing in direct-to-consumer and specialty retail channels, with German and UK consumers paying multiples for harvest-date specificity.
- Tea Bags:Standardized dust and fannings grades in double-chamber or pyramid formats dominate German and UK supermarket volume, though conventional packet lines require capital retrofit for nitrogen-flush capability.
- Pouches:Flexible resealable formats for loose-leaf and herbal blends balance convenience with premium positioning in French and German specialty retail.
- Bottled:Ready-to-drink cold-brew and functional tea beverages are expanding HoReCa and convenience retail presence in UK and French urban markets.
Volume leadership remains with Tea Bags. Premiumization momentum is strongest in Loose Leaf.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East African auction houses in Mombasa and Colombo supply the bulk black tea that German and British blenders convert into breakfast formulations. The regional market fragments across distinct national consumption rituals and regulatory enforcement intensities.
Germany
East Frisian tea culture sustains per-capita consumption leadership through strong black tea rituals and heavy cream service traditions. EFSA pesticide residue thresholds under EU Regulation 396/2005 disqualify conventional auction lots, pushing Hamburg-based importers toward estate-direct procurement with full conversion documentation. Berlin specialty merchants are displacing supermarket channels for premium Darjeeling and Assam single-origin lots.
United Kingdom
Afternoon tea service traditions and daily pantry replenishment sustain volume demand, though wellness-oriented consumers are displacing black tea with functional botanical infusions. The UK's post-Brexit retained EU law maintains EFSA residue standards while adding UK REACH chemical compliance for packaging materials. London's Marylebone and Notting Hill districts host expanding loose-leaf boutiques capturing 3-4x pricing multiples through harvest-date transparency.
France
Parisian salon culture and gastronomic tea pairing traditions drive premium positioning for Grand Cru classifications and single-estate lots. ANSM and DGCCRF enforcement of EU 2018/848 organic certification creates listing priority for compliant suppliers in Monoprix and Carrefour channels. The Marais and Saint-Germain-des-Prés districts concentrate specialty tea merchants bypassing traditional wholesale intermediaries.
Netherlands
Rotterdam port infrastructure and historical trading house dominance sustain bulk blending and re-export operations across Continental Europe. Dutch implementation of EU Green Deal deforestation-free supply chain mandates forces geolocation documentation back to 2020 for all imported leaf. Amsterdam's De Pijp district hosts emerging direct-to-consumer subscription services targeting wellness-focused urban households.
Poland
Price-sensitive household consumption and underdeveloped premium channels create volume expansion potential for bagged black tea and fruit infusion entry tiers. Polish alignment with EU organic regulation 2018/848 proceeds through phased implementation, delaying full compliance timelines versus Western counterparts. Warsaw and Kraków retail corridors concentrate modern trade expansion by German and British branded blenders seeking Eastern European growth.
Europe Tea Market Vendor Landscape
Direct-trade estate partnerships dominate the current landscape as importers absorb EU Green Deal compliance costs that fragment smaller competitors. The vendor base concentrates around three strategic tiers: multinational blenders with continental distribution infrastructure, heritage British brands with Yorkshire-centric provenance claims, and Indian plantation-integrated suppliers competing on origin traceability. Strategic archetypes include volume-driven commodity blenders, premium origin curators, and vertically integrated estate operators. M&A activity and traceability platform investments constitute the dominant competitive moves reshaping procurement relationships.
Within the multinational blender tier, Unilever PLC and Associated British Foods PLC exemplify scale-driven consolidation spanning multiple continents and retail channels. Among heritage-positioned British operators, Bettys & Taylors of Harrogate Ltd and Typhoo Tea Ltd occupy positions anchored in regional provenance and direct-trade relationships with estate gardens. At the plantation-integrated end, Tata Consumer Products Limited represents backward integration from Indian growing regions to European retail shelves, competing on cost discipline and documented origin traceability that satisfies tightening EFSA residue thresholds.
| Leading Market Players |
|---|
| Tata Consumer Products Limited |
| Bettys & Taylors of Harrogate Ltd |
| Unilever PLC |
| Clipper Teas |
| Dilmah Ceylon Tea Company PLC |
| Associated British Foods PLC |
| Nestlé S.A. |
| Typhoo Tea Ltd |
| Teekanne GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal deforestation-free mandates gate qualified supply and premium-tier pricing access, forcing importers to absorb estate-direct traceability costs that fragment smaller competitors while compliant players capture organic certification premiums in German and French retail channels.
Pricing Analysis
Warranty and service bundling separates estate-direct relationships with full conversion documentation from conventional auction-lot procurement lacking residue compliance guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by organic certification under EU Regulation 2018/848 and harvest-date transparency, with specialty merchants in London and Paris capturing 3-4x multiples for single-estate lots. Pricing pressure stems from EFSA residue threshold tightening that disqualifies conventional Kenyan and Indian smallholder lots, compressing margins for blenders dependent on auction sourcing. Individual consumers in Germany and the United Kingdom exhibit highest price sensitivity for daily pantry replenishment, while HoReCa operators in premium French hospitality venues demonstrate lowest sensitivity for loose-leaf organic procurement.
Supply Chain Analysis
Return and refurbishment flows are negligible for dried leaf products, though quality downgrade pathways redirect non-compliant lots to non-EU markets when residue testing fails EFSA thresholds. Geographic supply concentrates in Kenya, Sri Lanka, and India for black tea throughput, with China and Japan anchoring green tea and matcha powder flows. Raw material dependencies center on seasonal leaf harvests, nitrogen-flush packaging films, and organic conversion documentation. Single-origin vulnerability runs through East African auction dominance for breakfast blend formulations. Distribution runs through Rotterdam port infrastructure and Hamburg-based importers for Continental European re-export, with direct-to-consumer subscription services bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Regulation 2018/848 organic certification and deforestation-free documentation requirements create a barrier-to-entry moat that rewards first-mover estate partnerships and fragments capital-constrained competitors.
For Market Incumbents: Cement estate-direct procurement relationships with documented conversion periods and blockchain-traceable geolocation data to satisfy EU Green Deal mandates. Expand nitrogen-flush packaging capacity for volatile oil preservation in premium green tea lines. Absorb compliance costs that disqualify smaller rivals from German and French retail listing eligibility.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription curation targeting wellness-focused urban households in Amsterdam and Berlin, bypassing supermarket slotting fees. Target Polish and Romanian retail corridors for bagged black tea entry-price tiers where premium channel saturation remains underdeveloped. Exploit certification timeline compression gaps by acquiring distressed estate relationships from legacy importers facing working capital constraints.
For Investors and Strategic Acquirers: Dutch trading house adoption of blockchain-traceable procurement platforms is the leading indicator that compliance infrastructure is becoming a differentiable asset class. Long-term viability favors vertically integrated operators with captive plantation equity and Rotterdam port access. Monitor German specialty merchant consolidation patterns for early signals of estate-direct relationship scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Estate-Direct Procurement Consolidation | Absorbs EU Green Deal compliance costs that fragment auction-dependent competitors. |
| Blockchain Traceability Platform Deployment | Enables CSRD scope 3 emissions reporting and deforestation-free documentation back to 2020. |
| Nitrogen-Flush Packaging Retrofit | Preserves volatile oil integrity in premium green tea for HoReCa and specialty retail channels. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and captures recurring revenue from urban wellness households. |
| Eastern European Distribution Expansion | Accesses underpenetrated Polish and Romanian volume pools for bagged black tea entry tiers. |
Methodological Framework
Independent corroboration across plantation procurement directors, Hamburg and Rotterdam trading house executives, German supermarket category buyers, and French specialty tea merchants underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EFSA residue limit publications, EU Regulation 2018/848 implementation guidance, customs import records, and CSRD sustainability disclosure drafts anchored the analysis. Bottom-up volume modeling across product type, sales channel, and customer type segments triangulated against top-down macroeconomic consumption indicators.
Comparable-period anchoring to historical procurement patterns and consumption rituals across Germany, the United Kingdom, and France established the forecast baseline. Segmentation dimensions modeled include product type oxidation levels, packaging format nitrogen-flush capability, and customer type procurement sophistication. CAGRs derived from weighted average growth assumptions across the projection horizon, incorporating matcha integration velocity, wellness-oriented consumption displacement rates, and Eastern European modern trade expansion timelines.
Kenyan auction price volatility, Sri Lankan labor disruption cycles, and EFSA residue threshold revisions are the dominant revision risks to modeled outputs. Practitioners should monitor EU Green Deal implementation timelines and organic conversion period extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Camellia Sinensis Leaf Extract Market
Tea
Tea Pitchers Market
Tea
Moringa Tea Market
Tea
Tea Essence Market
Tea
Tea Infuser Market
Tea
Smart Tea Set Market
Tea
Tea Subscription Market
Tea
Single Origin Tea Market
Tea
China Tea Market
Tea
Tea Concentrate Market
Tea
US RTD Organic Tea Market
Tea
Global Tea Extract Market
Tea
Global Tea Market
Tea
Green Tea Extract Market
Tea
Nitro Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market