
 Plant-Based Butter Market | 2026-2036
Plant-Based Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Butter Market Outlook
Premium cultured and European-style grade tiers is unwinding conventional commodity positioning across the plant-based butter category. Miyoko's Creamery leverages fermentation-derived cultures to sustain authenticity cues in high-end retail. Upfield anchors global volume through its Flora and Country Crock portfolios. Califia Farms competes on almond and oat-based formulations with clean-label positioning.
Plant-based butter denotes a spreadable fat emulsion formulated from vegetable oils, lecithin, and water, typically containing 78-80% fat content with emulsion stability engineered through scraped-surface heat exchange. It substitutes dairy butter in baking, sautéing, and direct consumption applications where thermal stability and mouthfeel replication determine functional performance. Spreadable formats lead retail velocity due to convenience positioning, while baking-grade formulations command formulation premiums from commercial end-users. Coconut oil and avocado oil source bases are capturing fastest-growing status as consumers prioritize saturated fat profiles and clean ingredient decks.
The FDA maintains active scrutiny of plant-based dairy labeling standards, while the EU Green Deal and EFSA sustainability frameworks shape agricultural input sourcing requirements for European manufacturers. These regulatory layers elevate compliance costs but simultaneously validate product legitimacy for mainstream retail placement. Stakeholders must monitor evolving allergen disclosure mandates and carbon accounting rules that will determine which oil sources and packaging formats retain shelf access.
Market Dynamics
Fermentation-derived lipid structuring is compressing formulation cycles as manufacturers engineer cultured plant-based butters that replicate dairy mouthfeel without hydrogenation, forcing capital reallocation toward bioprocessing infrastructure and away from conventional oil-blending assets.
Growth Catalysts
- EU Green Deal agricultural sustainability targets:Binding carbon intensity benchmarks for oilseed cultivation are accelerating certified sustainable palm and coconut sourcing programs across European manufacturing bases.
- Bakery chain procurement mandates:Artisanal and commercial bakeries in Germany and the United Kingdom are specifying plant-based butter for clean-label product lines, creating pull-through demand for spreadable and baking-grade formulations.
- Scraped-surface heat exchange engineering:Advanced emulsion stability technology is enabling 78-80% fat content products with thermal performance matching dairy butter in laminated dough applications.
Market Restraints
- Coconut oil price volatility:Concentrated supply from Southeast Asian producers exposes margins to weather-driven harvest fluctuations and freight cost spikes.
- FDA plant-based dairy labeling scrutiny:Evolving guidance on "butter" nomenclature creates compliance uncertainty and potential reformulation costs for US-market products.
- Technical emulsion breakdown:Plant-based fats lack native milk protein structures, requiring lecithin and hydrocolloid stabilizers that complicate clean-label positioning.
Strategic Opportunities
- Avocado oil source expansion:Mexico and California production zones offer untapped supply for premium saturated-fat-profile positioning in North American retail.
- Food service bulk channel penetration:Untapped institutional baking and restaurant sautéing applications in the United States represent volume scale beyond current retail concentration.
- EFSA sustainability framework alignment:Early carbon accounting certification under emerging EU agricultural input rules secures preferential retail placement as disclosure mandates tighten.
Industry Challenges
- Fermentation technologist scarcity:Cultured product development requires specialized microbiology and lipid biochemistry expertise that outpaces current talent pipeline output.
- Clean-label stabilizer substitution:Removing modified starches and artificial emulsifiers while maintaining shelf stability demands extended R&D timelines and capital-intensive pilot scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Butter Market |
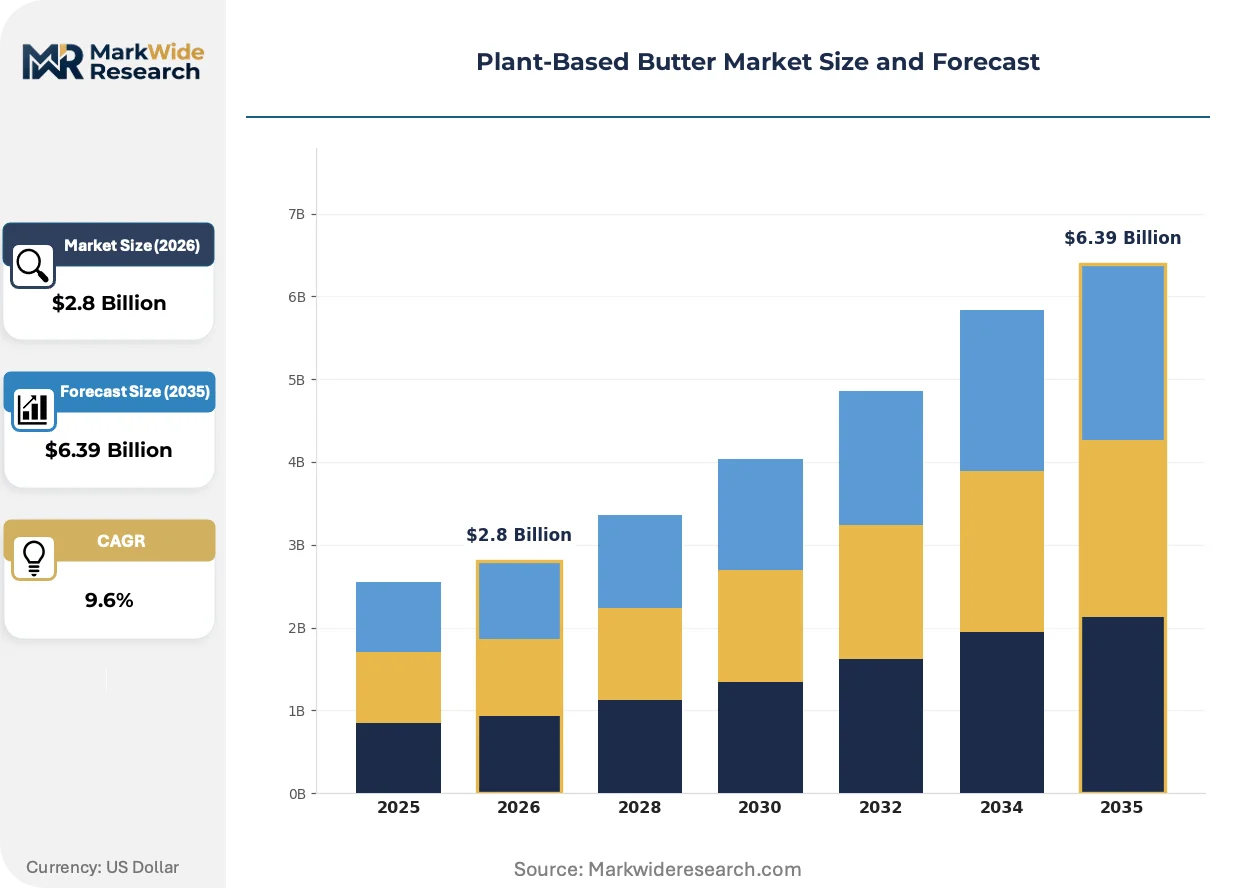
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Baking, Cooking, Confectionery Source: Coconut Oil, Almond Oil, Soybean Oil, Avocado Oil Packaging Type: Tub, Stick, Pouch, Jar Distribution Channel: Supermarkets, Online, Specialty Stores, Food Service |
| Companies Covered | Naturli Foods, Kite Hill, Upfield, Bunge Global, Ripple Foods, Conagra Brands, Califia Farms, Danone, Miyoko's Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Butter Market Strategic Shifts
Lipid structuring biotechnology and regulatory carbon accounting are converging to redefine competitive advantage, separating manufacturers with in-house fermentation capabilities from commodity oil blenders.
Precision fermentation of dairy-identical milk fats from microbial hosts is miniaturizing the performance gap between plant-based and conventional butter. Bakery R&D departments in the United Kingdom and Germany are piloting these ingredients for croissant lamination and shortbread applications where thermal behavior determines product acceptance. The technology is compressing the premium tier definition by enabling authentic cultured flavor profiles without animal agriculture inputs.
The EU Green Deal's Farm to Fork strategy is mandating deforestation-free supply chain verification for palm and coconut oil imports by 2025. European manufacturers are restructuring procurement to satellite-monitored certified sources, with compliance costs filtering through to shelf price architecture. German retailers are responding by creating dedicated shelf sections for verified-sustainable plant-based fats, privileging early adopters with placement velocity.
Direct-to-food-service distribution is displacing traditional broker networks for bulk baking-grade formulations. Specialty distributors in the United States are building temperature-controlled logistics dedicated to plant-based fats, shortening lead times for regional bakery chains. This channel restructuring is most visible in California and Texas, where restaurant group consolidation has created centralized procurement offices seeking single-source specialty fat suppliers.
Plant-Based Butter Market Segmentation
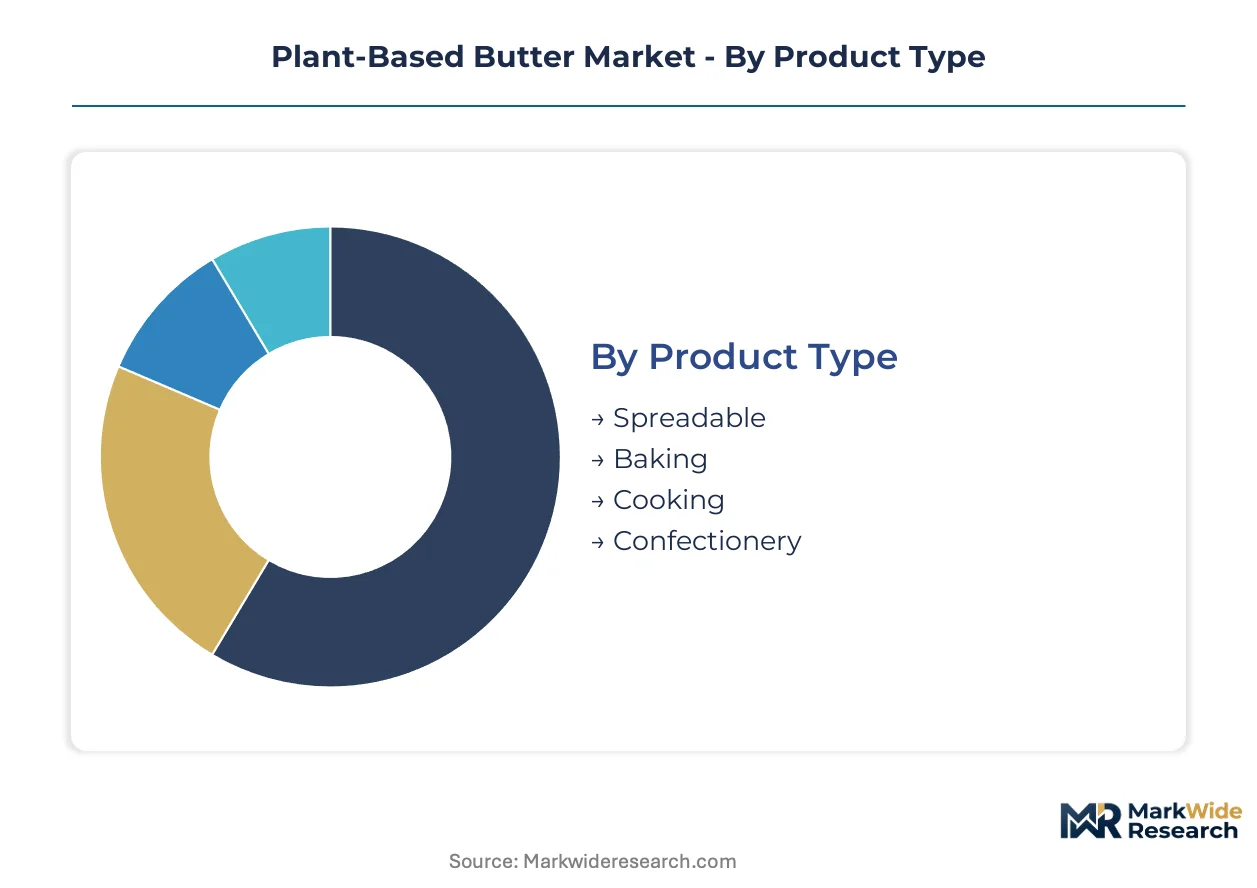
Segmentation in plant-based butter reveals how formulation specifications, packaging formats, and channel economics allocate margin pools across the value chain. Manufacturers configure production assets around fat-content tolerances and emulsion stability requirements that vary sharply by end-use application.
Product Type:
Spreadable formats dominate retail shelf placement through convenience positioning, while baking and cooking grades concentrate in commercial procurement channels with volume-based contracting.
- Spreadable:Formulated at 78-80% fat content with engineered emulsion stability for direct consumption. German and UK supermarket chains allocate prime refrigerated placement to these SKUs, driving velocity through breakfast and snacking occasions. Margins compress as private-label penetration deepens.
- Baking:Thermal stability specifications match dairy butter performance in laminated dough and shortbread applications. Artisanal bakeries in the United Kingdom specify these formulations for clean-label product lines, creating pull-through demand with formulation premiums attached.
- Cooking:Higher smoke-point engineering for sautéing and pan-frying applications. Restaurant procurement offices in California and Texas are consolidating supplier relationships around bulk formats.
- Confectionery:Precision fat crystallization for chocolate tempering and ganache applications. European confectionery manufacturers trial these as EU Green Deal sustainability targets tighten agricultural input requirements.
By volume, spreadable leads. By growth pace, baking-grade formulations are climbing the fastest as commercial end-users convert procurement specifications.
Source:
Raw material selection determines carbon intensity profiles and clean-label positioning that increasingly gate retail access under emerging sustainability disclosure mandates.
- Coconut Oil:Dominates current formulation bases with saturated fat profiles that replicate dairy mouthfeel. Southeast Asian supply concentration exposes margins to weather-driven harvest volatility and freight cost spikes that manufacturers hedge through forward contracting.
- Almond Oil:Califia Farms and similar competitors leverage California supply chains for allergen-conscious positioning. Water intensity of almond cultivation is attracting scrutiny from sustainability-focused retailers.
- Soybean Oil:Lowest-cost base oil with established commodity trading infrastructure. Genetic modification disclosure requirements complicate clean-label positioning in European markets.
- Avocado Oil:Premium saturated-fat-profile positioning commands shelf price architecture in North American retail. Mexico and California production zones offer expansion potential as food service channels specify specialty fat sources.
By volume, coconut oil leads. By margin expansion, avocado oil is gaining share fastest as premium tier definitions compress.
Packaging Type:
Format selection aligns with consumption occasion and channel economics, with bulk formats penetrating food service as retail stick and tub configurations standardize.
- Tub:Dominates household penetration through spreadable convenience positioning. Refrigerated dairy case placement in US supermarkets drives impulse purchase velocity.
- Stick:Baking occasion targeting with measurement markings and wrapper configurations familiar to dairy butter users. German retailers feature these in dedicated plant-based sections.
- Pouch:Emerging format for food service bulk dispensing and sampling programs. Reduced material intensity aligns with packaging sustainability targets.
- Jar:Premium gifting and specialty retail positioning. UK artisanal food channels favor glass packaging for shelf differentiation.
By volume, tub formats lead. By channel expansion, pouch configurations show steepest trajectory as food service penetration accelerates.
Distribution Channel:
Channel mix is shifting as direct-to-food-service distribution displaces traditional broker networks and e-commerce captures trial-driven household conversion.
- Supermarkets:Refrigerated dairy case placement remains the primary volume driver. German and UK retailers are creating dedicated shelf sections for verified-sustainable plant-based fats.
- Online:Subscription and direct-to-consumer models capture trial and loyalty program engagement. Califia Farms and Miyoko's Creamery leverage this channel for premium positioning.
- Specialty Stores:Health food and organic channels prioritize clean-label and certified-sustainable sourcing credentials. Margin structures support smaller-batch production economics.
- Food Service:Untapped institutional baking and restaurant sautéing applications in the United States represent volume scale beyond retail concentration. Specialty distributors are building temperature-controlled logistics dedicated to plant-based fats.
By volume, supermarkets lead. By growth pace, food service channels are expanding most quickly as procurement offices consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation-grade coconut oil and shea butter supply chains concentrate in Southeast Asian processing hubs, while finished product manufacturing clusters in Germany, the United Kingdom, and the United States where retail distribution infrastructure and food service penetration have matured most substantially.
Germany
Artisanal bakery chains and discount supermarket private-label programs drive procurement volumes for spreadable and baking-grade formulations. The EU Green Deal's Farm to Fork strategy mandates deforestation-free supply chain verification for palm and coconut oil imports by 2025, forcing manufacturers to restructure procurement toward satellite-monitored certified sources. Berlin and Hamburg host reformulation R&D facilities where manufacturers pilot precision fermentation-derived lipid structuring for clean-label positioning.
United Kingdom
Supermarket dedicated shelf sections for verified-sustainable plant-based fats and croissant lamination trials in commercial bakery R&D departments create dual-channel demand pull. EFSA sustainability frameworks shape agricultural input sourcing requirements, elevating compliance costs but validating product legitimacy for mainstream retail placement. London and the Midlands concentrate distribution infrastructure where specialty distributors build temperature-controlled logistics for food service bulk formats.
United States
Restaurant group consolidation in California and Texas has created centralized procurement offices seeking single-source specialty fat suppliers for sautéing and baking applications. FDA scrutiny of plant-based dairy labeling standards creates compliance uncertainty, particularly for "butter" nomenclature claims. The Pacific Northwest and Northeast corridor anchor retail velocity through refrigerated dairy case placement and direct-to-consumer subscription models.
France
Confectionery manufacturers trial plant-based butter formulations for chocolate tempering and ganache applications as EU agricultural sustainability targets tighten input requirements. ANSM and DGCCRF enforcement of allergen disclosure mandates elevates formulation transparency standards. The Île-de-France region hosts headquarters operations for multinational dairy-alternative portfolios expanding cultured product lines.
Netherlands
Rotterdam port infrastructure facilitates bulk oil import and re-export to European manufacturing bases, while domestic retail channels prioritize clean-label and certified-sustainable sourcing credentials. REACH compliance for lecithin and emulsifier additives shapes formulation choices. The Randstad region concentrates logistics providers developing dedicated cold-chain capabilities for plant-based fat distribution.
Plant-Based Butter Market Competitive Environment
Concentration sits with multinational food conglomerates and specialized dairy-alternative pioneers that have secured refrigerated retail placement and food service distribution contracts. The competitive structure stratifies across three tiers: global volume leaders with diversified oilseed sourcing infrastructure, premium cultured specialists leveraging fermentation-derived authenticity cues, and regional private-label suppliers competing on price. Dominant competitive moves include backward integration into certified sustainable oil supply chains and technology licensing agreements for scraped-surface heat exchange emulsion engineering.
Within the premium cultured tier, Miyoko's Creamery and Califia Farms exemplify positioning strategies built on fermentation-derived flavor profiles and clean-label ingredient decks. Upfield anchors the volume-driven segment through portfolio breadth and established retail relationships. These three entities represent distinct archetypes: the microbiology-forward specialist, the almond-oil-based challenger, and the global scale incumbent.
| Leading Market Players |
|---|
| Naturli Foods |
| Kite Hill |
| Upfield |
| Bunge Global |
| Ripple Foods |
| Conagra Brands |
| Califia Farms |
| Danone |
| Miyoko's Creamery |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal deforestation-free certification gates both supply qualification and price differentiation, forcing manufacturers to absorb compliance premiums or surrender shelf placement to verified competitors. Certification status now functions as a pricing tier separator in German and UK retail channels.
Pricing Analysis
FDA plant-based dairy labeling scrutiny dictates the pricing tier structure by elevating compliance costs for US-market products while EU sustainability frameworks enable premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and oil source provenance. Cost compression in economy tiers is intensifying because private-label penetration deepens in German discount channels. Food service procurement offices show least price sensitivity, prioritizing thermal performance specifications over unit cost.
Supply Chain Analysis
Strategic stockpiling of coconut and palm oil inventories dominates over just-in-time approaches due to Southeast Asian harvest volatility and freight cost spikes. Supply concentrates in Indonesia, Malaysia, and the Philippines for coconut oil feedstocks, while shea butter processing clusters in West Africa. Formulation draws from lecithin emulsifiers, hydrocolloid stabilizers, and fermentation-derived cultures as critical inputs. Single-source vulnerability in Southeast Asian oilseed supply creates margin exposure to weather-driven disruptions. Distribution runs through temperature-controlled specialty distributors for food service bulk channels and refrigerated retail dairy cases for household formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU deforestation-free certification and FDA labeling standards creates defensive moats for incumbent manufacturers with established compliance infrastructure. Switching costs for bakery chain procurement offices reinforce position stability.
For Market Incumbents: Shield market share by deepening backward integration into satellite-monitored certified oil supply chains and accelerating fermentation capability buildout. Precision fermentation-derived lipid structuring represents the critical R&D lever against commodity oil blender competition. Channel control through direct-to-food-service distribution contracts locks out broker-dependent challengers. For New Entrants and Emerging Players: Lead with food service bulk channel penetration in California and Texas restaurant group procurement offices, the most penetrable white-space target. Avocado oil source positioning offers differentiation in North American premium retail where sustainability credentials command shelf price architecture. Subscription-based direct-to-consumer models enable trial conversion without refrigerated dairy case placement barriers. For Investors and Strategic Acquirers: EU Green Deal Farm to Fork deforestation-free mandates reshape the acquisition landscape by privileging manufacturers with verified supply chain infrastructure already in place. Long-term viability centers on fermentation technologist talent pipelines and bioprocessing asset bases rather than conventional oil-blending capacity. The signal to watch is bakery chain procurement mandate conversion rates as commercial end-users shift specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Oil Supply | Satellite-monitored sourcing secures EU Green Deal compliance and preferential German retail placement. |
| Fermentation Capability Buildout | Precision fermentation-derived cultures replicate dairy mouthfeel without hydrogenation for premium tier positioning. |
| Direct-to-Food-Service Distribution Expansion | Temperature-controlled logistics dedicated to plant-based fats shortens lead times for California bakery chains. |
| Clean-Label Stabilizer Substitution R&D | Removing modified starches while maintaining shelf stability demands extended timelines but validates retail access. |
| Avocado Oil Source Expansion | Mexico and California production zones enable premium saturated-fat-profile positioning in North American retail. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with plant-based butter manufacturers, bakery chain procurement directors, and specialty food distributors, combined with secondary validation from EU Green Deal regulatory filings, FDA guidance documents, and customs trade records. Bottom-up triangulation across oilseed import volumes and top-down cross-check against retail audit data anchored the market sizing framework.
Across the analysis window, the forecasting framework modeled segmentation by product type, source oil, packaging format, and distribution channel, with CAGRs derived from elasticity analysis of bakery chain procurement conversion rates and food service penetration trajectories. Fermentation technology adoption curves and sustainability certification uptake patterns served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt FDA labeling reversals would require recalibration. Forecasts reflect assumptions around oil price volatility corridors and bakery R&D department trial timelines. Revision becomes warranted when coconut oil supply disruption crosses thresholds affecting margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Plant-Based Waters Market