
 Plant-Based Energy Drink Market | 2026-2036
Plant-Based Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Energy Drink Market Analytics
Specialized botanists and ethnobotanists with expertise in Amazonian and Andean stimulant plants is reorganizing how quickly brands can scale novel ingredient supply chains. Runa Energy Drink leverages direct partnerships with indigenous farming cooperatives in Ecuador to secure guayusa leaf volumes. Proper Wild, Inc. anchors its positioning through high-dose L-theanine formulations that differentiate from synthetic caffeine competitors. Tenzing Natural Energy Ltd sustains British market presence through carbon-neutral shipping commitments that resonate with urban professional buyers.
Plant-based energy drinks are non-alcoholic beverages formulated from botanical stimulants such as yerba mate, guayusa, green tea, or adaptogenic herbs, typically containing 80-150mg of caffeine per serving from natural sources rather than synthetic anhydrous caffeine, and serving the functional purpose of mental alertness and physical endurance without petrochemical-derived additives. Ready-to-Drink formats dominate shelf space and refrigerated logistics networks, while Powdered variants capture gym bag and travel use cases with lower shipping weights. Herbal Extracts as an ingredient source command premium positioning due to traceable sourcing stories, whereas Fruit Juices function as the accessible entry point for consumers transitioning from conventional sports drinks.
FDA GRAS self-affirmation requirements for novel botanical ingredients create compliance costs that favor established players with legal teams over new entrants. EFSA health claim regulations in Europe restrict how brands communicate energy and focus benefits, pushing marketing toward lifestyle imagery rather than physiological promises. USDA organic certification and Non-GMO Project verification have become baseline table stakes for health-conscious distribution channels. Stakeholders must monitor how evolving caffeine disclosure rules across multiple jurisdictions reshape formulation strategies and label architectures.
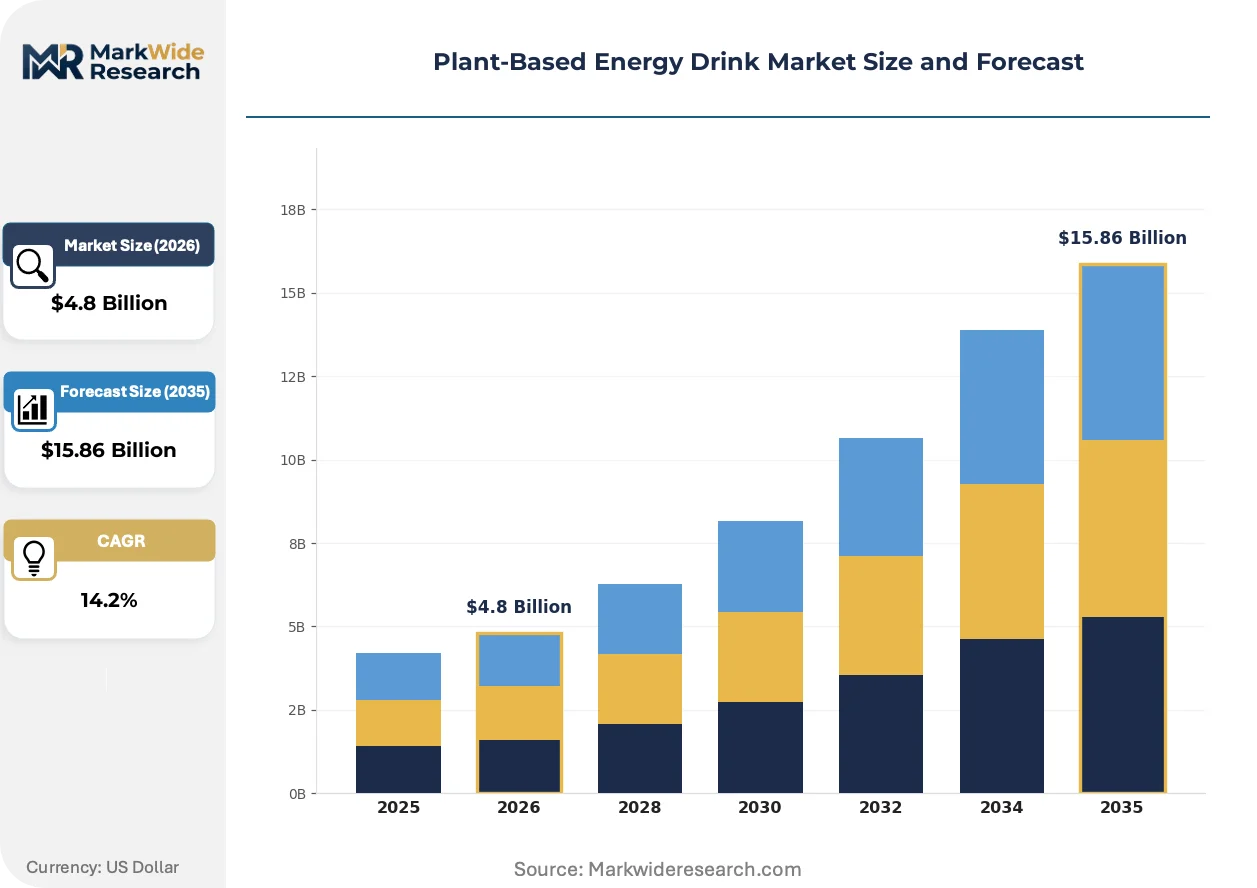
Market Dynamics
The EU Green Deal's farm-to-fork sustainability labeling requirements are forcing ingredient sourcing transparency that reshapes procurement economics and competitive positioning for brands serving European distribution channels.
Growth Catalysts
- Fitness Center Procurement:CrossFit gyms and boutique training studios have institutionalized yerba mate and guayusa-based formulations as standard cooler inventory, creating predictable volume contracts that stabilize upstream farming cooperatives in Ecuador and Argentina.
- REACH-Compliant Extraction:European solvent regulations for botanical processing have accelerated supercritical CO2 extraction adoption, yielding cleaner caffeine profiles that satisfy EFSA contaminant thresholds without synthetic purification steps.
- USDA Organic Certification:Health food retail chains in Germany and the United States now require organic verification as a baseline listing condition, expanding certified acreage across Paraguayan yerba mate plantations.
Market Restraints
- Amazonian Supply Concentration:Guayusa leaf production clusters in Ecuador's Napo Province creates monsoon-dependent harvest risk that limits formulation flexibility during drought cycles.
- FDA GRAS Compliance Burden:Novel botanical stimulants require self-affirmation documentation that consumes legal resources disproportionately, disadvantaging new entrants against established players with in-house regulatory teams.
- Synthetic Caffeine Substitution:Anhydrous caffeine from petrochemical sources maintains cost advantages in mass-market channels, pressuring premium positioning for plant-derived alternatives.
Strategic Opportunities
- Adaptogenic Herb Convergence:Formulators combining yerba mate with ashwagandha or rhodiola extracts target stress-resilience positioning that synthetic caffeine cannot replicate, opening wellness channel distribution beyond traditional energy drink placements.
- Carbon-Neutral Shipping Mandates:British urban professional buyers demonstrate willingness to absorb freight premiums for climate-neutral logistics, creating margin capture potential for brands with verified supply chain decarbonization.
- Powdered Format Expansion:Gym bag and travel use cases favor lower-weight shipping economics that bypass refrigerated logistics constraints, enabling direct-to-consumer penetration in markets lacking cold-chain infrastructure.
Industry Challenges
- Ethnobotanical Talent Scarcity:Brands scaling novel Amazonian ingredients require specialized botanists with indigenous partnership experience, a skill set concentrated among academic researchers rather than commercial supply chain professionals.
- Multi-Jurisdiction Caffeine Disclosure:Evolving label architecture requirements across FDA, EFSA, and national health ministries force simultaneous compliance redesigns that fragment packaging runs and inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Energy Drink Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Concentrated, Powdered, Carbonated Ingredient Source: Herbal Extracts, Fruit Juices, Vegetable Extracts, Grains Target Audience: Fitness Enthusiasts, Health-Conscious Consumers, Busy Professionals, Students Distribution Channel: Online Retail, Supermarkets, Health Stores, Vending Machines |
| Companies Covered | Runa Energy Drink, Proper Wild, Inc., Tenzing Natural Energy Ltd, Drinkoca, Teariot, Guru Energy, Guayaki Yerba Mate, Fire Bird Energy, Yerbaé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Energy Drink Market Evolving Landscape
Formulation science and regulatory disclosure requirements are converging to reshape how plant-derived stimulants achieve shelf stability and consumer trust in functional beverage channels.
Supercritical CO2 extraction technology for caffeine isolation from green tea and yerba mate is displacing traditional solvent-based methods that carried petrochemical residue risks. Premium brands targeting EFSA-compliant European distribution have adopted this capital-intensive process within three years of regulatory guidance publication. The technology compresses acceptable supplier lists to equipment owners with certified organic feedstock contracts.
EFSA health claim regulations now restrict direct physiological benefit communication for energy and focus positioning, forcing marketing execution toward lifestyle imagery and ingredient provenance storytelling. Brands must navigate claim substantiation databases that exclude most traditional stimulant effects. German and Austrian health food retailers have responded by reorganizing shelf sets around certification badges rather than functional promise headers.
Gym-based procurement committees have consolidated purchasing authority previously dispersed across individual location managers, compressing vendor negotiation cycles and demanding outcome-based performance guarantees for cooler placement. This concentration favors suppliers with national distribution infrastructure and refrigerated fleet coverage. The pattern is most visible in metropolitan clusters across England and the German Ruhr region where fitness chain consolidation has accelerated since 2023.
Plant-Based Energy Drink Market Segmentation
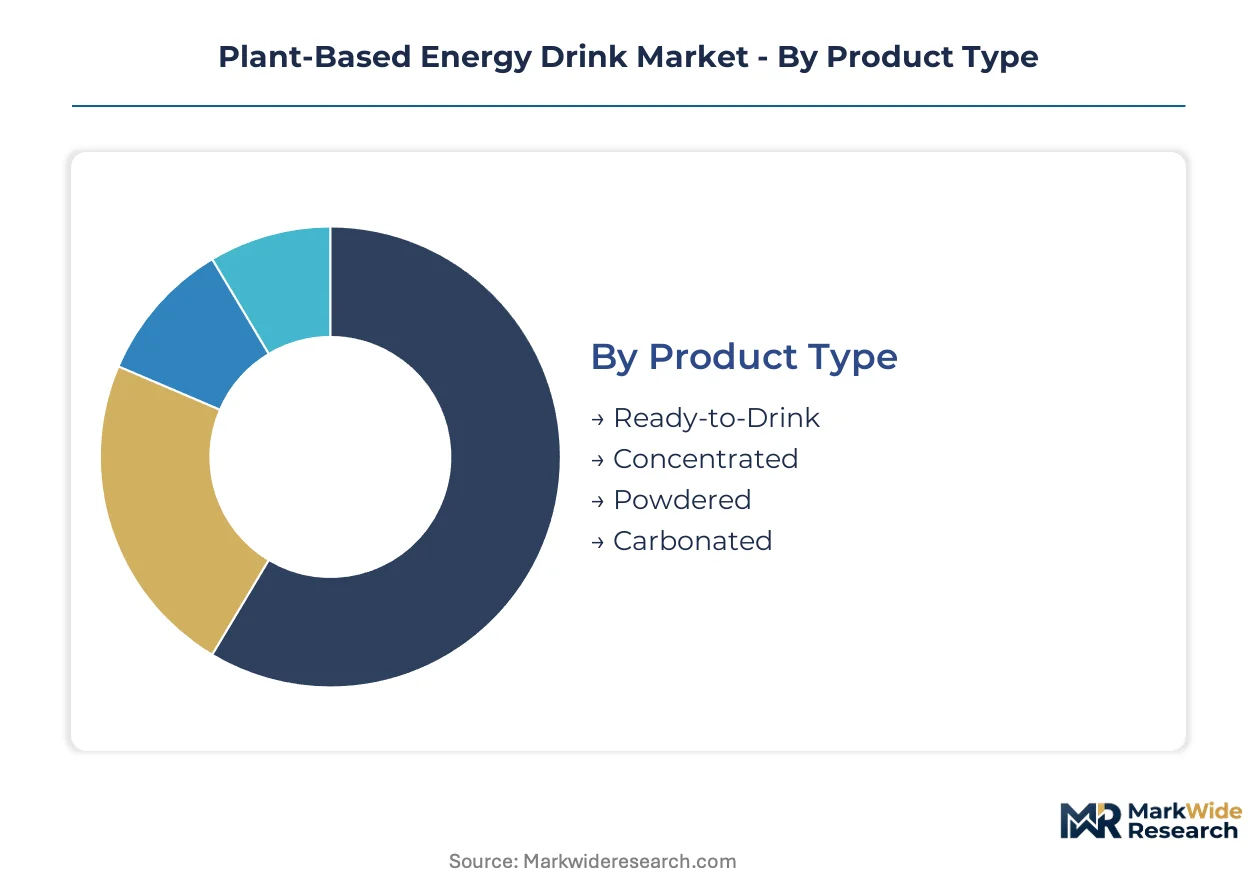
Plant-based energy drink segmentation reveals how formulation choices and channel strategies align with divergent regulatory requirements across FDA, EFSA, and national health ministries. Each dimension carries distinct compliance burdens that reshape competitive economics and market entry feasibility.
Product Type:
FDA GRAS self-affirmation and EFSA novel food regulations create divergent compliance pathways that favor formats with established safety dossiers over experimental delivery systems.
- Ready-to-Drink:Pre-formulated beverages in aluminum cans or glass bottles requiring refrigerated logistics networks dominate German health food retail chains with dedicated cooler sections. Fitness centers and CrossFit gyms in England and the German Ruhr region have consolidated procurement authority around this format, demanding national distribution infrastructure and refrigerated fleet coverage.
- Powdered:Dehydrated formulations in single-serve sachets or bulk canisters bypass cold-chain constraints and reduce shipping weights for gym bag and travel use cases. Direct-to-consumer penetration accelerates in markets lacking refrigerated infrastructure, though moisture barrier specifications trigger additional stability testing under FDA guidelines.
- Concentrated:Dilution-required formulations offer formulation flexibility for on-premise mixing in boutique training studios.
- Carbonated:Pressurized delivery systems compete with conventional energy drinks in mass-market vending placements.
Established volume favors Ready-to-Drink; emerging adoption favors Powdered.
Ingredient Source:
USDA organic certification and EU Green Deal farm-to-fork traceability requirements concentrate sourcing economics toward supply chains with verified cultivation documentation.
- Herbal Extracts:Supercritical CO2 extraction from yerba mate and guayusa leaves yields contaminant-free caffeine profiles that satisfy EFSA thresholds. Runa Energy Drink leverages direct partnerships with indigenous farming cooperatives in Ecuador's Napo Province to secure traceable volumes, though monsoon-dependent harvest risk limits formulation flexibility during drought cycles.
- Fruit Juices:Citrus and berry bases function as accessible entry points for consumers transitioning from conventional sports drinks, requiring less specialized botanical expertise and carrying lower novel ingredient compliance burdens. German health food retailers stock these formulations in standard ambient aisles rather than dedicated functional beverage sections.
- Vegetable Extracts:Beetroot and green vegetable derivatives target nitric oxide positioning for endurance applications.
- Grains:Malted barley and quinoa bases appeal to consumers seeking sustained carbohydrate release alongside caffeine stimulation.
Certification premiums concentrate in Herbal Extracts; price-accessible volume clusters in Fruit Juices.
Target Audience:
Channel placement authority and purchasing consolidation patterns determine which consumer segments command formulation investment and marketing resource allocation.
- Fitness Enthusiasts:Gym-based procurement committees have institutionalized yerba mate and guayusa-based formulations as standard cooler inventory, creating predictable volume contracts that stabilize upstream farming cooperatives in Ecuador and Argentina. These buyers absorb premium positioning for adaptogenic herb combinations targeting stress-resilience.
- Health-Conscious Consumers:Organic verification and Non-GMO Project certification serve as baseline table stakes for this segment, with German health food retail chains reorganizing shelf sets around certification badges rather than functional promise headers due to EFSA health claim restrictions.
- Busy Professionals:British urban professional buyers demonstrate willingness to absorb freight premiums for carbon-neutral logistics, creating margin capture potential for brands with verified supply chain decarbonization.
- Students:Price-sensitive demand concentrates in powdered formats and private-label supermarket offerings with lower per-serving costs.
Volume concentration favors Fitness Enthusiasts; margin expansion potential sits with Busy Professionals.
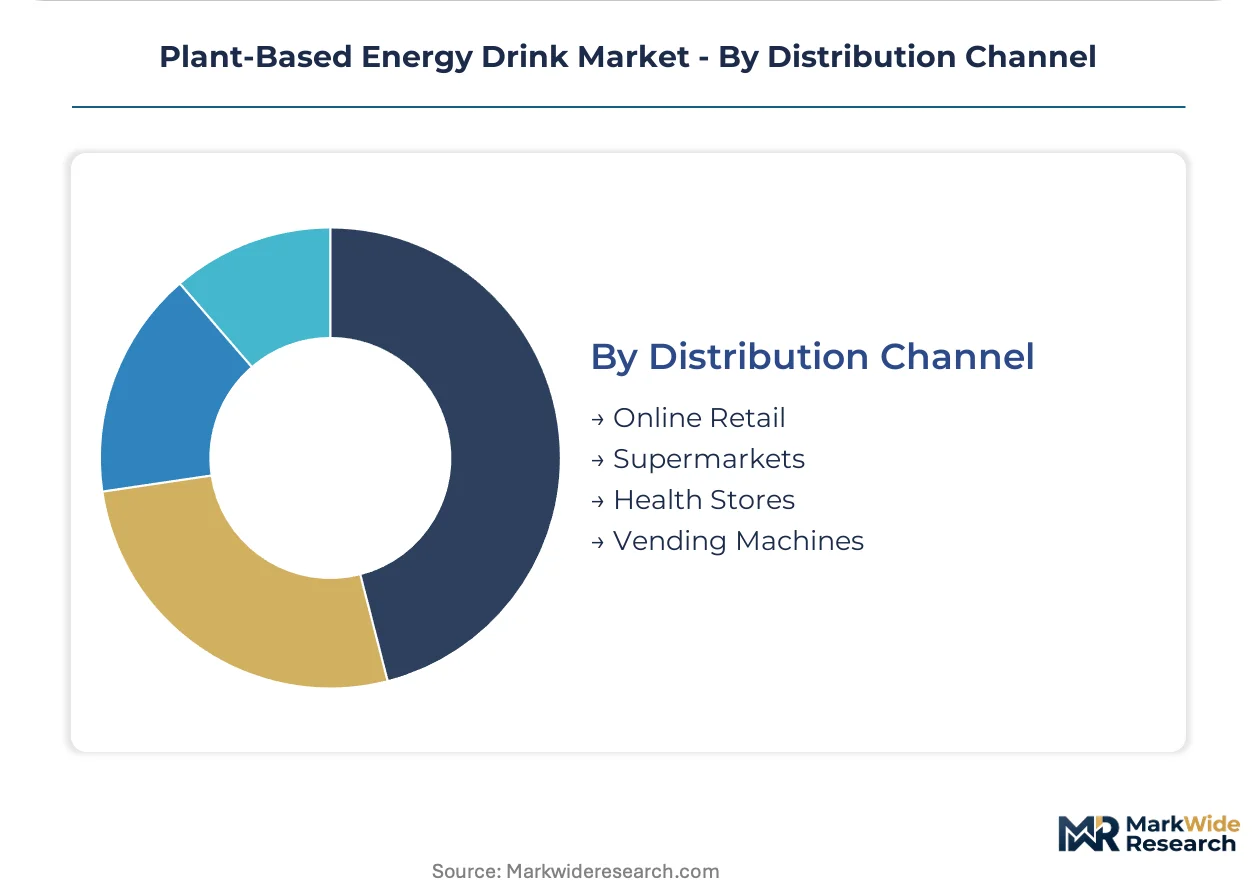
Distribution Channel:
Cold-chain infrastructure availability and regulatory disclosure requirements fragment channel economics across jurisdictions with divergent caffeine labeling mandates.
- Online Retail:Direct-to-consumer penetration bypasses refrigerated logistics constraints for powdered variants while enabling subscription models that stabilize demand forecasting. Multi-jurisdiction caffeine disclosure rules force simultaneous compliance redesigns that fragment packaging runs and inflate inventory carrying costs for cross-border shipments.
- Supermarkets:Mass-market placement requires competing with synthetic anhydrous caffeine products on price, pressuring premium positioning for plant-derived alternatives despite USDA organic verification.
- Health Stores:Dedicated functional beverage sections in German and Austrian retailers favor certified organic ingredient sourcing with traceable provenance storytelling.
- Vending Machines:Ambient temperature storage limits formulation options to shelf-stable concentrates and carbonated variants.
Margin capture favors Health Stores; volume scale favors Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German health food retail chains stock dedicated plant-based energy cooler sections, while British urban professionals absorb freight premiums for carbon-neutral logistics, and Ecuadorian farming cooperatives anchor raw material flows. This consumption-mix differential separates procurement-heavy European markets from supply-concentrated South American origins.
Germany
Fitness centers in the Ruhr region and health-conscious consumers in Berlin drive volume through dedicated cooler sections in organic retail chains. EU Green Deal farm-to-fork sustainability labeling requirements force certified organic ingredient sourcing as baseline table stakes. Bavarian distribution hubs manage refrigerated logistics networks serving Austrian and Swiss cross-border demand.
United Kingdom
Urban professionals in London demonstrate willingness to pay climate-neutral freight premiums, creating margin capture potential for verified supply chain decarbonization. EFSA health claim restrictions push marketing toward lifestyle imagery rather than physiological promises. CrossFit gym consolidation across England compresses vendor negotiation cycles and demands national refrigerated fleet coverage.
Ecuador
Indigenous farming cooperatives in Napo Province supply guayusa leaf volumes through direct partnership structures with international brands. Monsoon-dependent harvest risk limits formulation flexibility during drought cycles. Quito-based processing facilities handle initial leaf drying before export to North American and European formulation plants.
Argentina
Yerba mate plantations in Misiones Province expand certified organic acreage to meet USDA verification requirements for German and US export markets. Predictable volume contracts from gym-based procurement committees stabilize upstream farming economics. Buenos Aires logistics clusters coordinate Atlantic shipping routes to European ports.
United States
FDA GRAS self-affirmation requirements for novel botanical ingredients create compliance costs favoring established players with legal teams over new entrants. CrossFit gyms and boutique training studios in metropolitan areas institutionalize yerba mate and guayusa-based formulations as standard cooler inventory. California health food retail chains require Non-GMO Project verification as baseline listing conditions.
Plant-Based Energy Drink Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding indigenous partnership networks and the latter differentiating through formulation science. The market structure concentrates around players with certified organic supply chains and supercritical CO2 extraction capabilities. Three archetypes dominate: vertically integrated Amazonian sourcing specialists, adaptogenic formulation innovators, and carbon-neutral logistics operators. Competitive moves center on direct farming cooperative partnerships and refrigerated distribution infrastructure expansion.
Within the Amazonian sourcing tier, Runa Energy Drink exemplifies direct indigenous cooperative engagement, while Guayaki Yerba Mate anchors Argentine supply chain depth. Proper Wild, Inc. occupies a position among adaptogenic formulation specialists targeting stress-resilience positioning that synthetic caffeine cannot replicate. These three represent distinct competitive vectors: traceable provenance storytelling, South American plantation scale, and high-dose L-theanine differentiation.
| Leading Market Players |
|---|
| Runa Energy Drink |
| Proper Wild, Inc. |
| Tenzing Natural Energy Ltd |
| Drinkoca |
| Teariot |
| Guru Energy |
| Guayaki Yerba Mate |
| Fire Bird Energy |
| Yerbaé |
| Others |
Value Network & Pricing Analysis
Ninety-day leaf curing cycles in Ecuador's Napo Province compress formulation flexibility during monsoon disruptions, concentrating pricing power with indigenous cooperatives that hold direct partnership contracts with premium brands. This inventory constraint feeds into procurement economics where certified organic yerba mate commands substantial premiums over conventional grades, and carbon-neutral logistics commitments in British urban markets absorb freight cost differentials that mass channels reject.
Pricing Analysis
Long-term offtake agreements with Ecuadorian and Argentine farming cooperatives dominate procurement structures, locking volume commitments that stabilize upstream economics against spot-market volatility. Price differentiation rests on USDA organic certification and supercritical CO2 extraction capabilities, with certified herbal extracts commanding substantial premiums over fruit-juice-based entry formulations. Cost compression in standard-tier products is intensifying because synthetic anhydrous caffeine maintains cost advantages in supermarket channels. Students and price-sensitive segments drive volume through powdered private-label offerings, while fitness enthusiasts and busy professionals absorb premium positioning with minimal price elasticity.
Supply Chain Analysis
Inventory lead times stretching 60-90 days for dried guayusa leaf shipments from Quito to European formulation plants create working capital intensity that favors established players. Raw material flows concentrate in Ecuador's Napo Province and Argentina's Misiones Province, with secondary sourcing from Paraguayan yerba mate plantations. Supply chain risk centers on monsoon-dependent harvest vulnerability that limits formulation flexibility during drought cycles. Distribution runs through refrigerated logistics networks serving German health food retail chains and CrossFit gym procurement committees, with powdered variants bypassing cold-chain constraints through direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models for powdered formulations are expanding faster than ready-to-drink hardware sales, creating recurring revenue layers that improve customer lifetime value metrics. This service-attach opportunity reshapes how brands prioritize direct-to-consumer infrastructure against traditional retail placement investments.
For Market Incumbents: Secure exclusive multi-year offtake agreements with indigenous farming cooperatives in Ecuador's Napo Province to defend against new entrants lacking established partnership networks. Deepen backward integration into supercritical CO2 extraction capabilities to maintain EFSA-compliant contaminant thresholds that synthetic caffeine competitors cannot match. Channel control through refrigerated fleet expansion across England and the German Ruhr region protects placement authority as gym procurement committees consolidate vendor lists.
For New Entrants and Emerging Players: Lead with adaptogenic herb combinations targeting stress-resilience positioning that established synthetic caffeine brands cannot replicate, opening wellness channel distribution beyond traditional energy drink placements. White-space opportunity concentrates in carbon-neutral shipping mandates for British urban professionals willing to absorb freight premiums. Direct-to-consumer penetration through powdered subscription models bypasses refrigerated logistics barriers in markets lacking cold-chain infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because USDA organic verification and Non-GMO Project validation have become baseline table stakes that concentrate economics toward integrated supply chain operators. Acquisition targets should display direct indigenous cooperative partnerships and supercritical CO2 extraction assets. The signal to watch is evolving caffeine disclosure rules across FDA, EFSA, and national health ministries that will fragment packaging runs and inflate compliance costs for sub-scale players.
| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Cooperative Partnership | Direct agreements with Ecuadorian farming communities secure traceable guayusa volumes that satisfy EU Green Deal farm-to-fork requirements. |
| Supercritical CO2 Extraction Investment | Capital-intensive processing technology yields contaminant-free caffeine profiles compliant with EFSA thresholds and REACH solvent regulations. |
| Carbon-Neutral Logistics Certification | Verified supply chain decarbonization captures margin premiums from British urban professionals demanding climate-neutral freight options. |
| Powdered Format Expansion | Lower-weight shipping economics bypass refrigerated infrastructure constraints and enable subscription-based direct-to-consumer penetration. |
| Adaptogenic Formulation Development | Combinations of yerba mate with ashwagandha or rhodiola target stress-resilience positioning inaccessible to synthetic caffeine competitors. |
Research Methodology
Operator-level perspectives from brand formulation directors, indigenous cooperative leaders, health food retail category buyers, CrossFit gym procurement managers, and refrigerated logistics operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with supply chain stakeholders across Ecuador, Argentina, Germany, and the United Kingdom with secondary validation from FDA GRAS notification databases, EFSA novel food guidance documents, USDA organic certification records, and EU Green Deal farm-to-fork traceability frameworks. Bottom-up volume modeling from ingredient sourcing flows and top-down demand assessment from channel placement data were triangulated to ensure consistency.
Sensitivity analysis across certification adoption rates, monsoon harvest variability, and refrigerated logistics cost inflation tested forecast robustness throughout the projection horizon. Segmentation dimensions modeled include product format, ingredient source, target audience archetype, and distribution channel, with additional granularity on supercritical CO2 extraction adoption versus conventional solvent processing. CAGRs were derived from fitted growth curves applied to verified baseline volumes, with cross-checks against gym procurement committee expansion patterns and health food retail cooler section growth.
Underlying assumptions cover sustained EU Green Deal enforcement, stable indigenous cooperative partnership structures, and gradual caffeine disclosure rule harmonization, with deviation risk concentrated in drought-induced harvest shortfalls and synthetic caffeine price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Bubble Food and Beverages Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Whole Grain Drinks Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Root Beer Market
Beverages
Pineapple Juice Market
Beverages
Nitro-Infused Cola Market
Beverages
Beverage Premix Market
Beverages
Smoothies Market
Beverages
Carbonated Beverages Market
Beverages
India Bottled Water Market
Beverages
Hot Beverages Market
Beverages
Global Soda Maker Market
Beverages
Packaged Milkshake Market