
 Plant-Based Waters Market | 2026-2036
Plant-Based Waters Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Waters Market Analysis
Fitness centers and boutique wellness studios is unwinding the historical dominance of casual retail consumers in plant-based water procurement. Harmless Harvest leverages its raw coconut water specialization to command premium shelf positioning in natural grocery channels. PepsiCo Inc. competes through mass-market distribution density, extending its beverage portfolio into the functional hydration space. Danone anchors European demand through its existing plant-based nutrition infrastructure, sustaining R&D investment in extraction and preservation technologies.
Plant-based waters are aqueous extracts derived from vascular plant tissues—coconut endosperm liquid, maple xylem sap, birch cambium fluid, or aloe mesophyll gel—typically processed through cold sterilization or high-pressure processing to retain bioactive compounds and mineral profiles without thermal degradation. Their primary commercial purpose is to deliver functional hydration with inherent electrolyte content and minimal ingredient complexity, displacing formulated sports drinks and flavored waters in wellness-oriented consumption occasions. Coconut Water dominates volume due to established supply chains in Southeast Asian producing regions, while Maple Water captures accelerating North American demand as a lower-sugar seasonal alternative with distinct terroir marketing potential. Aloe Vera Juice occupies a narrower but higher-margin position in digestive health applications, with distribution concentrated through health food stores rather than mainstream supermarkets.
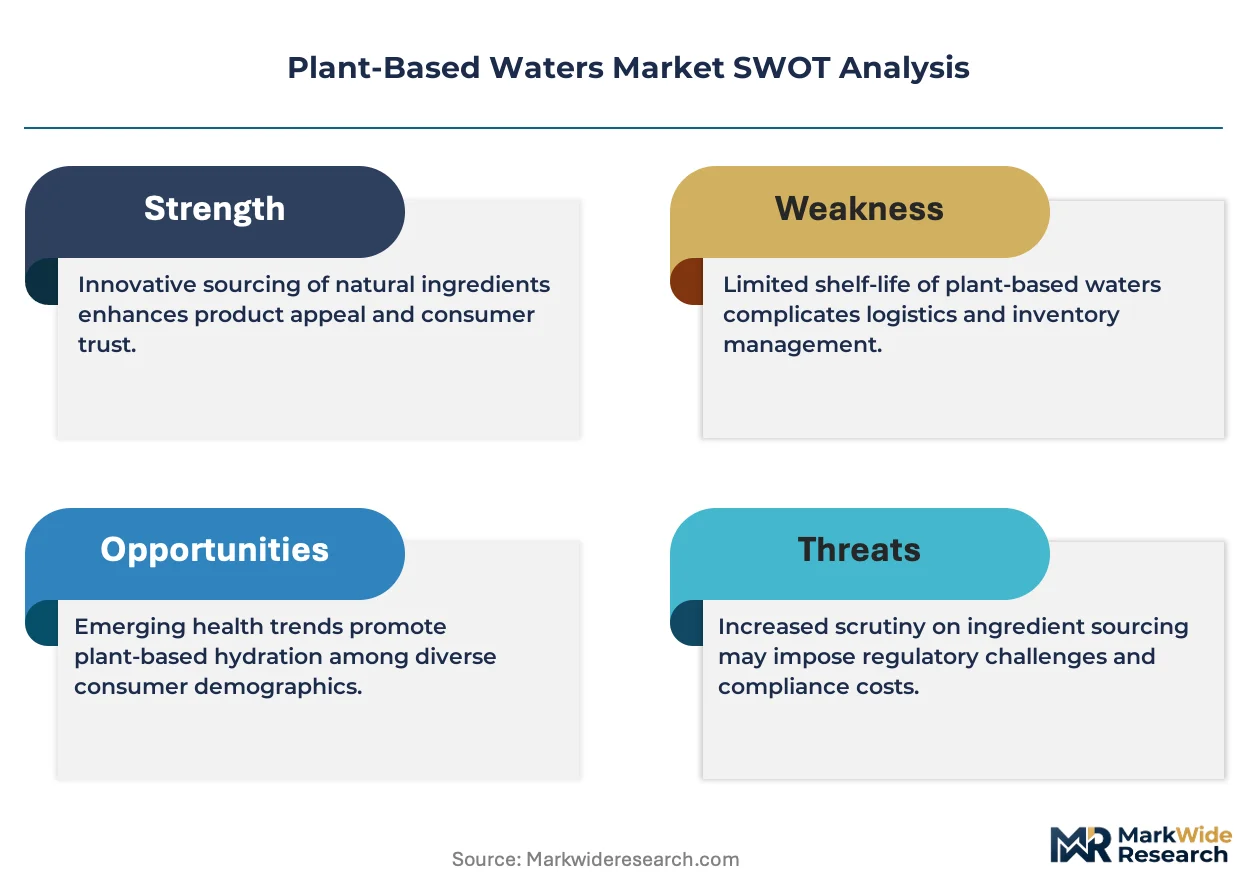
FDA oversight of health claims labeling and USDA organic certification requirements shape product positioning and margin structures for US-market entrants, while EFSA novel food assessments govern maple and birch water commercialization pathways in European jurisdictions. The EU Green Deal's packaging sustainability mandates are accelerating transitions from conventional bottles to Tetra Packs and aluminum cans across export-oriented producers. Stakeholders must monitor evolving clean-label enforcement intensity and decide whether to prioritize single-origin supply narratives or blended formulation strategies as regulatory scrutiny of functional beverage claims intensifies.
Market Dynamics
Fitness centers and boutique wellness studios are displacing casual retail consumers as the dominant procurement channel for plant-based waters, redirecting formulation priorities toward post-workout electrolyte density and away from flavor-first positioning.
Growth Catalysts
- Clean-label enforcement:The EU Green Deal's packaging sustainability mandates are accelerating transitions from conventional bottles to Tetra Packs and aluminum cans across export-oriented producers, favoring single-ingredient plant waters with minimal additive disclosure.
- Post-workout hydration protocols:Fitness centers and boutique wellness studios are unwinding historical retail dominance as synthetic sports drinks lose favor among performance-oriented consumers seeking vascular plant tissue extracts.
- Cold sterilization adoption:High-pressure processing technology is retaining bioactive compounds and mineral profiles without thermal degradation, enabling functional hydration claims previously restricted to formulated beverages.
Market Restraints
- Seasonal supply volatility:Maple xylem sap and birch cambium fluid harvest windows concentrate production in narrow climatic windows, creating inventory management complexity for North American processors.
- Novel food assessment timelines:EFSA novel food assessments govern maple and birch water commercialization pathways in European jurisdictions, extending market entry timelines by 18-24 months versus established coconut water categories.
- Sugar content perception:Coconut endosperm liquid faces substitution pressure from lower-sugar alternatives as wellness-oriented consumers scrutinize inherent carbohydrate levels in vascular plant extracts.
Strategic Opportunities
- Digestive health verticalization:Aloe mesophyll gel occupies a narrower but higher-margin position in digestive health applications, with distribution concentrated through health food stores rather than mainstream supermarkets.
- Terroir marketing development:Maple Water captures accelerating North American demand as a lower-sugar seasonal alternative with distinct regional sourcing narratives that command premium positioning.
- USDA organic certification leverage:USDA organic certification requirements shape product positioning and margin structures for US-market entrants, creating defensible shelf space in natural grocery channels.
Industry Challenges
- Preservation technology talent scarcity:Extraction and preservation technology R&D investment requires specialized expertise in cold sterilization methods that outpaces current food science program output.
- Multi-jurisdiction claim harmonization:FDA oversight of health claims labeling and EFSA novel food assessments create divergent compliance pathways that fragment global product portfolios.
- Supply chain reconfiguration costs:Transitioning from Southeast Asian coconut water supply chains to North American maple and birch sourcing requires capital-intensive processing infrastructure relocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Waters Market |
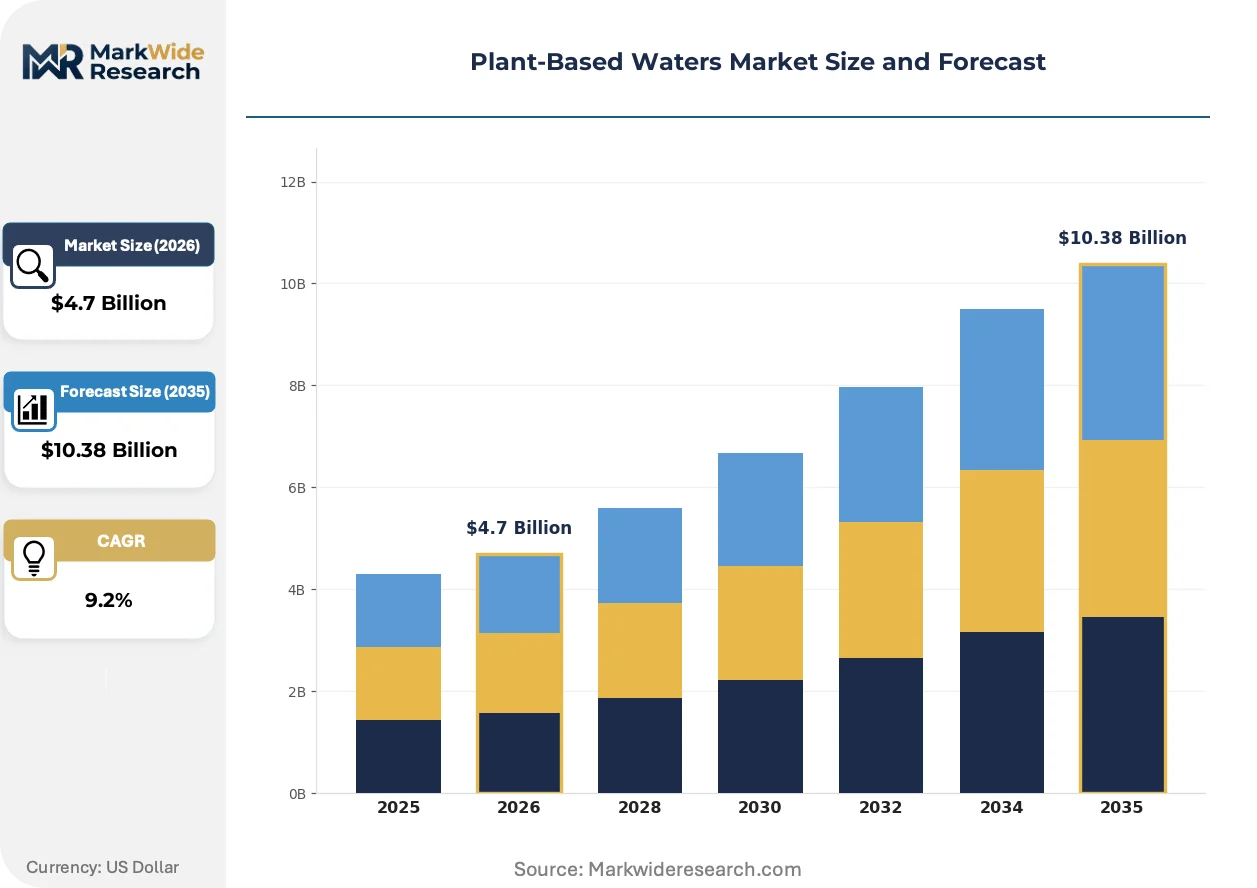
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.38 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Water, Maple Water, Birch Water, Aloe Vera Juice End User: Health Enthusiasts, Fitness Centers, Restaurants, Retail Outlets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Oviva Maple Water Company, World Waters LLC, The Coca-Cola Company, DRINKmaple, Harmless Harvest, PepsiCo Inc., Caliwater LLC, Danone, All Market Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Waters Market Emerging Trajectories
Functional beverage formulation is decomposing into ingredient-specific extraction protocols that preserve bioactive integrity, while regulatory pressure on additive disclosure accelerates single-component product development across wellness-oriented channels.
High-pressure processing is decomposing thermal pasteurization's historical dominance in plant water sterilization. Fitness centers and boutique wellness studios are adopting cold-sterilized coconut water and maple sap at accelerating rates for post-workout protocols. This technology is decomposing the cost advantage of mass-market formulated sports drinks by enabling premium positioning for minimally processed alternatives.
REACH chemical safety assessments and EU Green Deal packaging mandates are tightening additive disclosure and material sustainability requirements for plant water imports into European jurisdictions. Producers face reformulation pressure to eliminate synthetic preservatives and transition to aluminum or paper-based containers. Maple and birch water categories are most affected, with commercialization timelines extending as EFSA novel food assessments proceed.
Buyer concentration in coastal metropolitan clusters with established health-food retail infrastructure is compressing traditional grocery channel intermediation. Direct procurement relationships between wellness studios and regional distributors are replacing conventional wholesale arrangements. This pattern is most visible in United States demand concentration, where natural grocery chains anchor shelf access for single-origin supply narratives.
Plant-Based Waters Market Segmentation
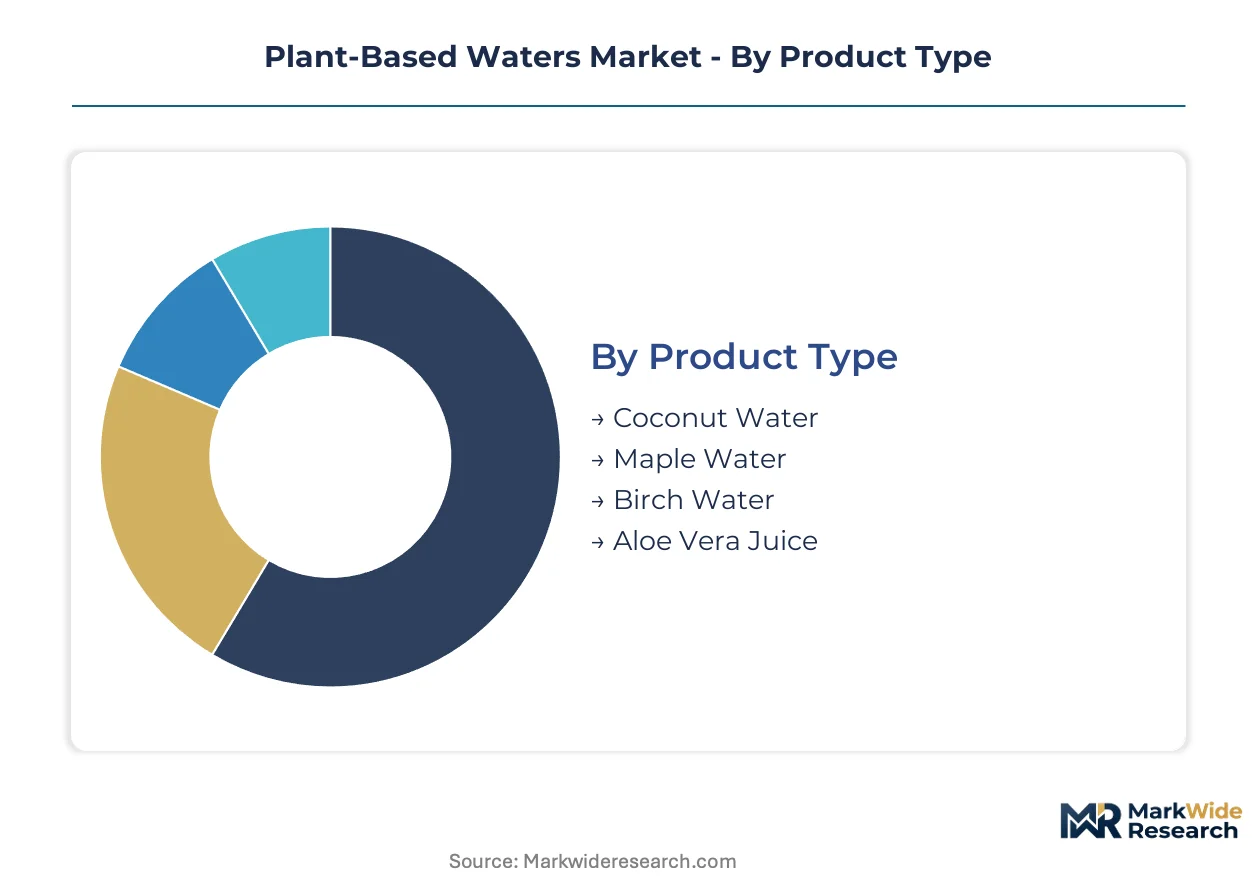
Plant-based waters fragment along extraction source, consumption occasion, and channel access. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Coconut water and maple water anchor domestic North American consumption, while birch water and aloe vera juice depend disproportionately on export authorization timelines.
- Coconut Water:Aqueous extract from coconut endosperm liquid, standardized through cold sterilization protocols. Demand concentrates in United States coastal metropolitan clusters where post-workout hydration protocols favor established electrolyte profiles over synthetic alternatives.
- Maple Water:Raw xylem sap harvested during narrow climatic windows in Quebec and Vermont, processed through high-pressure methods. Canadian and Northeastern US processors face seasonal inventory complexity as wellness studios adopt lower-sugar alternatives.
- Birch Water:Cambium fluid with shorter harvest windows than maple, requiring specialized preservation expertise. EFSA novel food assessments extend European commercialization timelines.
- Aloe Vera Juice:Mesophyll gel extract positioned for digestive health applications. Distribution runs through health food stores rather than mainstream supermarkets.
Coconut water commands the established base. The steepest expansion trajectory runs through maple water.
End User:
Cost tier differentiation separates premium wellness studio procurement from mass retail consumption.
- Health Enthusiasts:Individual consumers prioritizing clean-label credentials and single-origin supply narratives. United States demand concentrates in natural grocery channels.
- Fitness Centers:Boutique wellness studios displacing casual retail as the dominant procurement channel. Post-workout protocols drive electrolyte-density formulation priorities.
- Restaurants:Foodservice integration remains limited to premium positioning in health-focused dining concepts.
- Retail Outlets:Conventional grocery intermediation compresses as direct distributor relationships expand.
Fitness centers are gaining share fastest. Retail outlet dominance is eroding.
Distribution Channel:
Volume concentration favors high-throughput retail formats, while margin capture concentrates in specialized access points.
- Online Retail:Direct-to-consumer subscription models for single-origin coconut and maple waters. Subscription retention depends on cold-chain reliability.
- Supermarkets:Mass-market placement dominated by PepsiCo portfolio extensions. Shelf access requires USDA organic certification for natural channel positioning.
- Health Food Stores:Premium positioning for aloe vera juice and raw coconut water. Harmless Harvest anchors shelf space through raw specialization.
- Specialty Stores:Regional terroir marketing for maple water with distinct Quebec or Vermont sourcing narratives.
Health food stores command the established base. Online retail climbs the fastest.
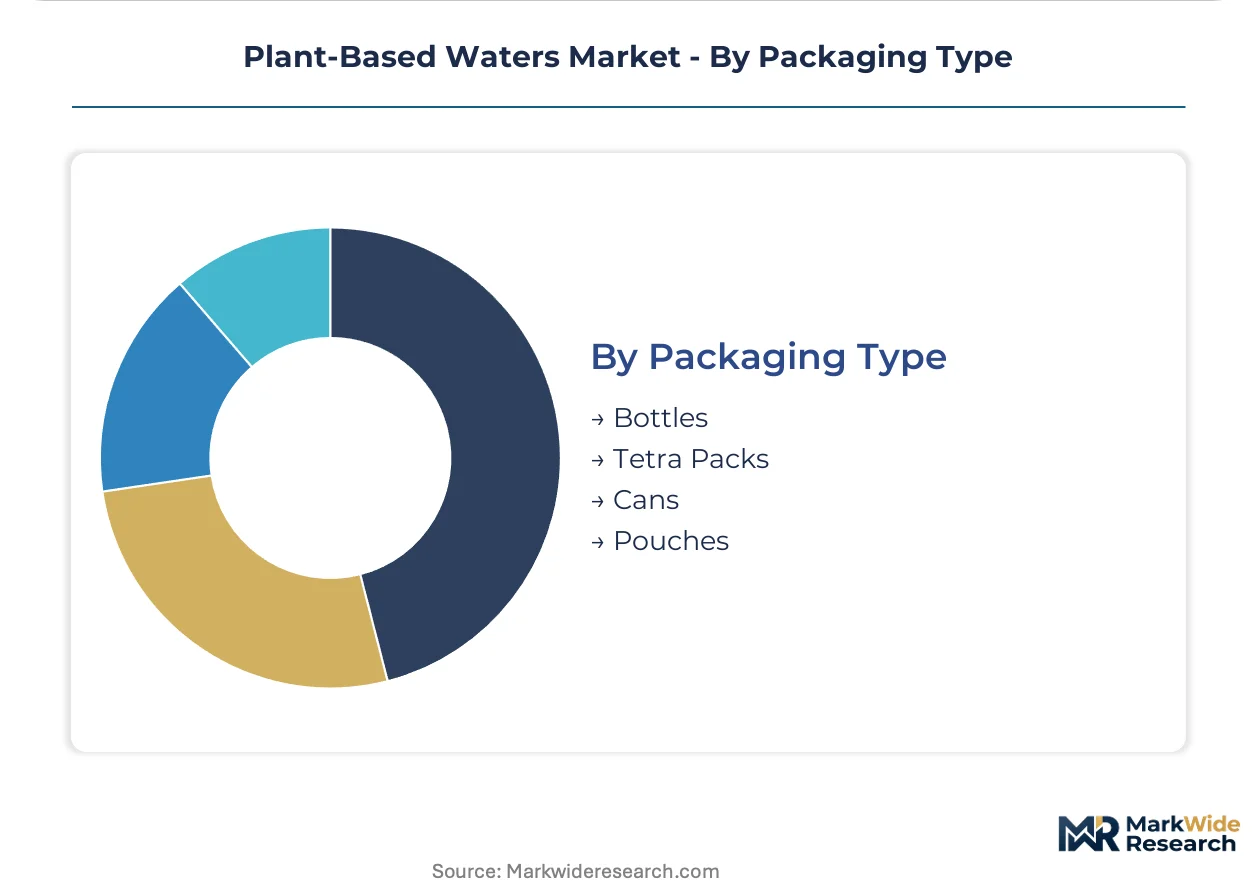
Packaging Type:
EU Green Deal mandates are forcing material transitions that favor aluminum and paper-based formats over conventional plastic.
- Bottles:Conventional PET and glass formats face sustainability pressure. Export-oriented producers accelerate transitions under packaging mandates.
- Tetra Packs:Paper-based cartons align with EU sustainability requirements. Cold sterilization compatibility supports premium positioning.
- Cans:Aluminum formats gain share in fitness center channels for post-workout portability. Recyclability supports clean-label marketing.
- Pouches:Flexible formats for on-the-go consumption. Limited penetration outside coconut water category.
Bottles retain the volume base. Cans are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian coconut water exports flow primarily to United States coastal metropolitan clusters, where cold-sterilized processing infrastructure supports premium positioning in natural grocery channels.
United States
FDA oversight of health claims labeling and USDA organic certification requirements shape product positioning for US-market entrants. Demand concentrates in California and New York metropolitan clusters where fitness centers and boutique wellness studios displace casual retail procurement. Post-workout hydration protocols favor established electrolyte profiles over synthetic alternatives.
Canada
Maple xylem sap harvest windows in Quebec and Vermont supply chains create seasonal inventory complexity for North American processors. Health Canada regulations govern novel food assessments for emerging plant water categories. Toronto and Vancouver anchor distribution infrastructure for domestic consumption and re-export to European jurisdictions.
Germany
EFSA novel food assessments extend commercialization timelines for maple and birch water categories entering European markets. EU Green Deal packaging sustainability mandates accelerate transitions from conventional bottles to Tetra Packs and aluminum cans. Berlin and Hamburg concentrate health-food retail infrastructure for clean-label beverage distribution.
France
ANSM and DGCCRF enforcement of additive disclosure requirements favors single-ingredient plant waters with minimal processing. Paris and Lyon metropolitan clusters drive demand concentration for premium-positioned coconut and aloe vera products. Danone anchors European demand through existing plant-based nutrition infrastructure.
Thailand
Cold sterilization adoption in coconut endosperm liquid processing retains bioactive compounds for export-oriented producers. National food safety standards align with FDA and EFSA requirements for international market access. Bangkok and Surat Thani province anchor supply chain infrastructure for global coconut water distribution.
Plant-Based Waters Market Vendor Landscape
Player mix skews toward beverage conglomerates diversifying into functional hydration alongside specialized raw coconut water purveyors and regional maple sap processors. Tiered structure separates mass-market distribution density from premium single-origin positioning. Strategic archetypes include cold-sterilization specialists, terroir-marketing regionalists, and portfolio-extending beverage majors. Dominant competitive moves encompass USDA organic certification leverage and direct procurement relationships with fitness center channels.
Among North American specialists, Oviva Maple Water Company and DRINKmaple exemplify terroir-marketing regionalists capitalizing on Quebec and Vermont sourcing narratives. Harmless Harvest occupies a position within the raw coconut water archetype, commanding premium shelf positioning through minimal processing claims. PepsiCo Inc. and The Coca-Cola Company represent beverage conglomerates extending portfolio reach into functional hydration through mass-market distribution density. Danone anchors European competitive positioning through existing plant-based nutrition infrastructure and sustained R&D investment in extraction technologies.
| Leading Market Players |
|---|
| Oviva Maple Water Company |
| World Waters LLC |
| The Coca-Cola Company |
| DRINKmaple |
| Harmless Harvest |
| PepsiCo Inc. |
| Caliwater LLC |
| Danone |
| All Market Inc. |
| Others |
Supply Flow & Price Mechanics
High-pressure processing substitution for thermal pasteurization simultaneously redraws processing geography toward coastal US infrastructure clusters and compresses margin structures for mass-market thermal processors unable to upgrade. This technology migration concentrates pricing power with cold-sterilization specialists while forcing conventional bottlers into discount positioning.
Pricing Analysis
Cold-sterilization technology premiums against legacy thermal processing anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on USDA organic certification tier and single-origin supply narrative depth. Pricing pressure stems from Southeast Asian coconut water oversupply flooding mass-market channels. Fitness centers and boutique wellness studios exhibit lowest price sensitivity, prioritizing electrolyte density and bioactive retention over per-unit cost.
Supply Chain Analysis
Thailand and Indonesia anchor coconut endosperm liquid extraction for global export, while Canada and the United States concentrate maple xylem sap harvesting within narrow climatic windows. Raw material flows draw from vascular plant tissue harvests, high-pressure processing equipment, and aluminum packaging substrates. Single-source vulnerability concentrates in Southeast Asian coconut supply chains exposed to monsoon disruption. Distribution runs through direct procurement relationships between wellness studios and regional cold-chain distributors, bypassing conventional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based waters represent an early-cycle expansion story, with post-workout hydration protocol adoption among fitness centers driving penetration ahead of mass-market saturation.
For Market Incumbents: Consolidate cold-sterilization processing capacity in California and New York metropolitan clusters to defend against emerging regional maple water processors. Secure exclusive procurement contracts with boutique wellness studio chains before channel access fragments. Prioritize USDA organic certification investment to maintain shelf positioning in natural grocery channels as clean-label enforcement intensifies. For New Entrants and Emerging Players: Post-workout subscription service gaps in mid-tier fitness chains offer white-space capture opportunities underserved by mass-market beverage conglomerates. Target secondary metropolitan clusters with developing health-food retail infrastructure. Pursue direct-to-consumer subscription models with cold-chain reliability guarantees as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional maple water processors possessing Vermont and Quebec sourcing narratives but limited distribution scale. Long-term viability over the next decade rests on securing exclusive harvest rights and cold-sterilization technology licenses. Monitor EFSA novel food assessment completion timelines for birch and maple water categories as the key inflection signal for European market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Sterilization Capacity Expansion | High-pressure processing infrastructure in California and New York secures bioactive retention claims for fitness center channels. |
| Single-Origin Supply Narrative Development | Quebec and Vermont terroir marketing commands premium positioning against commoditized Southeast Asian coconut water. |
| USDA Organic Certification Investment | Clean-label enforcement in FDA-governed markets makes organic tiering essential for natural grocery shelf access. |
| Direct Wellness Studio Procurement | Bypassing conventional wholesale intermediation captures margin and locks in post-workout protocol adoption. |
| EU Green Deal Packaging Transition | Aluminum can and Tetra Pack formats satisfy EFSA-aligned sustainability mandates for European export authorization. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with beverage R&D directors, wellness studio procurement managers, cold-chain logistics specialists, and natural grocery category buyers; alongside secondary validation through FDA filing databases, USDA organic certification registries, EFSA novel food assessment records, and trade customs data. Bottom-up volume triangulation against top-down value estimates anchored forecast reliability.
Across the analysis window, projections integrate extraction source segmentation, distribution channel tiering, packaging material transitions, and end-user occasion modeling. CAGRs derive from weighted scenario analysis across clean-label enforcement intensity and cold-sterilization adoption curves. Forecast inputs incorporate seasonal harvest volatility for maple and birch categories, plus EFSA authorization timeline distributions.
Underlying assumptions cover sustained fitness center channel expansion and stable Southeast Asian coconut supply, with deviation risk concentrated in EFSA regulatory delays and monsoon-driven harvest disruptions. Recalibration cycles align with material shifts in clean-label enforcement intensity and novel food assessment completion patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Japan Plant Protein Market