
 Pizza Scissors Market | 2026-2036
Pizza Scissors Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Scissors Market Analytics
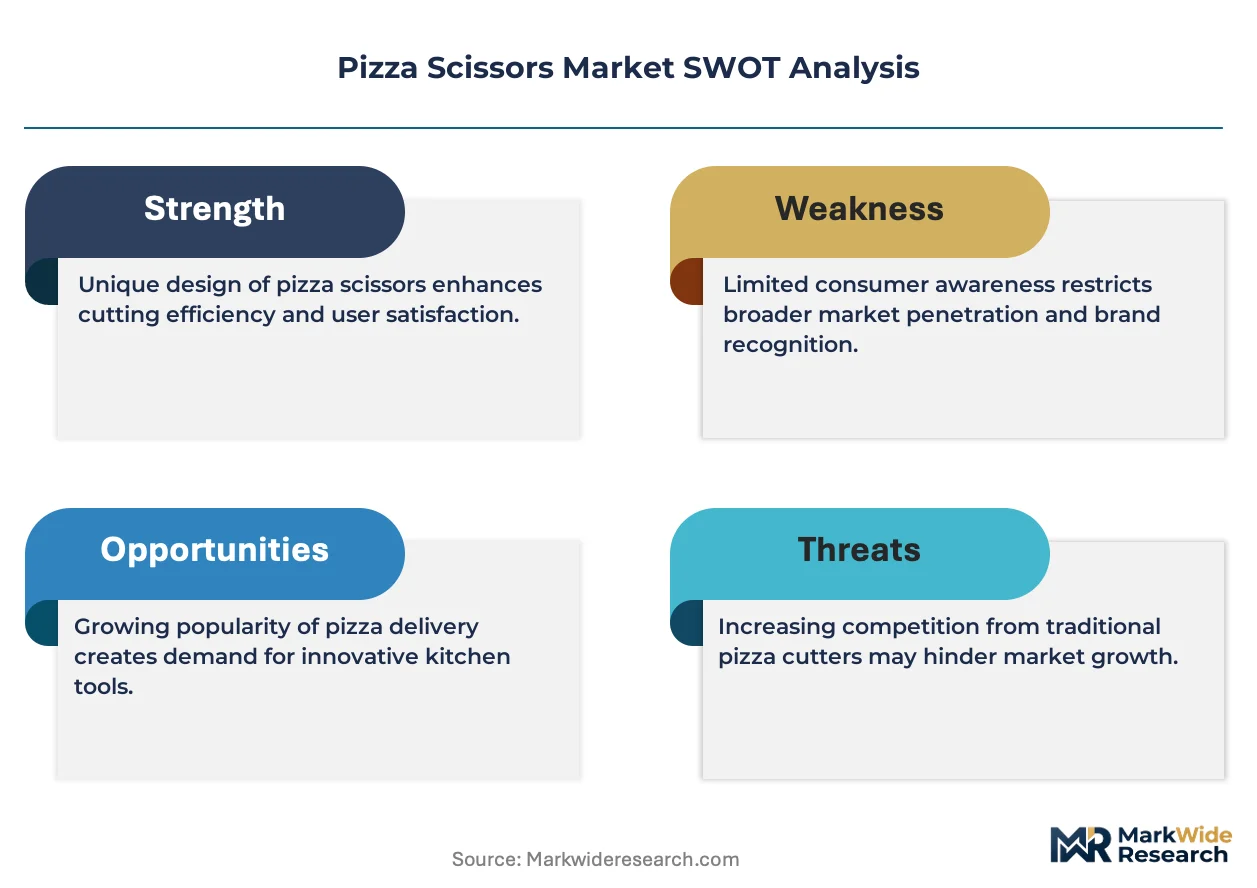
Premium-grade stainless steel specification is unwinding across the Pizza Scissors Market as consumers and professionals reject lower-alloy alternatives. Williams Sonoma leverages its specialty retail network to sustain pricing power in the premium segment. Dreamfarm anchors its position through ergonomic design specialization that commands repeat commercial orders.
Pizza scissors are handheld cutting tools combining hardened blade assemblies with integrated serving platforms, typically manufactured from food-grade stainless steel through stamping and heat-treatment processes, designed to portion and transfer pizza slices without crust deformation or topping displacement. Dual blade scissors and ergonomic scissors occupy distinct margin pools, with the former capturing commercial volume in pizzerias and the latter extracting premium pricing from households seeking reduced-wrist-strain designs. Stainless steel material grade differentiates performance tiers, with higher-alloy compositions resisting acidic tomato sauce corrosion across extended commercial wash cycles.
FDA food-contact substance regulations and EU REACH compliance frameworks govern stainless steel composition and surface finish requirements, directly shaping supplier qualification criteria for brands selling into the United States and European markets. BIS certification in India adds a third compliance layer for manufacturers targeting Asian expansion. Stakeholders must monitor evolving alloy disclosure rules and decide whether to consolidate supply chains under unified material standards or fragment sourcing by geography.
Market Dynamics
Commercial kitchen procurement teams are consolidating utensil suppliers under single-source contracts, compressing vendor counts and elevating compliance documentation requirements for pizza scissor manufacturers seeking institutional volume.
Growth Catalysts
- Quick-service restaurant expansion:Chains in the United States are standardizing portioning tools across franchise networks, creating recurring bulk orders for dual-blade commercial models.
- EU REACH material disclosure:Manufacturers achieving full alloy traceability certification are capturing shelf space in German and Italian specialty retail as consumers verify food-contact safety.
- Ergonomic design specialization:Wrist-strain reduction engineering is penetrating household segments in aging demographics across Japan and South Korea.
Market Restraints
- Nickel price volatility:Stainless steel 304 and 316 input costs fluctuate with Indonesian ore export policies, squeezing margin on mid-tier products.
- Guangdong stamping concentration:Over half of global blade assembly capacity sits in a single Chinese province, exposing supply to regional logistics disruptions.
- Pizza wheel substitution:Rocking blade cutters retain cost advantage in price-sensitive pizzeria segments, limiting scissors penetration in emerging markets.
Strategic Opportunities
- India cloud kitchen proliferation:Delivery-only pizza operations in Mumbai and Bangalore need compact, multi-function tools for tight prep spaces.
- US Inflation Reduction Act domestic content:Stainless steel fabricated in American mills qualifies for federal procurement preference, opening institutional channels.
- Smart packaging integration:QR-linked alloy certificates on product packaging enable direct-to-consumer transparency marketing.
Industry Challenges
- FDA 510(k) equivalence documentation:New blade geometries require substantial clinical safety filings, extending product launch timelines by 8-14 months.
- Heat-treatment technician scarcity:Specialized metallurgists capable of optimizing Rockwell hardness for food-grade applications command premium wages in manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Scissors Market |
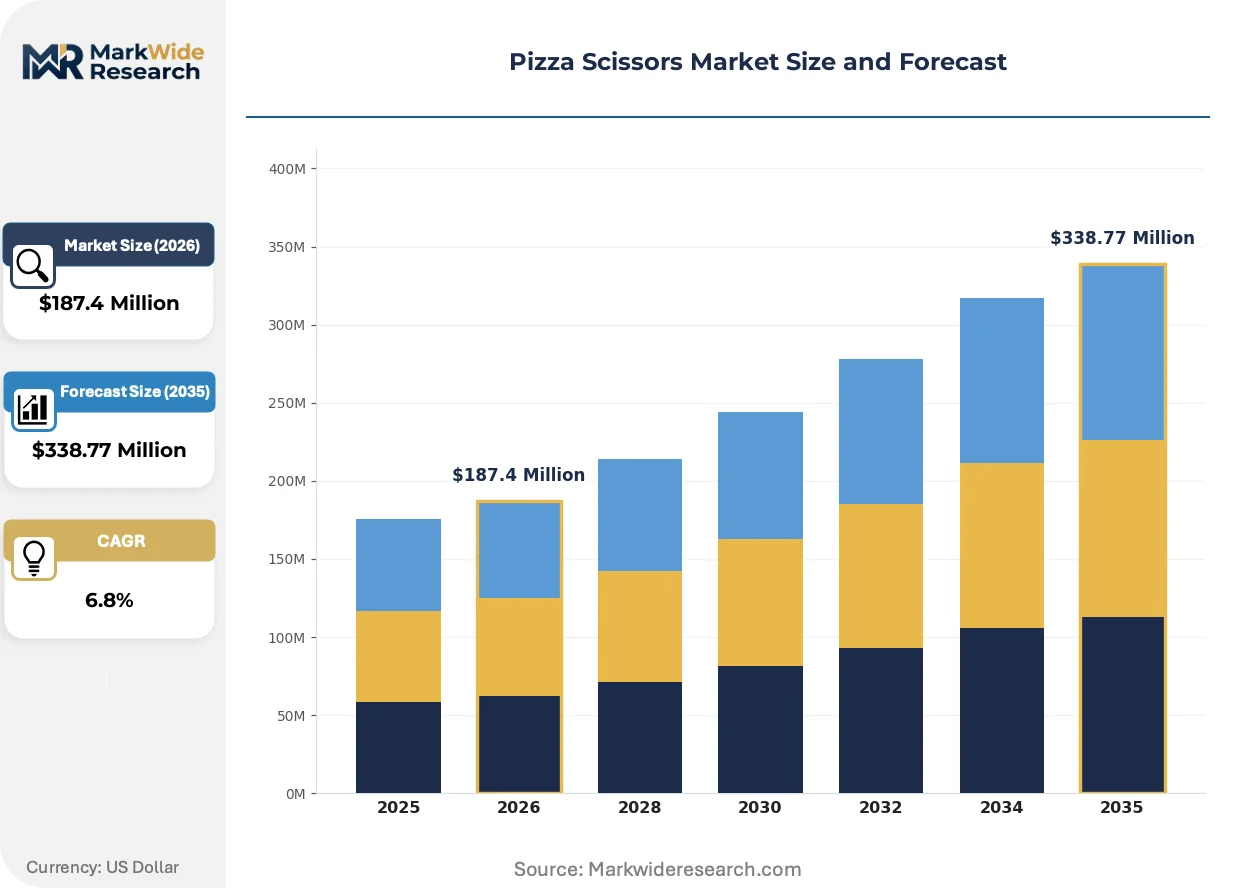
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Scissors, Dual Blade Scissors, Specialty Scissors, Ergonomic Scissors Material: Stainless Steel, Plastic, Alloy, Composite End User: Households, Restaurants, Pizzerias, Food Trucks Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Williams Sonoma, Dreamfarm, BOSKA, Joseph Joseph, Ooni, Zyliss, OXO, Pampered Chef, Brabantia Branding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Scissors Market Evolving Landscape
Material science advances and regulatory disclosure mandates are converging to reshape competitive positioning in pizza scissor manufacturing. Product differentiation increasingly hinges on verifiable alloy composition rather than cosmetic design alone.
Spring-assisted blade mechanisms are miniaturizing into compact household formats previously dominated by manual shear designs. Williams Sonoma and specialty kitchen retailers in California are accelerating adoption of these reduced-effort models. The technology is miniaturizing commercial-grade force multiplication into sub-200-gram consumer tools, collapsing the performance gap between professional and home kitchen segments.
EU REACH Annex XVII nickel release restrictions are tightening surface finish specifications for prolonged skin-contact tools. Manufacturers serving German and French markets must now submit migration testing data for 28-day exposure protocols. Small-batch Italian producers are responding by shifting to nitrogen-passivated surface treatments that reduce ion leaching below 0.5 micrograms per square centimeter weekly.
Direct-to-restaurant purchasing platforms are displacing traditional foodservice distributor intermediaries in North American equipment procurement. Independent pizzerias in Texas and Ohio now source specialty tools through consolidated e-procurement portals that bundle utensils with disposables and cleaning chemicals. This channel compression is most advanced in the United States, where distributor margins of 22-35 percent are being extracted by vertically integrated supply platforms.
Pizza Scissors Market Segmentation
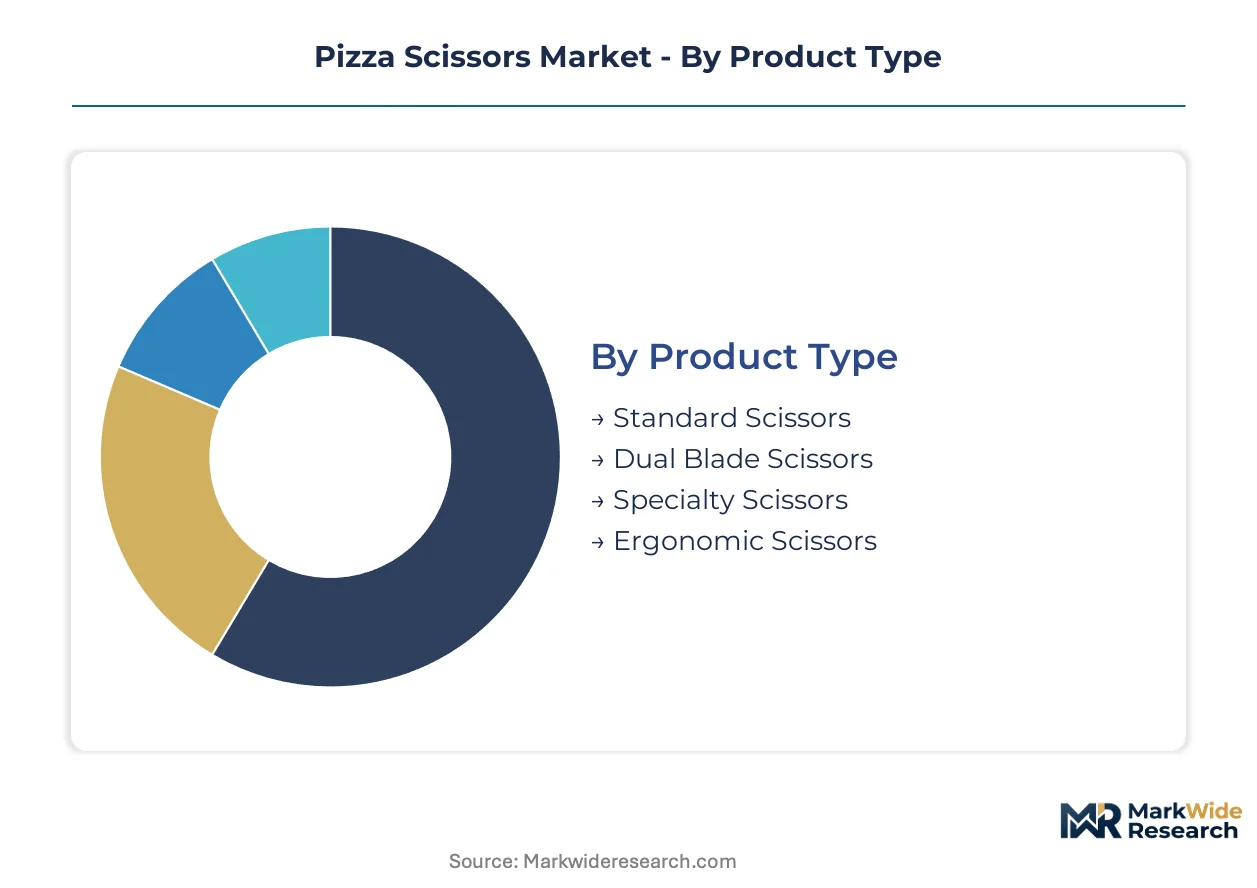
Pizza scissor purchasing patterns diverge sharply across user contexts, with commercial buyers prioritizing durability certifications and household segments emphasizing ergonomic comfort. Channel fragmentation forces manufacturers to maintain parallel product lines optimized for distributor bulk contracts versus direct-to-consumer packaging.
Product Type:
Dual-blade and ergonomic variants flow through divergent channel architectures, with the former dominating foodservice distributor catalogs and the latter commanding premium placement in specialty kitchen retail.
- Standard Scissors:Single-blade shears with riveted pivot joints and stamped stainless construction serve entry-level household demand. Volume concentrates in German and Italian supermarkets where private-label sourcing compresses unit economics.
- Dual Blade Scissors:Parallel blade assemblies with integrated serving platforms enable single-motion portioning and transfer. Quick-service restaurant chains in the United States standardize this format across franchise networks, generating recurring institutional procurement.
- Specialty Scissors:Custom geometries for deep-dish or stuffed-crust applications occupy niche manufacturing capacity.
- Ergonomic Scissors:Spring-assisted mechanisms and offset handle angles reduce wrist extension angles. Japanese aging demographics and South Korean single-person households drive adoption through Williams Sonoma and regional specialty retailers.
By volume, dual-blade configurations lead. By expansion trajectory, ergonomic designs are climbing the fastest.
Material:
Cost tier stratification separates food-grade certified supply from commodity alternatives, with alloy grade directly determining FDA and EU REACH qualification eligibility.
- Stainless Steel:304 and 316 grades with nitrogen-passivated surfaces resist tomato acid corrosion across commercial dishwasher cycles. Full alloy traceability certification unlocks German and Italian specialty retail placement.
- Plastic:Glass-reinforced nylon handles reduce thermal conductivity in high-volume pizzeria environments. Food trucks in Texas and Florida favor this lightweight specification for mobile prep constraints.
- Alloy:Mixed-metal compositions balance cost and corrosion resistance in emerging market price tiers.
- Composite:Carbon fiber or ceramic-reinforced polymers target premium household segments seeking reduced maintenance.
Stainless steel commands the revenue pool. Composite formulations are gaining share fastest among design-conscious consumers.
End User:
Application context dictates performance specifications, with commercial users validating Rockwell hardness ratings and households responding to aesthetic finish and packaging presentation.
- Households:Individual consumers purchasing through Amazon, Williams Sonoma, and Target prioritize spring-assisted mechanisms and dishwasher-safe certification. Aging demographics in Japan and South Korea drive ergonomic feature premiums.
- Restaurants:Full-service establishments source through consolidated e-procurement portals bundling utensils with cleaning chemicals and disposables. Texas and Ohio independent operators have shifted toward direct-to-restaurant platforms.
- Pizzerias:High-volume portioning demands hardened blade edges maintaining sharpness beyond 10,000 cutting cycles.
- Food Trucks:Compact multi-function tools suit Mumbai and Bangalore cloud kitchen proliferation where prep space constraints dominate tool selection.
Restaurants generate the bulk order flow. Food trucks are expanding most quickly as delivery-only operations proliferate.
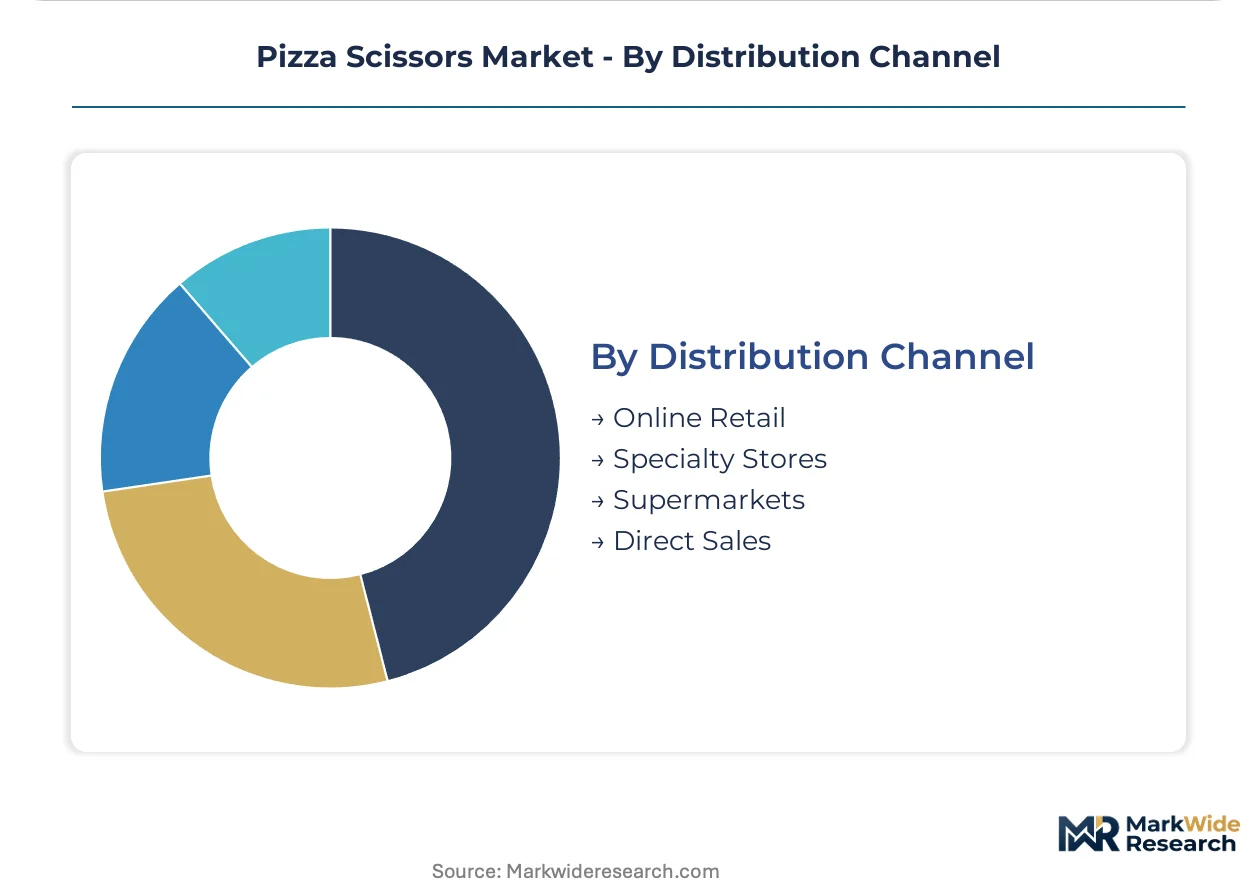
Distribution Channel:
Supply concentration in Guangdong stamping clusters shapes channel economics, with direct sales bypassing traditional distributor markups of 22-35 percent.
- Online Retail:Amazon, Alibaba, and vertical kitchenware platforms enable alloy certificate transparency through QR-linked packaging. German and French consumers verify REACH compliance before purchase.
- Specialty Stores:Williams Sonoma and Sur La Table sustain premium pricing through tactile merchandising and in-store demonstration. California and New York metropolitan concentrations anchor this channel.
- Supermarkets:Aldi, Lidl, and Kroger private-label programs compress margins in exchange for volume placement.
- Direct Sales:Manufacturer-to-restaurant platforms displace foodservice distributors in North American institutional procurement.
Online retail leads by transaction volume. Direct sales channels are deepening their share fastest among commercial buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pizza scissors tilt toward finished goods outflows from East Asian stamping clusters and alloy inflows from Indonesian ore processors. The United States, Germany, and Japan absorb premium ergonomic units while India and Brazil import mid-tier commercial configurations.
United States
Quick-service restaurant chains in Texas and Ohio standardize dual-blade portioning tools across franchise networks, generating recurring institutional procurement. FDA food-contact substance regulations govern stainless steel composition for domestic and imported inventory alike. California specialty retailers anchor premium ergonomic sales through tactile merchandising channels.
Germany
EU REACH Annex XVII nickel release restrictions drive migration testing for 28-day exposure protocols among specialty kitchen retailers. Independent pizzerias in Bavaria and North Rhine-Westphalia verify alloy traceability before sourcing. Stuttgart-area distributors consolidate e-procurement portals that bundle utensils with cleaning chemicals.
Japan
Aging demographics in Kanto and Kansai regions sustain premium pricing for spring-assisted wrist-strain reduction designs. METI standards for food-contact metallic materials shape import qualification criteria. Osaka-based specialty retailers command repeat household orders through ergonomic demonstration programs.
India
Cloud kitchen proliferation in Mumbai and Bangalore demands compact multi-function tools for tight prep spaces in delivery-only operations. BIS certification adds compliance layer for stainless steel food-contact applications. Gujarat stamping workshops supply blade assemblies to domestic fabricators serving institutional buyers.
Italy
Deep-rooted pizza culture in Lombardy and Emilia-Romagna sustains specialty retail channels for premium serving-platform designs. ECHA alloy disclosure requirements concentrate shelf space among fully certified producers. Small-batch Bologna manufacturers deploy nitrogen-passivated surface treatments to meet migration thresholds.
Pizza Scissors Market Competitive Landscape
Concentration sits with specialty kitchen retailers and ergonomic design houses rather than diversified industrial conglomerates. The vendor base spans three tiers: premium-brand specialty retailers commanding tactile merchandising premiums, mid-tier houseware specialists optimizing for catalog placement, and private-label fabricators serving supermarket volume programs. Strategic moves cluster around ergonomic patent filing and direct-to-restaurant platform partnerships.
Among specialty retail anchors, Williams Sonoma exemplifies the premium-tier archetype through California-based tactile merchandising networks. Dreamfarm occupies a parallel position representing ergonomic design specialization that commands repeat commercial orders. BOSKA anchors the European heritage fabricator segment with Dutch-structured operations.
| Leading Market Players |
|---|
| Williams Sonoma |
| Dreamfarm |
| BOSKA |
| Joseph Joseph |
| Ooni |
| Zyliss |
| OXO |
| Pampered Chef |
| Brabantia Branding B.V. |
| Others |
Value Network & Pricing Analysis
Nitrogen-passivated surface treatments replacing conventional chromium oxide finishes are simultaneously shifting production toward Italian and German specialty fabricators and compressing margin pools for commodity-grade suppliers unable to absorb certification costs. This substitution dynamic concentrates pricing power with alloy-traceability-certified producers while fragmenting supply geography between premium European finishers and volume-oriented Asian stampers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers extract margin through FDA and EU REACH certification documentation, while price erosion runs through mid-tier products as Indonesian nickel ore export volatility squeezes input costs. Quick-service restaurant procurement teams exhibit highest price sensitivity due to standardized franchise tool budgets, whereas specialty retailers like Williams Sonoma sustain lowest sensitivity through tactile merchandising premiums.
Supply Chain Analysis
Inventory cycles for blade assemblies stretch 8-14 weeks as Guangdong stamping clusters absorb order volatility from North American quick-service chains. Raw material flows draw from Indonesian nickel processors, German steel mills, and Indian BIS-certified foundries. Single-province concentration in Guangdong exposes the network to regional logistics disruptions. Distribution runs through consolidated e-procurement portals displacing traditional foodservice distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat-treatment technician scarcity constrains capacity expansion across all tiers, with specialized metallurgists capable of optimizing Rockwell hardness for food-grade applications commanding wage premiums that deter new facility investment.
For Market Incumbents: Consolidate supplier relationships under unified material standards to defend against nickel price volatility eroding mid-tier margins. Invest in captive nitrogen-passivation capacity within EU jurisdiction to preempt REACH Annex XVII migration testing bottlenecks. Secure direct-to-restaurant platform partnerships before channel compression eliminates distributor buffers entirely. For New Entrants and Emerging Players: EU REACH alloy traceability certification fast-tracks shelf placement in German and Italian specialty retail where incumbent documentation gaps persist. Target Mumbai and Bangalore cloud kitchen operators with compact multi-function designs for tight prep spaces. Pursue white-label partnerships with Gujarat stamping workshops to bypass capital-intensive blade assembly investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ergonomic design houses holding patent portfolios around spring-assisted mechanisms but lacking commercial scale infrastructure. Five-to-ten year viability hinges on backward integration into heat-treatment capacity rather than brand licensing alone. Monitor FDA 510(k) filing velocity as inflection signal for product launch pipeline health.| Strategic Initiative | Industry Significance |
|---|---|
| Alloy Traceability Certification | EU REACH compliance unlocks German and Italian specialty retail placement against undocumented competitors. |
| Direct-to-Restaurant Platform Partnership | Vertical integration into institutional procurement displaces 22-35 percent distributor markups in Texas and Ohio. |
| Spring-Assisted Mechanism Patent Filing | Ergonomic IP protection captures aging demographic premiums in Japan and South Korea. |
| Nitrogen-Passivation Capacity Addition | In-house surface treatment reduces migration testing costs for 28-day EU exposure protocols. |
| Cloud Kitchen Compact Tool Launch | Mumbai and Bangalore delivery-only operations demand multi-function designs for constrained prep spaces. |
Research Methodology
Operator-level perspectives from quick-service restaurant procurement directors, commercial kitchen equipment distributors, stainless steel alloy suppliers, and ergonomic design engineers anchored the qualitative base. Secondary validation drew from FDA food-contact substance filings, EU REACH Annex XVII migration testing databases, BIS certification registries, and customs trade records for blade assembly flows. Bottom-up volume estimates triangulated against top-down spending analysis across household, restaurant, and food truck end-use segments.
Sensitivity analysis tested forecast robustness across nickel price volatility scenarios and Guangdong logistics disruption assumptions. Segmentation dimensions modeled include product type, material grade, end-user application, and distribution channel structure. CAGRs derived from weighted average of historical volume trajectories and forward-looking procurement intent signals from franchise standardization programs and cloud kitchen expansion pipelines.
Underlying assumptions cover sustained quick-service restaurant franchise network expansion and stable EU REACH enforcement intensity, with deviation risk concentrated in Indonesian ore export policy shifts and FDA 510(k) review timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market