
 Perfusion Tubing Systems Market | 2026-2036
Perfusion Tubing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Perfusion Tubing Systems Market Analytics
The EU Medical Device Regulation is restructuring procurement criteria for cardiovascular perfusion circuits across European hospitals. Medtronic leverages its integrated perfusion portfolio to sustain long-term contracts with major cardiac surgery centers. LivaNova PLC anchors its competitive position through specialized oxygenator-tubing system integration. Terumo Corporation differentiates via advanced coating technologies that reduce platelet adhesion in extended bypass procedures.
Perfusion tubing systems are sterile, single-use conduits manufactured from medical-grade polymers such as polyvinyl chloride or silicone, extruded to precise inner diameters and wall thicknesses for controlled fluid dynamics during extracorporeal circulation. These systems maintain sterile, pulsatile or continuous blood flow through oxygenators and reservoirs during cardiopulmonary bypass or isolated organ perfusion. Multi-lumen tubing configurations command premium positioning due to their integration complexity in advanced bypass circuits, while silicone-based formulations are gaining preference in research applications requiring extended biocompatibility windows. Single-lumen tubing retains volume dominance in standard cardiopulmonary bypass procedures across high-throughput hospital settings.
The FDA enforces biocompatibility testing under ISO 10993 standards for all blood-contacting perfusion components, while the EU MDR requires enhanced clinical evidence documentation for Class III device accessories. Japan's PMDA maintains stringent lot-release protocols for imported cardiovascular perfusion sets, shaping market access timelines for non-domestic manufacturers. Stakeholders must monitor evolving regulatory convergence between FDA and EU MDR requirements for polymer extractables testing, as divergence in acceptance criteria will force parallel qualification strategies.
Market Dynamics
EU MDR compliance deadlines are compressing qualification timelines for polymer extractables testing, forcing manufacturers to parallelize documentation strategies across notified bodies while academic cardiac centers expand extracorporeal perfusion capabilities.
Growth Catalysts
- Cardiac surgery program expansion:Academic medical centers in Germany are upgrading bypass circuit infrastructure, creating concentrated demand for multi-lumen tubing configurations with integrated oxygenator compatibility.
- ISO 10993 standard harmonization:Convergence between FDA biocompatibility requirements and EU MDR clinical evidence mandates is streamlining dual-market qualification pathways for blood-contacting polymer components.
- Silicone formulation advances:Extended biocompatibility windows in medical-grade silicone variants are displacing PVC in research applications requiring prolonged perfusion protocols.
Market Restraints
- Medical-grade PVC supply concentration:Polymer feedstock production clusters in specific Asian manufacturing zones create vulnerability to regional logistics disruptions.
- PMDA lot-release protocols:Japan's stringent import inspection timelines extend market access cycles for non-domestic cardiovascular perfusion set manufacturers.
- Biocompatibility documentation burden:EU MDR enhanced clinical evidence requirements for Class III device accessories inflate regulatory compliance costs disproportionately for mid-scale tubing specialists.
Strategic Opportunities
- Isolated organ perfusion research:Extended-circulation applications in transplant medicine create demand for silicone-based formulations with superior platelet adhesion resistance.
- Integrated circuit contracting:Long-term supply agreements with specialized heart centers bundle oxygenator-tubing systems, locking out component-only competitors.
- Coating technology differentiation:Advanced surface treatments reducing thrombogenicity command premium positioning in high-complexity bypass procedures.
Industry Challenges
- Polymer extractables testing capacity:Divergent FDA and EU MDR acceptance criteria for leachable compounds force redundant analytical qualification programs.
- Perfusionist workforce constraints:Specialized clinical training pipelines for extracorporeal circulation management lag behind cardiac surgery program expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfusion Tubing Systems Market |
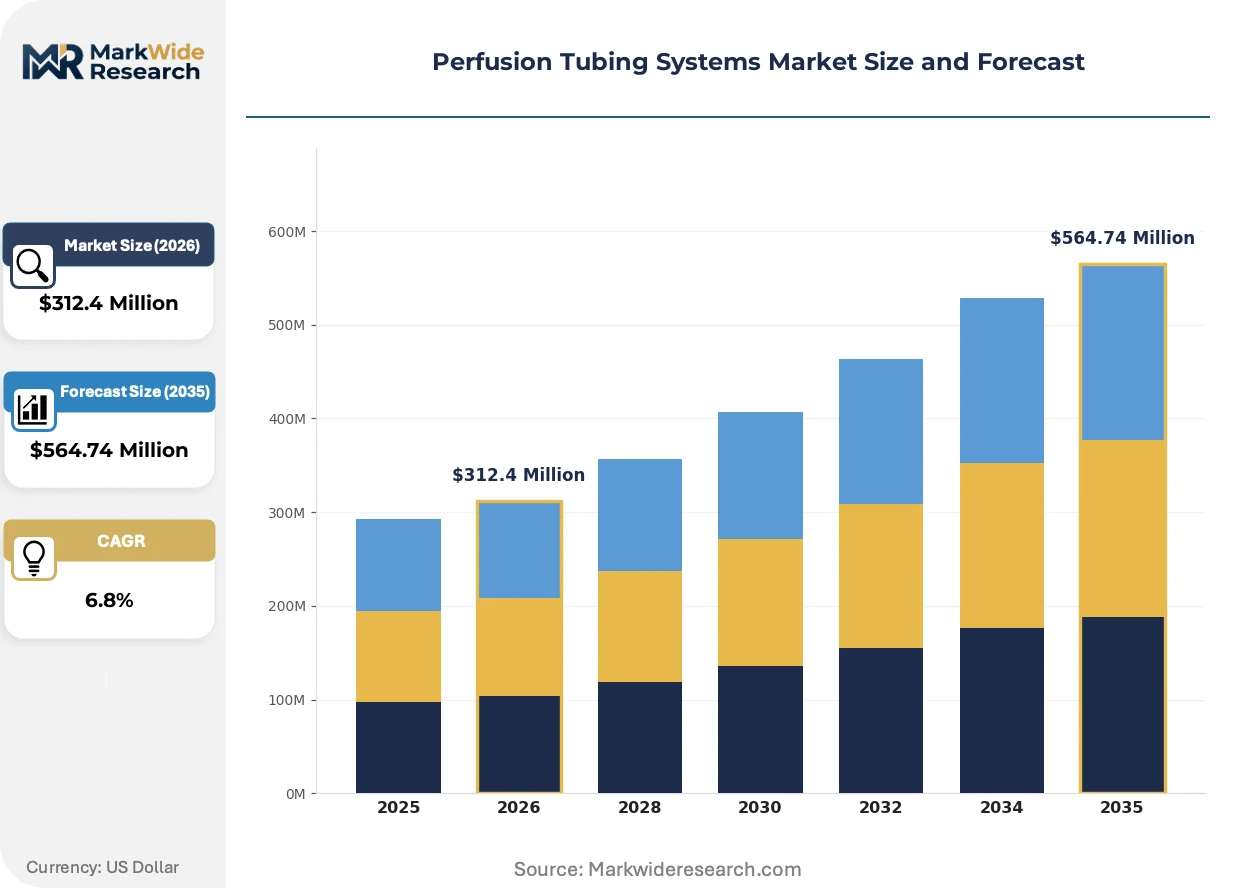
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-lumen Tubing, Multi-lumen Tubing, Pooled Tubing, Coiled Tubing Material: Polyvinyl Chloride, Polypropylene, Silicone, Thermoplastic Elastomers Application: Cell Culture, Blood Washing, Organ Perfusion, Drug Delivery End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Biotech Firms |
| Companies Covered | Medtronic, LivaNova PLC, Terumo Corporation, Getinge, Nipro Corporation, Laborie, XVIVO Perfusion AB, Biorep, Harvard Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfusion Tubing Systems Market Evolving Landscape
Surface engineering and polymer science advances are compressing the performance gap between standard and extended-perfusion tubing systems, while regulatory documentation requirements reshape competitive qualification barriers.
Antithrombogenic coating technologies incorporating heparin-bonded or phosphorylcholine surface modifications are rewriting performance benchmarks for platelet preservation in cardiopulmonary bypass circuits. German heart centers and North American academic hospitals are adopting these formulations for complex, multi-hour procedures despite cost premiums. The technology is rewriting procurement criteria, as clinical outcome data now outweighs unit price in tender evaluations for high-risk patient populations.
EU MDR Article 10 technical documentation requirements for Class III device accessories are mandating systematic clinical evidence portfolios for tubing systems previously qualified under self-certification routes. Manufacturers must now submit post-market surveillance plans and periodic safety update reports to notified bodies, inflating compliance resource allocation. German notified bodies and Dutch regulators are processing these submissions with variable timelines, creating competitive advantage for firms with established EU quality management systems.
Hospital procurement departments are consolidating cardiovascular perfusion circuit purchasing through integrated device contracts rather than component-level sourcing. Academic medical centers in Germany and specialized cardiac surgery units in France are bundling oxygenator-tubing-reservoir systems under multi-year agreements with single-source suppliers. This consolidation is most visible in high-throughput settings where standardization reduces perfusionist training burden and inventory complexity.
Perfusion Tubing Systems Market Segmentation
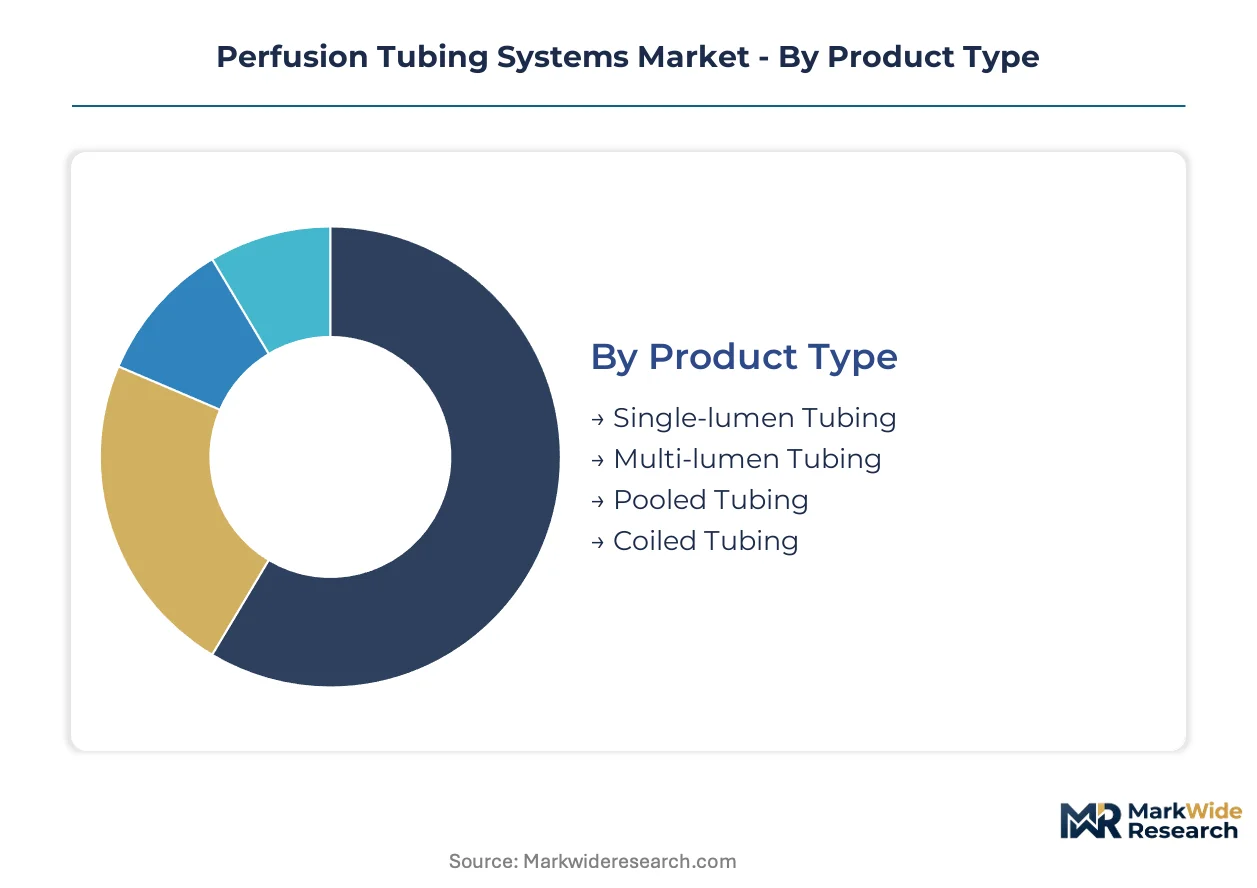
Perfusion tubing segmentation maps directly to regulatory pathway complexity and sterilization validation requirements. Manufacturers must align product architecture with specific ISO 10993 testing protocols and end-use biocompatibility windows.
Product Type:
FDA Class II designation covers single-lumen configurations, while multi-lumen and specialty formats trigger Class III accessory pathways under EU MDR Article 10.
- Single-lumen Tubing:Standard extruded medical-grade polymer conduit with uniform inner diameter. German heart centers deploy this format for high-throughput cardiopulmonary bypass procedures where circuit standardization reduces perfusionist training burden.
- Multi-lumen Tubing:Complex extrusion integrating separate channels for simultaneous blood, cardioplegia, and pressure monitoring lines. Academic medical centers in France specify these configurations for advanced bypass circuits requiring integrated oxygenator compatibility.
- Pooled Tubing:Pre-assembled manifold configurations for rapid circuit deployment. Research laboratories in isolated organ perfusion studies favor this format for protocol reproducibility.
- Coiled Tubing:Spiral-wound configurations minimizing priming volume and surface area. Pediatric cardiac units specify this geometry for neonatal bypass procedures.
Single-lumen tubing sits at the top of the volume ranking, with multi-lumen tubing climbing the fastest.
Material:
Polymer selection determines extractables testing burden and regional market access timelines.
- Polyvinyl Chloride:Dominant medical-grade formulation with established plasticizer biocompatibility profiles. High-throughput hospital settings specify PVC for cost-sensitive standard bypass procedures.
- Silicone:Platinum-cured elastomer with extended hemocompatibility windows. Transplant research centers in Germany specify silicone for prolonged ex-vivo organ perfusion protocols exceeding six hours.
- Polypropylene:Semi-crystalline thermoplastic with superior chemical resistance. Pharmaceutical manufacturing applications specify this material for drug delivery system compatibility.
- Thermoplastic Elastomers:Block copolymer formulations combining elastomeric performance with thermoplastic processability. Biotech firms specify TPE for single-use cell culture perfusion circuits.
Polyvinyl chloride commands the installed base, while silicone gains share fastest in extended-perfusion applications.
Application:
Clinical versus research use cases split regulatory qualification strategies and pricing architecture.
- Cell Culture:Sterile closed-loop perfusion for bioreactor nutrient delivery. Biotech firms in Cambridge and Basel clusters specify single-use tubing sets for GMP-compliant manufacturing.
- Blood Washing:Intraoperative autotransfusion and hemodilution management. French cardiac surgery centers deploy dedicated tubing circuits for cell salvage procedures.
- Organ Perfusion:Ex-vivo machine perfusion for transplant viability assessment. German transplant networks specify silicone-based systems for liver and kidney preservation protocols.
- Drug Delivery:Precision infusion for targeted therapeutic administration. Pharmaceutical companies specify materials with validated leachable profiles for parenteral applications.
Organ perfusion commands the steepest price tier, with cell culture expanding most quickly in bioproduction scale-up.
End User:
Procurement authority and volume commitment shape contract structure and technical service intensity.
- Hospitals:Integrated cardiovascular surgery departments with perfusionist-staffed bypass programs. German university hospitals negotiate multi-year oxygenator-tubing bundles under framework agreements.
- Research Laboratories:Academic and institutional investigators requiring protocol-specific configurations. Max Planck and Helmholtz network facilities specify custom silicone formulations for extended circulation studies.
- Pharmaceutical Companies:GMP manufacturing operations with validated single-use process trains. Merck KGaA and Boehringer Ingelheim facilities specify extractables-documented tubing for biologic production.
- Biotech Firms:Development-stage and commercial cell therapy manufacturers. Berlin and Munich biotech clusters specify scalable perfusion formats for clinical trial material production.
Hospitals anchor procurement volume, with biotech firms posting the most rapid contract expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiopulmonary bypass technology originated in the United States during the 1950s, with Minnesota-based researchers pioneering the first successful open-heart procedures using early perfusion circuits. This historical foundation established North American clinical standards that subsequently diffused to European and Asian cardiac surgery programs.
United States
Academic medical centers in Boston and Houston are expanding hybrid operating room capabilities requiring advanced bypass circuit infrastructure. The FDA enforces ISO 10993 biocompatibility testing protocols for all blood-contacting polymer components. The Texas Medical Center in Houston anchors procurement volume for multi-lumen tubing configurations with integrated oxygenator compatibility.
Germany
Specialized heart centers in Berlin and Munich are upgrading extracorporeal perfusion capabilities for complex aortic procedures. The EU Medical Device Regulation mandates enhanced clinical evidence documentation for Class III device accessories under Article 10. The Max Planck Institute network in Bavaria specifies silicone-based formulations for extended organ perfusion research protocols.
Japan
Tokyo University Hospital and Osaka cardiovascular institutes are adopting antithrombogenic coating technologies for prolonged bypass procedures. The PMDA maintains stringent lot-release protocols for imported cardiovascular perfusion sets, extending market access timelines. The Kanto region's cardiac surgery clusters concentrate demand for pre-assembled manifold configurations.
United Kingdom
NHS England's specialized commissioning frameworks are consolidating cardiovascular perfusion circuit purchasing through integrated device contracts. The MHRA aligns with EU MDR requirements for polymer extractables testing documentation. Cambridge's biotech corridor specifies single-use tubing sets for GMP-compliant cell therapy manufacturing.
France
Parisian academic hospitals and Lyon cardiac surgery units are bundling oxygenator-tubing-reservoir systems under multi-year supply agreements. ANSM enforces post-market surveillance plans for Class III device accessories. The Île-de-France region's hospital procurement consortia prioritize standardized circuit configurations to reduce perfusionist training burden.
Perfusion Tubing Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology and integrated system capabilities, with antithrombogenic surface treatments commanding price multiples over standard polymer formulations. The vendor base clusters around three strategic archetypes: diversified cardiovascular device conglomerates with full perfusion portfolios, specialized oxygenator-tubing integrators, and coating technology specialists. Dominant competitive moves include backward integration into polymer compounding operations and long-term exclusive supply agreements with high-volume cardiac surgery centers.
Among diversified cardiovascular device conglomerates, Medtronic and LivaNova PLC exemplify the integrated portfolio archetype, while Terumo Corporation occupies a position within the coating technology specialist tier. These three companies anchor the competitive structure through their representation of distinct strategic positions: Medtronic through its breadth of perfusion components, LivaNova PLC through oxygenator-tubing system integration, and Terumo Corporation through surface modification capabilities.
| Leading Market Players |
|---|
| Medtronic |
| LivaNova PLC |
| Terumo Corporation |
| Getinge |
| Nipro Corporation |
| Laborie |
| XVIVO Perfusion AB |
| Biorep |
| Harvard Bioscience |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between antithrombogenic coated systems and standard polymer tubing manifests in divergent margin structures and procurement patterns across cardiac surgery centers. Coated configurations command premium positioning through integrated oxygenator compatibility and extended biocompatibility windows, while commodity-grade PVC tubing concentrates in high-throughput hospital settings where standardization reduces inventory complexity. This tier divergence shapes supplier qualification requirements, with coating technology specialists maintaining captive polymer compounding operations to defend formulation intellectual property.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes procurement negotiations in academic medical centers and specialized heart centers. Price differentiation hinges on ISO 10993 certification grade and antithrombogenic surface treatment complexity, with silicone-based formulations carrying material cost premiums over PVC alternatives. Cost compression in standard single-lumen configurations is intensifying because German hospital procurement consortia are consolidating cardiovascular perfusion circuit purchasing through multi-year framework agreements. Research laboratories exhibit lowest price sensitivity due to protocol-specific customization requirements, while high-throughput cardiac surgery units prioritize unit economics in tender evaluations.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing zones to European cardiac centers is reshaping regional inventory positioning strategies among tubing distributors. Polymer feedstock production clusters in China, South Korea, and Japan supply medical-grade PVC and platinum-cured silicone elastomers to extrusion facilities in Germany and the United States. Raw material dependencies on plasticizer formulations, platinum catalyst systems, and antithrombogenic coating precursors create vulnerability to chemical regulatory shifts under EU MDR extractables testing protocols. Single-source vulnerability concentrates in specialized coating technology inputs. Distribution runs through authorized medical device distributors with cold-chain capabilities and sterile handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Perfusion Tubing Systems Market functions as a stable compounder anchored by irreversible cardiac surgery program expansion in academic medical centers requiring standardized bypass circuit infrastructure.
For Market Incumbents: To counter coating technology commoditization from emerging polymer science entrants, Medtronic and LivaNova PLC should deepen backward integration into medical-grade silicone compounding operations and secure exclusive multi-year supply agreements with German university hospitals bundling oxygenator-tubing-reservoir systems. Captive control over platinum-cured elastomer formulations defends margin position against specialty chemical suppliers. For New Entrants and Emerging Players: The mid-tier price-point gap between Terumo Corporation's heparin-bonded premium systems and commodity PVC tubing offers white-space entry for TPE-based formulations targeting biotech cell culture perfusion circuits in Cambridge and Basel clusters. Isolated organ perfusion research protocols at Max Planck Institute facilities represent the most penetrable segment given protocol-specific customization tolerance. A go-to-market angle emphasizing extractables documentation speed for EU MDR compliance captures procurement attention. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale coating technology specialists possessing validated antithrombogenic surface treatments but lacking integrated oxygenator partnerships. Long-term viability over a multi-year horizon rests on regulatory qualification asset accumulation rather than manufacturing scale. The acquisition target archetype combines ISO 10993 testing portfolios with established notified body relationships. Watch for PMDA lot-release timeline compression as an inflection indicator for Japanese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Pathway | Enhanced clinical evidence documentation for Class III device accessories accelerates notified body queue positioning. |
| Hospital System Partnership | Multi-year oxygenator-tubing bundles with German heart centers lock out component-only competitors. |
| Backward Integration into Polymer Compounding | Captive silicone formulation control defends antithrombogenic coating intellectual property from feedstock suppliers. |
| Coating Technology Licensing | Heparin-bonded surface modification patents generate royalty streams from non-integrated tubing manufacturers. |
| Research Laboratory Collaboration | Custom protocol development with Max Planck and Helmholtz networks builds extended-perfusion application credibility. |
Research Methodology
Direct dialogue with perfusionists, cardiovascular surgeons, hospital procurement managers, biomedical engineers, and GPO contracts specialists grounded primary intelligence collection for this study. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation submissions, hospital procurement databases, and GPO contract repositories. Bottom-up segmentation modeling triangulated against top-down market sizing from cardiovascular device trade associations.
Segmented outputs across material type, product configuration, application setting, and end-user archetype populated the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity modeling tied to cardiac surgery program expansion rates and polymer cost pass-through assumptions. Forecast inputs incorporated EU MDR compliance timeline uncertainty and PMDA lot-release protocol evolution.
Caveats apply where regulatory divergence in polymer extractables acceptance criteria or perfusionist workforce expansion shortfalls could materially shift the outlook. Forecasts reflect documented assumptions about standardization trends in high-throughput hospital settings. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market