
 Piping Hydro Testing Market | 2026-2036
Piping Hydro Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Piping Hydro Testing Market Analytics
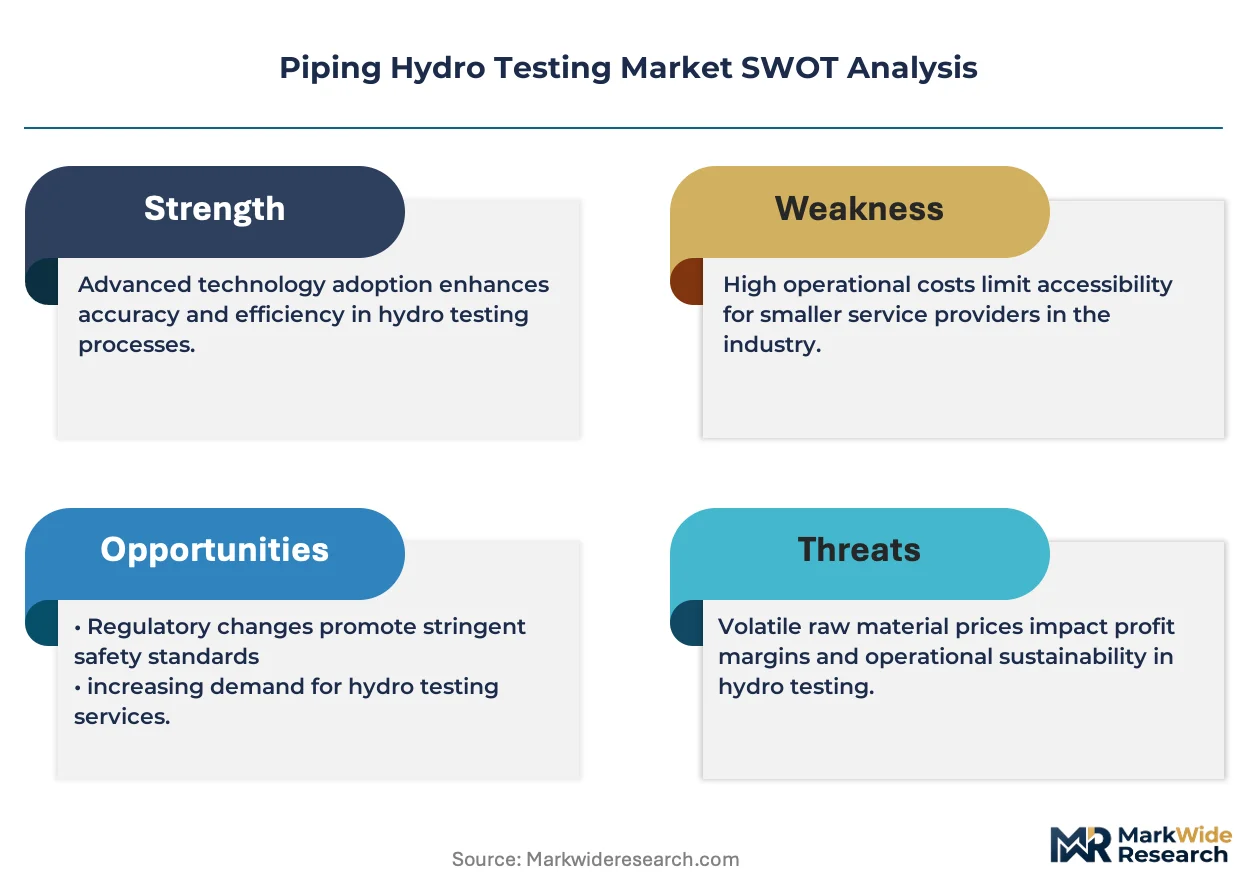
API 5L Grade X70 and above specification tiers is collapsing into mainstream procurement as pipeline operators face stricter integrity mandates. SGS SA leverages its global laboratory network to anchor certification workflows across upstream and midstream projects. Bureau Veritas competes through specialized risk-based inspection protocols that reduce downtime for offshore installations. Hydratight sustains market presence with portable tensioning and testing equipment deployed at remote construction sites.
Piping hydro testing subjects pressurized piping systems to water-filled pressure verification above design operating levels, typically at 1.5 times maximum allowable working pressure for sustained hold periods. The procedure validates weld integrity, flange sealing, and material performance before hydrocarbon or chemical service commencement. Pressure testing services dominate contract value due to mandatory pre-commissioning requirements in oil and gas and power generation applications, while ultrasonic testing technology gains share through non-destructive methods that eliminate fluid disposal costs. Hydraulic testing retains volume leadership in cross-country transmission pipelines where pneumatic alternatives present safety constraints.
ASME B31.3 process piping standards and API 570 inspection codes shape North American procurement specifications, while EPA spill prevention regulations tighten testing frequency for above-ground chemical transfer lines. The Pipeline and Hazardous Materials Safety Administration enforces hydrostatic retest intervals for natural gas transmission infrastructure, directly scheduling service demand. Stakeholders must weigh capital allocation between conventional pressure testing capacity and ultrasonic phased-array systems that promise faster turnaround without dewatering operations.
Market Dynamics
Digital pressure monitoring systems are decomposing the traditional manual gauge reading infrastructure across North American facilities, forcing service providers to reconfigure technician deployment models and equipment inventories around real-time data architectures.
Growth Catalysts
- ASME B31.3 integrity mandates:Process piping standards now require expanded hydro testing frequencies for high-pressure chemical service, compelling petrochemical operators to increase testing program scope.
- Ultrasonic phased-array adoption:Non-destructive testing methods eliminate dewatering requirements and fluid disposal costs, accelerating replacement of conventional hydraulic protocols in offshore installations.
- Gulf Coast petrochemical corridor concentration:Capacity expansion along the Texas-Louisiana industrial belt generates concentrated demand for pre-commissioning and integrity verification services.
Market Restraints
- Specialized technician scarcity:Qualified ultrasonic testing operators command premium wages, constraining service capacity expansion and compressing margins for regional contractors.
- Water sourcing constraints:Hydro testing consumes substantial freshwater volumes, creating operational friction in arid regions where discharge permits face heightened EPA scrutiny.
- Equipment capital intensity:Digital monitoring systems require upfront investment in pressure transducers and data acquisition hardware, disadvantaging smaller testing contractors.
Strategic Opportunities
- Carbon capture pipeline infrastructure:CO2 transport networks under development in the United States and Canada will require novel testing protocols for dense-phase service conditions.
- Hydrogen blending compatibility:Existing natural gas transmission systems undergoing hydrogen injection trials need reassessment of hydro testing parameters for embrittlement-sensitive materials.
- Remote Arctic developments:Portable testing equipment demand is concentrating at liquefied natural gas export facilities on the Alaskan North Slope and Russian Yamal Peninsula.
Industry Challenges
- Multi-standard harmonization:Contractors must simultaneously maintain ASME B31.3, API 570, and ISO 19840 certification portfolios, fragmenting training resources and audit cycles.
- Legacy system integration:Digital pressure monitoring platforms face interoperability barriers with existing SCADA architectures at brownfield refinery and chemical plant sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piping Hydro Testing Market |
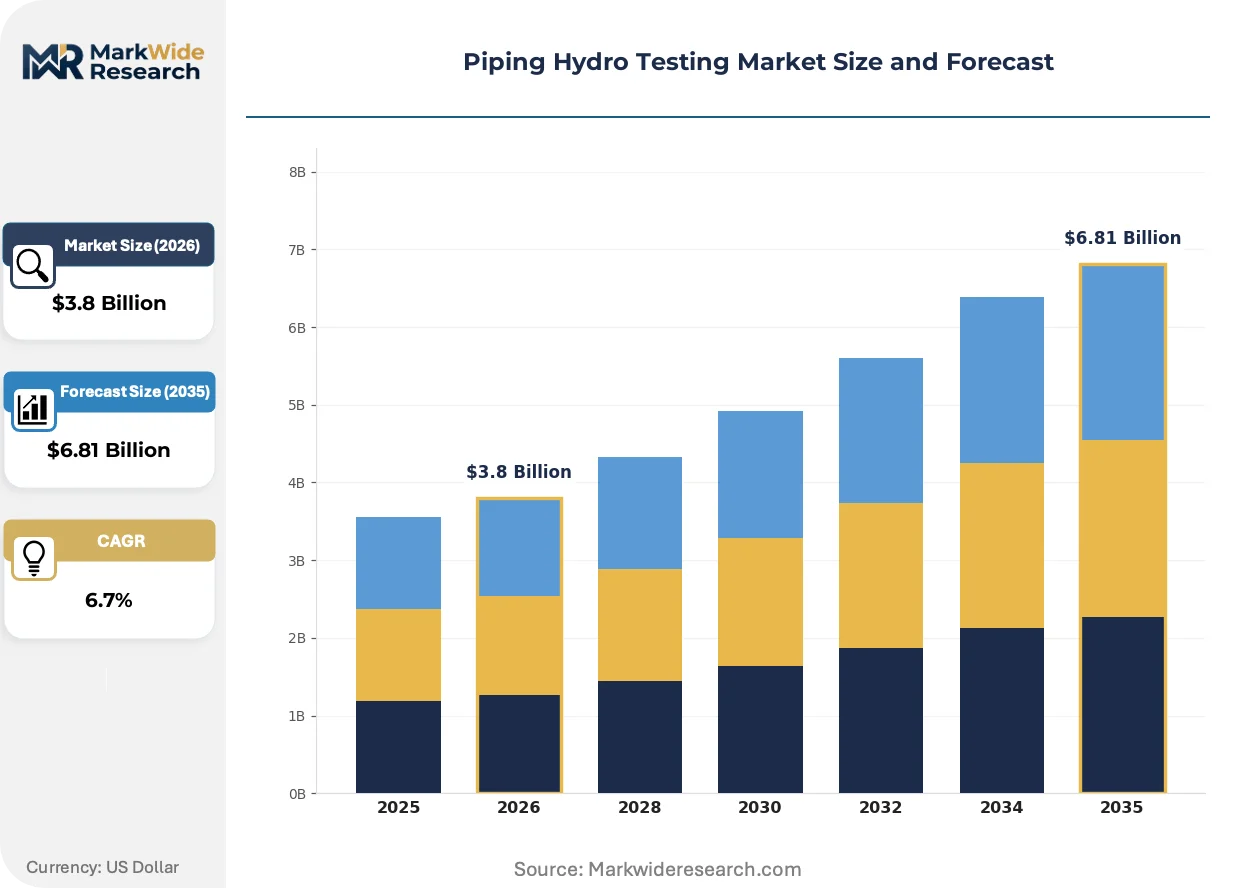
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pressure Testing, Leak Testing, Functional Testing, Integrity Testing Technology: Hydraulic Testing, Pneumatic Testing, Ultrasonic Testing, Electric Testing Application: Oil & Gas, Water Supply, Chemical Processing, Power Generation End User: Construction, Utilities, Manufacturing, Research Institutions |
| Companies Covered | SGS SA, Intertek Group, Bureau Veritas, Hydratight, Applus+, TÜV Rheinland, Compressor Engineering Corp., EnerMech, Milbar Hydro-Test, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piping Hydro Testing Market Evolving Landscape
Automation architectures are penetrating piping integrity verification workflows, compressing test cycle durations while elevating data granularity requirements for compliance documentation and predictive maintenance applications.
Wireless pressure transducer networks are decomposing the conventional technician patrol model for multi-point monitoring during extended hold periods. Offshore platform operators in the Gulf of Mexico are deploying these systems to reduce personnel exposure during high-pressure testing phases. The structural consequence is collapsing demand for manual gauge reading services while expanding the addressable market for integrated sensor-hardware-software packages.
EPA spill prevention regulations are tightening testing frequency mandates for above-ground chemical transfer lines, particularly at bulk storage terminals handling hazardous substances. Facility operators must now document integrity verification at shortened intervals, directly expanding recurring service contract volumes. Chemical manufacturing clusters in Texas and Louisiana are responding by consolidating testing programs under multi-year framework agreements with specialized contractors.
Buyer concentration among supermajor oil and gas producers is compressing vendor negotiation leverage and standardizing contract terms across regional service territories. Independent testing contractors face margin pressure as procurement functions centralize at corporate headquarters, displacing locally negotiated spot arrangements. This pattern is most pronounced along the United States Gulf Coast, where integrated operators have established preferred supplier panels for turnaround and maintenance cycles.
Piping Hydro Testing Market Segmentation
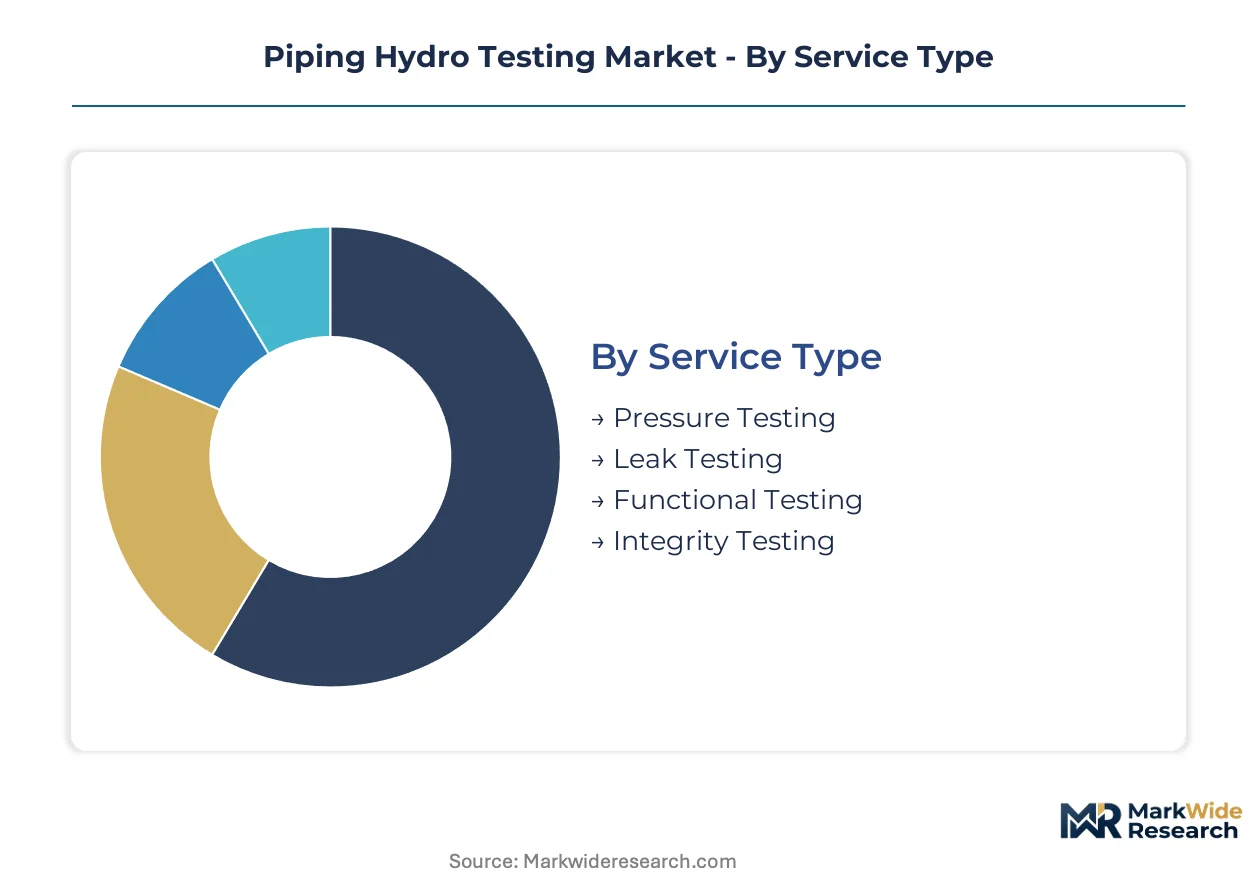
Segmentation in piping hydro testing reveals how service providers must configure capabilities around divergent technical requirements and regulatory exposures. Each dimension—service type, technology, application, and end user—carries distinct margin profiles and capital intensity thresholds that shape competitive positioning.
Service Type:
Pressure testing services face the most acute substitution threat from ultrasonic alternatives, forcing providers to defend value through integrated certification workflows rather than standalone hydraulic execution.
- Pressure Testing:Water-filled pressurization to 1.5 times design pressure validates weld integrity and flange sealing before hydrocarbon service. Demand concentrates along the United States Gulf Coast petrochemical corridor where ASME B31.3 mandates dominate procurement specifications.
- Leak Testing:Helium mass spectrometry and bubble emission methods detect micro-leakage below conventional pressure decay thresholds. Offshore platform operators in the Gulf of Mexico deploy these protocols for subsea manifold qualification where fluid discharge constraints eliminate hydraulic alternatives.
- Functional Testing:Operational verification of control valves, safety relief devices, and emergency shutdown systems under simulated process conditions.
- Integrity Testing:Risk-based inspection intervals mandated by API 570 for in-service piping systems, combining ultrasonic thickness measurement with fitness-for-service assessment.
Pressure testing anchors the volume base while integrity testing gains share at the steepest rate as operators extend asset life cycles through predictive maintenance programs.
Technology:
Cost tier stratification separates capital-intensive automated systems from labor-dependent manual methods, with mid-market contractors caught between equipment investment requirements and technician wage compression.
- Hydraulic Testing:Conventional water-glycol pressurization using positive displacement pumps and manual gauge verification. Cross-country transmission pipelines in arid regions face EPA discharge permit constraints that elevate fluid handling costs.
- Ultrasonic Testing:Phased-array systems generate volumetric weld inspection data without dewatering operations. Norwegian North Sea operators have standardized these methods for platform tie-in campaigns where weather windows compress execution schedules.
- Pneumatic Testing:Compressed gas pressurization restricted to low-hazard service classes due to stored energy safety constraints.
- Electric Testing:Electromagnetic acoustic transducers for corrosion mapping in insulated or buried piping where direct surface access is impractical.
Hydraulic testing retains the largest revenue footprint while ultrasonic methods climb the fastest as offshore project economics favor reduced cycle times over capital cost minimization.
Application:
Customer type concentration among integrated operators standardizes procurement terms across regional territories, compressing margin differentiation between application segments.
- Oil & Gas:Upstream gathering systems, midstream transmission pipelines, and downstream refinery units requiring API 5L and ASME B31.3 compliance. Pipeline and Hazardous Materials Safety Administration retest intervals directly schedule service demand for natural gas infrastructure.
- Chemical Processing:High-pressure reactor feed lines and heat exchanger bundles subject to EPA spill prevention frequency mandates. Texas and Louisiana bulk storage terminals have consolidated testing programs under multi-year framework agreements.
- Water Supply:Municipal distribution network pressure verification and treated water transmission main commissioning.
- Power Generation:Boiler feedwater piping, steam condensate systems, and cooling water circuits in combined-cycle facilities.
Oil and gas applications generate the highest contract values while chemical processing shows the steepest expansion trajectory as EPA regulations tighten testing intervals.
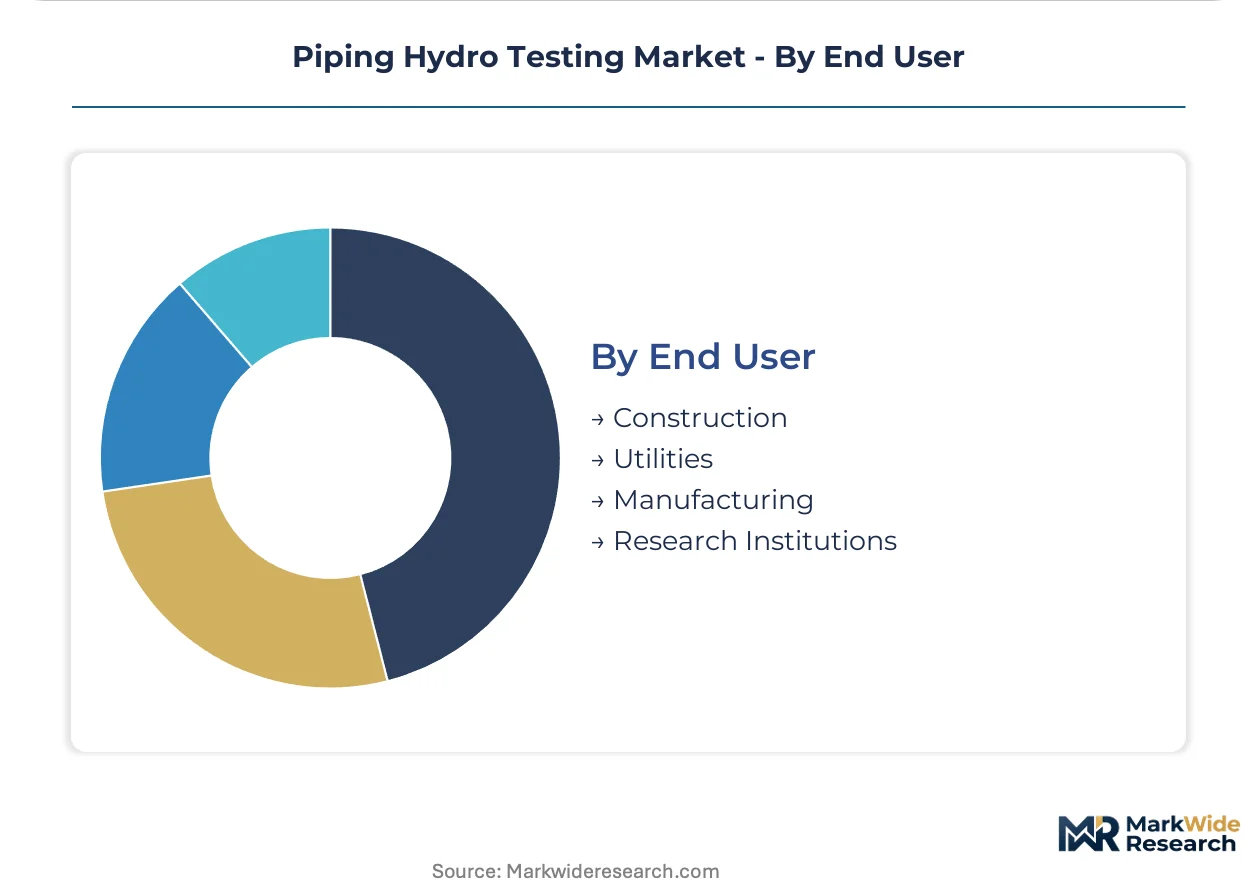
End User:
Supply concentration among supermajor producers centralizes procurement decisions at corporate headquarters, displacing locally negotiated spot arrangements that historically sustained independent contractors.
- Construction:Greenfield pipeline and process plant pre-commissioning campaigns requiring mobilization of portable testing equipment to remote sites. Alaskan North Slope liquefied natural gas developments concentrate demand for cold-climate qualified systems.
- Utilities:Regulated natural gas distribution operators subject to federal integrity management programs with mandated assessment frequencies.
- Manufacturing:In-house testing capabilities at integrated petrochemical complexes supplementing outsourced specialist services during turnaround cycles.
- Research Institutions:Protocol development for hydrogen blending compatibility and carbon capture pipeline materials qualification.
Construction end users anchor demand volume while research institutions represent the most rapidly expanding segment as novel energy infrastructure requires unproven testing parameters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States Gulf Coast corridor exhibit the lowest price sensitivity due to regulatory non-negotiability and concentrated petrochemical investment, while contractors in arid Middle Eastern markets face acute cost pressure from water sourcing logistics and discharge compliance burdens.
United States
Pipeline and Hazardous Materials Safety Administration retest mandates for natural gas transmission infrastructure generate recurring service demand concentrated along the Texas-Louisiana industrial belt. EPA spill prevention regulations tighten testing frequencies for above-ground chemical transfer lines at bulk storage terminals. Houston-area petrochemical complexes are consolidating testing programs under multi-year framework agreements with specialized contractors.
Germany
Industrial pipeline operators in the Rhine-Ruhr chemical corridor face REACH compliance obligations that elevate documentation requirements for integrity verification workflows. TÜV standards shape procurement specifications for process piping in downstream refinery applications. BASF's Ludwigshafen complex and Bayer's Leverkusen facilities anchor demand for automated pressure monitoring systems.
China
MIIT safety standards for high-pressure chemical service are expanding hydro testing program scope at coal-to-chemical complexes in Ningxia and Inner Mongolia. GB standards for pressure piping integrity create mandatory pre-commissioning requirements for new refinery capacity along the Bohai Rim. Sinopec's Zhenhai and Maoming facilities are deploying ultrasonic phased-array systems to compress turnaround schedules.
Saudi Arabia
SABIC's Jubail Industrial City operations and Saudi Aramco's Ras Tanura refinery generate concentrated demand for API-compliant testing services during major turnaround cycles. The national oil company's integrity management programs mandate risk-based inspection intervals that directly schedule contractor deployment. NEOM development projects are creating novel demand for portable testing equipment qualified for remote desert construction sites.
Canada
TransCanada's natural gas transmission network and oil sands steam-assisted gravity drainage operations in Alberta drive demand for cold-climate qualified testing systems. Health Canada and provincial regulators enforce hydrostatic retest intervals for interprovincial pipelines under federal jurisdiction. Edmonton-area fabrication shops and Calgary-based engineering contractors anchor the service provider ecosystem for western Canadian energy infrastructure.
Piping Hydro Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with inspection laboratories and certification bodies commanding premium positioning through integrated compliance workflows while regional equipment rental firms compete on mobilization speed and labor arbitrage. The market structure tiers between global multi-service conglomerates with accredited laboratory networks and specialized contractors focused on single-site execution. Three archetypes dominate: asset-light certification specialists, capital-intensive equipment fleet operators, and integrated turnaround service providers. Competitive moves concentrate on strategic partnerships between ultrasonic technology developers and established inspection firms, plus geographic expansion through acquisition of regional hydro testing contractors.
Within the certification-specialist tier, SGS SA and Bureau Veritas exemplify the integrated laboratory-network model that anchors upstream and midstream project workflows. Hydratight occupies a position among equipment-focused operators with portable tensioning and testing capabilities deployed at remote construction sites. These three entities represent distinct competitive vectors: compliance documentation depth, field execution flexibility, and equipment technology control.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group |
| Bureau Veritas |
| Hydratight |
| Applus+ |
| TÜV Rheinland |
| Compressor Engineering Corp. |
| EnerMech |
| Milbar Hydro-Test, Inc. |
| Others |
Value Network & Pricing Analysis
ASME B31.3 certification tiers simultaneously gate supplier qualification and stratify contract pricing, with accredited laboratories commanding premium positioning over uncertified regional operators while procurement centralization among Gulf Coast supermajors compresses margin differentiation across the service tier.
Pricing Analysis
Multi-year framework agreements anchor lifetime value for pressure testing providers, with three-tier pricing structure across premium, standard, and economy levels separating API-compliant certification workflows from basic hydraulic execution. Price differentiation rests on technician qualification depth and digital monitoring system integration, with ultrasonic phased-array operators capturing margin premiums over manual gauge services. Pricing pressure stems from buyer concentration among integrated operators standardizing procurement terms across the Texas-Louisiana corridor. Independent contractors exhibit highest price sensitivity due to equipment capital intensity, while certification specialists maintain lowest sensitivity through compliance documentation depth.
Supply Chain Analysis
United States and Germany anchor precision pressure transducer manufacturing, with China producing positive displacement pumps and portable testing skids at scale. Equipment fleets draw from German sensor technology, Chinese pump assemblies, and North American data acquisition hardware. Supply chain risk centers on single-source vulnerability for phased-array ultrasonic probes used in offshore applications. Distribution runs through specialized industrial service contractors and integrated turnaround providers, with direct OEM relationships penetrating supermajor procurement panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the petrochemical capital expenditure cycle, with ASME B31.3 mandate expansions signaling recovery-phase entry as integrity verification frequencies tighten across existing infrastructure.
For Market Incumbents: Secure multi-year framework agreements with Gulf Coast supermajors before procurement centralization completes, while acquiring ultrasonic technician capabilities to defend against phased-array substitution. Backward integration into pressure transducer distribution hedges equipment cost volatility. Certification portfolio breadth across ASME B31.3, API 570, and ISO 19840 creates switching costs for buyers consolidating vendor panels.
For New Entrants and Emerging Players: API 570 fast-track certification opens access to integrity testing contracts at chemical manufacturing clusters in Texas and Louisiana where incumbent capacity constraints create execution gaps. Target portable equipment deployment at remote Arctic LNG developments and NEOM desert construction sites where mobilization speed outweighs brand recognition. Partner with ultrasonic technology developers to bypass capital-intensive hardware ownership.
For Investors and Strategic Acquirers: EPA spill prevention regulation expansion reshapes the acquisition landscape by mandating shortened testing intervals for above-ground chemical transfer lines, extending contract visibility for specialized providers. Mid-cap certification specialists with accredited laboratory networks represent prime targets as corporate procurement centralization favors integrated compliance workflows. Watch hydrogen blending compatibility protocol development as the inflection signal for materials testing demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Phased-Array Technology Acquisition | Phased-array systems eliminate dewatering costs for Norwegian North Sea platform operators. |
| Multi-Year Framework Agreement Consolidation | Houston-area petrochemical complexes are consolidating testing programs under specialized contractors. |
| Portable Equipment Cold-Climate Qualification | Alaskan North Slope LNG developments concentrate demand for Arctic-qualified testing systems. |
| Carbon Capture Pipeline Protocol Development | CO2 transport networks in the United States require novel dense-phase testing parameters. |
| Digital Pressure Monitoring Platform Integration | Wireless transducer networks reduce personnel exposure during Gulf of Mexico high-pressure phases. |
Research Methodology
Initial hypotheses were tested against primary input from integrity management directors, turnaround procurement leads, ultrasonic testing technicians, and certification body auditors and refined through secondary validation against Pipeline and Hazardous Materials Safety Administration enforcement data, ASME interpretation bulletins, EPA spill prevention compliance records, and SEC filings from listed inspection firms. Bottom-up service provider revenue aggregation and top-down infrastructure investment flow analysis were cross-referenced for triangulation.
Variance decomposition across service type, technology tier, application vertical, and end-user category shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand modeling calibrated to regulatory mandate schedules and capital project pipelines. Forecast inputs incorporated PHMSA retest interval enforcement patterns and ultrasonic adoption curves from North Sea operator standardization.
Decision-makers should treat outputs as directional under assumptions of sustained ASME B31.3 integrity mandate expansion and stable petrochemical capital allocation; material deviation in regulatory enforcement intensity or upstream investment cycles would warrant model refresh. Recalibration cycles align with material shifts in EPA spill prevention frequency mandates and hydrogen infrastructure deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
China Material Testing Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
US Eddy-Current Testing Market