
 Ultrasonic Testing Market | 2026-2036
Ultrasonic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Testing Market Intelligence
A transition from outsourced inspection services toward developing in-house testing capabilities is shifting procurement patterns for ultrasonic equipment. MISTRAS Group sustains its market position by offering integrated service and technology solutions for asset protection. In contrast, Eddyfi Technologies specializes in the development of advanced NDT instruments and software. Baker Hughes Company leverages its extensive energy sector presence to deploy ultrasonic solutions for pipeline and infrastructure integrity assessments.
Ultrasonic testing is a non-destructive testing method that utilizes high-frequency sound waves, typically in the 0.1 to 15 MHz range, to characterize material properties or detect internal flaws. These sound waves are introduced into a material and the resulting echoes are analyzed to create a detailed image of the material's internal structure. Phased Array Ultrasonic Testing systems represent a high-growth product category, offering superior imaging and data collection. Within applications, weld inspection remains a foundational use case, while composite inspection is expanding rapidly in the aerospace and automotive sectors.
International standards, such as ISO 17640 for the testing of welds, establish global quality benchmarks for ultrasonic procedures. In the United States, the FAA mandates stringent NDT protocols for critical aerospace components, driving equipment sales. European directives concerning pressure equipment and pipeline safety also necessitate regular inspections using ultrasonic methods. The choice between adopting advanced techniques like Time of Flight Diffraction versus conventional pulse-echo methods will determine future operational efficiency for asset owners.
Market Dynamics
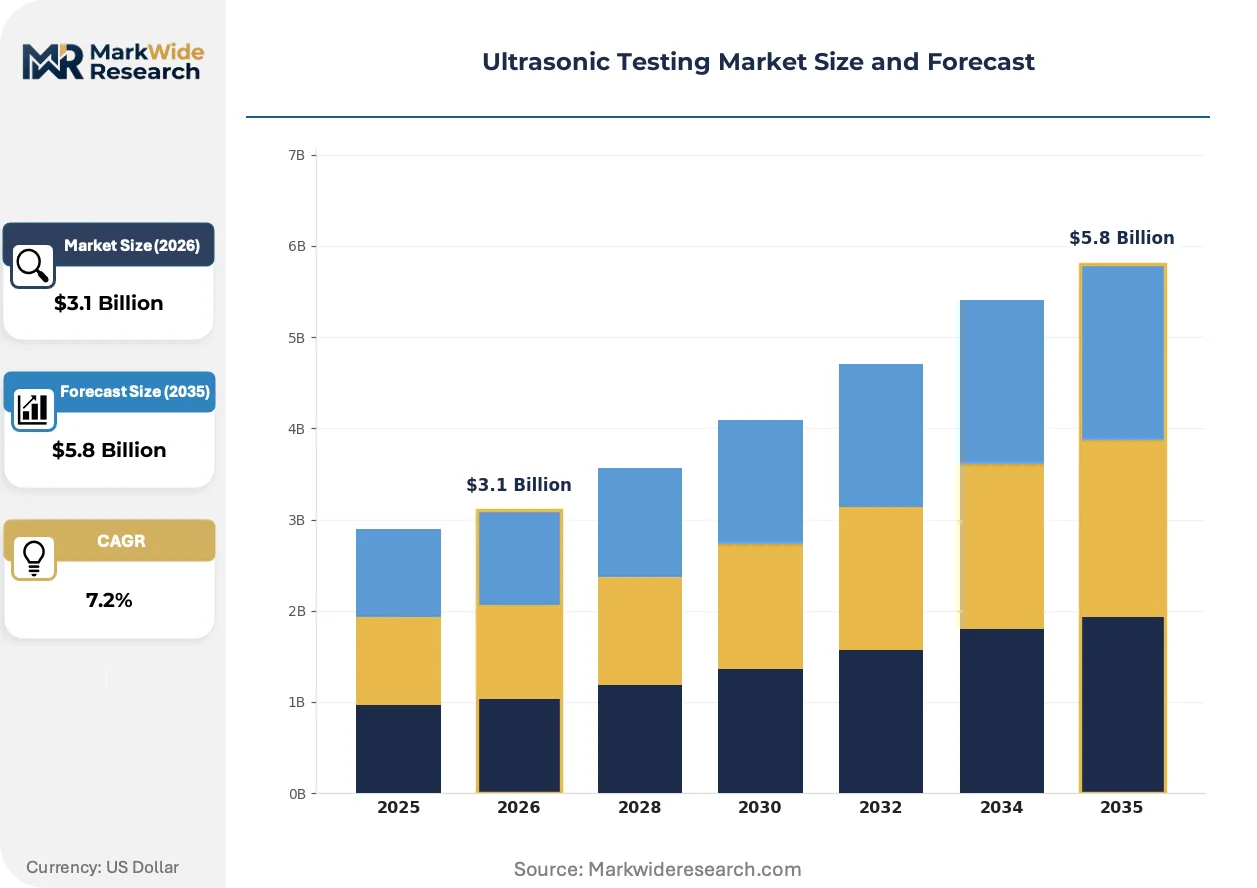
The market's central dynamic is the tension between outsourced service models and the growing trend of asset owners developing in-house testing capabilities. This shift alters equipment procurement patterns and elevates demand for user-friendly, advanced systems like Phased Array Ultrasonic Testing.
Growth Catalysts
- Aerospace Composites:Demand from aerospace manufacturers for lightweight composite structures in fuselages and wings requires advanced ultrasonic methods for detecting delamination, porosity, and other manufacturing defects.
- Regulatory Mandates:International standards like ISO 17640 for weld testing and FAA requirements for critical component inspection create a non-discretionary need for ultrasonic testing equipment and certified personnel.
- Infrastructure Integrity:Aging public infrastructure, including bridges, railways, and pipelines in developed economies, necessitates regular non-destructive evaluation to ensure public safety and prevent catastrophic failures.
Market Restraints
- High Capital Investment:The initial acquisition cost for advanced systems, particularly Phased Array Ultrasonic Testing (PAUT) and Time of Flight Diffraction (TOFD) equipment, presents a significant financial barrier for smaller service companies and manufacturers.
- Material Limitations:Conventional ultrasonic testing is less effective on highly attenuative or coarse-grained materials, such as certain cast irons and composites, which can scatter the sound beam and obscure defects.
- Alternative NDT Methods:In certain applications, particularly for surface crack detection or thin materials, alternative methods like magnetic particle testing, liquid penetrant testing, or eddy current testing offer a more cost-effective solution.
Strategic Opportunities
- Additive Manufacturing Inspection:The expansion of 3D printing in industrial production creates a new market for specialized ultrasonic techniques to qualify part integrity and detect unique flaws inherent to the layering process.
- AI-Powered Defect Recognition:Integrating artificial intelligence and machine learning algorithms with ultrasonic data can automate defect detection, reducing reliance on operator skill and improving the consistency and speed of inspections.
- Untapped Geographic Markets:Rapid industrialization and infrastructure development in regions like Southeast Asia and Latin America present significant growth opportunities for ultrasonic testing equipment and service providers.
Industry Challenges
- Skilled Technician Scarcity:A global shortage of certified Level II and Level III NDT technicians, who are qualified to perform and interpret complex ultrasonic tests, constrains service capacity and drives up labor costs.
- Data Management Burden:Advanced techniques like PAUT and Full Matrix Capture generate vast amounts of data per inspection, creating challenges related to data storage, transfer, and analysis for asset owners and service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Testing Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.8 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasonic Flaw Detectors, Conventional Ultrasonic Flaw Detectors, Phased Array Ultrasonic Testing Systems, Time of Flight Diffraction Instruments Technology: Pulse-Echo, Through Transmission, Phased Array, Time of Flight Diffraction, Electromagnetic Acoustic Transducers Application: Weld Inspection, Corrosion Monitoring, Thickness Measurement, Composite Inspection, Forging Inspection End User: Oilfield Service Providers, Aerospace Manufacturers, Power Generation Companies, Metal Fabricators, Construction Firms |
| Companies Covered | Eddyfi Technologies, MISTRAS Group, Baker Hughes Company, Zetec Inc, NDT Systems Inc, EVIDENT Corporation, Sonatest Ltd, DEKRA SE, Waygate Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Testing Market Strategic Shifts & Innovations
The evolution of ultrasonic testing is defined by a push toward greater automation and data-driven decision-making. Innovations focus on improving imaging resolution, simplifying operator workflows, and integrating inspection data into broader asset integrity management platforms for predictive maintenance.
Full Matrix Capture (FMC) and the associated Total Focusing Method (TFM) are advanced data acquisition and processing techniques that generate high-resolution images from raw ultrasonic signals. Aerospace and nuclear power sectors are adopting this technology for critical inspections where flaw characterization is paramount. FMC/TFM is electrifying the inspection of complex geometries and welds by providing near-radiographic image quality without the associated radiation hazards.
European Union directives, particularly the Pressure Equipment Directive (PED), impose strict safety and performance requirements on manufacturers and operators of pressurized systems. This regulation mandates rigorous non-destructive testing to verify material integrity and weld quality during both manufacturing and in-service phases. The oil and gas, chemical, and power generation industries across Europe are most affected, driving consistent demand for compliant ultrasonic testing solutions.
A notable behavioral change involves asset owners bundling inspection services into broader, long-term asset integrity management (AIM) contracts. This model displaces traditional, transactional procurement of one-off inspection jobs with integrated partnerships that include data analysis and maintenance planning. This shift is particularly visible within the North American oil and gas sector, where operators use this approach to optimize asset performance and extend operational life.
Ultrasonic Testing Market Segmentation
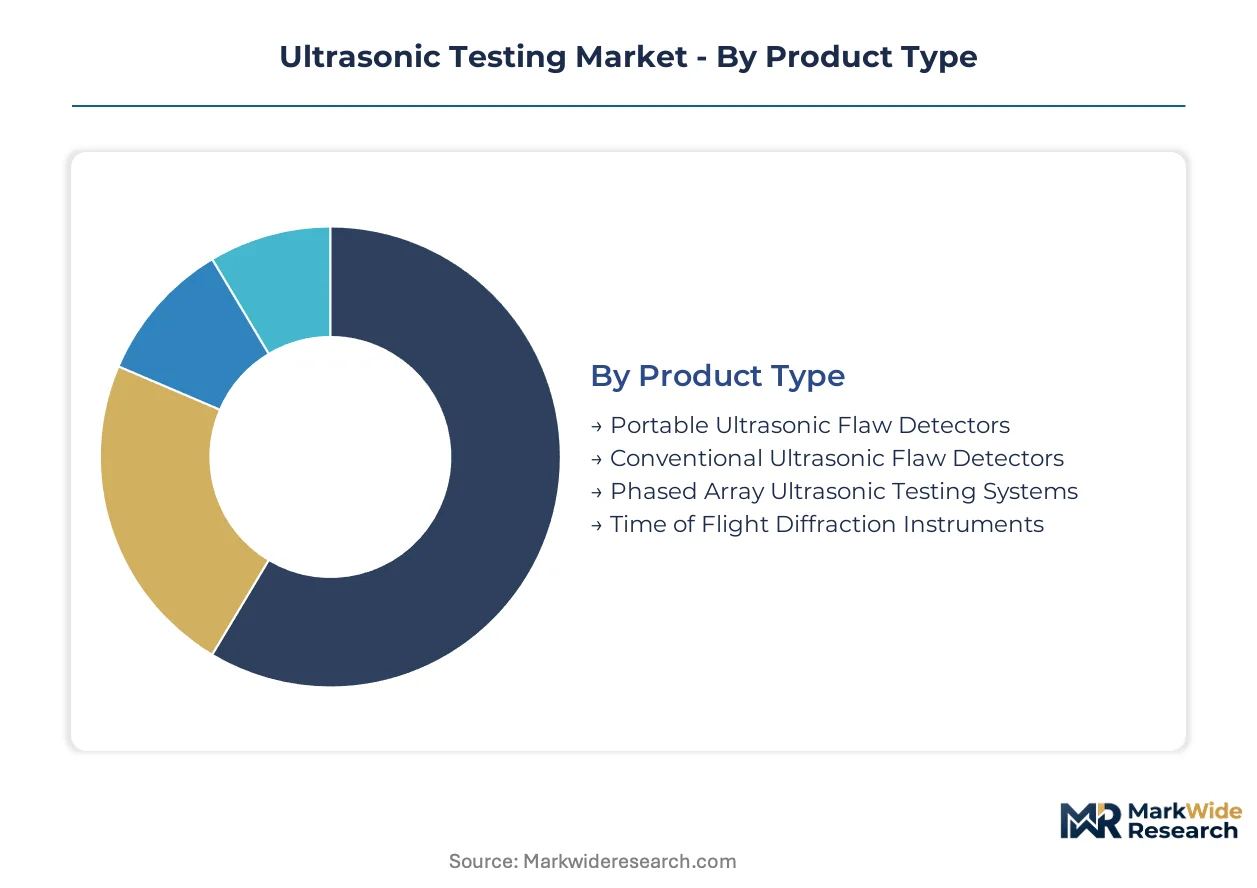
The Ultrasonic Testing Market's segmentation reveals diverse product types, technologies, applications, and end-user requirements. Understanding these distinct categories allows for targeted development and deployment of inspection solutions. This detailed analysis highlights areas of concentrated investment and emerging technological preferences across various industrial landscapes.
Product Type:
The capital intensity of ultrasonic testing equipment varies significantly, influencing procurement strategies across industries.
- Phased Array Ultrasonic Testing Systems:These advanced systems employ multiple transducers to steer and focus ultrasonic beams electronically, generating detailed cross-sectional images. Demand concentrates in the aerospace and power generation sectors for inspecting complex geometries and critical components, driven by stringent safety regulations.
- Time of Flight Diffraction Instruments:TOFD systems precisely measure diffraction signals from flaw tips to accurately size defects, particularly in welds. The energy sector, especially for pipeline integrity assessments, relies on TOFD for its superior sizing capabilities and high probability of detection.
- Portable Ultrasonic Flaw Detectors:These handheld devices provide basic flaw detection and thickness measurement capabilities for field use.
- Conventional Ultrasonic Flaw Detectors:Standard single-element transducer systems offer versatile, cost-effective inspection for a wide range of materials and simple geometries.
Most installed capacity flows through Conventional Ultrasonic Flaw Detectors. Expansion is steepest in Phased Array Ultrasonic Testing Systems.
Technology:
Different ultrasonic technologies cater to specific inspection challenges, optimizing defect detection and material characterization for varied applications.
- Phased Array:This technology uses multiple ultrasonic elements pulsed independently to create steerable and focusable beams, enabling precise flaw imaging and sizing. Aerospace manufacturers utilize phased array for inspecting composite structures and complex metallic components, enhancing defect characterization.
- Time of Flight Diffraction:TOFD technology measures the time difference of diffracted ultrasonic waves from defect edges, providing accurate through-wall sizing of discontinuities. Weld inspection in the oil and gas industry frequently employs TOFD for its reliability in detecting and characterizing planar defects.
- Pulse-Echo:This foundational method transmits a single ultrasonic pulse and analyzes the returning echoes to locate discontinuities and measure thickness.
- Through Transmission:The through-transmission technique involves placing a transmitter and receiver on opposite sides of a material to detect internal defects that attenuate the sound beam.
- Electromagnetic Acoustic Transducers:EMATs generate ultrasonic waves in materials without direct contact, suitable for hot surfaces or inspections requiring no couplant.
The foundational Pulse-Echo technique underpins broad industrial use, while advanced Phased Array methods unlock new inspection capabilities.
Application:
The prevalence of ultrasonic testing applications reflects critical safety and quality assurance requirements across heavy industries.
- Weld Inspection:This application utilizes ultrasonic waves to detect discontinuities like cracks, porosity, and inclusions within welded joints, ensuring structural integrity. Regulatory bodies like ISO 17640 mandate rigorous weld testing in construction and manufacturing, driving consistent equipment demand.
- Composite Inspection:Ultrasonic methods characterize internal structures of composite materials, identifying delaminations, voids, and fiber misalignment critical for performance. Aerospace manufacturers heavily rely on composite inspection for lightweight airframe components, ensuring flight safety and material quality.
- Corrosion Monitoring:Ultrasonic thickness measurements track material degradation over time, preventing catastrophic failures in pipes and pressure vessels.
- Thickness Measurement:Precise ultrasonic thickness gauges determine material thickness, crucial for quality control and wear assessment in various manufacturing processes.
- Forging Inspection:Ultrasonic testing identifies internal flaws such as cracks, voids, and inclusions in forged components, ensuring their mechanical reliability.
Traditional Weld Inspection applications ensure foundational structural integrity, as new material challenges in Composite Inspection drive demand for specialized protocols.
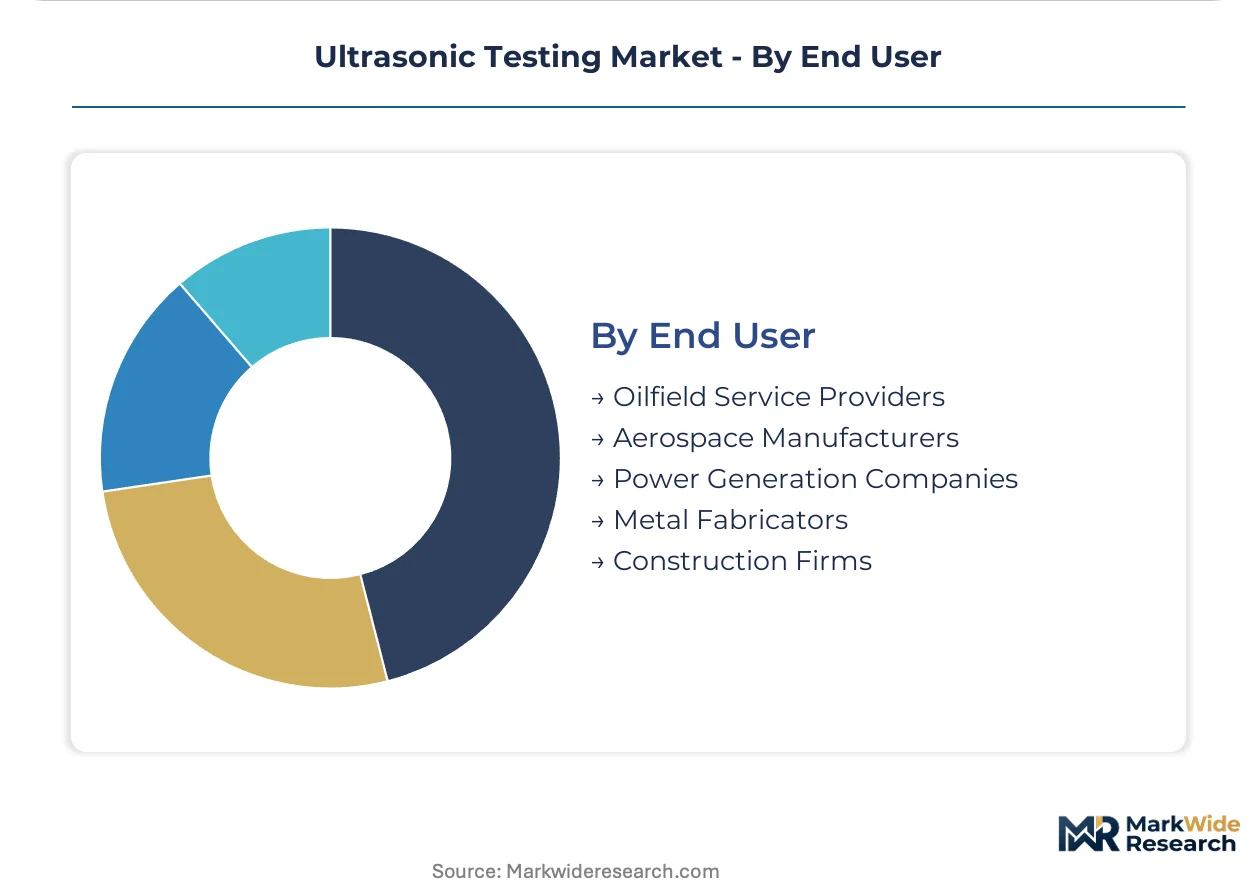
End User:
End-user segments are differentiated by the criticality of assets and the stringency of regulatory compliance in their respective operations.
- Aerospace Manufacturers:These entities require highly accurate ultrasonic testing for critical components like airframes, engine parts, and landing gear to detect minute flaws. The FAA mandates stringent NDT protocols for aerospace components, necessitating advanced equipment and certified personnel.
- Power Generation Companies:Operators in this sector use ultrasonic testing to inspect turbines, boilers, and piping systems, ensuring reliable and safe plant operation. European directives concerning pressure equipment and pipeline safety necessitate regular inspections to prevent failures.
- Oilfield Service Providers:These companies deploy ultrasonic solutions for pipeline integrity, wellhead inspection, and subsea asset evaluation in challenging environments.
- Metal Fabricators:Fabricators utilize ultrasonic testing for quality control of raw materials, castings, and finished products, ensuring compliance with manufacturing standards.
- Construction Firms:Construction firms employ ultrasonic testing for structural steel, concrete, and bridge components to verify integrity and adherence to building codes.
Industrial sectors with high safety compliance, such as Aerospace Manufacturers, drive consistent demand, while infrastructure development creates new opportunities for Construction Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ultrasonic testing market demonstrates varied regional dynamics, with procurement patterns often influenced by regulatory frameworks and the criticality of industrial assets. Production sometimes migrates to areas with less stringent compliance costs, impacting equipment demand in different geographies.
United States
Demand from aerospace manufacturers for inspecting composite structures drives significant ultrasonic equipment procurement in the United States. The FAA mandates stringent NDT protocols for critical aerospace components, necessitating advanced testing solutions. Seattle's aerospace industry cluster consistently invests in advanced ultrasonic equipment and services.
Germany
Power generation companies and heavy manufacturers in Germany require precise ultrasonic testing for turbines, boilers, and critical infrastructure. European directives, particularly the Pressure Equipment Directive (PED), necessitate rigorous inspections for pressurized systems. North Rhine-Westphalia's industrial heartland frequently implements advanced ultrasonic solutions for quality assurance.
China
Rapid infrastructure development and expanding manufacturing capabilities generate substantial demand for ultrasonic testing equipment in China. GB standards for industrial equipment and construction materials promote widespread adoption of NDT methods. The Yangtze River Delta's manufacturing hubs are increasingly adopting advanced ultrasonic technologies for quality control.
India
The growing energy sector, particularly oil and gas, alongside large-scale construction projects, fuels demand for ultrasonic testing in India. BIS standards for materials and components require quality verification across numerous industries. Gujarat's industrial corridors actively invest in portable ultrasonic flaw detectors for field applications.
United Arab Emirates
Extensive oil and gas infrastructure and ambitious construction mega-projects drive the need for robust ultrasonic testing in the United Arab Emirates. MOHAP regulations for industrial safety and asset integrity necessitate regular inspection services. Dubai's construction sector frequently utilizes ultrasonic testing for structural integrity and material verification.
Ultrasonic Testing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced NDT solutions and integrated asset management platforms. The market exhibits a tiered structure, with a few large players offering comprehensive solutions alongside numerous specialized providers. Strategic archetypes include technology innovators, service-focused integrators, and niche application specialists. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification into software and data analytics.
Within the advanced technology archetype, Eddyfi Technologies, a Canadian-based company, exemplifies specialization in sophisticated NDT instruments and software development. MISTRAS Group, an Inc.-structured entity, represents the service-focused integrator model, offering comprehensive asset protection solutions. Baker Hughes Company, leveraging its extensive energy sector presence, anchors the deployment of ultrasonic solutions for large-scale infrastructure integrity assessments.
| Leading Market Players |
|---|
| Eddyfi Technologies |
| MISTRAS Group |
| Baker Hughes Company |
| Zetec Inc |
| NDT Systems Inc |
| EVIDENT Corporation |
| Sonatest Ltd |
| DEKRA SE |
| Waygate Technologies |
| Others |
Cost & Logistics Intelligence
Skilled NDT technician availability, particularly in specialized Phased Array Ultrasonic Testing, directly influences service pricing and equipment procurement patterns. Labor-cost differentials therefore significantly contribute to pricing-tier spreads across different regional markets.
Pricing Analysis
Distributor margins and direct-to-OEM discounts establish foundational pricing for ultrasonic equipment. Project-based and transactional pricing models dominate for equipment sales and inspection services. Price differentiation stems from certification levels, such as ISO 17640 compliance, and the customization level required for advanced systems like PAUT. Pricing softness emerges from asset owners developing in-house capabilities, reducing reliance on external service providers. Smaller service companies exhibit the most price sensitivity, while aerospace manufacturers and power generation companies prioritize performance and compliance over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for ultrasonic testing equipment. Geographic supply concentration for advanced NDT instruments centers on countries like Germany, the United States, and Canada. The supply chain relies on critical raw materials and components, including specialized transducers, high-frequency electronic components, and proprietary software. Single-source vulnerability for advanced sensor arrays represents a structural supply chain risk. Distribution runs primarily through direct sales teams for major players and a network of specialized technical distributors for niche products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic testing market functions as a regulatory compounder, with demand consistently driven by mandates. FAA requirements for critical aerospace component inspection exemplify a key regulatory milestone fueling market expansion.
For Market Incumbents: Hedge against market disruption by integrating AI and machine learning algorithms into existing product lines, automating defect recognition. Acquire niche software development firms specializing in data analytics to counter the skilled technician scarcity. Invest in R&D for advanced material inspection, particularly for additive manufacturing, addressing the threat of alternative NDT methods for new applications.
For New Entrants and Emerging Players: Specialized channel partners, such as NDT training institutes or equipment rental companies, offer accessible go-to-market avenues. Target white-space applications like additive manufacturing inspection or focus on untapped geographic markets in Southeast Asia. Develop user-friendly, portable Phased Array Ultrasonic Testing systems for smaller manufacturers and construction firms, representing the most penetrable segment.
For Investors and Strategic Acquirers: Technology integrators, especially those with existing NDT portfolios, are the most active acquirers in this space, seeking to expand capabilities. The long-term viability of the market rests on asset integrity management platforms and predictive maintenance integration. Target acquisition archetypes include AI/ML software firms specializing in defect recognition and developers of advanced sensor technologies. Increased adoption of fully automated inspection robots serves as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI/ML for Defect Recognition | Automates flaw detection, reducing reliance on operator skill and improving inspection consistency. |
| Develop Advanced Composite Inspection Solutions | Addresses complex material challenges in aerospace and automotive sectors, expanding application scope. |
| Expand Certified Technician Training Programs | Mitigates the global scarcity of skilled NDT personnel, supporting service capacity. |
| Acquire Niche Software Development Firms | Enhances data management and analysis capabilities, crucial for advanced ultrasonic techniques. |
| Target Emerging Industrial Regions | Captures growth from rapid industrialization and infrastructure development in Southeast Asia. |
Research Approach
Direct dialogue with NDT engineers, aerospace manufacturers, power generation operators, and equipment procurement managers provided qualitative grounding. This primary research combined with secondary validation from ISO standards, FAA regulations, company annual reports, and industry association publications. The approach utilized bottom-up data collection, triangulated with top-down market sizing for comprehensive analysis.
The analytical framework employed a bottom-up approach for detailed market sizing, validated through top-down analyses across the modeling period. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical data analysis and projected adoption rates of advanced technologies. Infrastructure spending and aerospace production forecasts served as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to global economic downturns, rapid technological obsolescence, and changes in regulatory enforcement. Forecasts reflect assumptions regarding continued industrial growth and regulatory adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Durometers Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
Chemical Detector Market
Testing Equipment
United States Material Testing Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Oxidation Stability Analyzer Market