
 Global Life Science and Chemical Instrumentation Market | 2026-2036
Global Life Science and Chemical Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Life Science and Chemical Instrumentation Market Foresight
Quartz and silicon carbide components are displacing traditional glass and metal in high-performance optical and fluidic subsystems, is recalibrating cost structures across spectrometer and chromatograph manufacturing. Thermo Fisher Scientific Inc. leverages its captive supply of precision optics to control lead times for mass spectrometry platforms. Danaher Corporation anchors its competitive position through vertical integration into consumables that lock in recurring revenue streams alongside instrument placements.
Life science and chemical instrumentation encompasses analytical and measurement systems operating at detection limits ranging from parts-per-billion to single-molecule resolution, employing ionization sources, monochromators, and thermal sensors to quantify molecular composition and material structure. These systems serve regulatory compliance, research discovery, and process control across pharmaceutical, environmental, and industrial laboratories. Chromatographs and spectrometers command the largest installed bases, while mass spectrometry segments capture premium pricing through higher sensitivity specifications and software-locked method libraries. Microscopes and titrators occupy more mature demand curves with replacement-driven purchasing patterns rather than capacity expansion cycles.
FDA method validation guidelines, EPA analytical protocol requirements, and REACH substance detection mandates collectively elevate minimum performance thresholds and documentation standards for instrument vendors. ISO 17025 accreditation pressures push end users toward platforms with embedded compliance reporting rather than configurable open systems. Stakeholders must weigh capital deployment timing against evolving regulatory deadlines for PFAS monitoring and cell therapy release testing that will reshape instrument specification requirements.
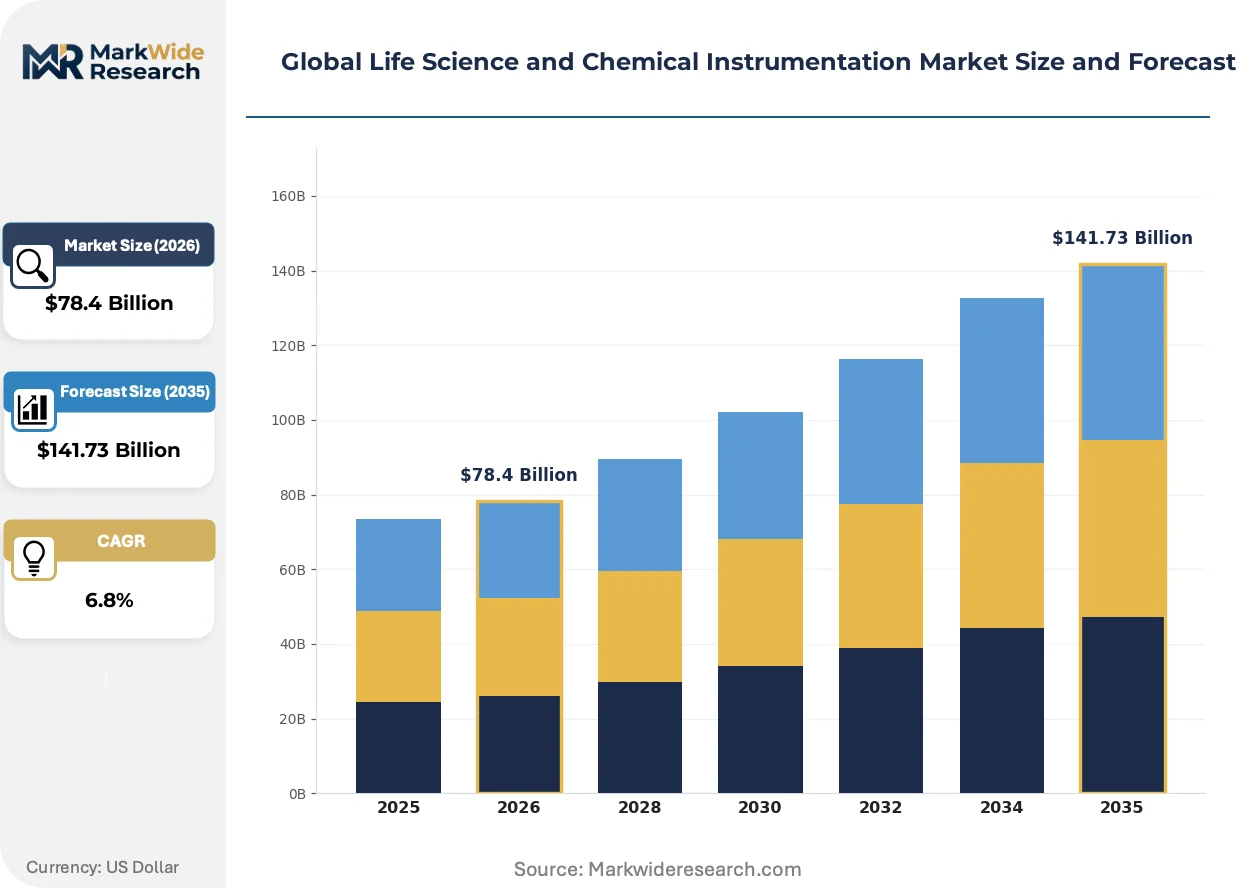
Market Dynamics
Pharmaceutical manufacturers in the United States, Germany, and China are accelerating capital deployment toward biologics quality control infrastructure, compressing instrument replacement cycles from seven years toward five-year refresh rates. This demand concentration is reshaping vendor capacity allocation and regional service network density.
Growth Catalysts
- Biologics manufacturing expansion:Cell therapy and monoclonal antibody production facilities in Massachusetts and Bavaria are driving mass spectrometry platform procurement for release testing protocols.
- REACH substance detection mandates:ECHA's evolving requirements for PFAS monitoring are elevating minimum sensitivity specifications across chromatograph installations in European environmental laboratories.
- Quartz and silicon carbide adoption:These materials in optical subsystems are enabling single-molecule resolution in next-generation spectrometers for proteomics research.
Market Restraints
- Helium supply volatility:Gas chromatography operations face input cost pressure from concentrated helium sourcing through the US Federal Helium Reserve and Algerian state suppliers.
- Precision optics fabrication bottleneck:German and Japanese specialty glass manufacturers control critical substrate supply for high-performance monochromators.
- ISO 17025 accreditation burden:Documentation requirements for embedded compliance reporting extend sales cycles by four to eight months for open-system vendors.
Strategic Opportunities
- India biopharma manufacturing:CDSCO's expanding oversight of biosimilar production is creating demand for analytical method validation infrastructure in Hyderabad and Bangalore clusters.
- AI-integrated spectral analysis:Machine learning convergence with mass spectrometry data processing is opening premium pricing tiers for automated compound identification.
- Consumables lock-in models:Reagent and column subscription programs are capturing recurring revenue alongside capital instrument placements in contract research organizations.
Industry Challenges
- Field service engineer scarcity:Ion source maintenance and vacuum system troubleshooting require specialized training that outpaces technical education pipeline output.
- Legacy LIMS integration friction:Open-architecture instruments face protocol mismatch with decades-old laboratory information management systems in government environmental labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Life Science and Chemical Instrumentation Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Chromatographs, Microscopes, Titrators, Calorimeters Technology: Mass Spectrometry, Liquid Chromatography, Gas Chromatography, Atomic Absorption, UV-Visible Spectroscopy Application: Pharmaceutical Analysis, Environmental Testing, Food Quality Control, Petrochemical Testing, Material Science Research End User: Pharmaceutical Manufacturers, Academic Institutions, Contract Research Organizations, Petrochemical Firms, Food & Beverage Companies |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Agilent Technologies Inc., Waters Corporation, Shimadzu Corporation, Becton, Dickinson and Company, PerkinElmer Inc., Bruker Corporation, Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Life Science and Chemical Instrumentation Market Shifts & Advancements
Digitalization of analytical workflows is compressing the gap between raw detection and regulatory-ready documentation, forcing vendors to embed compliance logic directly at the instrument level rather than through downstream software layers.
Silicon carbide optical components are rewriting thermal stability benchmarks for infrared spectrometers operating in process control environments. Pharmaceutical manufacturers in Basel and Boston are specifying these subsystems for continuous manufacturing monitoring. The technology is compressing calibration drift windows from quarterly to semi-annual intervals.
REACH authorization procedures for analytical reference materials are tightening supply chain provenance requirements across European testing laboratories. Vendors must now document full manufacturing genealogy for certified standards used in PFAS quantification. German environmental agencies are driving fastest adoption of blockchain-traceable reagent lots.
Consolidated procurement through group purchasing organizations is concentrating buyer power among the largest contract research and pharmaceutical testing networks. Independent distributors in secondary cities are losing share to direct vendor relationships. This pattern is most pronounced in the Research Triangle and San Diego biotech corridors.
Global Life Science and Chemical Instrumentation Market Segmentation
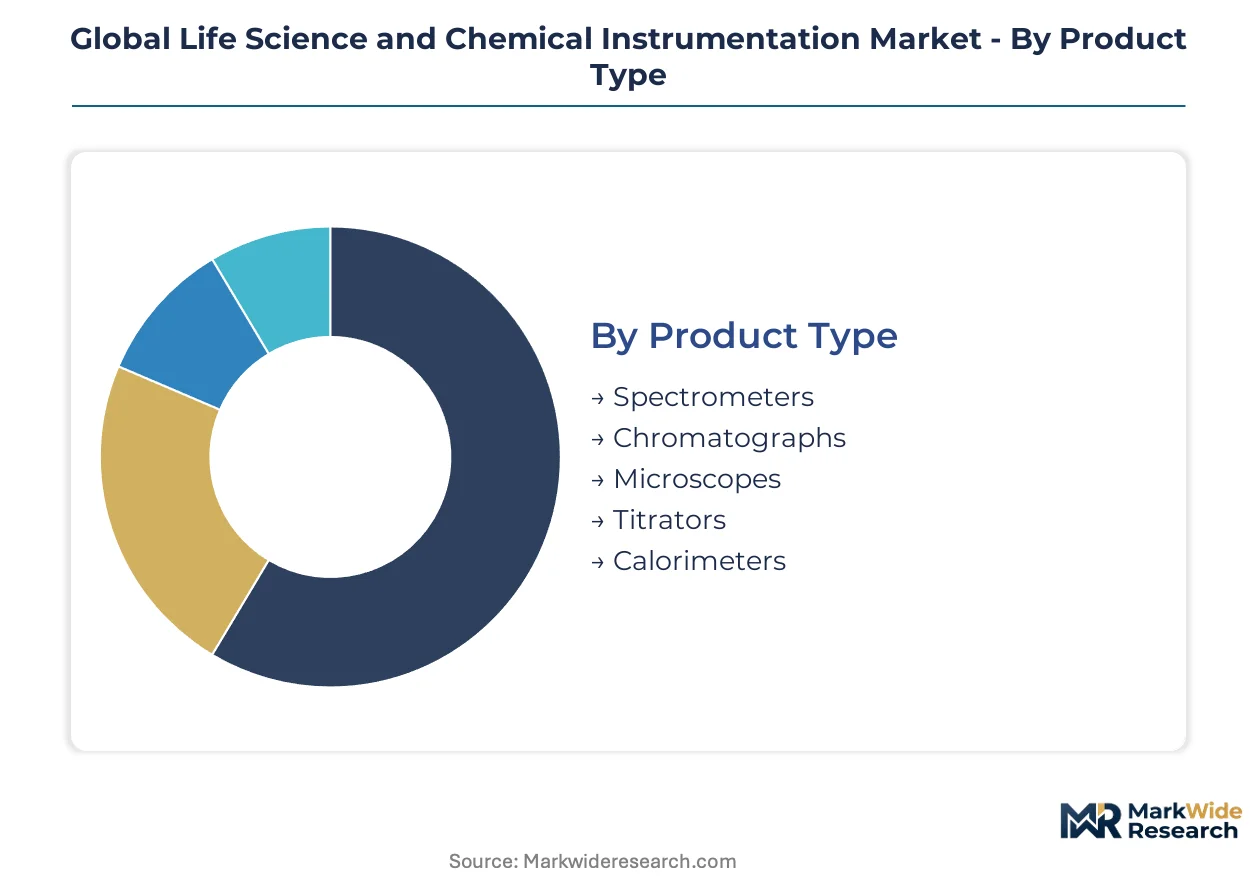
Instrumentation segmentation reveals how detection limits, throughput requirements, and regulatory documentation burdens fragment procurement decisions across laboratory environments. Vendors must configure platform architectures around these axes to avoid specification mismatches that extend sales cycles.
Product Type:
Detection sensitivity thresholds and optical subsystem complexity define tier boundaries across hardware categories.
- Spectrometers:These platforms span UV-visible through infrared configurations, with Fourier-transform infrared systems commanding premium positioning for polymer identification in petrochemical laboratories. Massachusetts and Bavaria biopharma clusters are driving ultraviolet-visible platform procurement for monoclonal antibody characterization.
- Chromatographs:Liquid and gas variants separate mixtures through differential partitioning, with ultra-high-performance liquid chromatography systems capturing dominant share in pharmaceutical quality control workflows. REACH PFAS monitoring mandates in German environmental agencies are accelerating high-resolution gas chromatograph replacement cycles.
- Microscopes:Optical and electron configurations serve morphological analysis with longer replacement intervals driven by capital budget cycles rather than specification obsolescence.
- Titrators:Automated potentiometric and Karl Fischer systems handle routine quantitative analysis in food safety and industrial quality laboratories.
- Calorimeters:Differential scanning and isothermal titration calorimeters quantify thermal transitions and binding energetics in biophysical characterization workflows.
Chromatographs lead on scale; spectrometers lead on momentum.
Technology:
Capital intensity and consumables attachment rates stratify vendor profitability across methodological approaches.
- Mass Spectrometry:Ion trap and quadrupole time-of-flight architectures achieve parts-per-billion detection for proteomics and metabolomics applications. Cell therapy release testing protocols at Basel and Boston manufacturing sites are specifying triple-quadrupole platforms with embedded FDA method validation libraries.
- Liquid Chromatography:Reverse-phase and hydrophilic interaction columns separate polar and nonpolar analytes with gradient elution programming. Hyderabad and Bangalore CDSCO-registered biosimilar facilities are expanding ultra-high-performance system procurement for analytical method validation infrastructure.
- Gas Chromatography:Capillary column systems with flame ionization or mass-selective detection handle volatile organic compound quantification. Helium supply volatility through US Federal Helium Reserve and Algerian state suppliers is forcing hydrogen carrier gas retrofits in European environmental laboratories.
- Atomic Absorption:Flame and graphite furnace configurations quantify trace metal content in drinking water and pharmaceutical raw materials.
- UV-Visible Spectroscopy:Single-beam and diode-array systems provide routine concentration measurements with lowest capital entry points across all detection technologies.
Liquid chromatography dominates installed base; mass spectrometry climbs the fastest on biologics manufacturing expansion.
Application:
Regulatory deadline density and documentation stringency create divergent purchasing urgency across vertical markets.
- Pharmaceutical Analysis:Method validation, stability testing, and release documentation for small molecules and biologics demand platforms with embedded compliance reporting. FDA evolving guidance on analytical method validation is elevating instrument performance requirements for Massachusetts and North Carolina manufacturing corridors.
- Environmental Testing:EPA analytical protocol requirements and ECHA REACH substance detection mandates drive sensitivity specification upgrades in water and soil monitoring laboratories. German environmental agencies are specifying blockchain-traceable reagent lots for PFAS quantification protocols.
- Food Quality Control:Pesticide residue and contaminant screening for import compliance and consumer safety.
- Petrochemical Testing:Hydrocarbon characterization and refinery process control with silicon carbide optical subsystems enabling continuous manufacturing monitoring.
- Material Science Research:Polymer characterization and nanomaterial structural analysis in academic and industrial R&D settings.
Pharmaceutical analysis leads on scale; environmental testing leads on momentum.
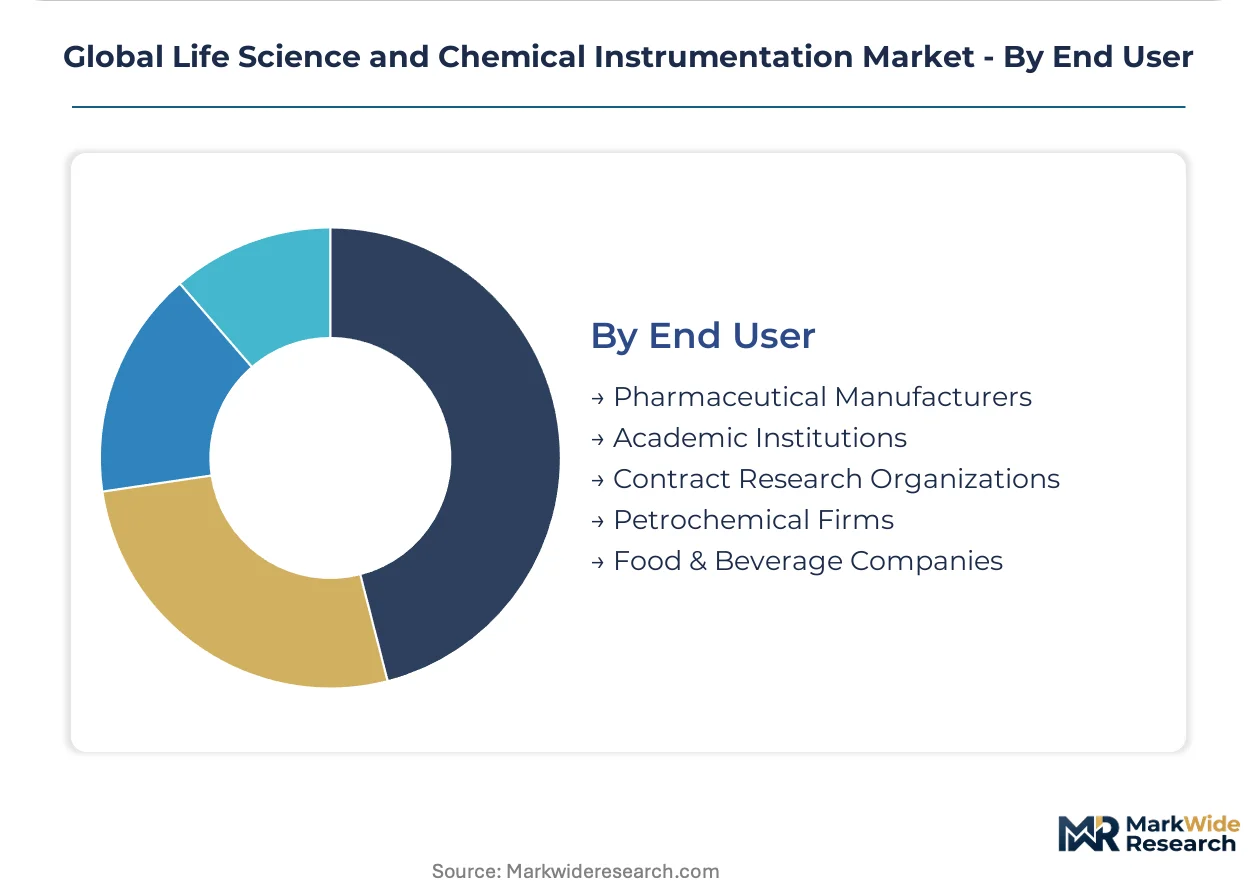
End User:
Procurement centralization and service contract structures differentiate customer economics across organizational types.
- Pharmaceutical Manufacturers:In-house quality control and release testing laboratories with compressed five-year refresh cycles replacing traditional seven-year replacement intervals. Consolidated procurement through group purchasing organizations is concentrating buyer power among largest testing networks.
- Academic Institutions:Research discovery instrumentation with grant-funded acquisition cycles and open-system preferences conflicting with ISO 17025 accreditation pressures.
- Contract Research Organizations:High-throughput screening and method development services with consumables lock-in models capturing recurring revenue alongside capital placements.
- Petrochemical Firms:Process control and product certification laboratories with thermal stability requirements driving silicon carbide optical component adoption.
- Food & Beverage Companies:Quality assurance and supplier verification testing with cost-sensitive procurement patterns.
Pharmaceutical manufacturers lead on scale; contract research organizations lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and Bavaria biopharma clusters command the highest instrument procurement velocity, with cell therapy manufacturing and monoclonal antibody production compressing replacement cycles toward five-year intervals. Regulatory deadline density varies sharply across jurisdictions, reshaping vendor capacity allocation and service network deployment.
United States
FDA evolving guidance on analytical method validation drives platform upgrades across Massachusetts and North Carolina manufacturing corridors. EPA analytical protocol requirements for PFAS monitoring elevate sensitivity specifications in environmental laboratories. The Research Triangle and San Diego biotech clusters concentrate consolidated procurement through group purchasing organizations, concentrating buyer power among contract research networks.
Germany
ECHA REACH substance detection mandates accelerate high-resolution chromatograph replacement cycles in environmental testing facilities. German environmental agencies specify blockchain-traceable reagent lots for PFAS quantification protocols, tightening supply chain provenance requirements. Bavaria biopharma manufacturing anchors mass spectrometry platform procurement for release testing, with Basel-Boston specifications migrating into regional quality control standards.
China
NMPA oversight expansion for biologics manufacturing elevates instrument performance requirements across Yangtze River Delta pharmaceutical clusters. Dual carbon goals and MEE environmental monitoring mandates drive spectrometer installations for industrial emissions compliance. Shanghai and Suzhou biopharma manufacturing sites specify ultra-high-performance liquid chromatography systems for biosimilar analytical method validation infrastructure.
India
CDSCO expanding oversight of biosimilar production creates demand for analytical method validation infrastructure in Hyderabad and Bangalore clusters. BIS standards alignment with ISO 17025 accreditation pressures push end users toward platforms with embedded compliance reporting. The Hyderabad-Bangalore pharmaceutical corridor accelerates ultra-high-performance system procurement as contract manufacturing organizations scale quality control capacity.
Japan
PMDA guidance on cell therapy release testing elevates triple-quadrupole platform specifications across Kanto region biopharma manufacturing. METI industrial technology roadmaps prioritize silicon carbide optical component adoption for process control thermal stability. Osaka and Nagoya petrochemical laboratories specify these subsystems for continuous manufacturing monitoring, compressing calibration drift intervals.
Global Life Science and Chemical Instrumentation Market Competitive Landscape
Global majors compete with regional champions across precision optics fabrication and consumables attachment models. The vendor base stratifies into three tiers: diversified conglomerates with captive supply chains, mid-scale specialists with geographic density advantages, and emerging players competing on price-sensitive configurations. Two dominant competitive moves define current positioning: backward integration into consumables manufacturing to capture recurring revenue, and strategic partnerships with biopharma manufacturers for co-development of method-locked platform libraries.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated archetype, leveraging in-house production of precision optics and consumables respectively to control lead times and lock in recurring revenue streams. Agilent Technologies Inc. occupies a position within the technology-specialist tier, with its geographic origin and corporate structure reflecting mid-century instrumentation heritage. These three entities represent distinct strategic postures: captive supply chain control, consumables lock-in economics, and platform-centric technology licensing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Waters Corporation |
| Shimadzu Corporation |
| Becton, Dickinson and Company |
| PerkinElmer Inc. |
| Bruker Corporation |
| Bio-Rad Laboratories Inc. |
| Others |
Supply & Pricing Matrix
Quartz and silicon carbide component adoption in optical subsystems is compressing manufacturing cost curves while concentrating precision optics supply among German and Japanese specialty substrate fabricators. This materials transition elevates performance thresholds for mass spectrometry platforms but tethered pricing power to captive supply chain control.
Pricing Analysis
Helium carrier gas cost pass-through from Algerian state suppliers and the US Federal Helium Reserve is intensifying pricing pressure across gas chromatography installations. Three-tier pricing structure across premium, standard, and economy levels separates triple-quadrupole mass spectrometry with embedded FDA method validation libraries from open-architecture configurations. Academic institutions exhibit highest price sensitivity due to grant-funded acquisition cycles, while pharmaceutical manufacturers absorb premium tiers for release testing compliance. Margins are tightening in the standard tier as consolidated procurement through group purchasing organizations concentrates buyer power among contract research networks.
Supply Chain Analysis
Instrument refurbishment and ion source remanufacturing flows are extending platform lifecycles in government environmental laboratories with legacy LIMS integration requirements. Critical substrate supply concentrates in Germany and Japan for precision monochromator optics, while helium sourcing draws from Algerian state suppliers and the US Federal Helium Reserve. Single-source vulnerability in specialty glass manufacturing creates lead time volatility for high-performance spectrometer production. Distribution runs through direct vendor relationships with consolidated procurement networks, displacing independent distributors in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH substance detection mandates and FDA evolving guidance on analytical method validation create procurement urgency that outpaces natural replacement cycles.
For Market Incumbents: Deepen backward integration into consumables manufacturing to capture recurring revenue streams alongside capital instrument placements. Lock in method-locked platform libraries through co-development partnerships with Basel and Boston biopharma manufacturers. Ion source maintenance service contracts represent a defensive moat against emerging players competing on price-sensitive configurations. For New Entrants and Emerging Players: Enter via Hyderabad and Bangalore CDSCO-registered biosimilar facilities where analytical method validation infrastructure demand outpaces established vendor service network density. Target contract research organizations with reagent and column subscription programs that bypass capital procurement committees. AI-integrated spectral analysis software licensing offers a go-to-market angle that sidesteps precision optics fabrication bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with geographic density advantages in India biopharma manufacturing clusters. Long-term viability hinges on consumables attachment rates rather than instrument shipment volumes. Watch for CDSCO enforcement action timelines as an inflection indicator for quality control infrastructure deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Lock-in Programs | Reagent subscription models capture recurring revenue alongside mass spectrometry platform placements at CROs. |
| AI-Integrated Spectral Analysis | Machine learning convergence with mass spectrometry data processing opens premium pricing tiers for automated compound identification. |
| Silicon Carbide Optical Component Adoption | Petrochemical laboratories in Osaka and Nagoya specify these subsystems for continuous manufacturing thermal stability. |
| Blockchain-Traceable Reagent Lots | German environmental agencies drive fastest adoption for PFAS quantification protocol provenance requirements. |
| Direct Vendor Relationship Expansion | Consolidated procurement through GPOs concentrates buyer power in Research Triangle and San Diego biotech corridors. |
Research Methodology
Bottom-up pharmaceutical manufacturer and contract research organization modeling reconciled against top-down precision optics and consumables supply tracking forms the analytical core of this study. Primary interviews with analytical instrumentation procurement managers, field service engineers, regulatory affairs specialists, and laboratory information system administrators combined with secondary validation from FDA method validation guidance documents, ECHA REACH authorization procedures, EPA analytical protocol requirements, ISO 17025 accreditation databases, and SEC instrument vendor filings. Triangulation across these sources ensures segmentation integrity across detection technology, application vertical, and end-user organizational type.
Input-output matrices map instrument placement volumes against consumables attachment rates and service contract penetration across the projection horizon. Segmentation dimensions modeled include product type, detection technology, application vertical, end-user organizational structure, and regional regulatory cluster. CAGRs derive from weighted average replacement cycle compression and capacity expansion trajectories. Forecast inputs incorporate biologics manufacturing facility buildout announcements and PFAS monitoring mandate implementation timelines.
The model holds under steady regulatory enforcement intensity; deviation in ECHA authorization acceleration or FDA guidance revision timing would shift instrument procurement velocity. Forecasts reflect documented assumptions regarding helium supply stability and precision optics fabrication capacity expansion. Practitioners should monitor CDSCO biosimilar oversight expansion and MEE environmental monitoring mandate enforcement for early signals of regional demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Chromatography Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
China Material Testing Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Paint Tester Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Adsorption Equipment Market