
 Laboratory Centrifuge and Accessories Market | 2026-2036
Laboratory Centrifuge and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Centrifuge and Accessories Market Foresight
Biologic research is shifting toward cell and gene therapy manufacturing, drawing new capital into ultracentrifuge capacity. Thermo Fisher Scientific dominates the high-speed refrigerated segment through its installed base in contract development organizations. Eppendorf AG specializes in compact microcentrifuge platforms that anchor workflows in academic molecular biology labs. Danaher Corporation leverages its Beckman Coulter life sciences unit to sustain premium positioning in analytical ultracentrifugation.
A laboratory centrifuge and its accessories constitute precision separation equipment that applies centrifugal force to density-gradient or differential pelleting protocols, typically operating at rotational speeds from 3,000 rpm for clinical sample preparation to over 100,000 rpm for subcellular fractionation and viral particle isolation. The primary commercial purpose spans diagnostic sample processing, biopharmaceutical purification, and materials characterization across regulated environments. Ultracentrifuges command the deepest margin pools due to optical detection systems and vacuum chamber engineering, while microcentrifuge volumes concentrate in price-sensitive academic procurement channels. Pharmaceutical development applications are outpacing clinical diagnostics in absolute growth as cell therapy developers scale plasmid and viral vector manufacturing.
The FDA enforces 21 CFR Part 820 quality system requirements on centrifuge manufacturers supplying clinical diagnostics, while ISO 13485 certification gates access to European IVD markets under the EU Medical Device Regulation. The EPA's energy conservation standards for laboratory equipment are beginning to shape motor and refrigeration specifications in new product development. Stakeholders must monitor how gene therapy manufacturing scale-up redistributes demand across refrigerated versus ultracentrifuge categories and whether rotor material innovations in carbon fiber composites displace traditional aluminum alloy supply chains.
Market Dynamics
Gene therapy manufacturing scale-up is redistributing demand toward ultracentrifuge systems with vacuum chamber engineering and optical detection capabilities, compressing procurement cycles for high-speed refrigerated units in contract development organizations.
Growth Catalysts
- 21 CFR Part 820 enforcement:The FDA's tightened quality system regulation for in-vitro diagnostic devices mandates enhanced centrifuge performance validation, forcing clinical laboratories to upgrade aging equipment fleets.
- Carbon fiber rotor composites:Precision engineering clusters in Germany's Baden-Württemberg region are supplying high-specification rotor assemblies that extend operational lifespan and reduce maintenance intervals for instrument OEMs.
- Cell therapy manufacturing:Biologic research laboratories across the United States are expanding ultracentrifuge capacity for plasmid and viral vector purification, drawing capital away from conventional clinical diagnostics procurement.
Market Restraints
- Aluminum alloy supply chain lock-in:Traditional rotor manufacturing depends on aerospace-grade aluminum suppliers concentrated in select European and North American foundries, creating input cost volatility when commodity markets fluctuate.
- ISO 13485 certification barriers:The EU Medical Device Regulation gates market access through stringent quality management requirements, extending time-to-revenue for new entrants by 18-24 months.
- Energy conservation standards:The EPA's laboratory equipment efficiency mandates are forcing motor and refrigeration redesigns that increase unit production costs without immediate buyer willingness to absorb premiums.
Strategic Opportunities
- India's biopharmaceutical corridor:CDSCO regulatory harmonization with ICH standards is opening procurement channels for analytical ultracentrifugation in contract research organizations around Hyderabad and Bangalore.
- Service unbundling:Aftermarket rotor refurbishment and calibration services are emerging as standalone revenue streams separate from equipment sales, particularly in academic molecular biology labs with constrained capital budgets.
- Dual-use materials characterization:Battery research and nanomaterials development are creating demand overlap between life sciences and industrial R&D facilities for subcellular fractionation protocols.
Industry Challenges
- Vacuum chamber engineering expertise:The specialized skill set for ultracentrifuge optical detection system integration is concentrated among a narrow cohort of senior technicians, constraining OEM production scaling.
- Legacy system interoperability:Cell therapy developers face integration friction when connecting new ultracentrifuge units to existing manufacturing execution systems and electronic batch record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Centrifuge and Accessories Market |
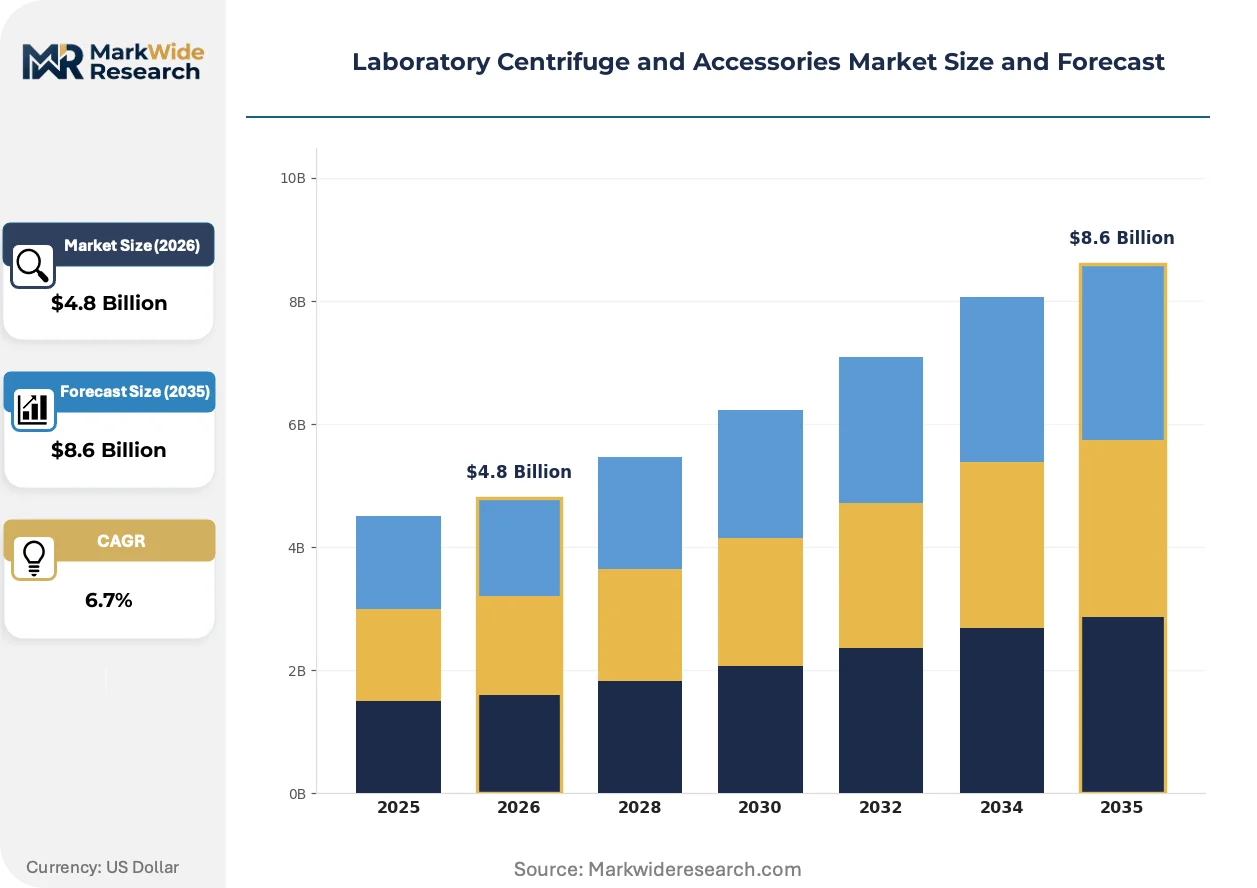
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Centrifuges, High-Speed Centrifuges, Microcentrifuges, Ultracentrifuges Application: Clinical Diagnostics, Blood Banking, Biologic Research, Pharmaceutical Development End User: Hospitals, Academic Institutions, Research Laboratories, Pharmaceutical Companies Accessory Type: Rotors, Tubes, Adapters, Ancillary Equipment |
| Companies Covered | KUBOTA Corporation, Becton, Dickinson and Company, Thermo Fisher Scientific, Sartorius AG, QIAGEN N.V., Danaher Corporation, Sigma Laborzentrifugen GmbH, Andreas Hettich GmbH & Co. KG, Eppendorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Centrifuge and Accessories Market Shifts & Advancements
Rotor material science and regulatory energy mandates are compressing traditional equipment lifecycles while opening adjacent service revenue pools. Buyers are renegotiating vendor relationships around total cost of ownership rather than acquisition price alone.
Carbon fiber composite rotors are absorbing market share from aluminum alloy designs through superior fatigue resistance and reduced thermal expansion coefficients. Gene therapy manufacturers in North American CDMOs are specifying carbon fiber for continuous processing runs exceeding 48 hours. The technology is absorbing margin pressure from energy efficiency regulations by enabling lighter drive systems with lower power draw.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in laboratory equipment, compelling refrigeration system redesigns for high-speed refrigerated centrifuges. Manufacturers serving European IVD markets must now certify alternative cooling chemistries under updated CE marking requirements. The clinical diagnostics segment is responding by extending equipment replacement cycles and negotiating refrigerant transition cost sharing with OEMs.
Academic procurement offices are consolidating centrifuge purchasing through cooperative agreements and shared service centers, fragmenting demand across fewer transaction points with higher volume per contract. Thermo Fisher Scientific and Eppendorf AG are restructuring field sales organizations to serve centralized procurement functions rather than individual principal investigator relationships. This concentration is most visible in United States research university systems where state-level purchasing consortia now dominate capital equipment acquisition.
Laboratory Centrifuge and Accessories Market Segmentation
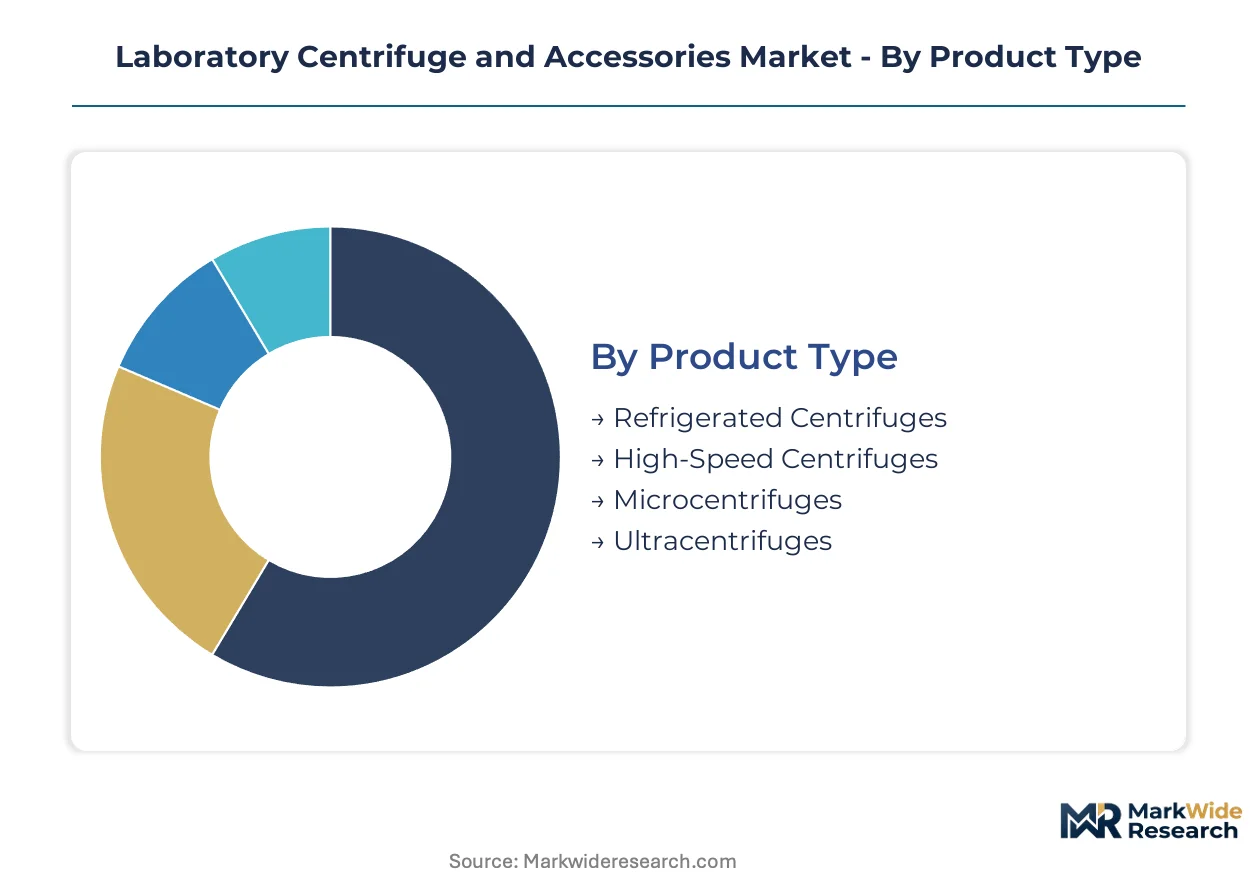
Centrifuge procurement patterns diverge sharply across performance tiers and end-use environments. Specification requirements for vacuum-chamber ultracentrifuges bear little resemblance to the cost-optimized priorities driving microcentrifuge purchasing in academic settings.
Product Type:
Rotational speed thresholds and thermal control capabilities define the technology hierarchy.
- Ultracentrifuges:Vacuum-sealed chambers enable rotational speeds exceeding 100,000 rpm for subcellular fractionation and viral vector isolation. Gene therapy manufacturers in United States CDMOs are specifying these systems for continuous processing runs exceeding 48 hours, compressing procurement cycles as plasmid purification scales.
- Refrigerated Centrifuges:Integrated cooling systems maintain sample integrity during high-speed clinical processing at 15,000–30,000 rpm. FDA 21 CFR Part 820 enforcement is forcing hospital laboratories to validate temperature stability performance, accelerating replacement of aging fleet units.
- High-Speed Centrifuges:Non-refrigerated designs serve cost-sensitive applications where thermal drift remains acceptable. Blood banking networks in Germany rely on these systems for high-throughput plasma separation.
- Microcentrifuges:Compact footprints accommodate 1.5–2.0 mL tube formats for routine molecular biology workflows. Academic procurement offices are consolidating purchases through shared service centers, fragmenting demand across fewer transaction points.
Refrigerated centrifuges lead on installed base scale; ultracentrifuges lead on capital deployment momentum.
Application:
End-use requirements split between regulated diagnostic workflows and exploratory research protocols.
- Pharmaceutical Development:Cell therapy developers deploy ultracentrifugation for lentiviral vector concentration and exosome purification. The EU F-Gas Regulation is compelling refrigeration system redesigns that extend equipment validation timelines.
- Biologic Research:Academic laboratories anchor workflows on microcentrifuge platforms for DNA/RNA extraction and protein precipitation. Carbon fiber rotor adoption is reducing maintenance intervals in continuous-use environments.
- Clinical Diagnostics:Hospital core laboratories process serum, plasma, and urine samples under FDA quality system mandates. ISO 13485 certification barriers are consolidating supplier relationships around established OEMs.
- Blood Banking:Regional collection centers separate whole blood components at high throughput. Precision engineering clusters in Germany's Baden-Württemberg region supply rotor assemblies optimized for 24-hour operational cycles.
Clinical diagnostics maintains the broadest installed footprint; pharmaceutical development exhibits the steepest expansion trajectory.
End User:
Capital allocation discipline varies dramatically across institutional categories.
- Pharmaceutical Companies:Cell therapy developers prioritize ultracentrifuge capacity with optical detection systems for real-time sedimentation monitoring. Integration friction with manufacturing execution systems constrains vendor selection.
- Research Laboratories:Biologic research facilities in United States academic medical centers balance specification requirements against constrained grant funding. Service unbundling is emerging as a procurement strategy for rotor refurbishment.
- Academic Institutions:State university purchasing consortia now dominate capital equipment acquisition, restructuring field sales relationships toward centralized procurement functions.
- Hospitals:Clinical laboratories face tightened validation requirements under FDA quality system regulations, forcing performance documentation upgrades.
Pharmaceutical companies command the highest per-unit spending; academic institutions are gaining procurement leverage fastest.
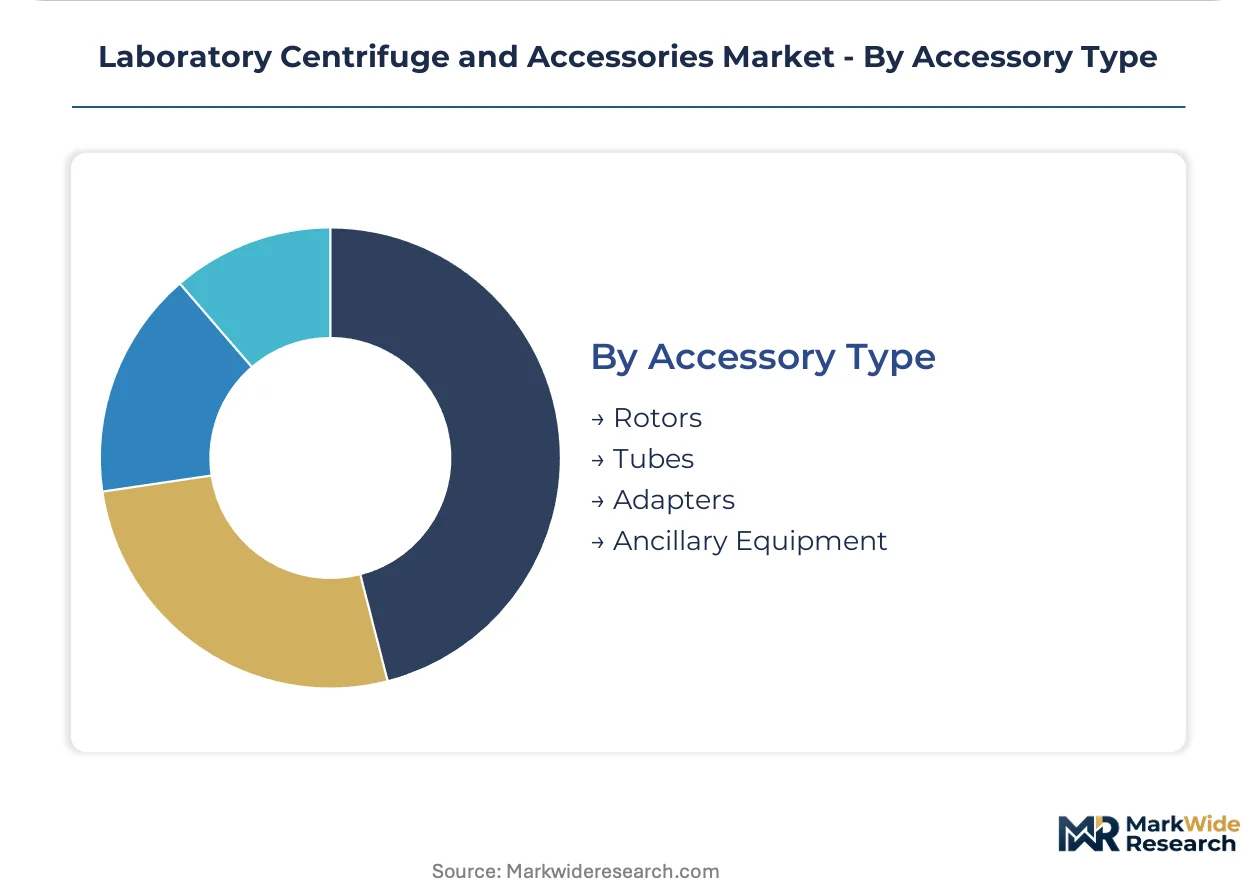
Accessory Type:
Aftermarket economics increasingly decouple from original equipment sales.
- Rotors:Carbon fiber composite designs absorb market share from aluminum alloy through superior fatigue resistance and reduced thermal expansion. Aerospace-grade aluminum supply chain concentration in European foundries creates input cost volatility.
- Tubes:Single-use polypropylene formats dominate clinical diagnostics to eliminate cross-contamination risk. Blood banking networks specify biochemically inert materials for plasma storage compatibility.
- Adapters:Modular designs enable rotor reconfiguration across tube formats, extending equipment utility in multi-protocol research environments.
- Ancillary Equipment:Vacuum pumps, refrigeration units, and optical detection modules support ultracentrifuge system integration. Specialized technician expertise for vacuum chamber engineering constrains OEM production scaling.
Rotors generate the deepest recurring revenue streams; carbon fiber variants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing centrifuge manufacturing capacity toward jurisdictions with streamlined quality system certification, while precision engineering clusters in high-cost economies defend positioning through rotor material innovation and vacuum chamber expertise.
United States
Gene therapy CDMOs in Massachusetts and North Carolina are scaling ultracentrifuge fleets for viral vector manufacturing. FDA 21 CFR Part 820 enforcement is accelerating hospital laboratory equipment replacement cycles. The Research Triangle Park cluster anchors contract development organization procurement for high-speed refrigerated systems.
Germany
Baden-Württemberg's precision engineering suppliers dominate carbon fiber rotor assembly production for instrument OEMs. EU F-Gas Regulation is compelling refrigeration system redesigns that extend equipment validation timelines for CE-marked products. The Tübingen-Stuttgart corridor concentrates vacuum chamber engineering expertise for analytical ultracentrifugation.
China
Domestic biopharmaceutical developers in Shanghai and Suzhou are localizing ultracentrifuge procurement for cell therapy manufacturing. NMPA medical device registration requirements are tightening performance documentation standards for clinical diagnostics equipment. The Yangtze River Delta biotech corridor is absorbing regional rotor fabrication capacity.
India
Contract research organizations around Hyderabad and Bangalore are expanding analytical ultracentrifugation capacity for biologic characterization. CDSCO regulatory harmonization with ICH standards is opening procurement channels previously gated by quality certification barriers. The Genome Valley biotech cluster is concentrating demand for microcentrifuge platforms in academic molecular biology workflows.
Japan
PMDA quality management requirements for in-vitro diagnostic devices are sustaining premium equipment replacement cycles in hospital core laboratories. METI industrial policy is supporting carbon fiber composite development for next-generation rotor materials. The Kansai medical device manufacturing belt maintains specialized technician training programs for vacuum system integration.
Laboratory Centrifuge and Accessories Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated relationships governing clinical diagnostics procurement while fragmented vendor pools serve academic research price sensitivity. Three archetypes dominate: diversified life sciences conglomerates with installed base leverage, precision engineering specialists with rotor material expertise, and compact equipment manufacturers anchored in molecular biology workflows. Competitive positioning hardens through M&A consolidation of aftermarket service capabilities and strategic partnerships for refrigerant transition engineering under EU energy mandates.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven archetypes with broad diagnostic and biopharmaceutical exposure. Eppendorf AG occupies a specialist position within compact microcentrifuge platforms. These three entities represent distinct competitive vectors: one leveraging contract development organization relationships, another sustaining analytical ultracentrifugation premium positioning, and the third anchoring academic procurement consolidation trends.
| Leading Market Players |
|---|
| KUBOTA Corporation |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| Sartorius AG |
| QIAGEN N.V. |
| Danaher Corporation |
| Sigma Laborzentrifugen GmbH |
| Andreas Hettich GmbH & Co. KG |
| Eppendorf AG |
| Others |
Supply & Pricing Matrix
Backward integration into carbon fiber rotor manufacturing anchors pricing power for German precision engineering clusters serving instrument OEMs. Captive production of aerospace-grade aluminum alternatives insulates Baden-Württemberg suppliers from commodity volatility while commanding premium positioning in ultracentrifuge assemblies.
Pricing Analysis
Distributor margins for clinical diagnostics equipment compress under consolidated procurement through United States hospital purchasing consortia. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified systems from CE-marked alternatives and non-validated academic units. Cost compression in refrigerated centrifuges intensifies because EPA energy mandates force motor redesigns without proportional buyer willingness to absorb premiums. Academic molecular biology labs exhibit highest price sensitivity; gene therapy CDMOs demonstrate lowest.
Supply Chain Analysis
Aerospace-grade aluminum supply rests on European and North American foundries concentrated in Germany, Switzerland, and select United States industrial corridors. Carbon fiber composite feedstocks draw from Japanese specialty polymer producers and German textile engineering facilities. Single-source vulnerability concentrates in vacuum chamber engineering expertise tethered to the Tübingen-Stuttgart corridor. Distribution runs through OEM direct sales for pharmaceutical customers and cooperative purchasing agreements for academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber rotor adoption enables margin expansion through material substitution premiums and reduced warranty exposure. OEMs capturing this shift deepen aftermarket service penetration.
For Market Incumbents: Anticipate procurement consolidation in United States academic consortia by restructuring field sales toward centralized purchasing functions. Defend analytical ultracentrifuge positioning through vacuum chamber engineering apprenticeships that constrain competitor production scaling. Certification investment in EU F-Gas-compliant refrigeration systems gates European IVD market retention. For New Entrants and Emerging Players: Launch via aftermarket rotor refurbishment services targeting budget-constrained research laboratories with extended equipment lifecycles. White-space concentrates in India's CDSCO-harmonized contract research corridors around Hyderabad and Bangalore. Unbundle calibration and maintenance from equipment sales to penetrate academic shared service centers. For Investors and Strategic Acquirers: Roll-up economics work for precision rotor specialists because carbon fiber composite expertise concentrates among Baden-Württemberg engineering clusters with limited replication. Five-to-ten year viability hinges on gene therapy manufacturing scale sustaining ultracentrifuge demand. Target acquisition archetype: regional service providers with ISO 17025 calibration capabilities. Watch rotor material substitution rates as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Rotor Manufacturing Scale-Up | Baden-Württemberg precision engineering clusters extend operational lifespan advantages over aluminum alloy competitors. |
| EU F-Gas Refrigeration System Redesign | CE marking requirements for alternative cooling chemistries extend validation timelines for European IVD market access. |
| Aftermarket Service Unbundling | Standalone rotor refurbishment revenue streams penetrate academic molecular biology labs with constrained capital budgets. |
| CDSCO Regulatory Harmonization Entry | ICH-aligned quality certification opens procurement channels for analytical ultracentrifugation in Indian contract research organizations. |
| Vacuum Chamber Engineering Apprenticeship Programs | Specialized technician pipeline constraints constrain OEM production scaling and defend incumbent positioning. |
Research Methodology
Direct dialogue with centrifuge OEM product managers, hospital laboratory directors, contract development organization procurement leads, and precision engineering cluster operations heads grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, NMPA medical device registration databases, and German engineering association production surveys. Bottom-up equipment shipment data triangulated against top-down biopharmaceutical capital expenditure disclosures.
Bottom-up modeling segmented demand across rotational speed tiers, thermal control configurations, and end-use regulatory environments. The analytical framework projected gene therapy manufacturing capacity expansion, EPA energy conservation compliance timelines, and rotor material substitution curves across the analysis window. CAGRs derived from equipment replacement cycle compression in clinical diagnostics and capacity build-out trajectories in North American CDMOs.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on carbon fiber composite exports and unanticipated refrigerant chemistry breakthroughs. Forecasts reflect assumptions about regulatory enforcement continuity and gene therapy pipeline advancement. A small set of named triggers warrants ongoing watch: CDSCO inspection capacity expansion, United States hospital purchasing consortium formation rates, and EU F-Gas phase-down acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
China Material Testing Market