
 Chemical Warfare Agent Detectors Market | 2026-2036
Chemical Warfare Agent Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Warfare Agent Detectors Market Insights
Software-defined threat libraries delivered through recurring firmware subscriptions is hardening the revenue model away from one-time hardware sales. Teledyne FLIR leverages its thermal imaging heritage to anchor premium positioning in portable detection. Bruker Corporation sustains R&D intensity in mass spectrometry sensing technology. Smiths Detection competes through channel control at major international airports and border crossings.
Chemical warfare agent detectors are instruments engineered to identify toxic chemical compounds at concentrations measured in parts per billion, typically employing ion mobility spectrometry or surface acoustic wave sensors operating at temperatures between 150°C and 300°C to achieve rapid molecular discrimination. Their primary purpose is enabling military personnel, first responders, and security operators to confirm contamination and execute protective protocols before exposure reaches lethal thresholds. Portable detector types command the largest installed base due to dismounted soldier requirements, while integrated systems capture the deepest margin pools through multi-sensor fusion architectures. Mass spectrometry represents the fastest-growing sensing technology segment as miniaturized units close the performance gap with laboratory-grade instruments.
The US Department of Defense's Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense shapes procurement specifications that ripple through NATO supply chains, while the EPA's emergency response guidelines for hazardous substance releases drive civilian agency adoption patterns. Germany's KBA and France's ANSM coordinate type-approval pathways that constrain market access for non-compliant hardware. Stakeholders must monitor how EU Green Deal material restrictions on rare earth components will reshape sensor fabrication economics and supplier qualification timelines.
Market Dynamics
The US Department of Defense's Joint Chemical Agent Detector program is compressing technology refresh cycles from seven-year intervals to three-year windows, forcing suppliers to restructure R&D cadences around firmware-defined architectures rather than hardware-centric platforms.
Growth Catalysts
- Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense procurement specifications:NATO member states are harmonizing detection sensitivity standards, creating cross-border volume opportunities for qualified vendors.
- Surface acoustic wave sensor miniaturization:Advances in microelectromechanical systems fabrication are reducing unit costs while maintaining parts-per-billion detection thresholds for sulfur mustard and VX agents.
- German KBA type-approval pathways:Accelerated certification timelines for dual-use detection systems are shortening market entry barriers for civilian emergency response agencies across Central Europe.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies on Chinese processing facilities expose sensor manufacturers to export quota volatility and price shocks.
- Ion mobility spectrometry false-positive rates:Cross-sensitivity to common industrial chemicals like ammonia and diesel exhaust limits deployment confidence in mixed-contamination environments.
- EU Green Deal material restrictions:Pending limitations on hexavalent chromium and cadmium in electronics assemblies will force sensor housing and contact redesigns with 18-24 month requalification timelines.
Strategic Opportunities
- Mass spectrometry-lidar sensor fusion:Converging molecular identification with standoff range detection enables perimeter monitoring applications previously served by point-contact devices alone.
- India's Civil Defence Corps modernization:Underpenetrated state-level procurement for metropolitan rapid response teams offers first-mover positioning ahead of federal standardization.
- Software-defined threat library subscriptions:Recurring firmware update revenue models are displacing one-time hardware sales, improving lifetime value per unit by 40-60% for vendors with cloud delivery infrastructure.
Industry Challenges
- Mass spectrometry miniaturization engineering talent:The intersection of vacuum physics, RF engineering, and embedded systems expertise commands premium compensation and extended recruitment cycles.
- Joint Chemical Agent Detector M50 qualification:MIL-STD-810H environmental testing and MIL-PRF-29504 interoperability certification require 14-18 month validation periods that consume 30-40% of product development budgets.
- Legacy IMS detector fleet integration:Backward compatibility requirements with NATO STANAG 4632 interfaces constrain architectural freedom for next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Warfare Agent Detectors Market |
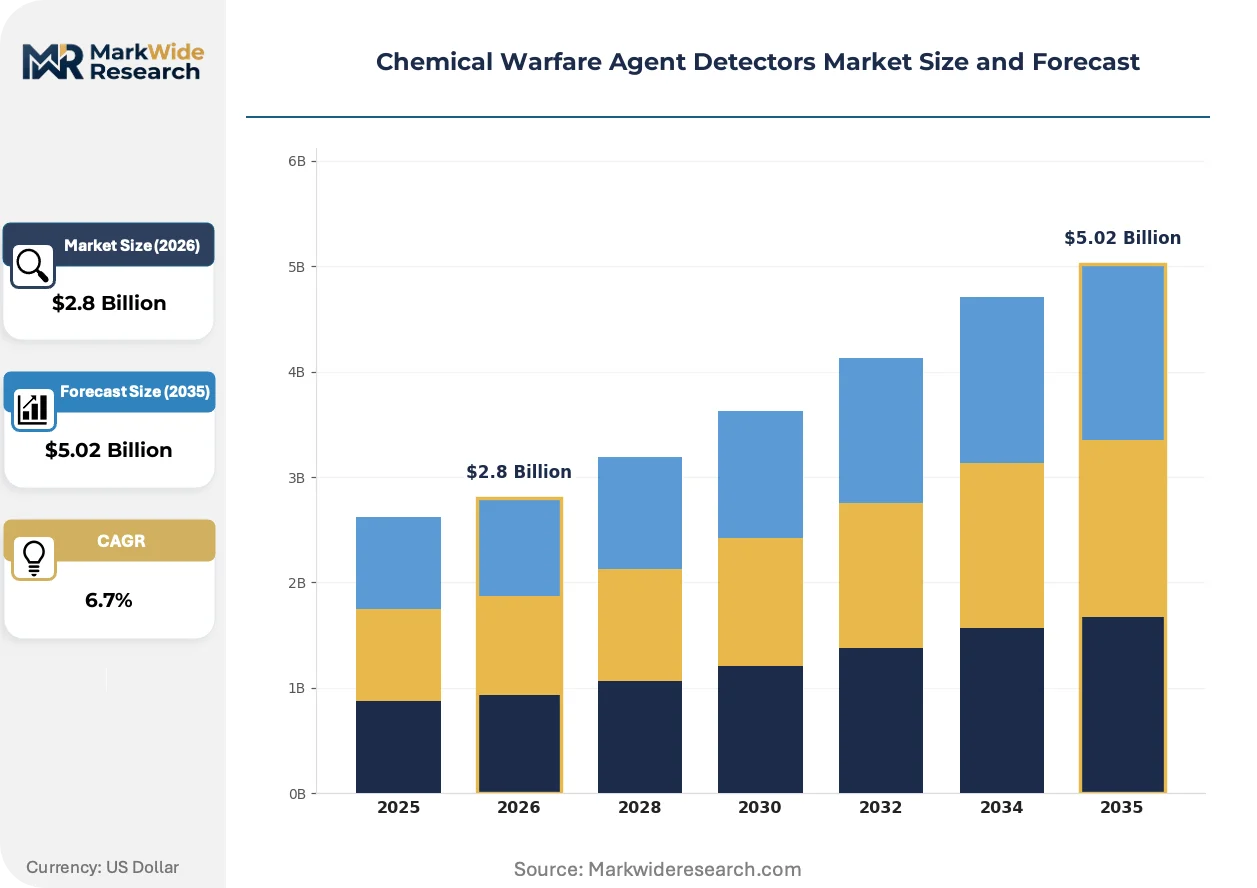
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Detector Type: Portable, Fixed, Handheld, Integrated Systems, Standalone Sensing Technology: Chemiluminescence, Infrared Spectroscopy, Ion Mobility Spectrometry, Surface Acoustic Wave, Mass Spectrometry Application: Military Defense, Counterterrorism, Environmental Monitoring, Border Surveillance, Emergency Response End User: Defense Agencies, Homeland Security, Fire Departments, Research Laboratories, Industrial Safety Departments |
| Companies Covered | Teledyne FLIR, 908 Devices, Thermo Fisher Scientific, Saab AB, Agilent Technologies, Bruker Corporation, Rheinmetall AG, Drägerwerk AG & Co. KGaA, Smiths Detection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Warfare Agent Detectors Market Trends and Innovations
Detection architectures are pivoting from standalone hardware to sensor-network nodes, with threat intelligence distribution and algorithmic refinement becoming as strategically significant as the physical sensing layer itself.
Miniaturized mass spectrometry units are integrating laboratory-grade molecular identification into backpack-portable form factors. Military special operations units in Germany and France are field-testing quadrupole-based systems weighing under 8 kilograms. This convergence is compressing the performance gap between forward-deployed and fixed-site detection, forcing incumbents to defend premium positioning through software differentiation rather than hardware exclusivity.
REACH substance restrictions under the EU Green Deal are mandating elimination of per- and polyfluoroalkyl substances from sensor membranes and seals by 2027. Industrial chemical manufacturers are reformulating fluoropolymer alternatives with comparable chemical resistance profiles. Detection system assemblers in Belgium and the Netherlands are accelerating qualification programs to avoid supply discontinuities during the 2026-2027 transition window.
Defense procurement offices are unbundling hardware acquisition from sustainment services, creating discrete competitive arenas for detection units, calibration consumables, and firmware subscriptions. The US Department of Defense's emphasis on competitive task orders for contractor logistics support is fragmenting supplier relationships that previously spanned full system lifecycles. This behavioral shift is most visible in NATO rapid deployment exercises, where mixed-vendor sensor networks must demonstrate interoperability under compressed mobilization timelines.
Chemical Warfare Agent Detectors Market Segmentation
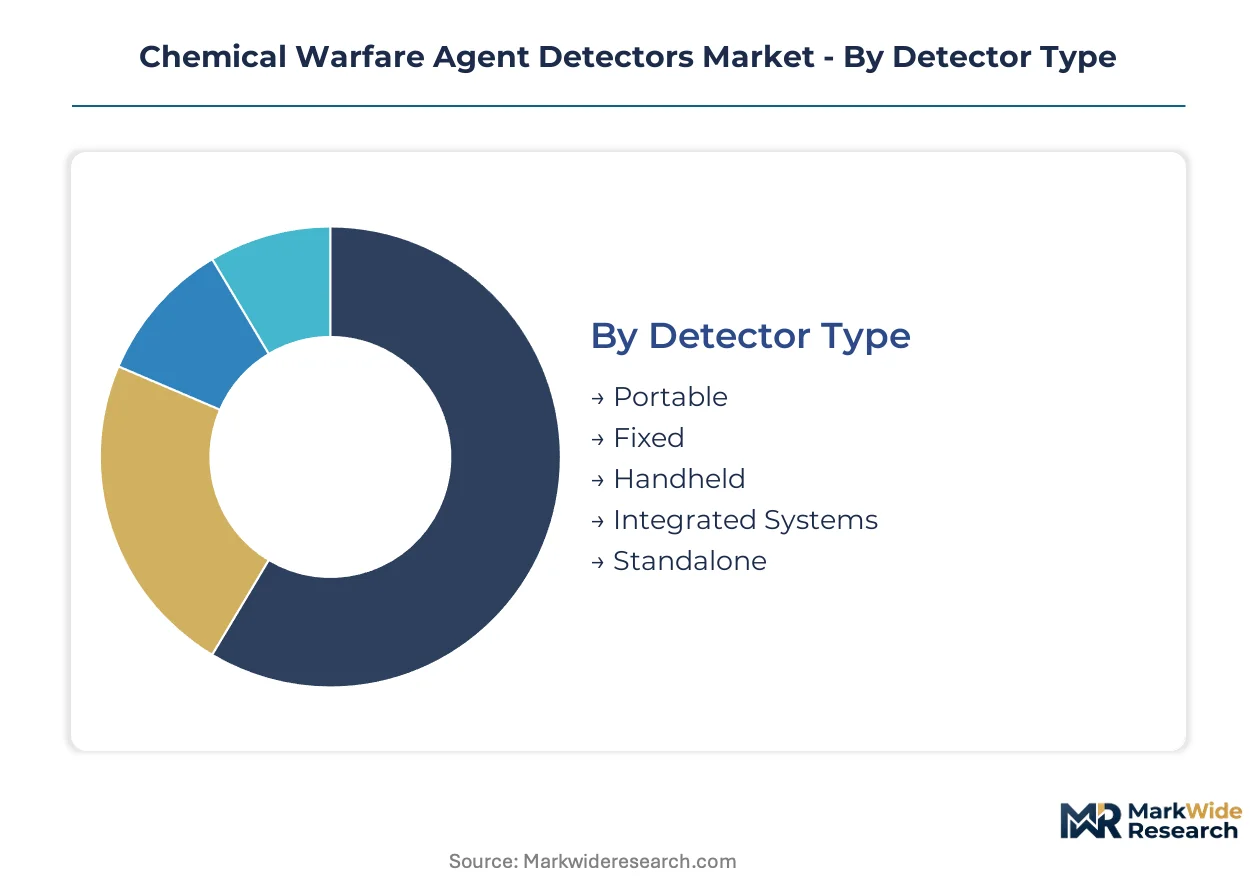
Segmentation in chemical warfare agent detectors reveals how procurement priorities diverge between rapid field deployment and fixed-site perimeter defense. Buyer budgets, operational tempo, and regulatory compliance requirements create distinct competitive arenas across detector configurations, sensing modalities, and end-user categories.
Detector Type:
Defense procurement offices weight portability against integration depth when allocating acquisition budgets across mission profiles.
- Portable:Backpack-configured units under 8 kilograms enable dismounted soldier operations and rapid contamination mapping. Demand concentrates with NATO special operations forces in Germany and France, where quadrupole mass spectrometry miniaturization is compressing performance gaps with laboratory systems.
- Fixed:Permanently installed multi-sensor arrays provide continuous perimeter monitoring at military installations and critical infrastructure sites. Border surveillance deployments across Central Europe favor these systems for their integration with command-and-control networks, though requalification timelines under EU Green Deal material restrictions are extending procurement cycles.
- Handheld:Single-operator devices dominate first responder arsenals for point detection at suspected contamination sites.
- Integrated Systems:Multi-sensor fusion architectures capture premium margins through centralized threat data correlation.
- Standalone:Self-contained units without network dependencies serve remote deployment scenarios and backup redundancy requirements.
Volume sits with portable configurations; growth tilts toward integrated systems as NATO standardizes network-centric detection architectures.
Sensing Technology:
Technology selection hinges on the trade-off between detection confidence and operational constraints like power draw, warm-up time, and maintenance burden.
- Mass Spectrometry:Miniaturized quadrupole and ion trap systems deliver laboratory-grade molecular identification in field-portable form factors. Military special operations units in Germany are accelerating procurement of sub-8-kilogram units, while vacuum physics engineering talent scarcity constrains supplier expansion.
- Ion Mobility Spectrometry:Established technology with mature supply chains dominates legacy fleet replacements. Cross-sensitivity to ammonia and diesel exhaust limits deployment confidence in mixed industrial-military environments, driving demand for complementary sensing modalities.
- Surface Acoustic Wave:MEMS fabrication advances are reducing unit costs while maintaining parts-per-billion thresholds for sulfur mustard and VX agents.
- Infrared Spectroscopy:Standoff detection capabilities enable perimeter monitoring without physical sample collection.
- Chemiluminescence:Enzyme-based detection provides specificity for nerve agent classes with minimal power requirements.
Installed base concentrates in ion mobility spectrometry; capability investment flows most heavily into mass spectrometry miniaturization.
Application:
Mission type dictates sensitivity specifications, response time requirements, and interoperability standards with protective equipment.
- Military Defense:Force protection programs specify detection thresholds, environmental hardening per MIL-STD-810H, and compatibility with M50 respirator systems. The US Department of Defense's Joint Chemical Agent Detector program compresses technology refresh cycles from seven-year to three-year intervals.
- Counterterrorism:Covert deployment scenarios favor low-signature portable units with rapid startup sequences.
- Emergency Response:Civil defense agencies prioritize ease of operation under stress and interoperability with hazardous materials protocols.
- Border Surveillance:High-throughput screening of cargo and vehicles drives demand for automated sampling systems.
- Environmental Monitoring:Remediation site characterization requires archival data capabilities and regulatory reporting integration.
Procurement volume clusters in military defense; counterterrorism applications are climbing the fastest as urban threat scenarios multiply.
End User:
Organizational capability maturity determines acceptable complexity levels and sustainment model preferences.
- Defense Agencies:Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense specifications shape NATO harmonized standards. These buyers unbundle hardware from sustainment services, fragmenting supplier relationships across competitive task orders for contractor logistics support.
- Homeland Security:Federal and state-level agencies balance interoperability requirements against procurement autonomy.
- Fire Departments:Metropolitan rapid response teams in underpenetrated markets like India's Civil Defence Corps offer first-mover positioning ahead of standardization.
- Research Laboratories:Reference-grade calibration and data export capabilities drive specification priorities.
- Industrial Safety Departments:Dual-use applications at chemical manufacturing facilities leverage military-derived technology for process safety.
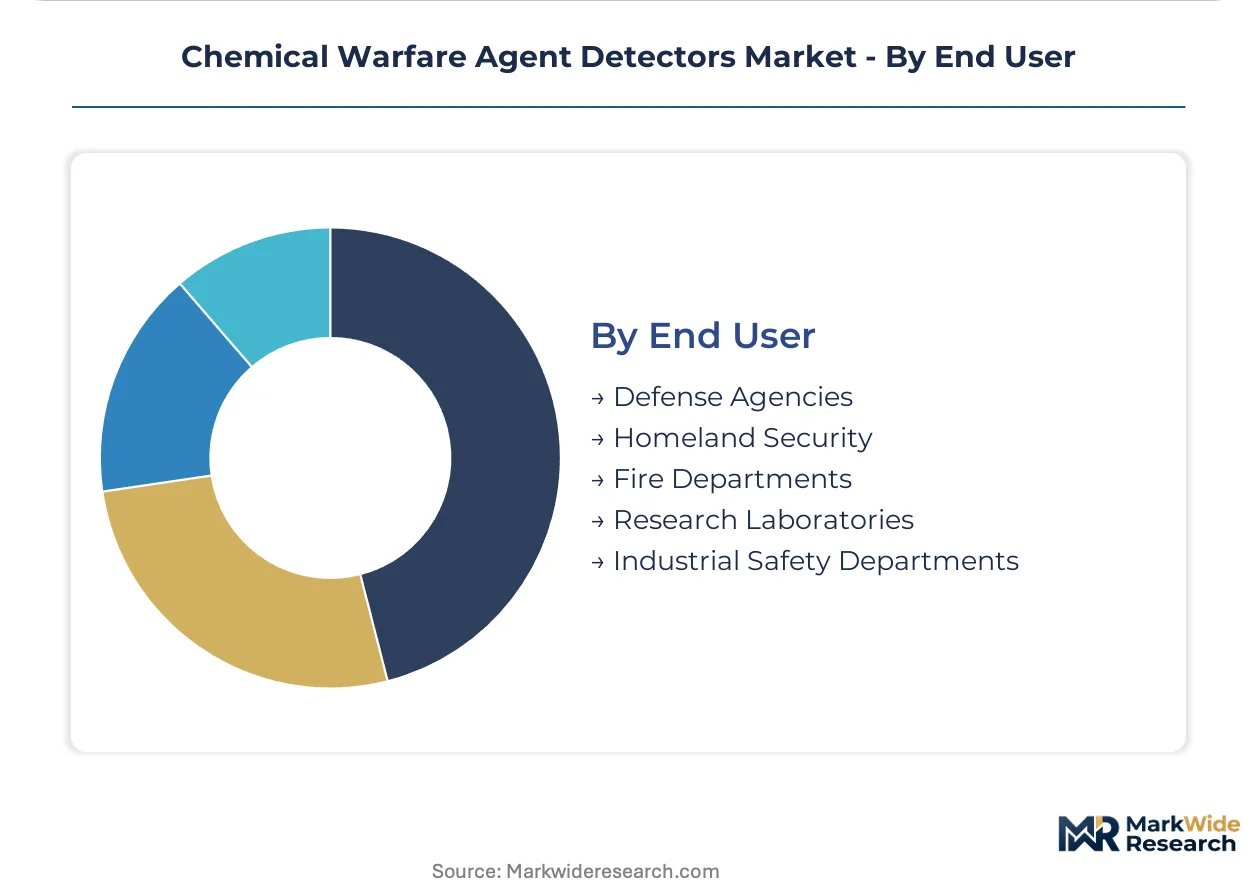
Revenue concentration remains with defense agencies; homeland security procurement is expanding most quickly as civilian agency adoption patterns accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States, while procurement demand spreads across NATO member states and emerging defense markets. Consumption patterns diverge between mature military modernization programs and first-time civilian agency acquisitions.
United States
The Joint Chemical Agent Detector program compresses technology refresh cycles from seven-year to three-year intervals, accelerating replacement demand across Army and Marine Corps units. EPA emergency response guidelines for hazardous substance releases drive parallel adoption by civilian agencies. Defense procurement clusters around Washington D.C. metro corridors and Huntsville, Alabama, where systems integration contractors align with Pentagon acquisition offices.
Germany
Rheinmetall AG and Drägerwerk anchor European supply chains for integrated detection systems serving Bundeswehr modernization. KBA type-approval pathways for dual-use equipment create accelerated certification channels that neighboring states leverage. Industrial concentration in North Rhine-Westphalia and Bavaria supports sensor fabrication clusters with proximity to NATO headquarters in Brussels.
France
ANSM coordinates type-approval pathways that constrain market access for non-compliant hardware, favoring domestic and established EU suppliers. Military special operations units field-test quadrupole mass spectrometry miniaturization for sub-8-kilogram portable units. Defense procurement concentrates in Île-de-France and Provence-Alpes-Côte d'Azur, with integration facilities near Marseille naval bases.
India
Civil Defence Corps modernization at state level creates first-mover positioning ahead of federal standardization for metropolitan rapid response teams. BIS certification requirements for imported safety equipment filter supplier eligibility. Industrial activity clusters in Maharashtra and Delhi-NCR, where defense public sector undertakings evaluate detection systems for integration with existing CBRN infrastructure.
United Kingdom
Ministry of Defence procurement aligns with NATO STANAG 4632 interoperability standards, preserving backward compatibility with legacy fleet investments. Counterterrorism applications drive demand for low-signature portable units with rapid startup sequences. Systems integration concentrates in Southeast England and the Midlands, with testing facilities at Porton Down supporting qualification protocols.
Chemical Warfare Agent Detectors Market Competitive Landscape
Top-tier vendors anchor defense procurement specifications, while mid-tier specialists compete on civilian agency certifications and price-competitive portable units. Market structure tilts toward consolidated supply relationships with NATO defense ministries, though fragmentation persists in dual-use and emergency response segments. Three archetypes dominate: thermal imaging heritage players, mass spectrometry instrument specialists, and integrated systems contractors with channel control at critical infrastructure sites. Competitive moves center on firmware-defined architecture transitions and unbundling of hardware from sustainment services.
Within the thermal imaging and sensing tier, Teledyne FLIR and Bruker Corporation occupy positions that leverage distinct technology heritages. Among German-based defense contractors, Rheinmetall AG and Drägerwerk exemplify integrated systems capabilities with established NATO supply chain relationships. Smiths Detection represents the channel-control archetype through presence at major international airports and border crossings.
| Leading Market Players |
|---|
| Teledyne FLIR |
| 908 Devices |
| Thermo Fisher Scientific |
| Saab AB |
| Agilent Technologies |
| Bruker Corporation |
| Rheinmetall AG |
| Drägerwerk AG & Co. KGaA |
| Smiths Detection |
| Others |
Pricing and Supply Chain Analysis
The US Department of Defense's three-year technology refresh mandate is compressing supplier R&D cycles and forcing hardware vendors toward firmware-defined architectures with recurring revenue attachments. This procurement acceleration concentrates pricing power with qualified NATO suppliers while squeezing margins for legacy hardware-centric platforms.
Pricing Analysis
Margin tightening in portable detector tiers reflects the shift from transactional hardware sales toward software-defined threat library subscriptions. Three-tier pricing structure across premium mass spectrometry, standard ion mobility spectrometry, and economy surface acoustic wave configurations stratifies by detection confidence and certification grade. Pricing pressure intensifies in the handheld segment as MEMS fabrication advances reduce unit costs for sulfur mustard and VX detection. Defense agencies exhibit lowest price sensitivity due to mission-critical specifications, while municipal fire departments in underpenetrated markets face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements for rare earth magnet components now dominate procurement qualification protocols across NATO defense ministries. Neodymium and dysprosium processing concentrates in China, with secondary refining capacity in Germany and Japan. Sensor fabrication draws from Belgian MEMS foundries, Dutch industrial chemical suppliers, and Bavarian precision engineering clusters. Single-source vulnerability in Chinese rare earth export quotas exposes manufacturers to supply discontinuities. Distribution runs through Rheinmetall AG and Drägerwerk's integrated logistics networks serving Bundeswehr and allied European forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical warfare agent detector market is becoming a vertical-integration race, with control over vacuum physics engineering talent and cloud delivery infrastructure determining who captures recurring firmware subscription revenue.
For Market Incumbents: Anchor firmware-defined architecture transitions ahead of Joint Chemical Agent Detector program qualification windows. Lock in exclusive relationships with German and French special operations units field-testing quadrupole mass spectrometry miniaturization. Defend against emerging MEMS-based entrants by accelerating KBA and ANSM type-approval pathways that constrain non-compliant hardware market access. For New Entrants and Emerging Players: Enter via India's state-level Civil Defence Corps modernization ahead of federal BIS standardization. Target metropolitan rapid response teams in Maharashtra and Delhi-NCR with price-competitive surface acoustic wave handheld units. Pursue OEM partnerships with German industrial chemical manufacturers reformulating fluoropolymer alternatives for EU Green Deal compliance. For Investors and Strategic Acquirers: The window for entry favors mass spectrometry miniaturization specialists with captive vacuum physics engineering teams. Long-term viability hinges on cloud infrastructure for threat library distribution and algorithmic refinement. Watch for Joint Program Executive Office unbundling of hardware from sustainment services as the inflection signal for contractor logistics support consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Defined Architecture Transition | Enables recurring subscription revenue from NATO defense agencies unbundling sustainment services. |
| Mass Spectrometry Miniaturization R&D | Captures procurement from German and French special operations units demanding sub-8-kilogram portable units. |
| Dual-Use Certification Acceleration | Leverages German KBA pathways to shorten market entry for civilian emergency response agencies across Central Europe. |
| Rare Earth Magnet Supply Diversification | Mitigates Chinese export quota exposure through Japanese and German secondary refining qualification. |
| Cloud Threat Library Infrastructure | Supports 40-60% lifetime value improvement per unit through algorithmic refinement and intelligence distribution. |
Research Methodology
Document review covered defense procurement databases, EPA emergency response guidelines, and EU Green Deal regulatory filings, complemented by interviews with program managers at the Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense, Bundeswehr technical directors, and civilian agency procurement leads at India's Civil Defence Corps. Secondary validation drew from NATO STANAG documentation, KBA type-approval records, and customs data on rare earth magnet trade flows. Bottom-up unit shipment estimates and top-down defense budget allocation analysis were triangulated to constrain forecast variance.
Historical procurement patterns across the US Department of Defense's Joint Chemical Agent Detector program were cross-referenced against panel input from systems integration contractors in Huntsville, Alabama and Washington D.C. metro corridors. Segmentation modeling incorporated detector type, sensing technology, application mission profile, and end-user organizational maturity. CAGRs were derived from technology refresh cycle compression and firmware subscription revenue transition assumptions. Industry-specific inputs included MIL-STD-810H environmental testing timelines and REACH substance restriction phase-out schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export quota volatility or extended EU Green Deal requalification timelines. Deviation in Joint Program Executive Office procurement unbundling velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Chromatography Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Global Analytical Standards Market
Testing Equipment
Bitumen and Asphalt Testing Services Market