
 Global Hydraulic Ironworker Machine Market | 2026-2036
Global Hydraulic Ironworker Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Ironworker Machine Market Intelligence
CE marking compliance is redrawing the competitive map for manufacturers accessing the European Union. This standard gates market entry by mandating specific safety and performance criteria. Scotchman Industries Inc. leverages its established distribution network in North America, while GEKA Group specializes in high-capacity automated systems for structural steel fabrication. ERMAKSAN differentiates its offerings through a focus on advanced CNC-controlled machines.
A hydraulic ironworker machine is a multi-purpose tool used for punching, shearing, notching, and bending steel plates, bars, and angles. Its core functionality is defined by hydraulic tonnage capacity, which dictates the thickness and type of metal it can process. While floor-mounted units constitute a large portion of the installed base, CNC controlled models are seeing the most significant new investment. Metal fabrication shops remain the primary application, valuing the machine's versatility for custom and short-run production.
Operator safety regulations, including standards from the US Occupational Safety and Health Administration (OSHA) and the EU's Machinery Directive, shape equipment design. These rules mandate features like safety guards, dual-control systems, and emergency stops. The evolution of ISO 12100 also provides a global framework for risk assessment. Manufacturer success will be determined by their ability to integrate advanced automation and safety systems while adapting to new high-strength steel alloys.
Market Dynamics
The industry-wide migration toward CNC-controlled systems is the central force shaping the hydraulic ironworker market. This technological shift enhances precision and automation, fundamentally altering equipment value propositions from raw power to intelligent fabrication, directly influencing purchasing decisions in key manufacturing sectors.
Growth Catalysts
- CNC Integration:The incorporation of Computer Numerical Control (CNC) systems enhances operational accuracy and reduces manual labor, meeting demands from high-specification sectors like aerospace and automotive component manufacturing for repeatable precision.
- Infrastructure Development:Government-led infrastructure projects, particularly in developing economies in Asia and through initiatives like the US Infrastructure Investment and Jobs Act, stimulate demand for fabricated structural steel, a core application for high-capacity ironworkers.
- High-Strength Steel Proliferation:The use of advanced high-strength steel alloys in construction and heavy equipment requires machinery with greater tonnage and durability, creating a replacement and upgrade cycle for older, less capable ironworker units.
Market Restraints
- High Capital Outlay:The significant initial investment required for advanced, CNC-equipped hydraulic ironworkers presents a considerable barrier to entry for smaller metal fabrication shops and startups, slowing adoption in fragmented market segments.
- Substitution from Laser and Plasma:For applications demanding intricate cuts and fine finishes, particularly on thinner materials, laser and plasma cutting systems offer a competitive alternative, limiting the ironworker's scope to shearing, punching, and notching tasks.
- Skilled Operator Scarcity:A persistent shortage of technicians trained to program, operate, and maintain sophisticated CNC-controlled machinery constrains the productivity gains that these advanced systems are designed to deliver, limiting their effective utilization.
Strategic Opportunities
- Renewable Energy Sector:The fabrication of components for wind turbine towers, solar panel mounting structures, and geothermal equipment represents a significant opportunity, as these applications require the precise cutting and punching of heavy steel profiles.
- Software and IIoT Integration:Developing proprietary software for process simulation, remote diagnostics, and integration with Industrial Internet of Things (IIoT) platforms creates new revenue streams and enhances customer loyalty through improved operational visibility.
- Emerging Market Industrialization:Targeting industrializing economies in Southeast Asia and Latin America, where manufacturing and construction sectors are expanding, provides new geographic avenues for growth beyond traditionally dominant markets.
Industry Challenges
- Regulatory Compliance Divergence:Manufacturers face complexity and added cost in designing machines that simultaneously comply with differing regional safety mandates, such as OSHA standards in the United States and the EU's Machinery Directive for CE marking.
- Legacy System Integration:Integrating modern, automated ironworkers into existing production lines populated with older, manual equipment poses significant workflow and compatibility challenges for established fabrication shops, delaying modernization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Ironworker Machine Market |
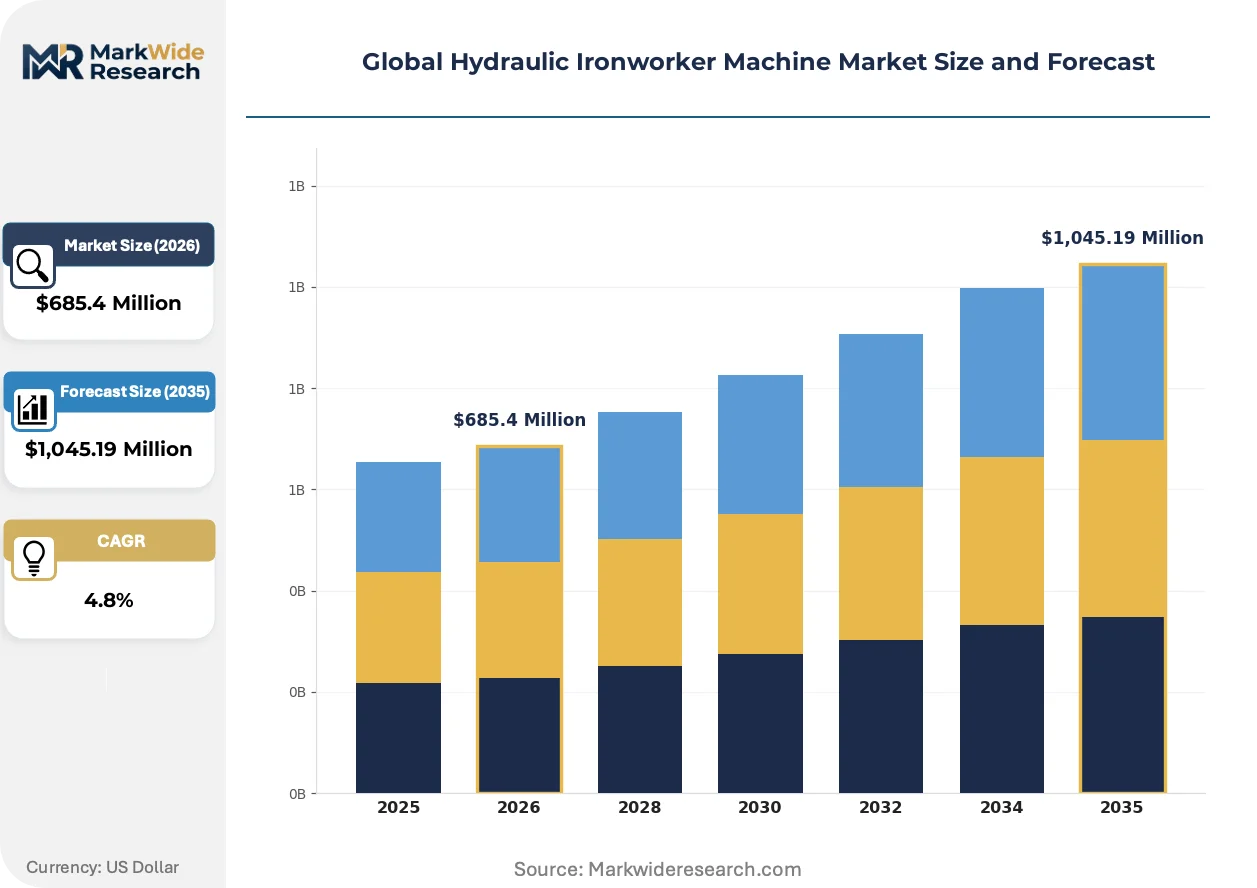
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Floor Mounted, CNC Controlled, Manual, Hydraulic Pneumatic Technology: Hydraulic, Mechanical, Electric, Electro-Hydraulic, Servo Application: Metal Fabrication Shops, Heavy Equipment Production, Shipbuilding, Construction Equipment, Agricultural Tools End User: Fabricators, OEMs, Maintenance Workshops, Defense Equipment Makers, Tool Manufacturers |
| Companies Covered | Piranha, Prada Nargesa S.L., Scotchman Industries Inc., ERMAKSAN, HARSLE, GEKA Group, DARAMCO, Cleveland Steel Tool, Edwards Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Ironworker Machine Market Strategic Shifts & Innovations
The convergence of automation and enhanced safety protocols is defining the next generation of hydraulic ironworker machines. This evolution is driven by software-defined controls and advanced sensor technology, shifting the competitive focus from sheer hydraulic force to intelligent, safe, and efficient metal fabrication.
Integrated automation software, which combines design, programming, and machine operation into a single interface, is a key product evolution. Structural steel fabricators and heavy equipment manufacturers are rapidly adopting these systems to streamline complex, multi-step processes. This level of software-driven control is displacing standalone, single-function machines by enabling a single ironworker to execute a complete sequence of punching, shearing, and notching operations from one digital file.
Global safety standards, particularly the risk assessment framework outlined in ISO 12100, are increasingly shaping equipment design. This standard compels a shift towards designing for inherent safety, integrating features like light curtains, dual-palm buttons, and enclosed workstations directly into the machine's core architecture. This affects all manufacturers with global distribution, pushing the market toward a baseline of advanced safety systems, especially for models destined for Europe and North America.
A notable behavioral shift is occurring in custom fabrication, where shops now prioritize machine versatility to manage high-mix, low-volume orders. This demand for flexibility is disrupting the traditional model of using separate machines for each function, favoring all-in-one ironworkers that can be quickly reconfigured. This trend is especially visible in North American and German job shops serving diverse sectors, from agricultural equipment repair to bespoke architectural metalwork.
Global Hydraulic Ironworker Machine Market Segmentation
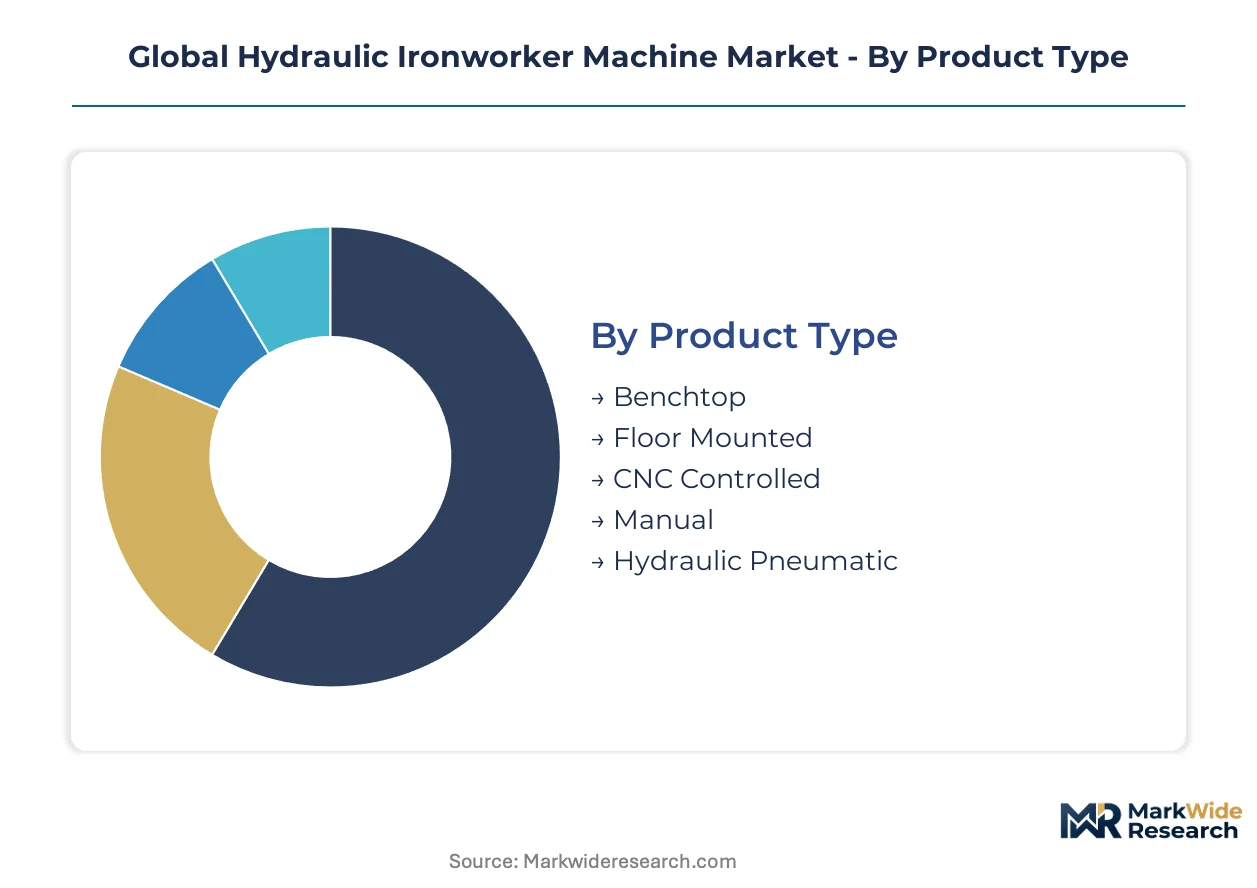
Segmenting the global hydraulic ironworker machine market provides clarity on demand patterns across diverse industrial needs. This analysis highlights how specific machine configurations and technological advancements cater to distinct operational requirements and regional preferences. Understanding these segments is crucial for manufacturers to align product development with evolving market drivers.
Product Type:
The geographic distribution of hydraulic ironworker machine product types reflects varying levels of industrial maturity and regulatory environments. Domestic markets in developing economies often favor simpler, cost-effective models, while export-led industries demand advanced, compliant systems.
- CNC Controlled:These advanced machines integrate computer numerical control for automated, high-precision operations, meeting stringent demands from aerospace and automotive component manufacturing in Germany and Japan. CNC integration significantly reduces manual labor and enhances repeatable accuracy for complex fabrication tasks.
- Floor Mounted:Representing a substantial portion of the established base, these robust units offer high tonnage capacity for heavy-duty punching and shearing. Metal fabrication shops in the United States and China widely adopt floor-mounted systems for their versatility in custom and short-run production.
- Benchtop:Compact and space-efficient, benchtop models cater to smaller workshops and specialized tasks requiring less hydraulic force.
- Manual:Manual ironworkers provide basic, operator-controlled functionality, often preferred in cost-sensitive markets for straightforward metalworking.
- Hydraulic Pneumatic:These machines combine hydraulic power with pneumatic controls for specific applications requiring a blend of force and operational precision.
Floor Mounted machines command the established base. The steepest expansion runs through CNC Controlled models.
Technology:
Technology choices in hydraulic ironworkers often reflect a balance between initial investment and long-term operational efficiency, influencing procurement decisions across various manufacturing scales. Advanced technologies typically involve higher upfront costs but deliver superior precision and automation capabilities.
- Hydraulic:This foundational technology utilizes fluid pressure to generate immense force for punching, shearing, and bending tasks. Hydraulic systems are prevalent across all machine types due to their reliability and ability to handle thick materials.
- Electro-Hydraulic:Combining electric motors with hydraulic power, these systems offer enhanced control and energy efficiency compared to purely hydraulic counterparts. Electro-hydraulic machines find application in modern fabrication facilities seeking optimized performance.
- Mechanical:Older mechanical systems rely on flywheel energy and cams to generate force, typically for simpler, high-volume operations.
- Electric:Purely electric ironworkers are emerging, offering quieter operation and reduced maintenance requirements for specific lighter-duty applications.
- Servo:Servo technology provides precise control over machine movements, enabling intricate cuts and bends with high repeatability for specialized fabrication.
Hydraulic technology remains foundational. Servo systems are gaining traction for advanced applications.
Application:
The volume of metal processing varies significantly across different applications, influencing machine specifications and throughput requirements. Industries with high-volume production demand automated, durable ironworkers, while custom fabrication values versatility.
- Metal Fabrication Shops:These shops represent the largest application segment, utilizing ironworkers for diverse custom and short-run projects. Versatility in punching, shearing, and notching makes these machines indispensable for metal fabricators globally.
- Heavy Equipment Production:The manufacturing of construction machinery and mining equipment requires high-tonnage ironworkers for processing thick steel plates and structural components. This sector drives demand for robust and durable machines capable of continuous operation.
- Shipbuilding:Large-scale shipbuilding operations require powerful ironworkers to process heavy steel plates and profiles for hull construction and structural components.
- Construction Equipment:This segment uses ironworkers for fabricating frames, brackets, and other metal parts for excavators, loaders, and other construction vehicles.
- Agricultural Tools:Ironworkers are essential in manufacturing and repairing agricultural implements, demanding machines capable of handling various metal thicknesses and shapes.
Metal Fabrication Shops represent the broadest user base. Heavy Equipment Production drives demand for high-capacity units.
End User:
Different end-user segments exhibit varied purchasing power and prioritize distinct machine features, impacting manufacturer margins. Original Equipment Manufacturers (OEMs) often seek integrated, high-volume solutions, while smaller fabricators prioritize cost-effectiveness and versatility.
- Fabricators:Independent and contract metal fabricators constitute the primary end-user group, requiring versatile ironworkers for diverse job shop operations. Their purchasing decisions often balance initial cost with machine flexibility and reliability.
- OEMs:Original Equipment Manufacturers integrate ironworkers into their production lines for fabricating components of larger machinery, such as agricultural or construction equipment. OEMs prioritize precision, automation, and seamless integration with existing manufacturing processes.
- Maintenance Workshops:These workshops use ironworkers for repair, refurbishment, and custom part creation for various industrial and commercial equipment.
- Defense Equipment Makers:Manufacturers in the defense sector require ironworkers that meet stringent specifications for strength, durability, and precision in component fabrication.
- Tool Manufacturers:Companies producing hand tools, machine tools, and specialized implements utilize ironworkers for shaping and cutting raw metal stock.
Fabricators constitute the largest purchasing group. OEMs increasingly seek integrated solutions from suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-led infrastructure initiatives, including the US Infrastructure Investment and Jobs Act, significantly stimulate demand for fabricated structural steel across global markets. These projects require robust hydraulic ironworker machines for processing heavy steel profiles and plates. The industry responds with advanced CNC-controlled systems to meet stringent precision requirements.
United States
The US Infrastructure Investment and Jobs Act drives substantial demand for high-capacity ironworkers in construction and heavy equipment production. OSHA standards dictate rigorous safety features, influencing machine design and adoption across American fabrication shops. Industrial clusters in states like Texas and Ohio utilize these versatile machines for energy sector projects and automotive component manufacturing.
China
China's massive manufacturing base and ongoing infrastructure expansion efforts fuel significant demand for hydraulic ironworker machines. GB standards enforce specific performance and safety criteria for machinery entering the Chinese market, promoting localization efforts. Major industrial hubs in the Yangtze River Delta actively deploy advanced ironworkers for shipbuilding and construction equipment fabrication.
Germany
German automotive and aerospace sectors require high-precision hydraulic ironworkers for complex component manufacturing. CE marking compliance is a mandatory prerequisite for market access, ensuring machines meet strict European safety and performance criteria. Manufacturing centers in Bavaria and Baden-Württemberg leverage CNC-controlled systems for advanced metal processing applications.
India
India's rapid urbanization and government-backed infrastructure projects, including the PLI scheme for manufacturing, boost demand for robust ironworker machines. BIS standards guide the quality and safety of industrial machinery, supporting domestic production and market growth. Fabrication clusters in Gujarat and Maharashtra increasingly integrate these machines for construction and agricultural equipment production.
Japan
Japanese heavy equipment and shipbuilding industries prioritize durable hydraulic ironworkers capable of processing high-strength steel alloys. JIS standards ensure the quality and reliability of manufacturing equipment, reflecting Japan's focus on precision engineering. Industrial zones around Tokyo and Osaka adopt advanced ironworkers for automotive chassis and structural steel fabrication.
Global Hydraulic Ironworker Machine Market Key Industry Players
Listed leaders compete with private specialists across the hydraulic ironworker machine market, creating a tiered structure. The market exhibits consolidation in high-end, CNC-controlled segments, where technological innovation is paramount, while fragmented players serve regional and niche markets. Strategic archetypes include global technology innovators, who push automation boundaries, regional specialists with established distribution, and cost-focused generalists catering to broader demand. Companies pursue portfolio diversification and geographic expansion as dominant competitive moves to capture market share and enhance customer reach.
Among the prominent global manufacturers, Scotchman Industries Inc. exemplifies a regional specialist, leveraging its established distribution network in North America for diverse fabrication needs. GEKA Group occupies a position as a high-capacity automation provider, specializing in integrated systems for structural steel fabrication applications requiring significant throughput. ERMAKSAN represents a technology innovator, focusing its offerings on advanced CNC-controlled machines to meet evolving industry demands for precision and efficiency. These companies anchor distinct market segments through their specialized product development and strategic customer engagement, influencing competitive dynamics.
| Leading Market Players |
|---|
| Piranha |
| Prada Nargesa S.L. |
| Scotchman Industries Inc. |
| ERMAKSAN |
| HARSLE |
| GEKA Group |
| DARAMCO |
| Cleveland Steel Tool |
| Edwards Manufacturing |
| Others |
Cost & Logistics Intelligence
The proliferation of advanced high-strength steel alloys simultaneously reshapes supply geography and pricing economics for hydraulic ironworker machines. This material shift necessitates more capable machinery, impacting component sourcing and driving value-based pricing for specialized units.
Pricing Analysis
Certification level (CE marking, GB standards, JIS) creates the primary spread in hydraulic ironworker machine pricing. The dominant pricing model is per-unit transactional, reflecting the capital equipment nature of these machines. Price differentiation stems from hydraulic tonnage capacity and the level of CNC automation integrated into the system. Pricing pressure stems from the availability of cost-effective manual units in developing markets. Smaller metal fabrication shops typically exhibit the highest price sensitivity, often opting for more basic or floor-mounted models.
Supply Chain Analysis
Logistics chokepoints for heavy machinery components underwrite the regional concentration of manufacturing facilities. Supply concentration for critical components like advanced hydraulic systems and CNC controllers centers in Germany, Japan, and China. Raw material dependencies include high-grade steel for machine frames and specialized electronic components for automation systems. Single-source vulnerability for specific high-precision parts represents a structural supply chain risk. Distribution primarily runs through established regional dealer networks and direct sales channels for larger OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for hydraulic ironworker machines currently faces a capability gap, particularly in integrating advanced automation with operator skill sets. This scarcity necessitates strategic interventions to bridge the talent and technology divide for efficient utilization.
For Market Incumbents: Compound existing strengths in precision engineering and established distribution networks. Invest in R&D to further integrate advanced sensor technology and IIoT platforms, countering the threat of substitution from laser and plasma cutting systems. Focus on developing comprehensive training programs to address the skilled operator scarcity. Pursue strategic acquisitions of software firms specializing in fabrication process optimization.
For New Entrants and Emerging Players: Differentiate on software-driven versatility and robust after-sales support. Target underpenetrated emerging markets in Southeast Asia and Latin America, where industrialization drives demand for foundational fabrication equipment. A strong go-to-market angle involves offering modular, upgradeable CNC systems paired with accessible financing options for smaller fabrication shops. Focus on niche applications like renewable energy component fabrication.
For Investors and Strategic Acquirers: Capital is best deployed toward technology innovators specializing in advanced CNC integration and IIoT solutions. The long-term viability of this market hinges on the ongoing shift towards intelligent, automated manufacturing processes. Acquire companies with strong intellectual property in software-defined controls or those with established market access in rapidly industrializing economies. Watch for increasing regulatory mandates for operator safety as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software & IIoT Integration | Enhances operational visibility and predictive maintenance for metal fabrication shops. |
| CNC System R&D | Drives precision and automation, meeting demands from aerospace and automotive sectors. |
| Emerging Market Expansion | Captures new demand in industrializing economies like India and Southeast Asia. |
| Advanced Safety Feature Development | Ensures compliance with global standards like CE marking and OSHA, gating market entry. |
| High-Strength Steel Processing Capacity | Addresses the growing requirement for machinery capable of handling new steel alloys. |
Research Approach
Initial hypotheses were tested against primary input from metal fabrication shop owners, heavy equipment production managers, CNC machine engineers, and safety compliance officers, and refined through iterative feedback. This approach combined in-depth primary interviews with rigorous secondary data validation. Secondary sources included manufacturing association reports, government industrial statistics, patent databases, and equipment manufacturer annual reports, triangulating insights from multiple perspectives.
The variance-decomposition analytical framework was applied to project market trajectories across the analysis window. Segmentation dimensions modeled included product type (CNC controlled, floor-mounted), technology (hydraulic, electro-hydraulic), application (metal fabrication shops, heavy equipment production), end-user (fabricators, OEMs), and regional industrialization level. Compound annual growth rates were derived from historical trends and future projections, integrating infrastructure spending commitments and high-strength steel production volumes as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant shifts in global trade policies or rapid advancements in competing technologies would require recalibration. Forecasts reflect assumptions regarding economic stability and technological adoption rates. Practitioners should keep alternative scenarios live as regulatory mandates and material science innovations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market