
 Pipe Anti-Corrosion Tape Market | 2026-2036
Pipe Anti-Corrosion Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Anti-Corrosion Tape Market Insights
Skilled applicator labor availability is reorganizing how contractors bid on large-diameter pipeline projects across North America and the Middle East. 3M Company leverages its polymer science depth to supply multi-layer tape systems for subsea and buried installations. Nitto Denko Corporation anchors its position through controlled-thickness manufacturing that meets Japanese industrial standards for gas distribution networks. Berry Global Inc. competes on scale, operating extrusion facilities that feed construction and utility channels across multiple continents.
Pipe anti-corrosion tape comprises polymer-backed adhesive membranes, typically 0.25 mm to 2.0 mm thick, engineered to block moisture ingress and electrochemical degradation on steel, ductile iron, or concrete substrates. Manufacturers apply butyl rubber or polyolefin hot-melt adhesives onto polyethylene or polyvinyl chloride carrier films, then calibrate peel strength and cathodic disbondment resistance for specific service temperatures and soil chemistries. Polyethylene tapes lead volume due to their balance of flexibility, UV resistance, and compatibility with mechanical wrapping equipment on field joints. Bituminous tapes retain share in below-ground water pipelines where low-cost, hand-applied solutions suffice and installation budgets constrain material selection. Gas pipeline applications command premium positioning because operators specify high-performance cold-applied systems that eliminate the fire hazards of hot enamel coating in hydrocarbon-rich environments.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces coating integrity rules that mandate regular assessment and repair of external corrosion protection on interstate pipelines. In Europe, CE marking under the Construction Products Regulation and adherence to EN 12068 standards govern tape performance claims for buried steel pipelines, creating compliance costs that favor established suppliers with notified body certifications. ISO 21809-3 provides a global reference for field joint coatings, including tape systems, that national regulators in the Middle East and Asia-Pacific increasingly adopt into procurement specifications. Stakeholders must monitor how carbon accounting requirements and low-emission construction mandates reshape material specifications and supplier qualification criteria for pipeline infrastructure programs.
Market Dynamics
Aging pipeline infrastructure across North American shale basins and Middle Eastern export corridors is forcing operators to accelerate tape replacement cycles while regulators tighten coating integrity mandates.
Growth Catalysts
- PHMSA coating integrity rules:US interstate pipeline operators must assess and repair external corrosion protection on defined schedules, sustaining replacement demand for certified tape systems.
- Polyethylene tape flexibility:Compatibility with mechanical wrapping equipment on field joints reduces labor hours and accelerates project completion for large-diameter installations.
- Gas distribution networks:Japanese industrial standards for cold-applied systems eliminate hot enamel fire hazards in hydrocarbon-rich environments, expanding specification of butyl rubber adhesives.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polyolefin resin prices swing with crude oil benchmarks, compressing margin visibility for extrusion-based manufacturers.
- Skilled applicator scarcity:North American contractors face labor shortages for certified tape installation on large-diameter projects, extending bid timelines and inflating field costs.
- Bituminous tape substitution ceiling:Low-cost hand-applied solutions retain share in municipal water rehabilitation where budgets constrain material upgrades to polymer-backed systems.
Strategic Opportunities
- Subsea installation expansion:Offshore pipeline projects in the Middle East require multi-layer tape systems engineered for high-pressure, saline environments with extended design life.
- Carbon accounting integration:Low-emission construction mandates in European infrastructure programs favor suppliers with verified lifecycle assessments and notified body certifications under EN 12068.
- Digital procurement platforms:Utility aggregators in the United States are consolidating tape purchasing through centralized vendor qualification systems, favoring scaled manufacturers with national distribution.
Industry Challenges
- Certification timeline compression:ISO 21809-3 adoption across Asia-Pacific procurement specifications requires suppliers to synchronize testing protocols with multiple national regulators simultaneously.
- Cathodic disbondment testing capacity:Limited third-party laboratory availability for accelerated aging validation creates bottlenecks for new product qualification in high-temperature service categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Anti-Corrosion Tape Market |
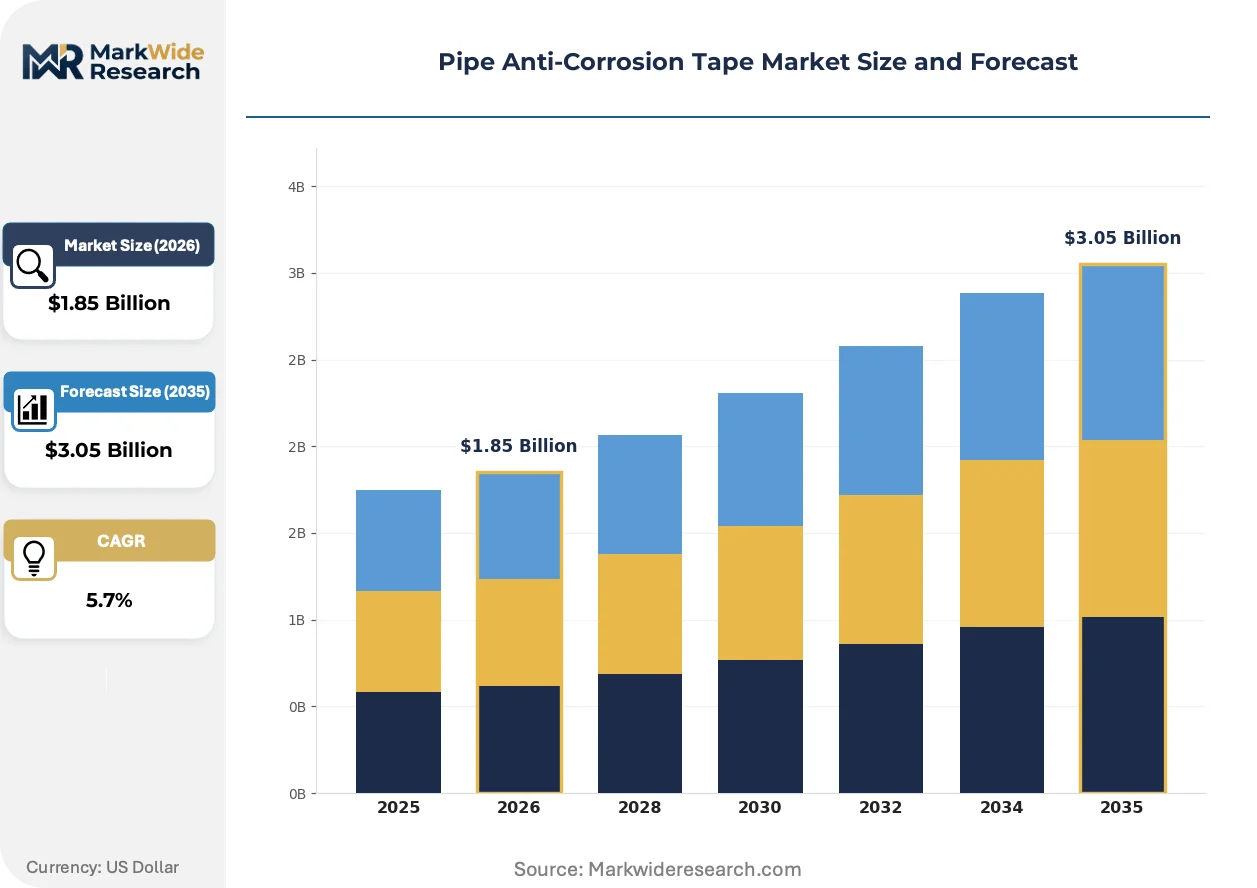
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinyl Chloride, Bituminous, Others Application: Water Pipelines, Oil Pipelines, Chemical Pipelines, Gas Pipelines End User: Construction, Oil & Gas, Chemical Manufacturing, Utilities Installation Type: Above Ground, Below Ground, Indoor, Outdoor |
| Companies Covered | 3M Company, Nitto Denko Corporation, Berry Global Inc., Shurtape Technologies, LLC, Tesa SE, Avery Dennison Corporation, Scapa Group plc, Coroplast Fritz Müller GmbH & Co. KG, Jining Xunda Pipe Coating Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Anti-Corrosion Tape Market Trends and Innovations
Material science advances and regulatory digitization are restructuring how tape specifications propagate through pipeline engineering workflows and contractor procurement decisions.
Multi-layer tape systems integrating viscoelastic inner layers with mechanical outer wraps are bifurcating performance expectations between standard field joint applications and extreme-service subsea installations. Offshore operators in the Middle East specify these configurations for design lives exceeding thirty years, while onshore utilities in the United States prioritize cost-optimized single-layer polyethylene for gathering line rehabilitation. This technical divergence is compressing mid-tier product positioning and forcing manufacturers to commit capital to either premium subsea qualification or high-volume extrusion scale.
CE marking under the Construction Products Regulation now governs tape performance claims for buried steel pipelines across European Union member states, creating compliance costs that favor established suppliers with notified body relationships. The regulation mandates traceable documentation of peel strength and cathodic disbondment resistance, which engineering procurement departments are embedding into digital vendor scorecards. Water utility frameworks in Germany and France have responded by consolidating supplier panels to reduce audit burden, concentrating specification authority among pre-qualified manufacturers.
Buyer concentration through utility cooperative purchasing organizations is displacing fragmented distributor networks in North American municipal water rehabilitation. Regional purchasing alliances in Texas and California now negotiate master service agreements for tape procurement across multiple construction seasons, compressing pricing cycles and demanding inventory guarantees from manufacturers. This channel consolidation is most visible in standard polyethylene grades where product differentiation is minimal and logistics reliability determines contract awards.
Pipe Anti-Corrosion Tape Market Segmentation
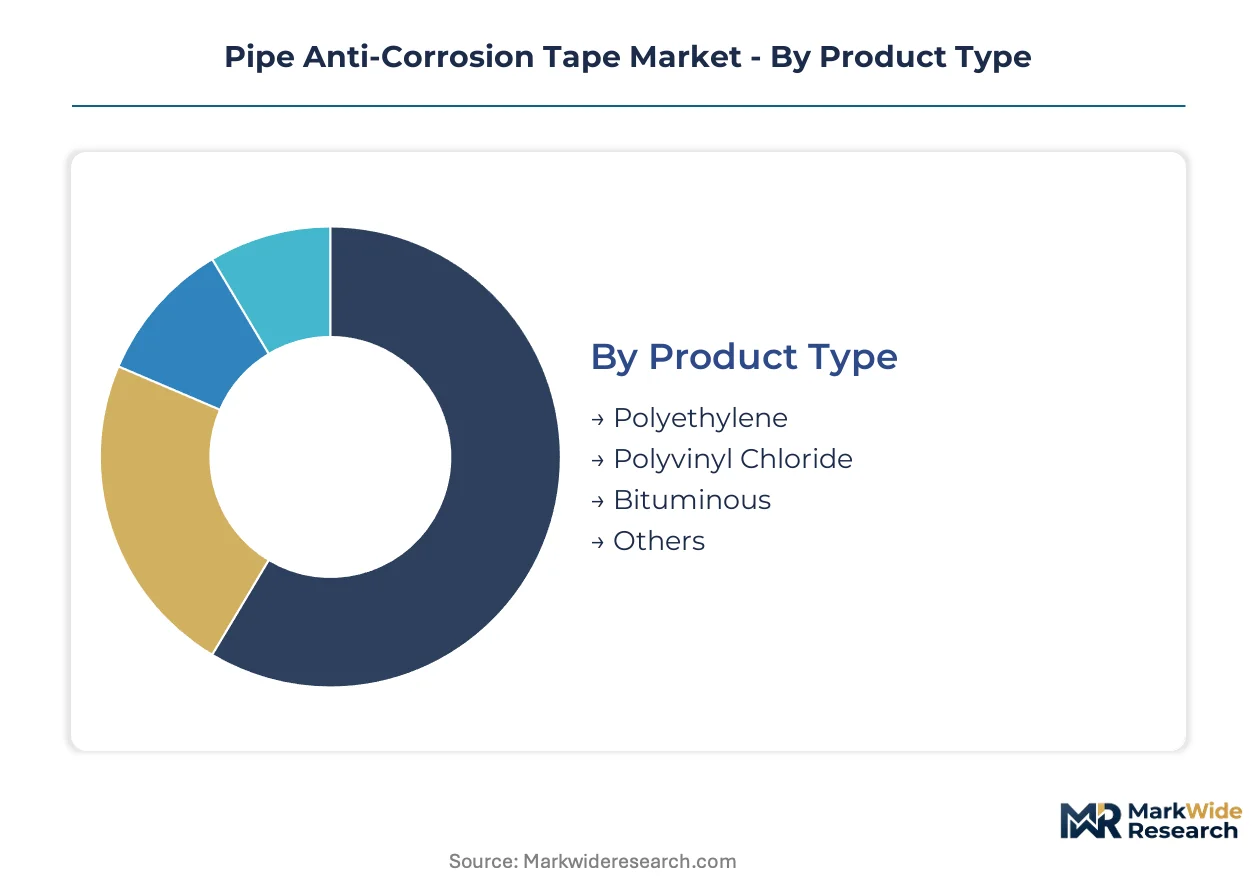
Segmentation in pipe anti-corrosion tape markets determines procurement specifications, installation protocols, and channel economics. Product chemistry, application environment, and installation method each create distinct margin structures and certification requirements that reshape supplier positioning.
Product Type:
Channel mix varies sharply by polymer chemistry, with polyethylene and bituminous tapes flowing through divergent distribution networks.
- Polyethylene:Multi-layer extruded films with butyl rubber adhesives dominate mechanical wrapping equipment compatibility. Demand concentrates in United States shale field gathering lines where PHMSA coating integrity rules mandate certified cold-applied systems on interstate pipelines.
- Bituminous:Coal-tar or asphalt-based compounds saturated into fabric carriers serve hand-applied municipal water rehabilitation. Budget constraints in below-ground water infrastructure sustain this segment despite inferior cathodic disbondment resistance.
- Polyvinyl Chloride:Rigid carrier films with aggressive adhesives suit indoor chemical processing environments where UV exposure is absent.
- Others:Viscoelastic and hybrid polymer formulations address niche subsea specifications in Middle Eastern offshore developments.
Polyethylene dominates installed base. Viscoelastic hybrids are where expansion concentrates.
Application:
Cost tier stratification separates premium-specified gas infrastructure from price-sensitive water networks.
- Gas Pipelines:High-performance cold-applied systems eliminate hot enamel fire hazards in hydrocarbon-rich environments. Japanese industrial standards and PHMSA interstate rules drive specification of butyl rubber adhesives with extended design life validation.
- Water Pipelines:Municipal rehabilitation programs prioritize low-cost hand-applied solutions where installation budgets constrain material selection to bituminous or single-layer polyethylene grades.
- Oil Pipelines:Crude transport specifications balance chemical resistance with mechanical damage protection across gathering and trunk line segments.
- Chemical Pipelines:Process plant applications demand solvent-resistant adhesive formulations for aggressive media containment.
Water pipelines dominate installed base. Gas pipelines are climbing the fastest.
End User:
Customer type determines contract structure, with utilities consolidating procurement through cooperative purchasing organizations.
- Oil & Gas:Majors and midstream operators specify multi-layer systems with ISO 21809-3 qualification for field joint coatings on export corridors.
- Utilities:Regional purchasing alliances in Texas and California negotiate master service agreements across construction seasons, compressing pricing cycles.
- Construction:General contractors bid on infrastructure rehabilitation with labor availability constraints extending project timelines.
- Chemical Manufacturing:Plant operators specify tape systems compatible with process safety management and hazardous area classifications.
Oil and gas dominates installed base. Utility cooperative purchasing is where specification authority concentrates.
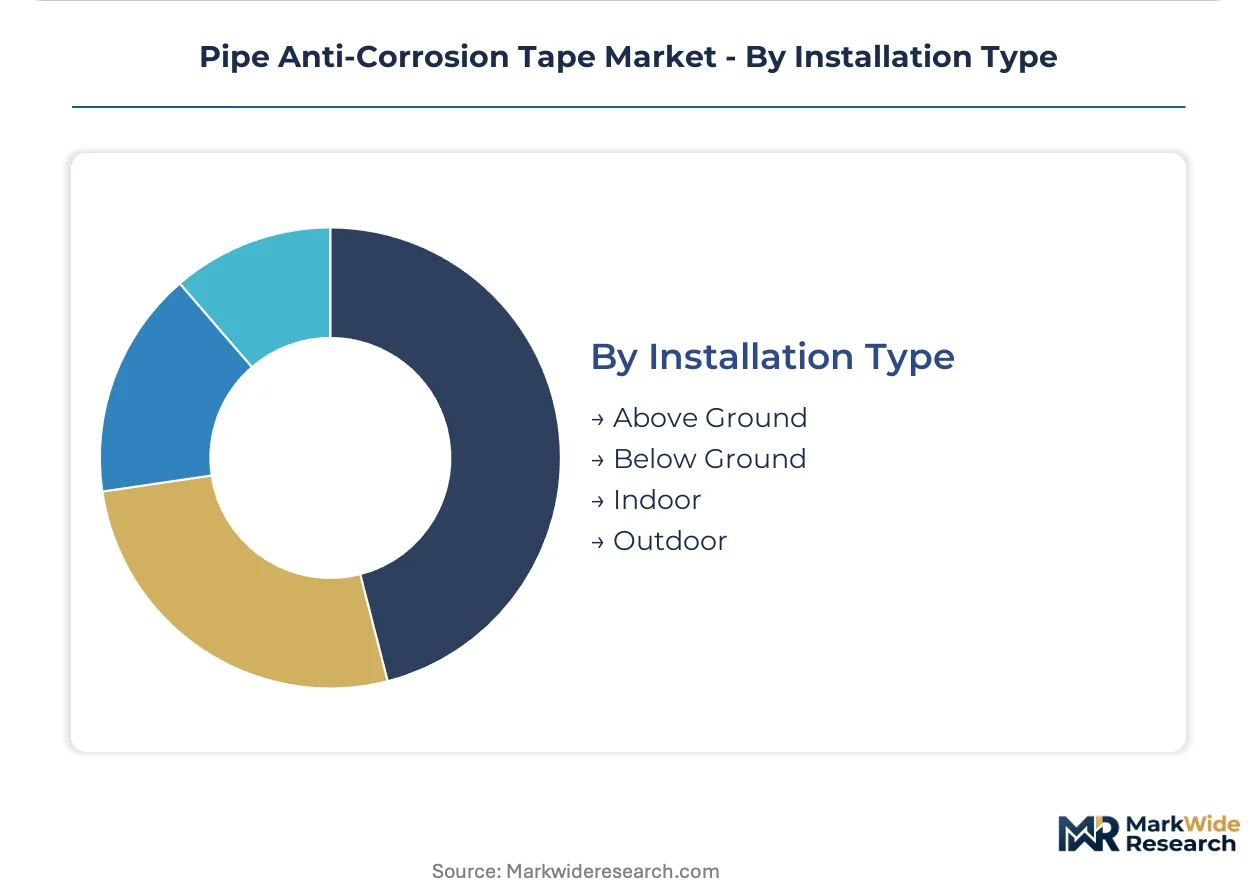
Installation Type:
Volume distribution tracks infrastructure age, with below-ground rehabilitation outpacing new above-ground construction.
- Below Ground:Buried steel pipelines require cathodic protection compatibility and soil chemistry calibration for peel strength performance. North American shale basins and Middle Eastern export corridors drive replacement cycles.
- Above Ground:Elevated piping in processing facilities prioritizes UV-resistant outer wraps with simplified inspection access.
- Outdoor:Exposed installations combine weathering resistance with mechanical damage protection for gathering line segments.
- Indoor:Controlled environment applications reduce specification complexity, focusing on chemical resistance and fire safety ratings.
Below ground dominates installed base. Subsea and deep burial specifications are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States favors mechanical wrapping equipment for shale field gathering lines, while Germany prioritizes CE-marked systems for buried steel pipelines, and Japan specifies cold-applied butyl rubber adhesives for gas distribution networks.
United States
Shale basin infrastructure aging drives replacement cycles across Texas and North Dakota oil fields. PHMSA coating integrity rules mandate certified tape systems on interstate pipelines with defined assessment schedules. Regional purchasing alliances in California and Texas consolidate procurement through master service agreements.
Germany
Water utility frameworks prioritize EN 12068-compliant systems for municipal rehabilitation programs. CE marking under the Construction Products Regulation mandates traceable documentation of peel strength and cathodic disbondment resistance. Industrial clusters in North Rhine-Westphalia concentrate specification authority among pre-qualified manufacturers.
Japan
Gas distribution network expansion specifies cold-applied systems eliminating hot enamel fire hazards. METI industrial standards govern controlled-thickness manufacturing for butyl rubber adhesives. Manufacturing concentration in the Kansai region supplies domestic distribution networks with precision-calibrated products.
Saudi Arabia
Offshore pipeline developments in the Arabian Gulf require multi-layer tape systems for high-pressure saline environments. SFDA and national procurement specifications increasingly adopt ISO 21809-3 for field joint coatings. Eastern Province industrial zones anchor subsea installation demand from export corridor operators.
China
Petrochemical infrastructure expansion sustains demand for polyethylene-backed systems across Sichuan-Chongqing shale plays. GB standards and MIIT regulations govern material specifications for buried steel pipelines. Yangtze River Delta manufacturing bases supply domestic mechanical wrapping equipment compatibility.
Pipe Anti-Corrosion Tape Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the pipe anti-corrosion tape market. Polymer science depth separates manufacturers capable of multi-layer subsea qualification from extrusion-scale competitors serving municipal water rehabilitation. Three archetypes dominate: diversified materials conglomerates with adhesive technology platforms, regional specialists with notified body certifications for European compliance, and scale-driven extrusion operators feeding utility cooperative purchasing channels. Competitive moves concentrate on capacity expansion for mechanical wrapping equipment compatibility and strategic partnerships with offshore engineering contractors.
Among diversified materials conglomerates, 3M Company and Nitto Denko Corporation occupy positions defined by polymer science capabilities and controlled-thickness manufacturing expertise. Berry Global Inc. exemplifies the scale-driven archetype with multi-continent extrusion facilities. These three represent the vertical tiering between premium subsea qualification and high-volume construction channel supply.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| Berry Global Inc. |
| Shurtape Technologies, LLC |
| Tesa SE |
| Avery Dennison Corporation |
| Scapa Group plc |
| Coroplast Fritz Müller GmbH & Co. KG |
| Jining Xunda Pipe Coating Materials Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Extrusion capacity utilization above eighty percent in United States Gulf Coast facilities creates margin leverage for polyethylene tape manufacturers serving PHMSA-mandated interstate pipeline programs. Scale economies in butyl rubber compounding anchor price floors for multi-layer systems, while hand-applied bituminous grades compete on raw material arbitrage from coal-tar derivatives.
Pricing Analysis
Long-term offtake agreements dominate procurement for oil and gas majors specifying ISO 21809-3 qualified systems, compressing spot market liquidity for premium grades. Three-tier pricing structure across premium, standard, and economy levels separates subsea multi-layer configurations from single-layer polyethylene and commodity bituminous wraps. Pricing pressure stems from petrochemical feedstock volatility swinging with crude benchmarks, squeezing margin visibility for extrusion-based manufacturers. Municipal water utilities exhibit highest price sensitivity, constraining material selection to hand-applied grades, while offshore operators in the Middle East absorb premium positioning for extended design life validation.
Supply Chain Analysis
Inventory lead times for butyl rubber adhesives stretch during peak construction seasons in North American shale basins, forcing contractors to pre-position material ahead of PHMSA assessment windows. Manufacturing concentrates in the United States, Germany, and Japan, with each hub serving distinct regulatory certification clusters. Raw material dependencies center on polyethylene resin, synthetic rubber feedstocks, and polyolefin hot-melt compounds. Single-source vulnerability concentrates in specialty adhesive formulations qualified for subsea cathodic disbondment resistance. Distribution runs through utility cooperative purchasing organizations consolidating procurement across multiple construction seasons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHMSA coating integrity digitization and ISO 21809-3 adoption across Middle Eastern procurement specifications are accelerating qualification timelines, compressing competitive windows for established and emerging suppliers alike.
For Market Incumbents: Fortify notified body relationships under EN 12068 and CE marking frameworks to defend specification authority in European water utility panels. Expand extrusion capacity in Texas and North Dakota to capture regional purchasing alliance consolidation. Counter skilled applicator scarcity through automated mechanical wrapping equipment partnerships that reduce field labor dependence.
For New Entrants and Emerging Players: Certification fast-track through ISO 21809-3 pre-qualification testing opens specification access in Saudi Arabian offshore developments. Target subsea viscoelastic hybrid formulations where mid-tier positioning has compressed and incumbent capital commitments lag. Pursue joint development agreements with offshore engineering contractors lacking captive tape supply.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with dual capability in premium subsea qualification and high-volume extrusion scale. Five-to-ten year viability hinges on carbon accounting integration and low-emission construction mandate alignment. Watch for cathodic disbondment testing capacity expansion as signal of qualification bottleneck resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-layer Subsea Qualification | ISO 21809-3 certification unlocks Arabian Gulf offshore project specifications. |
| Backward Integration into Adhesive Compounding | Captive butyl rubber supply insulates margins from petrochemical volatility. |
| Utility Cooperative Purchasing Alignment | Master service agreements with Texas and California alliances secure multi-season volume. |
| Automated Mechanical Wrapping Equipment Partnership | PHMSA-mandated assessment schedules favor labor-reducing installation technology. |
| CE Marking and EN 12068 Certification Investment | Notified body relationships concentrate specification authority in German water utility panels. |
Research Methodology
The analysis maps polyethylene, bituminous, polyvinyl chloride, and viscoelastic hybrid sub-sectors, each validated through pipeline engineering directors, coating applicator contractors, utility procurement managers, and regulatory compliance officers. Primary interviews with PHMSA-certified inspectors and notified body certification specialists combined with secondary validation from NACE International standards documentation, EN 12068 compliance databases, and customs trade records. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled product chemistry, application environment, installation method, and end-user contract structure dimensions. CAGRs derived from segment-level growth rate reconciliation with infrastructure replacement cycle timing and regulatory mandate phase-in schedules. Forecast inputs incorporated shale basin gathering line age profiles and offshore project development pipelines.
Underlying assumptions cover PHMSA enforcement continuity, ISO 21809-3 adoption trajectory, and petrochemical feedstock price band stability, with deviation risk concentrated in skilled labor availability shocks and carbon accounting mandate acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Wing Walk Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Building and Construction Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Reflective Tape Market
Tapes
Sterilization Tape Market
Tapes
High Bond Tape Market
Tapes
North America Packaging Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Flatback Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
Heat Release Tape Market
Tapes
Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Non-UV Dicing Tapes Market