
 Hand and Power Tools Market | 2026-2036
Hand and Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Hand and Power Tools Market Analysis
Tool-as-a-service subscription models and software-enabled diagnostics is broadening revenue streams beyond one-time hardware sales. Stanley Black & Decker leverages its service network to lock in recurring maintenance contracts with commercial fleets. Techtronic Industries anchors its growth in battery platform stickiness across the Milwaukee and Ryobi ecosystems. Makita competes through deep vertical integration in motor manufacturing and strict quality control over its Asian supply base.
Hand and power tools encompass manually operated implements and motor-driven devices, typically constructed from chrome-vanadium steel or sintered carbide, designed to cut, fasten, shape, or finish materials across industrial and consumer tasks. Cordless power tools now dominate capital expenditure in the construction end user segment, as lithium-ion platforms displace pneumatic alternatives on job sites. Hand tools retain margin concentration in the automotive repair application, where precision tolerances and durability requirements sustain premium pricing for forged alloy products. The woodworking application shows fastest growth in multi-functional tool features, driven by hobbyist DIY enthusiasts seeking space-efficient equipment.
OSHA workplace safety mandates and the EPA's hazardous waste disposal rules shape product design and end-of-life obligations for US manufacturers. The EU's REACH chemicals framework restricts certain coatings and alloys, forcing suppliers to reformulate surface treatments for European market access. China's GB standards for electrical safety and the NMPA's equipment certification requirements create compliance thresholds that filter smaller exporters. Stakeholders must monitor battery platform interoperability standards and evolving carbon-border adjustments that could restructure sourcing economics.
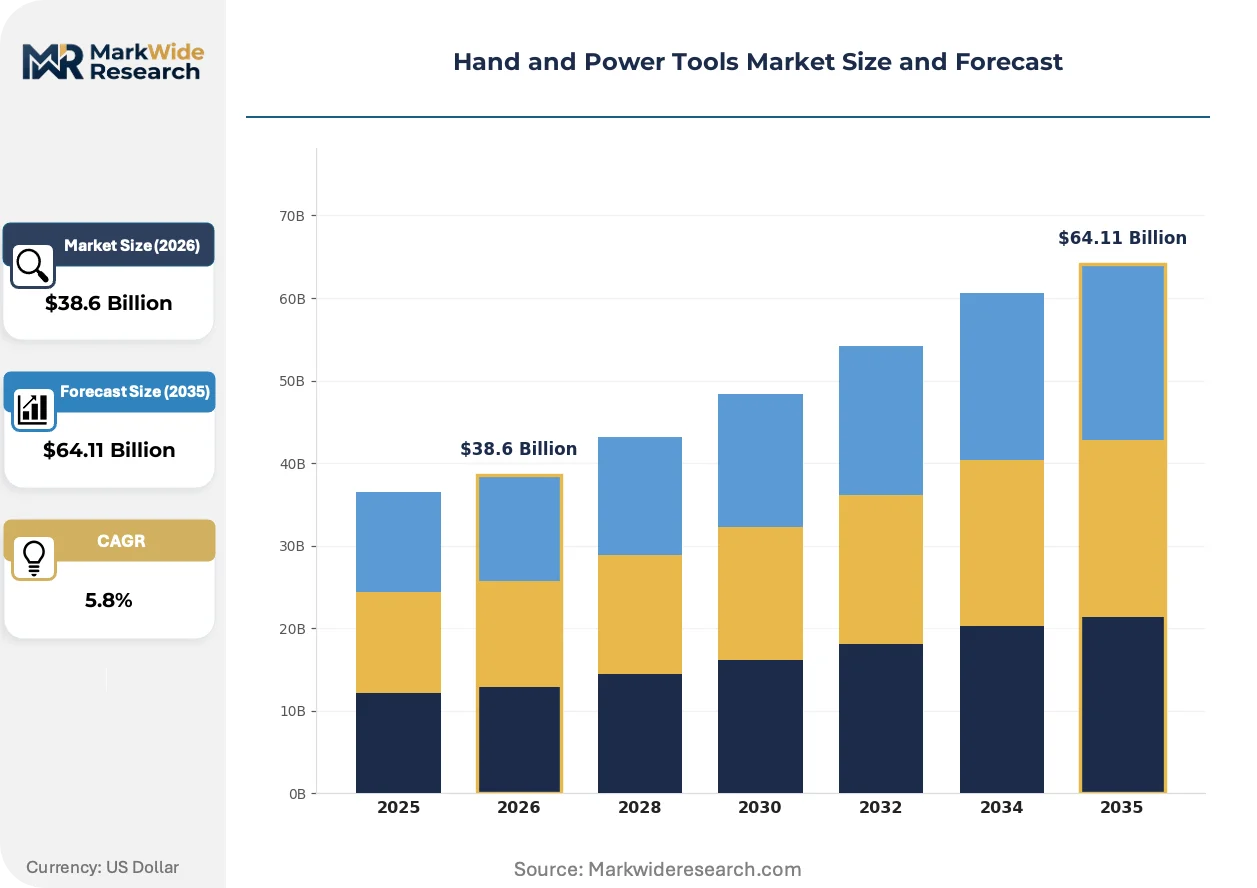
Market Dynamics
China's manufacturing scale concentration and lithium-ion battery platform standardization are compressing supplier margins while locking end-users into interoperable ecosystems across cordless power tools.
Growth Catalysts
- OSHA Silica Dust Rule:US construction contractors face mandated dust extraction on job sites, accelerating demand for integrated vacuum systems in angle grinders and rotary hammers.
- Automotive Fleet Electrification:EV assembly plants in Germany and the United States require precision torque tools with data-logging capabilities for battery pack installation.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are extending cordless runtime to full-shift coverage, displacing pneumatic lines in commercial framing operations.
Market Restraints
- Rare Earth Magnet Supply:Neodymium price volatility and China's export licensing regime for processed rare earths constrain brushless motor production scheduling.
- REACH Substance Restrictions:The EU's chromium VI ban in surface coatings forces reformulation of chrome-plated hand tools, extending certification timelines for European market entry.
- Pneumatic Tool Installed Base:Existing compressed air infrastructure in North American auto plants creates switching cost barriers for full cordless conversion.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for capital goods assembly attract toolmakers seeking tariff-advantaged export platforms to Southeast Asia and Africa.
- Tool-as-a-Service Models:Subscription-based equipment provisioning with predictive maintenance analytics opens recurring revenue streams among commercial facility management fleets.
- Battery Platform Stickiness:Cross-tool compatibility within voltage ecosystems creates captive aftermarket demand for bare-tool expansion among DIY and pro-sumer segments.
Industry Challenges
- Certification Backlogs:UL and TÜV testing queue delays for new battery platforms extend product launch windows by six to nine months.
- Field Technician Shortage:Declining enrollment in industrial maintenance programs constrains service network expansion for diagnostics-enabled tool fleets.
- Legacy System Integration:Construction ERP software lacks native APIs for tool telemetry data, forcing middleware development for fleet management dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand and Power Tools Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Pneumatic Tools, Gardening Tools End User: Construction, Manufacturing, DIY Enthusiasts, Maintenance Services Tool Feature: Wireless, Ergonomic, Multi-Functional, Corded Application: Woodworking, Metalworking, Automotive Repair, Home Improvement |
| Companies Covered | Makita, Koki Holdings, Stanley Black & Decker, Husqvarna Group, Festool, Techtronic Industries, Hilti, Ingersoll Rand, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand and Power Tools Market Emerging Trajectories
Intelligent tool connectivity and predictive maintenance algorithms are transforming capital equipment from depreciating assets into data-generating nodes within operational workflows.
Brushless DC motor control systems are automating torque feedback and stall prevention in real time. Commercial electricians in the United States and Germany are specifying these platforms for conduit installation where precision prevents material waste. The technology is automating quality assurance steps previously requiring manual verification, compressing job completion timelines on fixed-bid contracts.
The EU's F-Gas Regulation phase-down is restricting hydrofluorocarbon refrigerants in cooling systems for battery charging stations. Tool manufacturers with European distribution must redesign thermal management for fast-charge docks. The construction end-use segment is responding by specifying air-cooled alternatives that eliminate sealed refrigeration circuits entirely.
Buying committees at national home improvement retailers now mandate connected inventory tracking for power tool assortments. Vendor-managed replenishment with RFID-enabled loss prevention is displacing traditional purchase-order procurement in the North American retail channel. The shift is most visible in seasonal tool category resets where real-time sell-through data determines shelf space allocation.
Hand and Power Tools Market Segmentation
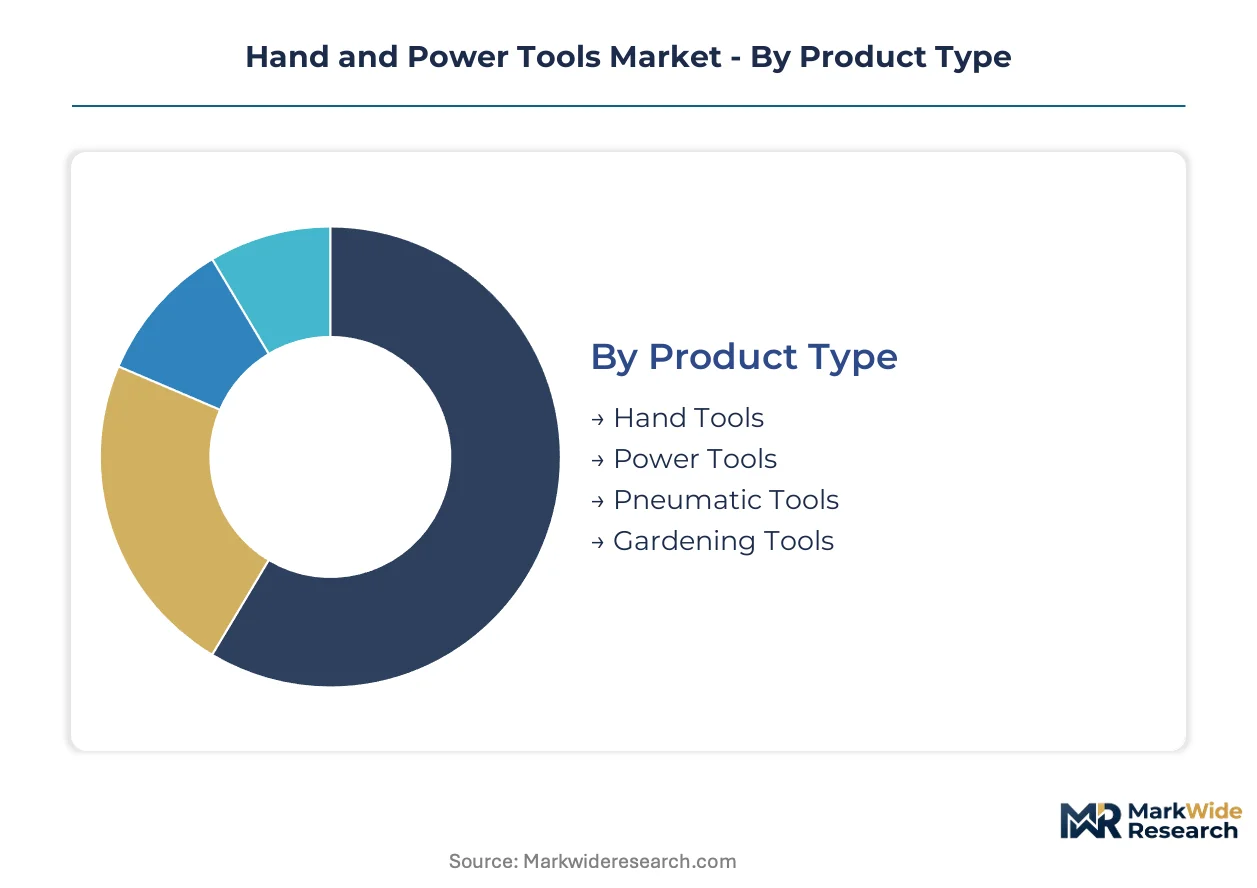
Segmentation in the hand and power tools market reveals how specification requirements diverge across professional versus consumer use cases. Battery platform ecosystems, torque precision demands, and workspace mobility constraints create distinct purchasing logics that reshape product development priorities.
Product Type:
Lithium-ion cell density and brushless motor efficiency separate high-performance cordless platforms from legacy alternatives.
- Power Tools:Brushless DC motor systems with variable speed triggers and electronic clutch mechanisms dominate commercial job sites. Demand concentrates in residential construction across the United States, where OSHA silica dust rules mandate integrated vacuum extraction in rotary hammers and angle grinders.
- Hand Tools:Chrome-vanadium and sintered carbide compositions deliver precision tolerances for torque-critical applications. Automotive repair shops in Germany sustain premium pricing for forged alloy ratchets and torque wrenches with calibration certification.
- Pneumatic Tools:Compressed air systems retain installed base in North American auto assembly plants where existing infrastructure creates switching cost barriers.
- Gardening Tools:Cordless lithium-ion platforms displace two-stroke engines in consumer lawn maintenance, with battery stickiness driving bare-tool expansion.
Mature deployment sits with pneumatic systems in legacy manufacturing. Newer deployment is concentrated in cordless power tools with cross-platform battery compatibility.
End User:
Procurement authority and total cost of ownership calculations split volume across institutional buyers versus discretionary purchasers.
- Construction:Fleet operators specify tool-as-a-service contracts with predictive maintenance analytics. Demand clusters with commercial framing contractors in the United States replacing pneumatic lines for full-shift cordless coverage.
- Manufacturing:EV assembly plants in Germany require data-logging torque tools for battery pack installation with traceability compliance.
- DIY Enthusiasts:Hobbyist woodworkers prioritize space-efficient multi-functional equipment with voltage ecosystem stickiness.
- Maintenance Services:Facility management fleets adopt subscription-based equipment provisioning to convert capital expenditure to operational budgets.
Volume concentration rests with construction contractors. Margin expansion is climbing the fastest in manufacturing precision applications.
Tool Feature:
Ergonomics and connectivity specifications now filter assortment decisions at national home improvement retailers.
- Wireless:Battery platforms with RFID-enabled inventory tracking satisfy vendor-managed replenishment mandates. Retail buyers in North America now require connected sell-through data for shelf space allocation.
- Ergonomic:Anti-vibration handles and balanced weight distribution reduce repetitive strain injuries. Commercial electricians in Germany specify these platforms for conduit installation where precision prevents material waste.
- Multi-Functional:Modular head systems and interchangeable attachments address space constraints in urban workshops.
- Corded:Continuous power delivery retains niche in stationary metalworking where runtime certainty outweighs mobility.
Established specification dominance belongs to corded systems in industrial metalworking. Feature innovation is expanding most quickly in wireless platforms with telemetry integration.
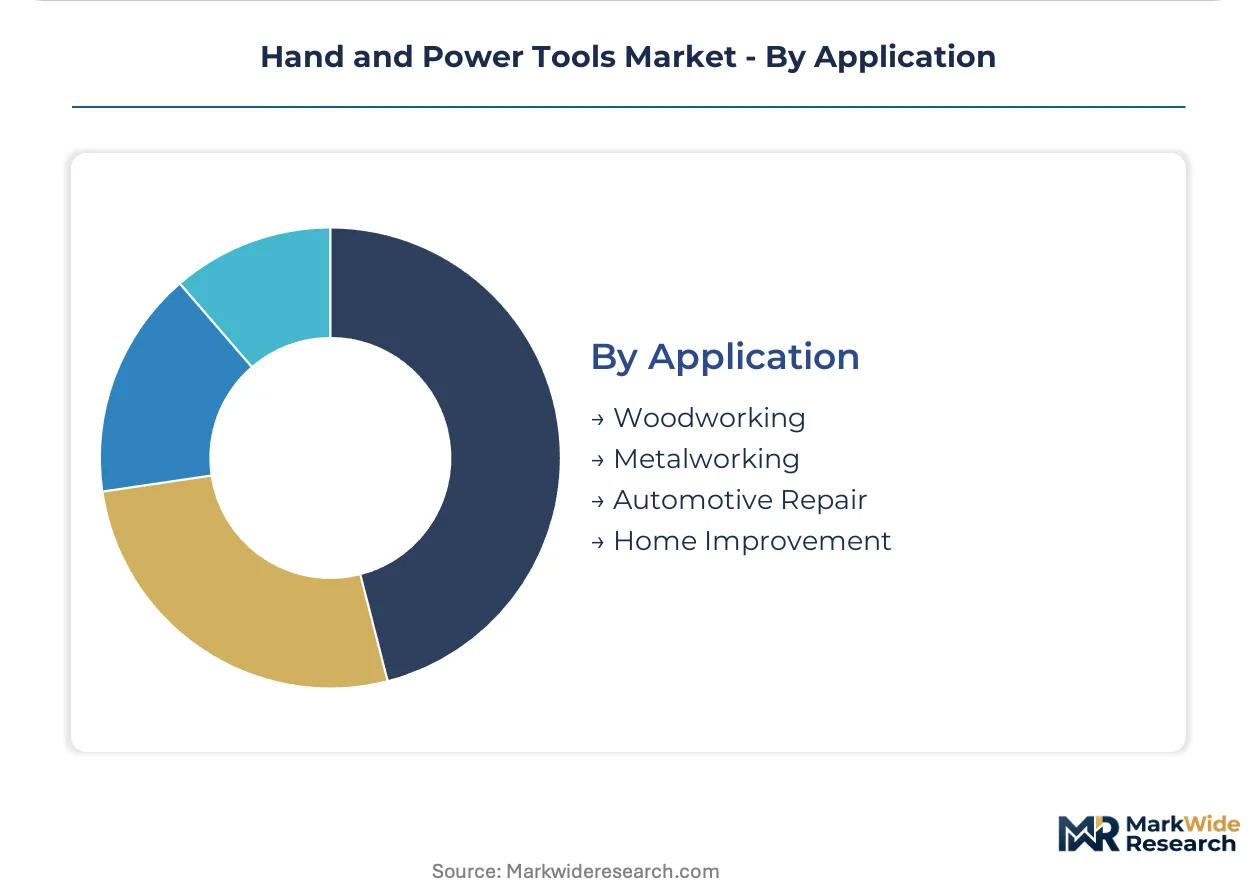
Application:
Material hardness and finish tolerance requirements dictate tool selection across trade specializations.
- Automotive Repair:Precision torque tools with calibration traceability command premium pricing. EV service networks in Germany and the United States require specialized equipment for high-voltage battery isolation procedures.
- Woodworking:Multi-functional features with dust extraction integration address hobbyist space constraints. The segment shows steepest expansion trajectory among DIY enthusiasts seeking compact workshop footprints.
- Metalworking:High-torque grinding and cutting tools with thermal overload protection serve fabrication shops.
- Home Improvement:General-purpose drill/drivers and fastening tools dominate consumer purchase frequency.
Application maturity centers on automotive repair with established certification requirements. Fastest adoption velocity appears in woodworking among residential hobbyists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of hand and power tools exported worldwide, while the United States and Germany absorb the highest-value consumption. This production-consumption divide shapes regional strategies across the industry.
United States
Residential construction contractors drive cordless power tool procurement, with OSHA silica dust rules mandating integrated vacuum extraction systems. The EPA's hazardous waste disposal regulations impose end-of-life obligations on manufacturers serving the market. Tool-as-a-service subscription models concentrate in Texas and Florida, where commercial facility management fleets convert capital expenditure to operational budgets.
Germany
EV assembly plants in Baden-Württemberg and Bavaria require precision torque tools with data-logging capabilities for battery pack installation. The EU's REACH chemicals framework restricts chromium VI in surface coatings, forcing reformulation of chrome-plated hand tools. Stuttgart's automotive supplier cluster sustains premium pricing for forged alloy products with calibration certification.
China
Manufacturing scale and export infrastructure give domestic producers cost advantages in both hand tools and power tool categories. The NMPA's equipment certification requirements and GB standards for electrical safety create compliance thresholds that filter smaller exporters. Lithium-ion battery production concentrates in the Yangtze River Delta, enabling platform standardization across cordless ecosystems.
India
The PLI scheme for capital goods assembly attracts toolmakers seeking tariff-advantaged export platforms to Southeast Asia and Africa. BIS certification mandates shape product design for domestic market access. Manufacturing investment clusters in Gujarat and Maharashtra, where production-linked incentives reduce effective tax rates for assembly operations.
Japan
Brushless DC motor control systems originate from precision engineering traditions serving commercial electricians and industrial maintenance. METI efficiency standards accelerate displacement of pneumatic alternatives in manufacturing. Nagoya's industrial machinery corridor supplies motor manufacturing equipment to regional tool producers.
Hand and Power Tools Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the hand and power tools market. The vendor base separates into integrated manufacturers with captive battery cell supply and brand licensors outsourcing production to contract assemblers. Three archetypes dominate: vertically integrated motor manufacturers, platform ecosystem orchestrators, and subscription-based fleet service operators. Capacity expansion in lithium-ion cell production and strategic partnerships for retail distribution represent the dominant competitive moves.
Within the integrated manufacturing tier, Makita exemplifies captive supply chain control through in-house motor production. Techtronic Industries occupies a position as a platform ecosystem orchestrator spanning multiple voltage systems. Stanley Black & Decker anchors the service-oriented archetype, converting hardware sales into recurring maintenance contracts.
| Leading Market Players |
|---|
| Makita |
| Koki Holdings |
| Stanley Black & Decker |
| Husqvarna Group |
| Festool |
| Techtronic Industries |
| Hilti |
| Ingersoll Rand |
| Bosch |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery platform standardization is compressing supplier margins while concentrating procurement power among ecosystem orchestrators who control voltage compatibility. Brushless motor manufacturing scale in China and Japan feeds cost-down pressure through the cordless tool segment, forcing hand tool specialists to differentiate through alloy certification and calibration services.
Pricing Analysis
Margin tightening in the cordless power tool tier reflects lithium-ion cell commoditization and cross-platform battery stickiness. Three-tier pricing structure across premium brushless platforms, standard brushed motor systems, and economy private-label alternatives dominates transactional procurement. Price differentiation rests on torque precision certification and after-sales service bundling. DIY enthusiasts exhibit highest price sensitivity, while EV assembly plants in Germany absorb premium positioning for data-logging torque compliance.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for finished tools. Manufacturing concentrates in China, Vietnam, and Mexico for final assembly, with brushless motors and battery cells drawing from Japan and South Korea. Neodymium magnet supply from China creates single-source vulnerability for brushless motor production. Distribution runs through vendor-managed inventory programs at national home improvement retailers with RFID-enabled loss prevention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand and power tools market sits in a cordless transition phase, with lithium-ion platforms displacing pneumatic infrastructure in commercial construction. This technology replacement cycle rewards ecosystem control and punishes component-level commoditization.
For Market Incumbents: Cement battery platform stickiness through voltage ecosystem expansion and bare-tool compatibility guarantees. Defend against Chinese cost competition by deepening captive motor manufacturing in Japan and securing UL certification priority for new battery platforms. Prioritize service network density in Texas and Florida where tool-as-a-service adoption concentrates. For New Entrants and Emerging Players: Launch via direct-to-prosumer digital channels targeting woodworking hobbyists seeking multi-functional space-efficient equipment. White-space opportunity sits in subscription-based maintenance services for facility management fleets in India under PLI-advantaged tariff structures. Bypass retail slotting fees through online torque tool calibration services for independent automotive repair shops. For Investors and Strategic Acquirers: Exit pathways concentrate in platform ecosystem acquisitions by industrial conglomerates seeking cordless technology access. Long-term viability favors vertically integrated motor manufacturers with Asian supply base control over brand licensors dependent on contract assembly. Watch for battery platform interoperability standards as inflection signal for ecosystem consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Expansion | Voltage ecosystem stickiness locks in aftermarket bare-tool demand across DIY and pro-sumer segments. |
| Backward Integration into Motors | In-house brushless DC production insulates against neodymium price volatility and China's export licensing regime. |
| Tool-as-a-Service Launch | Subscription provisioning with predictive maintenance converts capital expenditure to operational budgets for facility fleets. |
| Certification Priority Investment | UL and TÜV queue positioning accelerates product launch windows by six to nine months in cordless categories. |
| India PLI Manufacturing Footprint | Production-linked incentives in Gujarat and Maharashtra enable tariff-advantaged export platforms to Southeast Asia and Africa. |
Methodological Framework
Trade association filings, customs export records, and equipment certification databases formed the secondary backbone for supply-side calibration. Primary interviews with maintenance directors at commercial construction fleets, procurement leads at EV assembly plants, category buyers at national home improvement retailers, and aftermarket service heads at industrial distributors provided demand-side validation. Bottom-up channel checks and top-down production capacity assessments were triangulated against lithium-ion battery platform shipment data.
Historical trendline analysis of cordless power tool adoption rates, hand tool premium pricing persistence, and pneumatic installed base erosion informed the projection framework. Segmentation modeling spanned product type, end-user procurement authority, tool feature specification, and application material requirements across the analysis window. CAGRs were derived from battery chemistry improvement curves and construction employment forecasts, with OSHA regulatory compliance timelines and EU REACH substance restriction phase-ins as industry-specific adjustment inputs.
Rare earth export licensing disruptions, REACH reformulation delays, and construction employment cyclicality are the dominant revision risks for forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Indexable Inserts Market
Tools
Ripper Market
Tools
Global Cordless Power Tools Market
Tools
2D Laser Cutting Machine Market
Tools
Tool Setting Gauges Market
Tools
Metal Forming Tools Market
Tools
Yard Scraper Market
Tools
Global Standard Parts for Tool Making Market
Tools
Chainsaw Market
Tools
Cordless Planer Market
Tools
Cordless Power Drill Market
Tools
Cutting Tools Market
Tools
Concrete Saw Market
Tools
Lathe Machines Market
Tools
Industrial Cleaning Equipment Market
Tools
Global Table Saws Market