
 Cutting Tool Inserts Market | 2026-2036
Cutting Tool Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Tool Inserts Market Analysis
Ceramic matrix composites and silicon nitride substrates are shifting cost-performance tradeoffs in high-speed machining. Sandvik AB leverages captive powder metallurgy capabilities to control substrate quality from mine to finished insert. Kennametal Inc. anchors North American aerospace supply chains through long-term direct contracts with tier-one engine manufacturers. Tungaloy Corp. competes on cermet formulations optimized for lean-burn engine component finishing.
Cutting tool inserts are indexable, geometrically defined cutting elements manufactured from cemented carbide, ceramic, cubic boron nitride, or polycrystalline diamond, typically featuring precision-ground edges and chipbreaker geometries for controlled material removal in turning, milling, and drilling operations. Carbide inserts dominate volume shipments due to cobalt-binder formulations balancing toughness and hot hardness across steel and cast iron applications. Premium-grade carbide segments capture disproportionate margin pools in aerospace superalloy machining, while ceramics and CBN inserts represent the fastest-growing product categories as manufacturers push cutting speeds beyond thermal limits of conventional grades.
ISO 13399 standardization governs insert geometry interchangeability across multinational supply chains, while REACH restrictions on cobalt compounds and hexavalent chromium coatings constrain formulation flexibility for European manufacturers. The U.S. Department of Commerce export controls on advanced ceramics and China MIIT domestic substitution mandates for high-performance cutting materials are fragmenting procurement strategies. Stakeholders must monitor divergence between Western sustainability mandates and Asian industrial policy to align capacity investments with regulatory access requirements.
Market Dynamics
EU Ecodesign for Sustainable Products Regulation is forcing cobalt reduction in carbide formulations while aerospace demand for titanium-capable inserts concentrates procurement around German precision engineering clusters.
Growth Catalysts
- Aerospace Superalloy Machining:Engine manufacturers index procurement toward inserts rated for titanium and Inconel finishing, with Stuttgart and Aachen tooling clusters capturing contract volumes from co-located OEMs.
- REACH Cobalt Restrictions:European manufacturers accelerate nickel-binder and cermet formulations to maintain market access, creating formulation innovation pressure that diffuses to Asian suppliers.
- Silicon Nitride Substrates:Ceramic matrix composites enable cutting speeds beyond thermal limits of conventional carbide, with automotive powertrain manufacturers adopting for high-volume cast iron machining.
Market Restraints
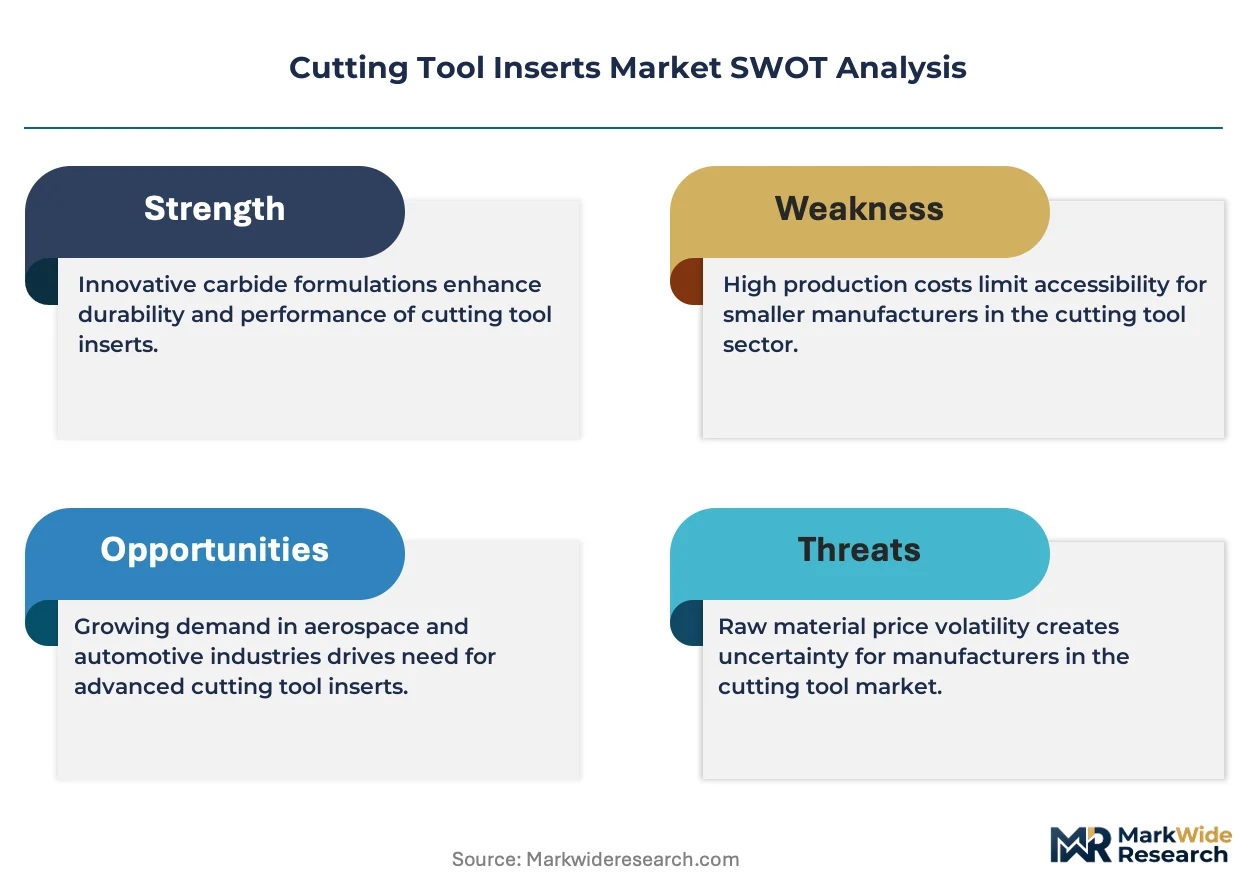
- Tungsten Supply Concentration:China controls approximately 80% of global tungsten concentrate output, creating input cost volatility for cemented carbide producers outside the country.
- Technical Limitation in Interrupted Cuts:Ceramic and CBN inserts fracture under shock loading in roughing operations, constraining their displacement of cobalt-binder carbide in heavy stock removal.
- Substitution Threat from Additive Manufacturing:Powder bed fusion reduces machining requirements for complex aerospace components, compressing insert consumption per finished part in certain engine programs.
Strategic Opportunities
- India Machine Tool Consumption:The country's PLI scheme for capital goods and automotive component export growth creates underpenetrated demand for coated carbide grades in crankshaft and transmission machining.
- Tool-as-a-Service Models:Cutting tool management contracts bundle insert supply with wear monitoring and reconditioning, capturing lifecycle value from automotive tier-one suppliers seeking to outsource tooling expertise.
- ISO 13399 Digital Twin Integration:Standardized insert geometry data enables predictive tool life algorithms in machine control systems, opening software-adjacent revenue streams for substrate suppliers.
Industry Challenges
- Grinding Specialist Scarcity:Precision edge preparation and chipbreaker geometry finishing require skilled operators that German and Japanese tooling clusters struggle to replace from retiring workforces.
- Dual Certification Burden:Suppliers must simultaneously qualify for AS9100 aerospace standards and IATF 16949 automotive requirements to serve converging OEM supply chains, extending validation timelines.
- Legacy ERP Integration:Tool management systems from incumbent vendors resist API connectivity with modern MES platforms, complicating data-driven procurement implementations at mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Tool Inserts Market |
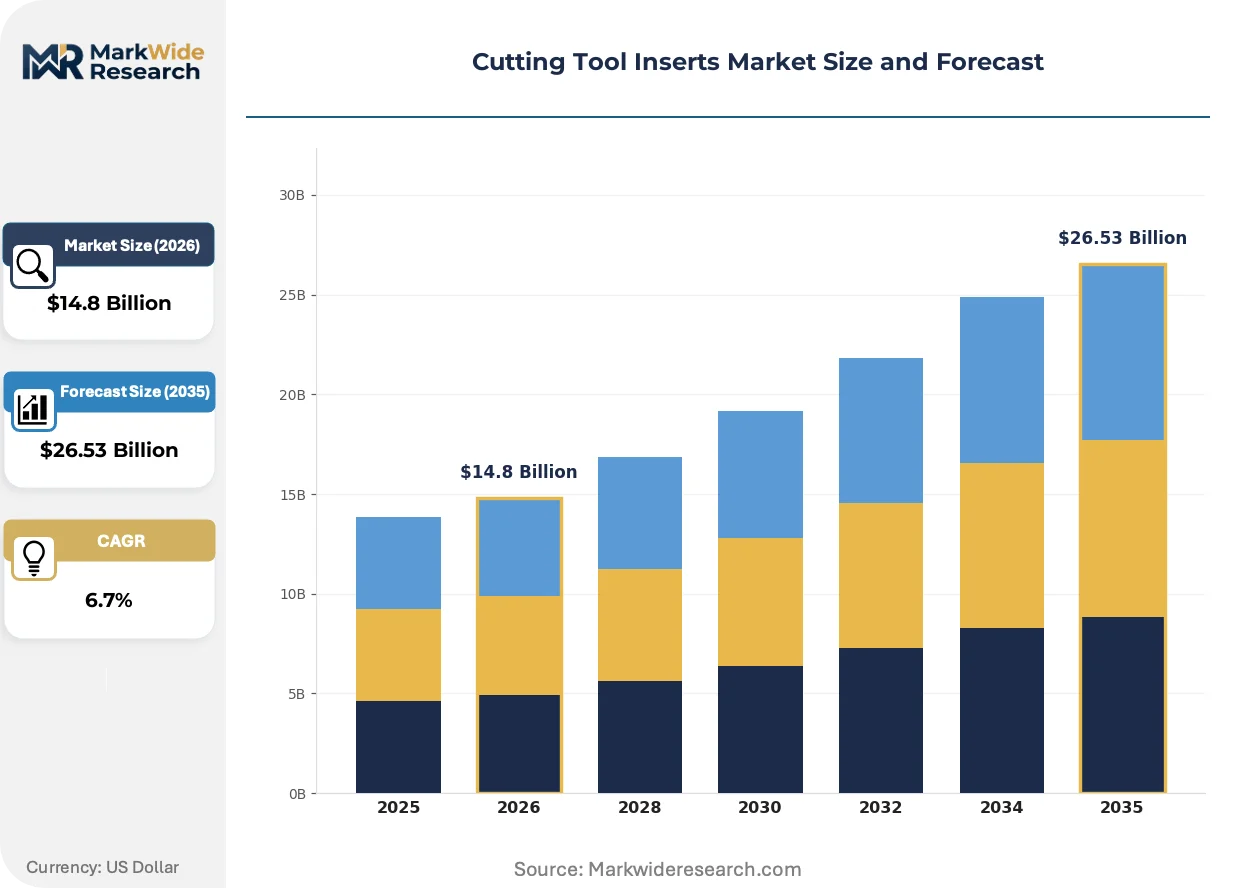
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbide Inserts, Ceramics, CBN Inserts, PCD Inserts Application: Metal Cutting, Woodworking, Machining, Plastic Processing End User: Aerospace, Automotive, Electronics, Construction Grade: Standard Grade, Premium Grade, High Performance, Economy Grade |
| Companies Covered | Kyocera Corp., Sumitomo Corp., Sandvik AB, Seco Tools AB, Ceratizit SA, Kennametal Inc., ISCAR Ltd., Tungaloy Corp., Mitsubishi Materials Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Tool Inserts Market Emerging Trajectories
Material science advances and digital thread integration are compressing the traditional boundaries between substrate engineering, geometry optimization, and consumables lifecycle management.
Polycrystalline diamond inserts with optimized cobalt-sintered substrates are rewriting performance benchmarks in aluminum aerospace structural machining. Tier-one airframe manufacturers specify these grades for wing rib and bulkhead finishing where surface integrity requirements exceed carbide capabilities. The technology is compressing cycle times in high-volume aluminum component programs while displacing brazed tools in legacy equipment.
China MIIT domestic substitution mandates for high-performance cutting materials are fragmenting procurement strategies for multinational manufacturers. Western suppliers face technology transfer requirements to maintain access to state-sponsored machine tool procurement programs. Domestic Chinese carbide producers capture share in standard grades while foreign specialists retreat to premium aerospace and medical segments.
Direct contracting between insert manufacturers and large automotive powertrain producers is disintermediating traditional distribution channels. Long-term agreements specify volume commitments, technical support integration, and joint R&D on application-specific geometries. This pattern concentrates most visibly in Germany where OEMs co-locate engineering teams with tooling specialists for synchronous development of next-generation engine block machining processes.
Cutting Tool Inserts Market Segmentation
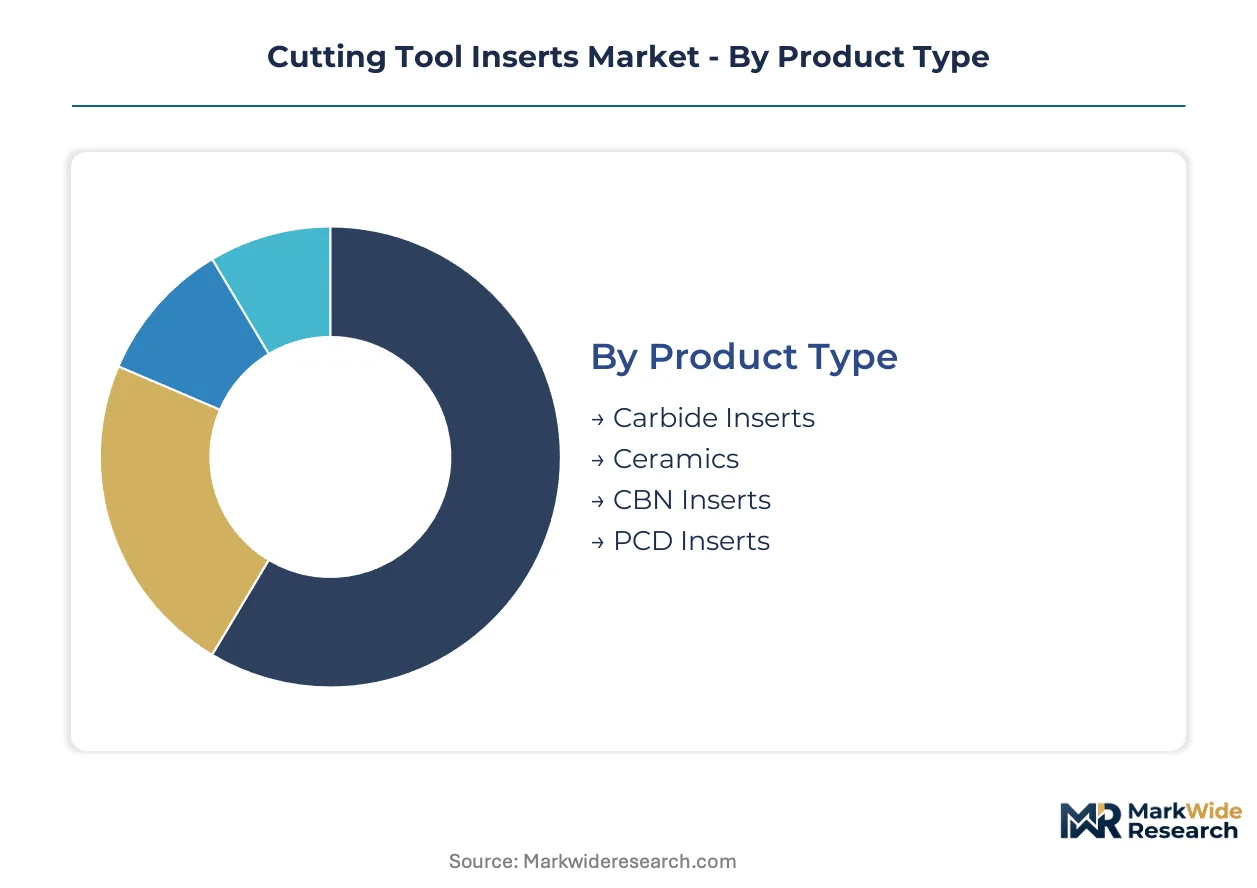
Cutting tool inserts segment across multiple dimensions that determine pricing power, technical qualification requirements, and procurement channel strategy. Product material and grade specifications govern performance ceilings in specific machining operations, while end-user industry concentration shapes contract structures and inventory holding patterns.
Product Type:
Customization intensity spans from commodity carbide geometries to application-engineered superhard materials, with standardization decreasing as substrate sophistication increases.
- Carbide Inserts:Cemented tungsten carbide with cobalt binders dominates volume shipments across steel and cast iron applications. Automotive powertrain manufacturers in Germany's Stuttgart cluster index procurement toward coated carbide grades for crankshaft and transmission component machining, with REACH cobalt restrictions forcing nickel-binder formulation shifts.
- Ceramics:Silicon nitride and alumina-toughened zirconia substrates enable cutting speeds beyond thermal limits of conventional carbide. Aerospace engine manufacturers specify ceramic matrix composites for Inconel turbine blade finishing where hot hardness requirements exclude metallic binders entirely.
- CBN Inserts:Polycrystalline cubic boron nitride grades target hardened steel machining above HRC 45.
- PCD Inserts:Synthetic diamond sintered onto carbide substrates addresses aluminum aerospace structural programs.
Leading the category by volume: Carbide Inserts. Expanding most quickly: Ceramics.
Application:
Process-specific chip formation mechanics and surface integrity requirements fragment demand across machining disciplines with distinct tooling economics.
- Metal Cutting:Turning, milling, and drilling operations consume the majority of insert volume across subtractive manufacturing. German precision engineering clusters around Stuttgart and Aachen concentrate demand for titanium-capable geometries serving co-located aerospace OEMs.
- Machining:General-purpose material removal spans prototype through production volumes with grade-flexible procurement.
- Woodworking:Carbide-tipped inserts for solid wood and panel processing emphasize wear resistance over thermal stability.
- Plastic Processing:Glass-filled polymer machining requires polished rake faces to prevent material buildup.
Metal Cutting commands the largest volume share. Machining shows the steepest expansion trajectory as reshoring programs rebuild Western production capacity.
End User:
Industry-specific certification requirements and co-location patterns with tooling specialists create distinct procurement ecosystems with varying contract sophistication.
- Aerospace:AS9100-qualified inserts for titanium, Inconel, and composite machining command premium positioning through direct OEM contracts. Tier-one engine manufacturers specify substrate grades through long-term agreements with technical support integration.
- Automotive:IATF 16949 requirements and high-volume cast iron machining dominate consumption patterns. Powertrain producers adopt tool-as-a-service models bundling insert supply with wear monitoring.
- Electronics:Miniaturized component machining drives demand for precision-ground micro-inserts.
- Construction:Heavy equipment component roughing prioritizes toughness over finishing precision.
Aerospace leads by margin contribution. Automotive dominates absolute volume. Electronics climbs fastest as semiconductor capital equipment manufacturing expands.
Grade:
Performance tiering aligns with end-user qualification burdens and application criticality, with certification overhead concentrating in upper tiers.
- Premium Grade:Application-specific coatings, edge preparations, and substrate formulations qualified for aerospace superalloy and medical implant machining. Dual AS9100 and IATF 16949 certification requirements extend validation timelines.
- High Performance:Advanced PVD/CVD coatings for demanding but non-critical applications in automotive and general engineering.
- Standard Grade:General-purpose coated and uncoated carbide for routine steel and cast iron operations.
- Economy Grade:Uncoated or basic-coated inserts for short-run job shops and maintenance operations.
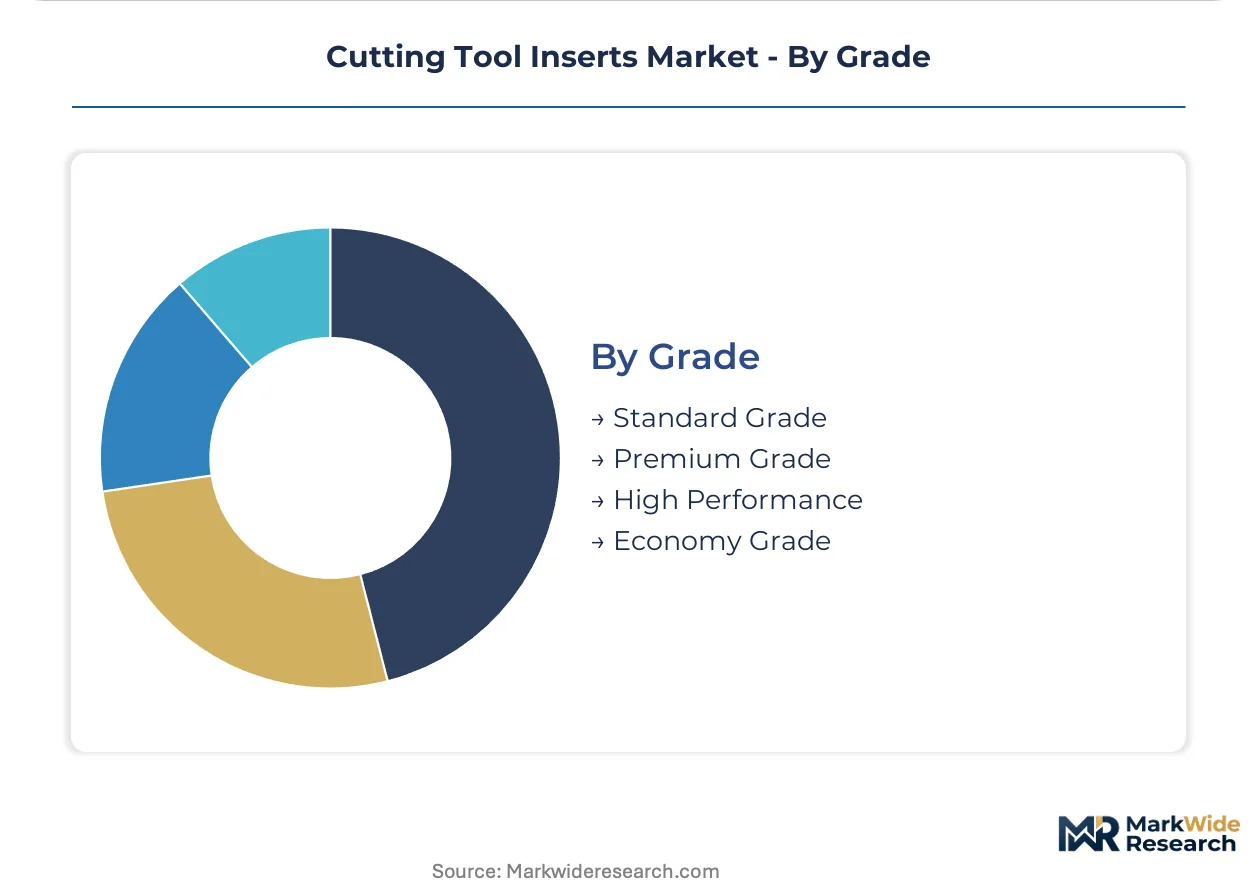
Standard Grade leads by unit volume. Premium Grade captures disproportionate margin pools. High Performance gains share fastest as manufacturers push speed-feed parameters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters around Stuttgart and Aachen operate as de facto special economic zones for cutting tool procurement, concentrating aerospace and automotive OEM demand alongside advanced tooling specialists.
Germany
Automotive powertrain manufacturers and aerospace engine producers index procurement toward titanium-capable inserts. ECHA REACH restrictions on cobalt compounds force nickel-binder formulation shifts among local carbide producers. The Stuttgart-Aachen corridor concentrates co-located engineering teams developing synchronous machining processes for next-generation engine blocks.
United States
Tier-one aerospace engine manufacturers specify substrate grades through long-term direct contracts with technical support integration. FAA certification requirements for AS9100-qualified inserts extend validation timelines for European suppliers seeking market access. Midwest manufacturing belts around Detroit and Cincinnati maintain dense networks of automotive tier-one suppliers adopting tool-as-a-service models.
China
MIIT domestic substitution mandates for high-performance cutting materials fragment procurement strategies for multinational manufacturers. State-sponsored machine tool procurement programs impose technology transfer requirements on Western suppliers. Yangtze River Delta industrial zones host expanding domestic carbide producers capturing share in standard grades while foreign specialists retreat to premium aerospace segments.
Japan
Precision component manufacturers drive demand for ceramic matrix composites and silicon nitride substrates in high-speed machining applications. METI industrial policy supports advanced materials R&D through collaborative research consortia. Nagoya-based automotive suppliers and Tokyo-area precision engineering clusters maintain captive relationships with domestic insert specialists.
India
The PLI scheme for capital goods and automotive component export growth creates underpenetrated demand for coated carbide grades. BIS quality certification requirements for cutting tools complicate market entry for unqualified foreign suppliers. Maharashtra and Gujarat industrial corridors concentrate new machine tool installations serving reshoring-linked component manufacturing.
Cutting Tool Inserts Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium aerospace and medical applications concentrating around qualified specialists while standard grades fragment across regional producers. The vendor base organizes into three strategic archetypes: captive powder metallurgy operators controlling substrate quality from raw material through finished insert; application-engineered specialists qualifying for direct OEM contracts; and scale-driven commodity producers competing on volume and distribution reach. Dominant competitive moves include backward integration into tungsten powder production and geographic expansion through technology licensing arrangements with local partners.
Among Japanese precision materials specialists, Kyocera Corp., Sumitomo Corp., and Mitsubishi Materials Corp. occupy positions anchored in ceramic and carbide substrate expertise developed through decades of captive research. These companies exemplify the application-engineered archetype, with their geographic naming and corporate structures reflecting integrated materials-to-components business models. Their presence in the market represents the competitive importance of controlling substrate formulation and edge preparation capabilities for qualified supply to aerospace and automotive OEMs.
| Leading Market Players |
|---|
| Kyocera Corp. |
| Sumitomo Corp. |
| Sandvik AB |
| Seco Tools AB |
| Ceratizit SA |
| Kennametal Inc. |
| ISCAR Ltd. |
| Tungaloy Corp. |
| Mitsubishi Materials Corp. |
| Others |
Supply Flow & Price Mechanics
Captive powder metallurgy capabilities at Sandvik AB and Kyocera Corp. anchor both supply security and pricing power across premium carbide grades, with in-house tungsten processing insulating these operators from raw material volatility that erodes margins at third-party-dependent competitors. This backward integration pattern concentrates margin capture among substrate-to-insert specialists while forcing price competition in standard grades.
Pricing Analysis
Volume-margin splits sharply across grade tiers, with standard carbide inserts transacting on commodity spot dynamics and premium aerospace grades commanding contract-based long-term offtake structures. Price differentiation rests on dual AS9100-IATF 16949 certification overhead and cobalt-binder versus nickel-binder formulation costs. Cost compression in standard grades intensifies as Chinese domestic producers expand capacity, while automotive powertrain buyers prove most price-sensitive and aerospace engine OEMs least sensitive due to qualification lock-in effects.
Supply Chain Analysis
Single-source vulnerability sits with China's dominance in tungsten concentrate extraction, which feeds cemented carbide production in Germany, Japan, and the United States. Raw material dependencies encompass cobalt compounds, silicon nitride powders, and polycrystalline diamond substrates. REACH restrictions on cobalt and hexavalent chromium coatings in Europe create regulatory fragmentation that complicates cross-border inventory positioning. Distribution runs through direct OEM contracting for premium grades and industrial distributors for standard volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around qualified substrate specialists as REACH cobalt restrictions and dual certification burdens force smaller formulators into acquisition or exit.
For Market Incumbents: Deepen captive tungsten powder capabilities to offset China's supply concentration risk, while accelerating nickel-binder and cermet R&D to defend aerospace contract positions against emerging ceramic matrix composite substitutes. Prioritize synchronous engineering partnerships with Stuttgart-Aachen automotive clusters to embed tool-as-a-service offerings before distribution channels fully disintermediate. For New Entrants and Emerging Players: Silicon nitride substrate innovation offers a technology-first wedge into high-speed cast iron machining for automotive powertrain applications, where incumbent ceramic specialists underpenetrate. Target India's PLI-subsidized machine tool installations through BIS-qualified coated carbide grades, leveraging local reconditioning partnerships to bypass established distribution networks. For Investors and Strategic Acquirers: Exit pathways concentrate in application-engineered specialists with captive powder metallurgy and existing dual certification, as these assets command scarcity premiums in aerospace-medical convergence plays. Monitor MIIT domestic substitution enforcement intensity as the inflection signal for Western premium-grade retreat versus technology-transfer compliance decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Powder | Captive raw material control insulates margin structures from China's concentrate volatility. |
| Dual Certification Investment | AS9100-IATF 16949 qualification opens synchronous development contracts with German OEM clusters. |
| Cermet Formulation Expansion | REACH-compliant nickel-binder grades defend European market access against regulatory exclusion. |
| Tool-as-a-Service Launch | Bundled insert supply with wear monitoring captures lifecycle value from automotive tier-one suppliers. |
| India Market Entry Partnership | PLI-linked machine tool demand in Maharashtra-Gujarat corridors offers underpenetrated coated carbide volume. |
Methodological Framework
Independent corroboration across primary interviews with carbide plant managers, aerospace procurement leads at tier-one engine manufacturers, automotive powertrain tooling engineers, and industrial distribution channel heads underwrites the qualitative findings. Secondary validation draws from ECHA REACH regulatory filings, China MIIT domestic substitution mandates, SEC 10-K disclosures from listed substrate specialists, and ISO 13399 standardization documentation. Bottom-up insert volume modeling triangulates against top-down machine tool consumption data across the analysis window.
Comparable-period anchoring to historical carbide consumption patterns, ceramic adoption curves, and superalloy machining intensity metrics structures the projection horizon. Segmentation dimensions span substrate material class, end-user industry certification tier, grade performance level, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating silicon nitride thermal performance gains and additive manufacturing substitution effects in aerospace component programs.
Several conditions sit outside the modeled scope, including unannounced export control expansions on advanced ceramics, abrupt cobalt supply disruptions from geopolitical events, and step-change breakthroughs in binderless carbide formulations. Forecasts reflect documented assumptions about REACH enforcement continuity and MIIT technology transfer requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Blowing Torch Market
Tools
Cordless Bandsaw Sander Market
Tools
Entrenching Tool Market
Tools
Gear Hobbing Cutter Market
Tools
Chainsaw Market
Tools
Ratchet Wringer Market
Tools
Automated Plasma Beveller Market
Tools
Assembly Fastening Tool Market
Tools
Tile Saw Market
Tools
Air Hammer Market
Tools
2D Laser Cutting Machine Market
Tools
Log Splitters Market
Tools
Drill Set Market
Tools
Welding Products Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Allen Key Market