
 Clamps Market | 2026-2036
Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
Clamps Market Outlook
REACH is hardening the cost-of-entry calculus for clamp manufacturers serving European automotive and industrial channels. Oetiker Group leverages its Swiss metallurgy heritage to sustain premium positioning in stainless steel hose clamps for powertrain applications. Destaco anchors its competitive stance through specialized workholding and fastening solutions that dominate automated assembly lines across North American manufacturing.
Clamps are mechanical fastening devices engineered to apply compressive force around cylindrical objects—pipes, hoses, or cables—typically manufactured from stamped metal bands, injection-molded polymers, or cast aluminum with specified clamping force ratings measured in newtons per square millimeter. Their primary industrial purpose spans fluid system integrity, structural alignment, and vibration dampening across capital-intensive sectors. Hose clamps lead product type demand due to pervasive automotive cooling and turbocharger applications, while stainless steel commands the material hierarchy on corrosion resistance premiums in marine and chemical processing environments. Plastic and nylon segments are gaining traction in electrical and lightweight automotive routing where galvanic isolation and mass reduction override metallic durability requirements.
FDA, EPA, and OSHA frameworks govern clamp deployment in food processing equipment, emission control systems, and industrial safety guard installations across the United States, with compliance audits intensifying for suppliers serving regulated end markets. The EU Green Deal and CE marking directives are embedding circular economy criteria into fastener procurement specifications, reshaping supplier qualification protocols for construction and automotive channels. Stakeholders must monitor evolving alloy composition standards and regional carbon border adjustment mechanisms to preempt sourcing disruptions and qualification gaps.
Market Dynamics
EV thermal management architectures are forcing clamp suppliers to engineer lighter, corrosion-resistant fastening solutions that withstand glycol-based coolant chemistries and rapid thermal cycling across extended vehicle lifespans.
Growth Catalysts
- EV Thermal System Proliferation:Battery electric vehicles require redundant cooling loops for power electronics, driving specification upgrades in stainless steel hose clamps rated for higher pressure tolerances.
- REACH Material Traceability Mandates:ECHA enforcement of Substance of Very High Concern declarations is filtering non-compliant fastener suppliers from European automotive qualification lists.
- Marine Chemical Processing Corrosion Standards:Duplex and super-duplex stainless steel grades are displacing standard 300-series alloys in offshore platform and desalination plant specifications.
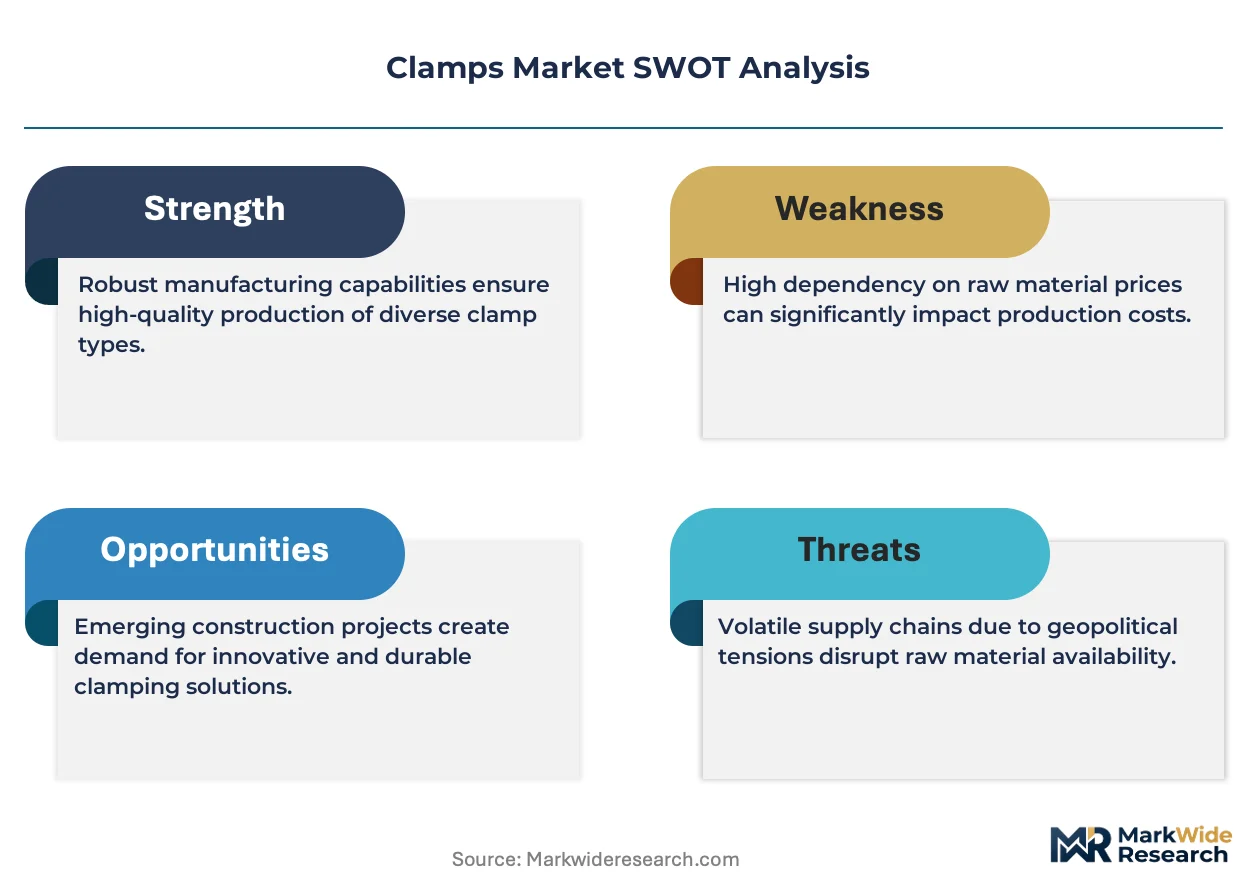
Market Restraints
- Nickel Price Volatility:Stainless steel feedstock costs swing with LME nickel contract fluctuations, compressing margin buffers for commodity-grade clamp fabricators.
- German Automotive Tier Concentration:Three dominant OEM procurement consortia control specification-setting for European hose clamp standards, limiting new entrant access.
- Polymer Substitution in Low-Load Applications:Glass-filled nylon 66 clamps are capturing wire routing and non-pressurized fluid lines where metallic durability exceeds functional requirements.
Strategic Opportunities
- India Industrial Infrastructure Buildout:PLI scheme incentives for capital goods manufacturing are opening specification windows for corrosion-resistant fastening in chemical process plants.
- Hydrogen Distribution Network Deployment:High-pressure hydrogen fueling infrastructure requires specialized 700-bar rated clamps with metallic sealing surfaces that polymer alternatives cannot replicate.
- Additive Manufacturing Convergence with Topology Optimization:Laser powder bed fusion enables lattice-structured clamp bands that reduce mass while maintaining clamping force ratings for aerospace ducting applications.
Industry Challenges
- Metallurgical Talent Scarcity:Stainless steel alloy specification expertise is concentrating among retiring German and Swiss engineering cohorts, constraining new product development velocity.
- Multi-Certification Timeline Compression:Simultaneous TÜV, UL, and marine classification society approvals extend qualification cycles for universal product platforms.
- Legacy Inventory System Integration:Real-time clamp torque monitoring sensors require retrofit compatibility with decades-old hydraulic assembly equipment in North American heavy manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clamps Market |
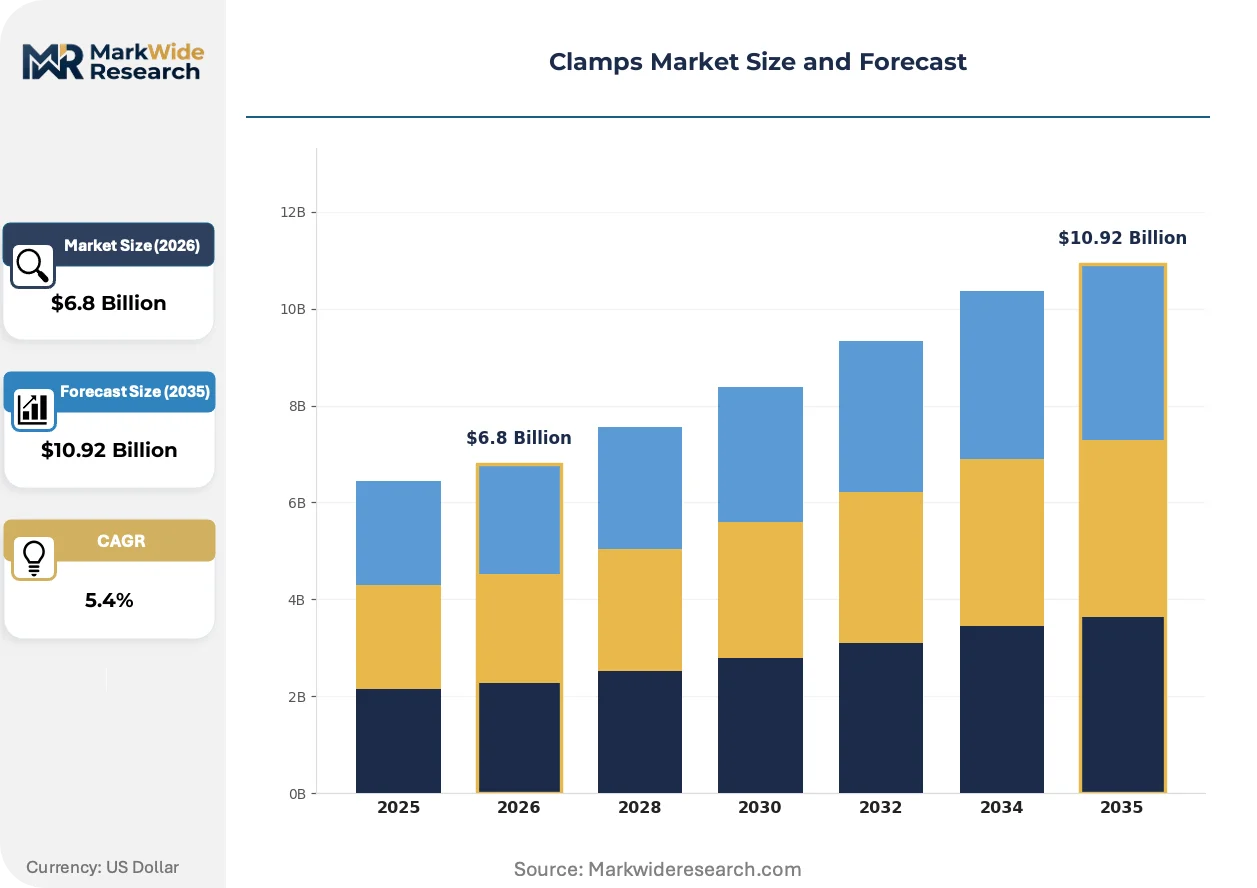
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipe Clamps, Hose Clamps, Spring Clamps, C-Clamps Material: Stainless Steel, Plastic, Aluminum, Nylon Application: Construction, Automotive, Electrical, Plumbing End User: Manufacturers, Contractors, DIY Enthusiasts, Maintenance Providers |
| Companies Covered | Oetiker Group, Destaco, Parker Hannifin, BorgWarner Inc., Carr Lane Manufacturing Co., Gates Corporation, Norma Group, Schaeffler AG, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clamps Market Strategic Shifts
Clamp engineering is bifurcating between premium corrosion-resistant metallurgy for harsh-environment capital equipment and mass-optimized polymer formulations for electrified vehicle architectures. This divergence is compressing mid-tier commodity positioning.
Continuous band worm-drive clamps with integrated torque-limiting mechanisms are consolidating specification authority in automotive OEM thermal systems. Tier 1 suppliers are mandating these designs to eliminate over-torque failures during high-volume assembly. The technology is consolidating aftermarket demand into original equipment configurations, reducing private-label interchangeability.
EU F-Gas Regulation phase-down schedules are accelerating demand for hermetically sealed clamped connections in commercial refrigeration and heat pump systems. Manufacturers must now certify leak-tight performance across temperature extremes from minus 40 to plus 150 degrees Celsius. German and Italian HVAC OEMs are driving specification harmonization through Eurovent certification protocols.
Fleet operators and industrial maintenance departments are compressing supplier rosters to single-source framework agreements with integrated inventory management. Distributor intermediaries are losing specification influence as direct OEM-to-fleet digital procurement platforms capture high-volume aftermarket demand. This concentration is most visible in North American Class 8 trucking and European chemical processing maintenance channels.
Clamps Market Segmentation
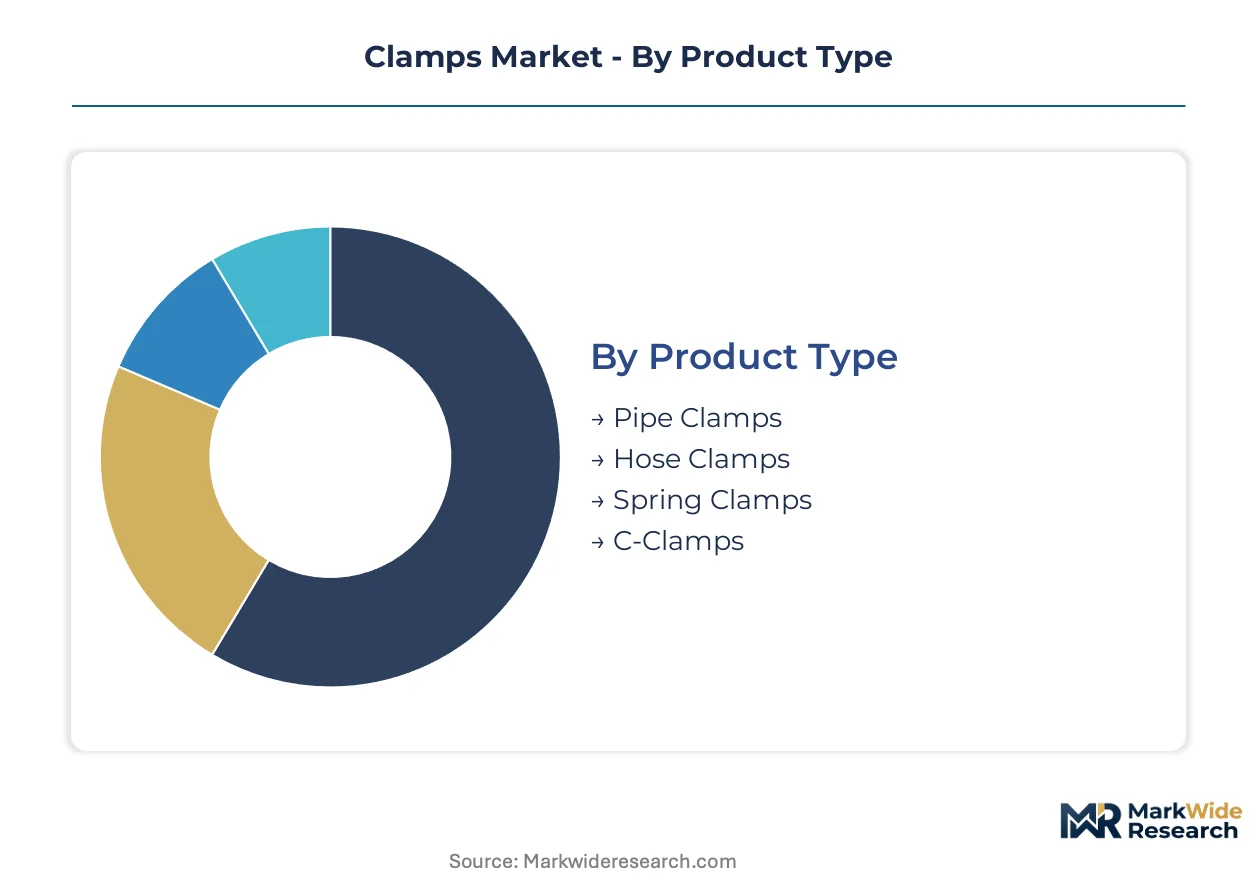
Clamps serve both standalone installation and embedded system integration, with specification requirements diverging sharply between field-service replacement and OEM-designed subassemblies. Understanding where each segment sits on this integration spectrum reveals margin architecture and procurement power dynamics.
Product Type:
Standalone fastening dominates construction and maintenance channels, while embedded hose and spring clamps integrate into pre-assembled thermal and fluid modules.
- Hose Clamps:Worm-drive and constant-tension bands secure pressurized coolant, fuel, and pneumatic lines across vehicle powertrains and industrial fluid systems. Automotive OEM thermal management specifications in Germany and Japan are driving demand for torque-limiting designs that eliminate assembly-line over-tightening failures.
- Pipe Clamps:Rigid saddle and U-bolt configurations anchor structural piping in commercial construction and process infrastructure. North American commercial building codes and MEP contractor procurement standards sustain volume concentration in copper and steel plumbing risers.
- Spring Clamps:Self-tensioning wire and silicone hose fasteners deploy in high-vibration engine compartments and HVAC ducting where thermal cycling demands continuous radial pressure.
- C-Clamps:Adjustable forged-steel frames provide temporary workholding and fabrication fixturing in metalworking shops and construction sites.
Hose clamps lead volumes today; spring clamps are gaining share fastest in electrified vehicle thermal architectures.
Material:
Cost tier stratification separates corrosion-resistant metallurgy for capital-intensive infrastructure from mass-optimized polymers in consumer-accessible channels.
- Stainless Steel:Austenitic and duplex grades deliver chloride resistance for marine, chemical processing, and underhood automotive exposure. REACH Substance of Very High Concern traceability mandates in the European Union are elevating specification authority for mills with certified alloy documentation.
- Plastic:Glass-reinforced polypropylene and PBT compounds serve electrical routing and non-pressurized fluid retention where galvanic isolation matters. Injection molding scale economies in Chinese and Mexican contract manufacturers compress pricing for consumer-grade hardware.
- Aluminum:Extruded and cast lightweight bands address aerospace ducting and weight-sensitive automotive assemblies where magnetic neutrality and thermal conductivity add value.
- Nylon:Glass-filled PA66 formulations capture wire harness management and low-load retention in appliance and consumer electronics manufacturing.
Stainless steel dominates value capture; plastic compounds are climbing the fastest as EV manufacturers prioritize mass reduction.
Application:
Volume concentration varies by customer procurement maturity, with automotive and electrical channels consolidating supplier rosters while construction remains fragmented.
- Automotive:OEM thermal system, powertrain, and fuel line specifications demand ISO-certified production with PPAP documentation and zero-defect protocols. Battery electric vehicle cooling loop redundancy is expanding specification windows for high-pressure-rated hose clamps.
- Construction:Commercial MEP and structural steel contractors source through distributor networks with project-based pricing and limited brand loyalty. German and US building code harmonization around seismic bracing is elevating engineered clamp requirements.
- Electrical:Cable management and grounding applications prioritize UL-listed nylon and steel configurations with documented torque performance across temperature ranges.
- Plumbing:Residential and commercial potable water systems specify lead-free brass and stainless steel to comply with NSF/ANSI 61 and equivalent national health standards.
Automotive leads volume concentration; electrical applications are expanding most quickly with datacenter and renewable energy infrastructure buildout.
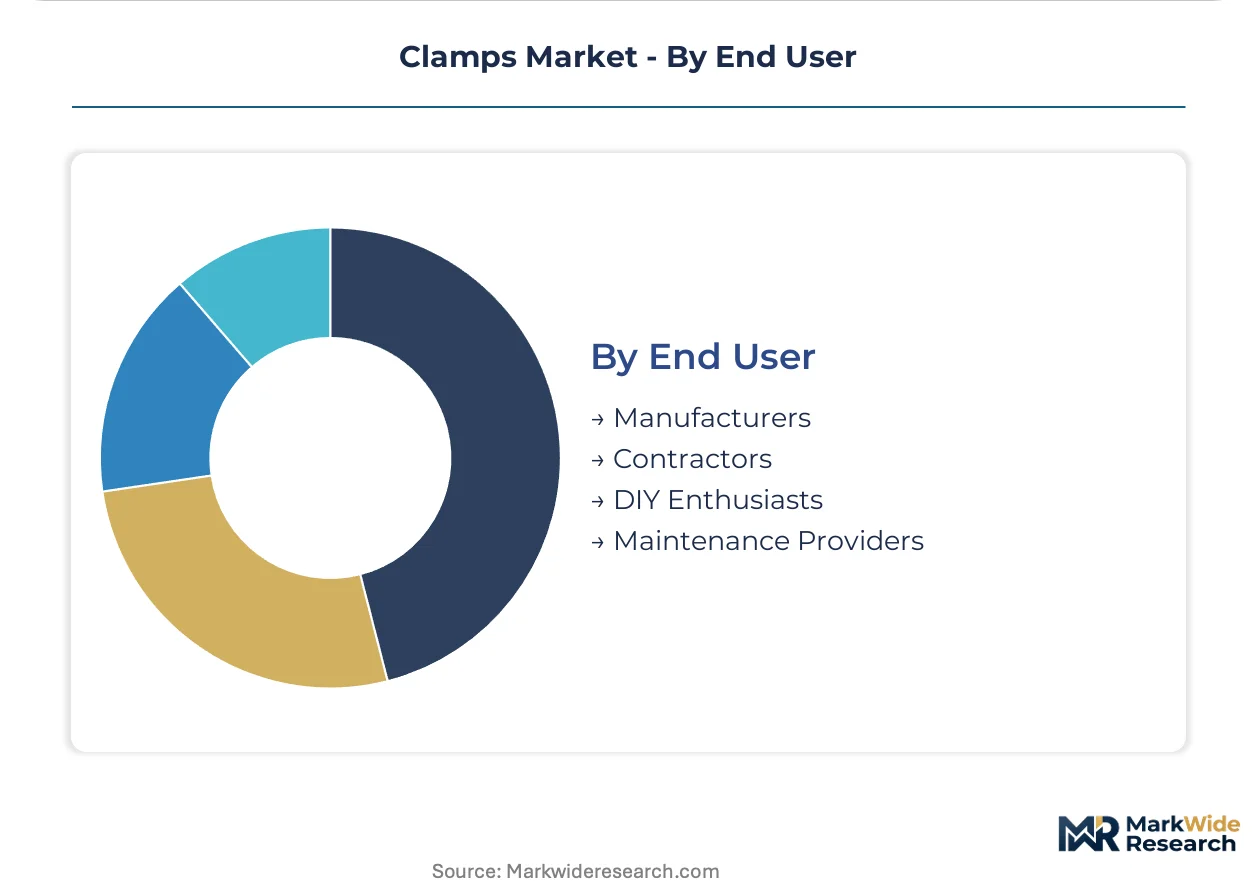
End User:
Customer type determines specification authority, with manufacturers holding design control while contractors and maintenance providers execute replacement demand.
- Manufacturers:OEM and tier supplier engineering teams specify clamp performance, material certification, and assembly torque for integration into finished products. Direct procurement relationships and long-term framework agreements lock out distributor intermediaries in high-volume automotive and appliance channels.
- Maintenance Providers:Industrial facilities and fleet operators manage preventive replacement programs with inventory systems tracking mean-time-between-failure data. North American Class 8 trucking and European chemical processing operations are consolidating to single-source agreements with vendor-managed inventory.
- Contractors:Construction and installation trades purchase through wholesale distributors with price-driven selection and limited technical specification involvement.
- DIY Enthusiasts:Consumer retail channels move commodity-grade hose and C-clamps through home improvement stores with private-label and national brand shelf competition.
Manufacturers command specification authority today; maintenance providers are gaining procurement sophistication fastest with predictive analytics integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metallurgical engineering cohorts and Swiss precision manufacturing talent anchor European specification authority for corrosion-resistant fastening systems. Japanese automotive supplier networks and South Korean EV battery manufacturing clusters drive Asian demand concentration. North American heavy manufacturing maintenance operations sustain aftermarket volume through consolidated procurement platforms.
Germany
Automotive OEM thermal system procurement and tier supplier engineering concentration dominate specification-setting for European hose clamp standards. REACH Substance of Very High Concern declarations enforced by ECHA filter non-compliant fastener suppliers from qualification lists. Stuttgart and Munich engineering clusters house precision clamp fabrication operations serving powertrain and battery electric vehicle cooling architectures.
United States
Class 8 trucking fleet operators and industrial maintenance departments compress supplier rosters to single-source framework agreements with integrated inventory management. OSHA compliance audits intensify for clamp deployment in industrial safety guard installations across heavy manufacturing facilities. Detroit automotive supplier corridors and Gulf Coast chemical processing corridors anchor regional demand concentration.
China
Injection molding scale economies for glass-reinforced polypropylene and PBT compounds compress pricing for consumer-grade hardware serving electrical routing applications. MIIT industrial standards and GB certification protocols govern fastener quality for domestic automotive and appliance manufacturing. Yangtze River Delta manufacturing clusters concentrate contract fabrication capacity for nylon wire harness management systems.
Japan
Automotive OEM engineering teams specify zero-defect protocols and PPAP documentation for integration into thermal system subassemblies. METI industrial policy and JIS standards certification sustain qualification barriers for foreign fastener suppliers. Nagoya automotive supplier networks and Osaka precision manufacturing districts anchor domestic production of constant-tension spring clamps.
India
PLI scheme incentives for capital goods manufacturing open specification windows for corrosion-resistant fastening in chemical process plant buildouts. BIS quality certification requirements and DGFT import regulations shape supplier qualification for domestic infrastructure projects. Gujarat and Maharashtra industrial corridors concentrate demand from petrochemical and pharmaceutical processing facilities.
Clamps Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated specification authority concentrates among German and Swiss engineering heritage firms serving automotive OEM channels, while fragmented commodity fabrication disperses across Chinese and Mexican contract manufacturers. Two strategic archetypes dominate: metallurgical premium-positioned specialists and scale-driven polymer injection molders. Competitive moves center on backward integration into stainless steel alloy supply and geographic expansion through distributor network consolidation.
Among Swiss and German heritage fabricators, Oetiker Group and Schaeffler AG occupy positions exemplifying metallurgical premium-tier specialization. Destaco anchors North American competitive presence through workholding and fastening solutions for automated assembly lines. These three companies represent contrasting archetypes: European metallurgical engineering lineage, diversified automotive supplier conglomerate structure, and focused industrial automation specialization.
| Leading Market Players |
|---|
| Oetiker Group |
| Destaco |
| Parker Hannifin |
| BorgWarner Inc. |
| Carr Lane Manufacturing Co. |
| Gates Corporation |
| Norma Group |
| Schaeffler AG |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
LME nickel contract volatility cascades through stainless steel feedstock tiers, compressing margin buffers for commodity-grade clamp fabricators while REACH-compliant alloy documentation commands premium positioning in European automotive procurement channels.
Pricing Analysis
Unbundled torque-limiting mechanisms and bundled vendor-managed inventory agreements split procurement economics across automotive OEM and maintenance provider channels. Three-tier pricing structure across premium corrosion-resistant metallurgy, standard 300-series stainless, and economy-grade carbon steel separates specification authority from price-driven replacement demand. Cost compression in commodity bands intensifies as Chinese injection molders scale glass-reinforced nylon 66 output for electrical routing applications. Fleet operators consolidating to single-source framework agreements exhibit lowest price sensitivity; construction contractors purchasing through wholesale distributors show highest.
Supply Chain Analysis
Container freight rate normalization and Red Sea routing disruptions have recalibrated landed cost calculations for European automotive tier suppliers sourcing precision bands from East Asian mills. Feedstock concentration centers on Indonesian nickel pig iron, Chinese ferrochrome, and German cold-rolled strip steel. Supply chains draw from Swiss precision stamping operations, Yangtze River Delta injection molding clusters, and Stuttgart-area metallurgical finishing facilities. Single-source vulnerability in certified duplex alloy supply threatens qualification continuity for offshore platform specifications. Distribution runs through direct OEM procurement platforms for high-volume automotive, distributor networks for construction, and integrated inventory management systems for fleet maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where battery electric vehicle thermal system redundancy shifts procurement weight toward corrosion-resistant metallurgy with documented alloy traceability.
For Market Incumbents: Deploy backward integration into certified stainless steel melt shop capacity to defend margin position against nickel price volatility and REACH documentation requirements. Consolidate specification authority through exclusive torque-limiting design licensing to automotive Tier 1 suppliers. Counter glass-filled nylon substitution threat by embedding real-time clamp torque monitoring sensors that polymer alternatives cannot replicate. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the most penetrable route for specialty clamp suppliers seeking bypass of entrenched automotive OEM qualification barriers. Target Indian chemical process plant buildouts under PLI scheme incentives where corrosion-resistant fastening specification windows remain open. Pursue additive manufacturing topology optimization for aerospace ducting applications as a differentiated entry vector. For Investors and Strategic Acquirers: Asymmetric upside sits with Swiss and German heritage fabricators possessing retiring metallurgical engineering cohorts and captive alloy documentation systems. Five-to-ten year viability hinges on transfer of stainless steel specification expertise to successor engineering talent. Watch hydrogen distribution infrastructure deployment signals as inflection indicator for 700-bar rated clamp demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Alloy Supply | Captive melt shop capacity secures REACH documentation continuity for European automotive qualification lists. |
| Direct-to-Fleet Digital Procurement Platform Launch | Bypasses entrenched distributor intermediaries in North American Class 8 trucking maintenance channels. |
| Additive Manufacturing Topology Optimization Program | Laser powder bed fusion enables lattice-structured bands for aerospace mass reduction specifications. |
| Hydrogen Infrastructure Fastening Certification | 700-bar rated clamp validation opens specification windows in emerging fueling network deployment. |
| Vendor-Managed Inventory System Integration | Predictive analytics lock in long-term framework agreements with industrial maintenance providers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, automotive platform engineers, aftermarket distribution heads, metallurgical engineering directors, and fleet maintenance operations managers with secondary validation against customs trade databases, SEC filings from diversified industrial conglomerates, automotive production registration data, and ECHA REACH substance notification records. Bottom-up clamp volume modeling triangulated against top-down thermal system content-per-vehicle estimates.
Segment-weighting applied differential growth assumptions across hose clamp, pipe clamp, spring clamp, and C-clamp product categories, with material tier splits between stainless steel, aluminum, and polymer compounds, and end-use weighting across automotive OEM, construction, electrical, and plumbing channels. CAGRs derived from regression analysis of historical procurement patterns and forward projection of EV thermal management system penetration curves. Forecast inputs incorporated nickel price volatility scenarios and hydrogen infrastructure deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal architectures would alter the outlook for redundant cooling loop specifications. Forecasts reflect documented assumptions around REACH enforcement intensity and automotive platform consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wood-Burning Tool Market
Tools
Cutting Tool Inserts Market
Tools
Jade Engraving Machines Market
Tools
Mechanical Hand Tools Market
Tools
Digital Laser Levels Market
Tools
Adjustable Gripping Hand Tools Market
Tools
US Power Tools Market
Tools
Hand Saw Market
Tools
Bandsaw Market
Tools
Metal Cutting Tools Market
Tools
Global Vertical Grinding Machine Market
Tools
Masonry Cleaners Market
Tools
Boring-Milling Machines Market
Tools
Global Swaging Machine Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Pneumatic Tools Market