
 Adoption of Benelux Power Tools Market | 2026-2036
Adoption of Benelux Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Adoption of Benelux Power Tools Market Analysis
Modular battery-platform bundling is realigning procurement patterns across commercial trade channels. Robert Bosch GmbH leverages its 18V ecosystem to anchor professional loyalty through cross-tool compatibility. Stanley Black & Decker, Inc. competes by extending battery interoperability across its DeWalt and Craftsman lines. Makita Corporation differentiates through sub-compact 12V platforms that occupy space-constrained renovation environments in Amsterdam and Brussels.
The adoption of Benelux power tools encompasses electrically driven and manually operated mechanical devices rated typically from 12V to 36V for cordless units and 110V to 230V for corded equivalents, engineered for material removal, fastening, cutting, and surface finishing across construction and industrial maintenance workflows. Cordless tools lead volume traction as lithium-ion cell energy density improvements enable runtime parity with corded alternatives in medium-duty applications. DIY Enthusiasts represent the fastest-expanding end-user category as home improvement centers expand private-label battery-platform offerings. Specialty Stores retain margin concentration through technician-grade diagnostic services and warranty-handling capabilities that online retail cannot replicate.
The EU F-Gas Regulation and REACH compliance frameworks administered by ECHA shape product material specifications and thermal process equipment standards across Belgium, the Netherlands, and Luxembourg. CE marking requirements under the EU Machinery Directive govern noise emission limits and vibration exposure thresholds that manufacturers must certify before market placement. National implementations through the Dutch Rijksdienst voor Ondernemend Nederland and Belgian Federal Public Service Economy enforce conformity assessment procedures at port-of-entry inspection points. Stakeholders must monitor evolving battery transport classification under ADR agreements and prepare chemistry disclosure documentation ahead of anticipated EU Battery Regulation delegated acts.
Market Dynamics
Modular battery-platform ecosystems are restructuring procurement loyalty across Belgian, Dutch, and Luxembourg construction channels, as contractors consolidate vendor relationships around interoperable cordless systems that reduce fleet complexity and spare-part inventory.
Growth Catalysts
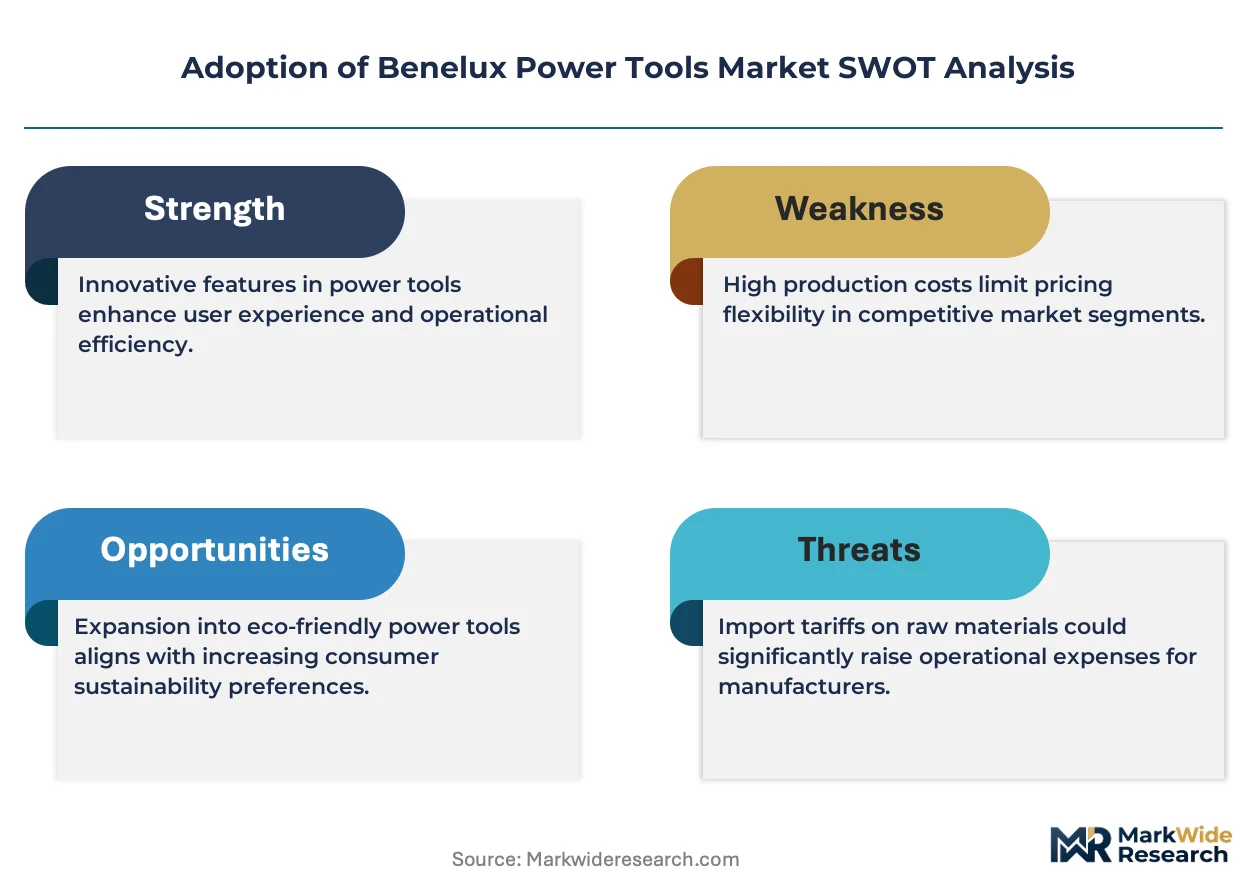
- EU F-Gas Regulation phase-down:The progressive reduction of hydrofluorocarbon availability in thermal processes is accelerating contractor migration from gas-powered to battery-electric equipment across Benelux metalworking and HVAC installation trades.
- Brushless motor adoption:Permanent magnet motor technology is extending tool lifespan and runtime in high-frequency fastening applications, particularly among Dutch residential renovation crews operating in dense urban environments.
- Belgian construction permit volumes:Residential and light commercial building approvals in Flanders and Wallonia are channeling demand toward compact, multi-function drill-driver combinations for framing and finishing work.
Market Restraints
- Lithium-cell raw material concentration:Cathode active material supply chains concentrate in East Asian refining capacity, exposing Benelux distributors to price volatility and logistics bottlenecks for high-nickel battery packs.
- REACH substance restrictions:ECHA candidate list updates on cobalt compounds and nickel salts are forcing reformulation of battery electrode chemistries, extending product recertification timelines.
- Manual tool substitution:Low-cost hand tools retain cost advantage in occasional-use DIY segments, limiting cordless premiumization in Luxembourg's smaller household market.
Strategic Opportunities
- Wallonia industrial maintenance:Belgium's southern region hosts concentrated automotive and aerospace manufacturing facilities with underpenetrated predictive maintenance tool fleets.
- EU Battery Regulation delegated acts:Anticipated carbon footprint disclosure and recycled content mandates will reward early movers with established supply chain documentation systems.
- Tool-as-a-service platforms:Subscription-based fleet management is emerging among Dutch mid-size contractors seeking to convert capital expenditure into operational expenditure.
Industry Challenges
- Battery transport classification complexity:ADR agreement updates on lithium-ion cell shipping categories are forcing distributors to reconfigure warehouse segregation and documentation workflows.
- Technician certification gaps:Brushless motor diagnostics and battery management system troubleshooting require training programs that vocational institutions in the Netherlands and Belgium are only beginning to standardize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adoption of Benelux Power Tools Market |
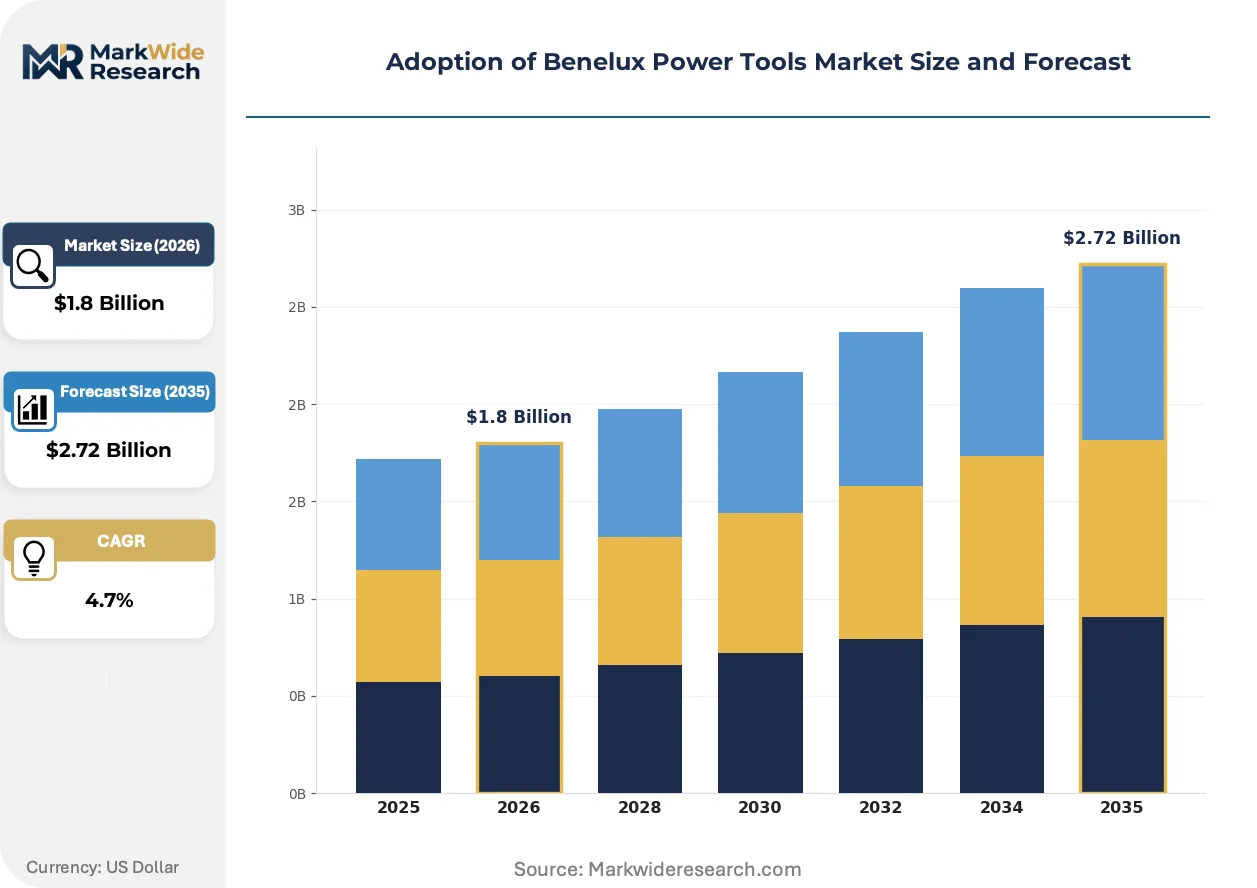
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded Tools, Cordless Tools, Handheld Tools, Stationary Tools End User: Construction, Manufacturing, DIY Enthusiasts, Maintenance Services Application: Woodworking, Metalworking, Renovation, Automotive Repair Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Home Improvement Centers |
| Companies Covered | Robert Bosch GmbH, Stanley Black & Decker, Inc., Makita Corporation, Hilti Corporation, Festool GmbH, Techtronic Industries, Atlas Copco AB, Snap-on Incorporated, Koki Holdings Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adoption of Benelux Power Tools Market Emerging Trajectories
Three intersecting developments are compressing product lifecycles and rewiring channel economics across the Benelux power tools sector: chemistry transitions in energy storage, tightening substance regulations, and evolving procurement behaviors among professional end-users.
Lithium-iron-phosphate cell chemistry is overtaking nickel-manganese-cobalt configurations in medium-duty cordless tools, offering thermal stability advantages for continuous runtime applications. Dutch renovation contractors are adopting these platforms for all-day flooring and decking installations without battery swap interruptions. This chemistry shift is enabling smaller OEMs to enter the market without legacy nickel supply chain dependencies.
The EU F-Gas Regulation and its national implementations through the Dutch Rijksdienst voor Ondernemend Nederland and Belgian Federal Public Service Economy are prohibiting refrigerant-based thermal processes in new equipment categories. Tool manufacturers serving HVAC installation trades are redesigning copper tube cutters and flaring tools for battery-electric operation. Belgium's port-of-entry inspection points are enforcing conformity assessment documentation that delays non-compliant product introductions.
Specialty retailers are unbundling after-sales service from product margins, charging separately for diagnostic testing and warranty claim processing that online channels cannot replicate. This service stratification is concentrating high-value transactions in physical storefronts across Amsterdam and Brussels while commodity cordless kits migrate to digital marketplaces. Dutch home improvement centers are responding by expanding in-store battery-platform demonstration zones staffed with certified technicians.
Adoption of Benelux Power Tools Market Segmentation
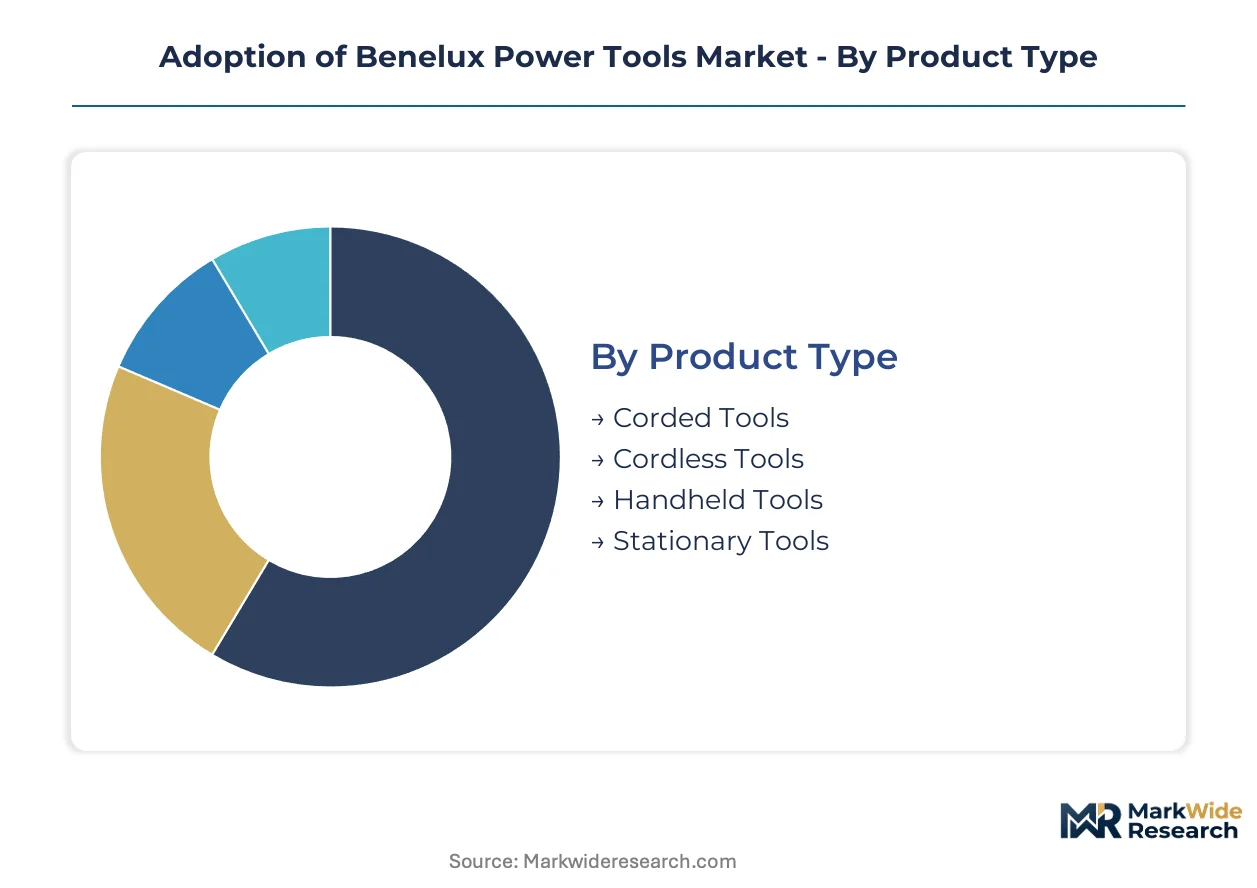
Power tool procurement patterns across Belgium, the Netherlands, and Luxembourg fragment sharply by power source, end-use intensity, and channel service requirements. Understanding these divides reveals where battery-platform consolidation and regulatory compliance costs concentrate margin pressure.
Product Type:
Standalone cordless systems dominate contractor fleets, while corded and stationary tools retain embedded positions in fixed industrial workflows.
- Cordless Tools:Battery-electric platforms from 12V to 36V leverage lithium-iron-phosphate cell chemistry for thermal stability during continuous Dutch flooring installations. Rotterdam and Amsterdam renovation crews prioritize these for mobility in dense urban job sites where generator access is restricted.
- Corded Tools:Mains-powered units from 110V to 230V sustain peak torque output in Belgian metalworking shops where uninterrupted runtime outweighs portability needs. Wallonia automotive suppliers specify these for production-line fastening stations.
- Handheld Tools:Manual mechanical devices serve occasional-use DIY segments in Luxembourg's smaller household market where battery investment cannot be amortized.
- Stationary Tools:Bench-mounted saws and drill presses anchor woodworking operations in Flanders craft workshops with dedicated electrical infrastructure.
Cordless tools lead volumes today; stationary tools are gaining share fastest in industrial maintenance retrofits.
End User:
Cost tier stratification separates capital-intensive fleet operators from price-sensitive intermittent users.
- Construction:Belgian, Dutch, and Luxembourg contractors consolidate procurement around interoperable 18V battery platforms to reduce spare-part inventory complexity across multi-trade crews.
- DIY Enthusiasts:Home improvement centers in the Netherlands target this expanding category with private-label battery-platform bundles and in-store demonstration zones staffed by certified technicians.
- Manufacturing:Wallonia automotive and aerospace facilities deploy predictive maintenance tool fleets with brushless motor diagnostics requiring specialized technician certification.
- Maintenance Services:HVAC installation trades across Benelux convert to battery-electric copper tube cutters as EU F-Gas Regulation phases down refrigerant-based thermal processes.
Construction leads volumes today; DIY Enthusiasts are expanding most quickly through retail channel penetration.
Application:
Volume concentration varies by material removal intensity and regulatory exposure across the three countries.
- Renovation:Dutch residential activity drives demand for compact brushless-motor drill and impact-driver combinations in Amsterdam and Brussels space-constrained environments.
- Woodworking:Framing and finishing work in Flanders channels procurement toward multi-function drill-driver systems specified in Belgian construction permit approvals.
- Metalworking:East Asian cathode active material supply chain dependencies expose Benelux distributors to price volatility for high-nickel battery packs used in heavy-duty cutting applications.
- Automotive Repair:REACH substance restrictions on cobalt compounds and nickel salts force battery electrode reformulation, extending recertification timelines for garage equipment.
Renovation leads volumes today; automotive repair is climbing the fastest as electric vehicle service requirements multiply.
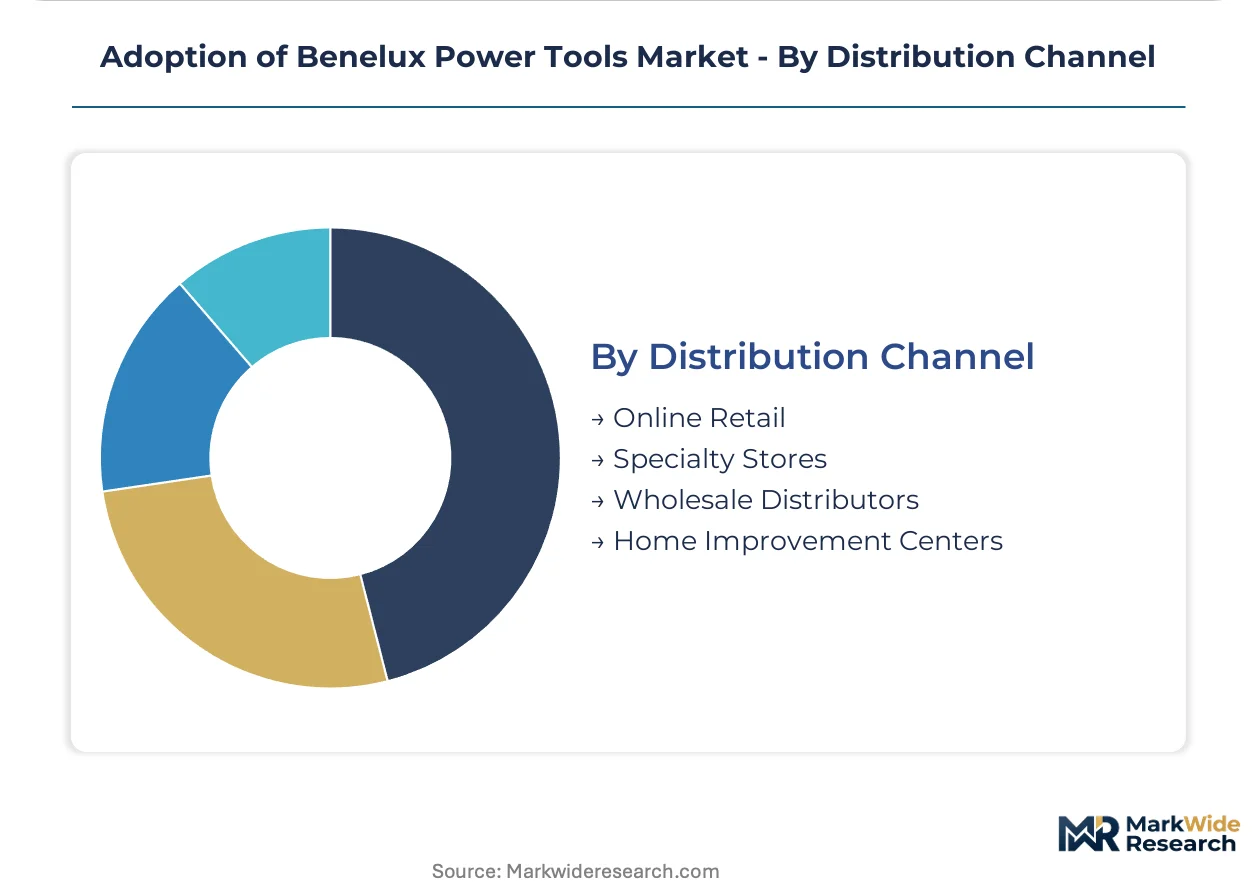
Distribution Channel:
Margin capture separates service-embedded physical retail from commodity digital transactions.
- Specialty Stores:Amsterdam and Brussels storefronts unbundle after-sales service from product margins, charging separately for diagnostic testing and warranty claim processing that online channels cannot replicate.
- Online Retail:Digital marketplaces concentrate commodity cordless kit transactions where price transparency erodes distributor margins.
- Home Improvement Centers:Dutch retailers expand in-store battery-platform demonstration zones to defend high-value transactions against pure-play e-commerce.
- Wholesale Distributors:ADR agreement updates on lithium-ion cell shipping categories force reconfiguration of warehouse segregation and documentation workflows at port-of-entry inspection points.
Specialty stores lead volumes today; home improvement centers are gaining share fastest through technician-staffed experiential retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power tool manufacturing first industrialized in Germany during the early twentieth century, with subsequent scaling across Western Europe establishing the technical foundations that now define Benelux procurement standards and regulatory alignment.
Belgium
Flemish construction permit approvals drive demand for compact drill-driver combinations in residential framing and finishing work. The Federal Public Service Economy enforces CE marking conformity assessments at Antwerp and Zeebrugge port-of-entry inspection points. Wallonia's automotive and aerospace manufacturing corridor around Charleroi hosts underpenetrated predictive maintenance tool fleets requiring brushless motor diagnostics.
Netherlands
Amsterdam and Rotterdam renovation crews prioritize lithium-iron-phosphate cordless platforms for mobility in dense urban job sites with restricted generator access. The Rijksdienst voor Ondernemend Nederland administers national implementations of EU F-Gas Regulation phase-down schedules. Dutch home improvement centers in the Randstad expand in-store battery-platform demonstration zones staffed by certified technicians to defend high-value transactions.
Luxembourg
Smaller household market scale limits cordless premiumization as low-cost hand tools retain cost advantage in occasional-use DIY segments. National regulators align with ECHA REACH compliance frameworks governing cobalt compound and nickel salt restrictions in battery electrode chemistries. Cross-border procurement from Belgian and Dutch distributors concentrates tool supply through wholesale channels serving the Grand Duchy's compact geography.
Adoption of Benelux Power Tools Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with established battery-platform ecosystems. Vendor concentration remains moderate, with professional-grade loyalty anchored through cross-tool interoperability rather than pure market share dominance. Three archetypes define positioning: integrated battery-platform owners, specialized brushless-motor technicians, and private-label mass-market suppliers. Consolidation activity centers on portfolio diversification into adjacent fastening and cutting categories, while geographic expansion targets underpenetrated industrial maintenance corridors.
Within the integrated battery-platform tier, Robert Bosch GmbH and Stanley Black & Decker, Inc. occupy positions exemplifying ecosystem lock-in strategies. Makita Corporation represents the compact-platform specialization archetype, with sub-18V configurations targeting space-constrained renovation environments. These three anchors demonstrate how interoperability investments and chemistry transitions reshape procurement loyalty across Belgian, Dutch, and Luxembourg construction channels.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black & Decker, Inc. |
| Makita Corporation |
| Hilti Corporation |
| Festool GmbH |
| Techtronic Industries |
| Atlas Copco AB |
| Snap-on Incorporated |
| Koki Holdings Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Battery-platform certification tiers split procurement budgets between professional-grade interoperability premiums and private-label commodity bundles. Dutch contractors pay markups for cross-tool compatibility that reduces fleet complexity, while Luxembourg DIY buyers select entry-level cordless kits where battery investment cannot be amortized across occasional use. This tier divergence channels margin capture toward service-embedded specialty retailers in Amsterdam and Brussels, while price-transparent online marketplaces erode distributor returns on standardized cordless combinations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Benelux power tool transactions. CE marking tier and battery-platform interoperability drive price differentiation, with brushless-motor diagnostics commanding technician-grade premiums. Pricing pressure stems from East Asian cathode active material volatility transmitting into high-nickel battery pack costs. DIY Enthusiasts exhibit highest price sensitivity, while Wallonia automotive maintenance fleets accept premium positioning for predictive tool diagnostics.
Supply Chain Analysis
Lithium-iron-phosphate cell supply rests on Chinese and South Korean cathode refiners with emerging European production scale-up. Cobalt compound and nickel salt dependencies feed from Central African mining corridors and Indonesian nickel processing. Single-source vulnerability concentrates in East Asian battery management system semiconductor fabrication. Distribution runs through Antwerp and Rotterdam port-of-entry inspection points with ADR-classified warehouse segregation for lithium-ion cell storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Benelux power tools market compounds steadily as EU F-Gas Regulation phase-down mandates permanent equipment replacement cycles across HVAC and metalworking trades. This regulatory forcing function sustains replacement demand regardless of construction cycle volatility.
For Market Incumbents: Hedge chemistry transition risk by diversifying electrode supplier relationships beyond high-nickel configurations toward lithium-iron-phosphate qualified sources. Secure backward integration into battery pack assembly within the EU to preempt carbon footprint disclosure requirements under anticipated EU Battery Regulation delegated acts. Anchor professional loyalty through expanded cross-tool compatibility within existing 18V ecosystems rather than fragmenting procurement with incompatible voltage introductions. For New Entrants and Emerging Players: Begin with Wallonia predictive maintenance tool fleets where incumbent presence remains underdeveloped around Charleroi automotive and aerospace corridors. Target subscription-based tool-as-a-service platforms among Dutch mid-size contractors seeking operational expenditure conversion. Lead go-to-market through certified technician staffing partnerships with specialty retailers unbundling diagnostic services from product margins. For Investors and Strategic Acquirers: Consolidation pressure builds where battery-platform ecosystem gaps fragment contractor procurement loyalty across interoperable system boundaries. Frame long-term viability around chemistry-agnostic platform owners capable of absorbing electrode reformulation costs without customer disruption. Watch for EU Battery Regulation enforcement timing as inflection signal determining which distributors possess pre-positioned supply chain documentation systems versus compliance laggards facing port-of-entry delays.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Transition | Lithium-iron-phosphate adoption reduces thermal runaway risk for Dutch all-day flooring crews. |
| Platform Interoperability Expansion | Cross-tool compatibility within 18V ecosystems anchors contractor procurement consolidation. |
| Service Unbundling | Separate diagnostic pricing defends specialty retailer margins against online commodity erosion. |
| Regulatory Pre-Positioning | Carbon footprint documentation systems reward early movers under EU Battery Regulation. |
| Tool-as-a-Service Launch | Subscription fleet management converts capital expenditure for Dutch mid-size contractors. |
Methodological Framework
Bottom-up contractor fleet modeling reconciled against top-down battery-platform shipment tracking forms the analytical core. Primary interviews with maintenance directors at Wallonia automotive suppliers, procurement leads at Dutch home improvement centers, aftermarket service heads at Benelux distributors, and OEM platform engineers at power tool manufacturers combined with secondary validation from EU F-Gas Regulation implementation schedules, ECHA REACH candidate list updates, Belgian Federal Public Service Economy conformity assessment records, and Dutch Rijksdienst voor Ondernemend Nederland enforcement data. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped lithium-ion cell energy density improvements to runtime parity thresholds, brushless motor adoption curves to replacement cycle compression, and regulatory phase-down schedules to equipment migration timelines. Segmentation dimensions modeled include power source voltage tier, end-use intensity classification, distribution channel service embedding, and regional construction permit velocity. CAGRs derived from fitted trend extrapolation with scenario-weighted regulatory enforcement assumptions. Industry-specific forecast inputs incorporated ADR agreement revision timing and vocational certification program rollout pace.
Several conditions sit outside the modeled scope, including unannounced EU Battery Regulation delegated act publication dates, lithium-cell raw material price spike magnitudes beyond historical bands, and disruptive solid-state battery commercialization timelines. Forecasts reflect assumptions about regulatory enforcement consistency and chemistry transition cost pass-through elasticity. A small set of named triggers warrants ongoing watch: ECHA substance restriction list expansions affecting electrode materials, Antwerp port inspection capacity constraints, and Dutch vocational curriculum standardization completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Striking Tools Market
Tools
Woodworking Circular Saw Blades Market
Tools
Power Tool Accessories Market
Tools
Construction Nails Market
Tools
Wood Floor Grinding Machine Market
Tools
Clamps Market
Tools
Tapping Machine Market
Tools
Industrial Ladder Market
Tools
Global Staple Gun Market
Tools
Diamond Hole Saw Market
Tools
Portable Rolling Toolbox Market
Tools
Wood-Burning Tool Market
Tools
Telescopic Tool Boxes Market
Tools
Surface Levelling Equipment Market
Tools
Concrete Saw Market
Tools
Coil Thread Insert Market