
 Concrete Spreader Market | 2026-2036
Concrete Spreader Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Spreader Market Analytics
Commercial infrastructure contractors are unwinding their historical reliance on generalist rental fleets and shifting toward owned specialized equipment. Putzmeister leverages its deep hydraulic engineering heritage to anchor premium positioning in European highway projects. GOMACO Corporation dominates the North American slipform paving segment where precision spreading integrates with continuous paving workflows. XCMG Group extends its cost-engineered manufacturing scale across emerging Asian road networks.
A concrete spreader is a mechanized distribution device engineered to deposit, level, and screed fresh concrete across horizontal surfaces at specified thicknesses, typically operating with adjustable blade spans of 2.5 to 12 meters and vibration frequencies between 3,000 and 6,000 RPM to achieve specified surface regularity. The equipment serves primary industrial purposes in bridge decks, airport runways, and warehouse floor slabs where manual placement cannot achieve tolerance requirements. Hydraulic spreaders command the largest installed base due to their power density and reliability in continuous-duty environments, while electric spreaders represent the fastest-expanding category as battery energy density improves and job site emissions rules tighten. Trailer-mounted configurations concentrate margin pools in the heavy-duty size class where transportability between dispersed infrastructure sites reduces mobilization costs for regional contractors.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine downsizing or electrification in diesel-hydraulic spreaders, reshaping supplier R&D priorities and component sourcing. OSHA silica exposure limits and ISO 16001 energy management standards further constrain equipment design, pushing manufacturers toward enclosed operator cabs and regenerative hydraulic systems. Stakeholders must monitor how rapidly battery-electric spreaders achieve parity in runtime and torque output against established hydraulic platforms.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing the development timeline for battery-electric spreader platforms while hydraulic engineering expertise becomes a scarcer competitive moat.
Growth Catalysts
- Highway modernization programs:Germany's Federal Transport Infrastructure Plan and China's National Highway Network upgrades sustain fleet procurement for slipform paving contractors.
- OSHA silica exposure limits:Tighter workplace safety standards in the United States mandate enclosed operator cabs with HEPA filtration, accelerating equipment replacement cycles.
- Battery energy density improvements:Lithium-iron-phosphate cell chemistry advances enable electric spreaders to achieve runtime parity with diesel-hydraulic units in continuous-duty bridge deck applications.
Market Restraints
- Steel and hydraulic component cost volatility:Fluctuations in high-grade alloy prices compress margin pools for mid-tier equipment manufacturers dependent on outsourced casting.
- Precision gearbox supplier concentration:German and Japanese precision gear manufacturers control critical transmission supply, exposing spreader OEMs to extended lead times.
- Electric platform torque limitations:Battery-electric drivetrains currently underperform hydraulic systems in high-torque cold-start conditions required for high-viscosity concrete mixes.
Strategic Opportunities
- Urban renewal corridors in India:Smart Cities Mission infrastructure spending creates first-mover advantage for trailer-mounted spreader suppliers establishing local assembly.
- Airport runway resurfacing cycles:FAA-mandated pavement condition index thresholds in the United States drive specialized equipment demand for 24-hour continuous paving operations.
- EU Green Deal construction equipment incentives:Member-state subsidies for zero-emission machinery reduce total cost of ownership gaps for electric spreader adopters.
Industry Challenges
- Mechatronics technician scarcity:Integration of electric drivetrains with legacy hydraulic screed controls demands cross-trained service personnel unavailable in regional contractor networks.
- ISO 16001 energy management certification timelines:Documentation requirements for regenerative hydraulic systems extend product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Spreader Market |
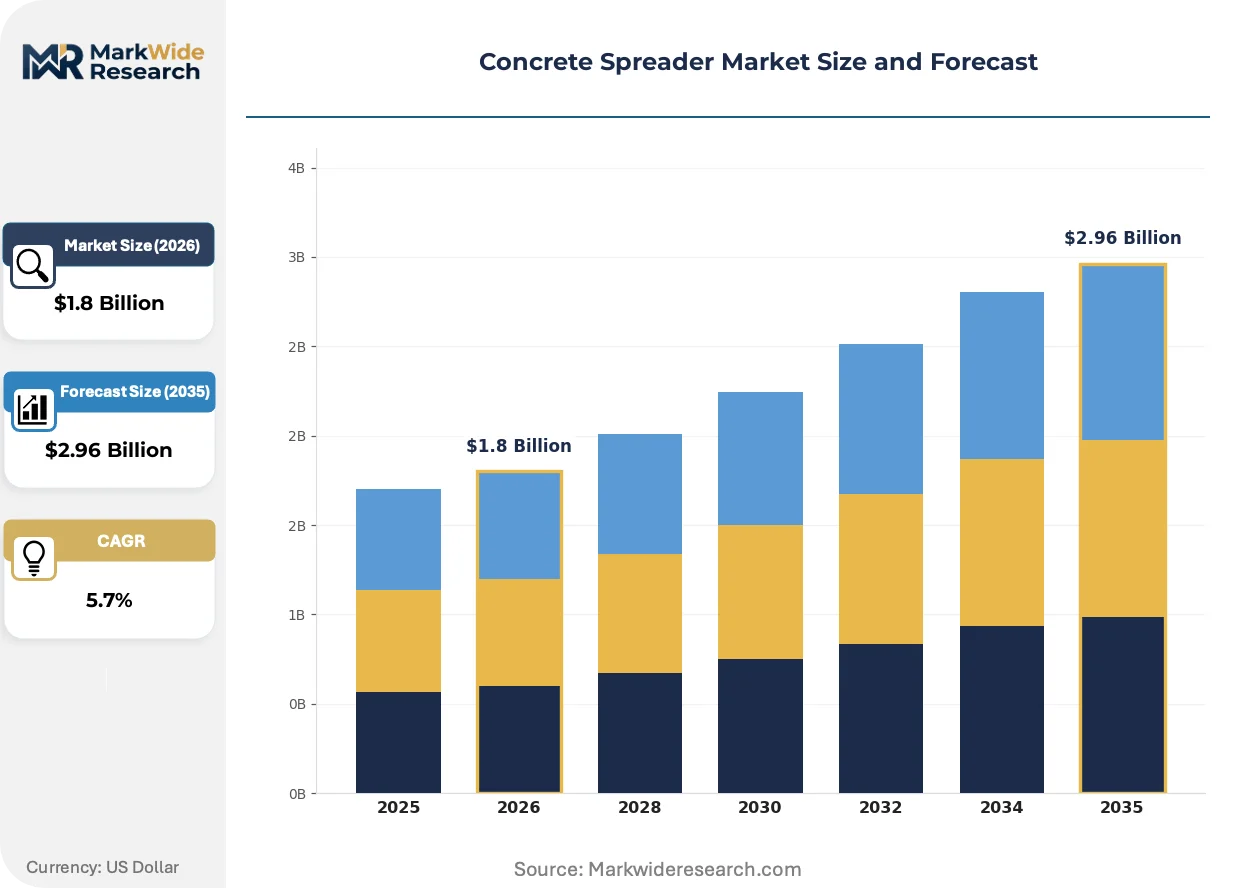
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Spreaders, Electric Spreaders, Hydraulic Spreaders, Trailer-Mounted Spreaders End User: Construction Companies, Contractors, Manufacturers, DIY Enthusiasts Size: Small, Medium, Large, Heavy-Duty Feature: Adjustable Width, High Capacity, Lightweight Design, Durable Materials |
| Companies Covered | GOMACO Corporation, Putzmeister, Wirtgen Group, SCHWING Stetter India, XCMG Group, Caterpillar, Ammann Group, CMI Roadbuilding Inc., SANY Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Spreader Market Evolving Landscape
Electrification is rewriting equipment architecture while regulatory compliance costs reshape supplier economics and contractor ownership models.
Telematics-integrated spreader control systems is supplanting manual depth-adjustment mechanisms on highway paving fleets. State transportation departments in the United States now mandate real-time density logging for federal reimbursement eligibility. This connectivity layer is compressing warranty liability onto OEMs while creating recurring software revenue streams.
REACH substance restrictions on hydraulic fluids are forcing European manufacturers to reformulate seal materials and migrate to bio-based synthetic alternatives. The compliance burden falls heaviest on rental fleet operators maintaining mixed-vintage equipment pools. German contractors are responding by consolidating supplier relationships to simplify fluid inventory management.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized commercial infrastructure firms. Monthly utilization-based payments bundle maintenance, telematics, and upgrade rights. This shift is most visible in the United States where contractor balance sheet constraints meet investor-backed fleet financing vehicles.
Concrete Spreader Market Segmentation
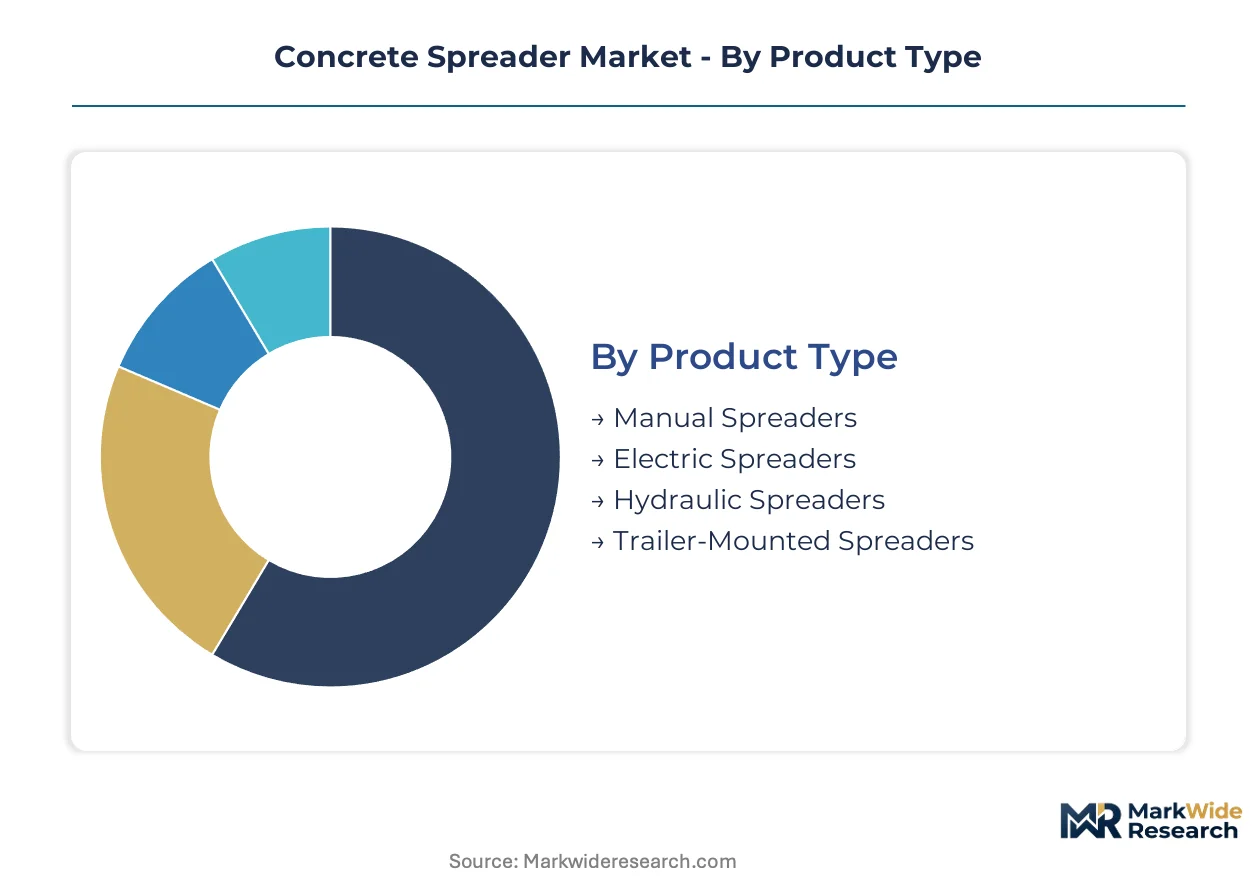
Concrete spreader procurement patterns diverge sharply across equipment configurations and operator profiles. Segmentation reveals where electrification pressure concentrates and which customer tiers drive replacement cycles.
Product Type:
Hydraulic spreaders face the most acute substitution pressure as battery-electric platforms achieve runtime parity in continuous-duty applications.
- Hydraulic Spreaders:Diesel-hydraulic powertrains deliver torque density essential for high-viscosity concrete distribution across bridge decks and airport runways. EPA Tier 4 Final compliance costs are compressing margin pools for regional OEMs dependent on outsourced engine sourcing.
- Electric Spreaders:Lithium-iron-phosphate battery packs now enable 8-hour continuous operation matching hydraulic runtime in standard slump conditions. Demand concentrates in Germany and California where job site emissions rules and EU Green Deal subsidies accelerate fleet conversion.
- Trailer-Mounted Spreaders:Transportable configurations reduce mobilization costs for contractors operating across dispersed highway segments.
- Manual Spreaders:Hand-operated units persist in small-scale residential flatwork where equipment capital constraints outweigh productivity tradeoffs.
Hydraulic spreaders anchor the volume base while electric spreaders gain share at the steepest rate.
End User:
Customer scale determines equipment ownership models, with capital availability separating rental-dependent tiers from integrated fleet operators.
- Construction Companies:National infrastructure contractors maintain owned fleets of 50-plus units with integrated telematics for federal reimbursement compliance. Balance sheet capacity supports equipment-as-a-service transitions bundling maintenance and upgrade rights.
- Contractors:Regional slipform paving specialists concentrate procurement in trailer-mounted hydraulic units for highway mobility. OSHA silica exposure limits are accelerating cab-enclosure replacement cycles among this tier.
- Manufacturers:Precast concrete producers utilize fixed-mount spreaders integrated with automated batching systems.
- DIY Enthusiasts:Residential owner-operators represent minimal equipment revenue, primarily sourcing manual or small electric units through retail channels.
Construction companies dominate absolute unit demand while contractors generate the highest replacement velocity.
Size:
Blade span specifications align with project scale, with width-adjustable platforms capturing cross-segment flexibility premiums.
- Large:8-to-12-meter blade spans serve airport runway and highway paving where continuous operation demands justify capital intensity.
- Heavy-Duty:Reinforced frames and high-torque drivetrains handle high-viscosity mixes in cold-climate bridge deck applications.
- Medium:4-to-8-meter configurations balance productivity with transportability for urban renewal corridors.
- Small:Compact units under 4 meters address warehouse floor slabs and residential flatwork with limited access.
Large spreaders concentrate revenue per unit while medium configurations expand most quickly into municipal infrastructure programs.
Feature:
Specification bundles separate premium fleet positioning from cost-optimized procurement, with durability claims requiring ISO 16001 certification documentation.
- Adjustable Width:Telescoping blade mechanisms enable single-unit deployment across variable pour specifications, reducing fleet size requirements for regional contractors.
- Durable Materials:High-grade alloy construction extends service intervals in abrasive aggregate environments.
- High Capacity:Extended hopper volumes support uninterrupted feeding from ready-mix delivery cycles.
- Lightweight Design:Aluminum structural components reduce transport weight for trailer-mounted configurations.
Adjustable width features command specification premiums while durable materials drive replacement timing in high-wear applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure contractors in the United States, Germany, and China concentrate the heaviest procurement volumes for hydraulic and electric spreader platforms. These three markets anchor fleet investment decisions through federal highway programs, emissions transition mandates, and urban renewal corridors.
United States
FAA-mandated runway resurfacing cycles and state transportation department density-logging requirements drive specialized equipment demand. OSHA silica exposure limits accelerate enclosed-cab replacement cycles among regional slipform paving contractors. Texas and California highway modernization programs sustain trailer-mounted spreader procurement across dispersed infrastructure corridors.
Germany
The Federal Transport Infrastructure Plan funds continuous paving operations requiring precision spreading integration. EU Stage V emissions frameworks and REACH substance restrictions on hydraulic fluids compel equipment reformulation and supplier consolidation. Bavarian and North Rhine-Westphalian contractors lead fleet conversion toward battery-electric platforms supported by EU Green Deal subsidies.
China
National Highway Network upgrades and Smart Cities Mission infrastructure spending sustain heavy-duty spreader procurement across provincial road networks. MIIT dual carbon goals and GB standards for construction equipment emissions accelerate electric platform development. Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate domestic OEM assembly capacity for cost-engineered units.
India
Smart Cities Mission urban renewal corridors create first-mover opportunities for trailer-mounted spreader suppliers establishing local assembly. BIS certification requirements and PLI scheme incentives for construction equipment manufacturing reshape import-dependent supply structures. Maharashtra and Gujarat infrastructure contractors drive demand for medium-size adjustable-width configurations in municipal road programs.
United Arab Emirates
Airport expansion projects and logistics corridor development sustain premium heavy-duty spreader procurement for 24-hour continuous paving. MOHAP workplace safety alignments with international silica exposure standards mandate cab-enclosure specifications. Dubai and Abu Dhabi construction conglomerates concentrate fleet investments in large blade-span units for runway and highway applications.
Concrete Spreader Market Competitive Landscape
Player mix skews toward diversified industrial equipment conglomerates with construction machinery divisions alongside specialized road-building equipment fabricators. Market structure exhibits tiered consolidation with premium hydraulic engineering specialists, scale-driven cost-optimized manufacturers, and regional rental fleet service providers occupying distinct competitive bands. Dominant competitive moves include strategic partnerships for electric drivetrain sourcing and geographic expansion through local assembly joint ventures in high-growth corridors.
Within the premium hydraulic engineering tier, Putzmeister and GOMACO Corporation exemplify specialized positioning anchored in continuous paving workflow integration. XCMG Group occupies a scale-driven archetype with cost-engineered manufacturing concentration serving emerging Asian road networks. Among diversified industrial conglomerates, Caterpillar and SANY Group represent construction machinery divisions where concrete spreader portfolios sit within broader road-building equipment ecosystems.
| Leading Market Players |
|---|
| GOMACO Corporation |
| Putzmeister |
| Wirtgen Group |
| SCHWING Stetter India |
| XCMG Group |
| Caterpillar |
| Ammann Group |
| CMI Roadbuilding Inc. |
| SANY Group |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 85% at German and Japanese precision gearbox foundries create dual pressure: OEMs face extended lead times that compress working capital, while regional contractors absorb transport-cost premiums that reset price floors for trailer-mounted configurations. This scale asymmetry rewards integrated fleet operators with volume-locked contracts while squeezing mid-tier rental-dependent tiers.
Pricing Analysis
Cost-plus contracts with steel indexation dominate procurement between mid-sized contractors and regional OEMs, insulating suppliers from alloy volatility while transferring margin risk to buyers. Three-tier pricing structure across premium, standard, and economy levels separates EPA Tier 4 Final-certified hydraulic platforms from basic trailer-mounted units and manual alternatives. Price differentiation rests on ISO 16001 energy management certification and telematics integration depth. Cost compression in the standard tier is intensifying because outsourced casting dependencies expose regional manufacturers to alloy spot-price swings. DIY enthusiasts and small residential contractors exhibit highest price sensitivity, while national infrastructure firms with equipment-as-a-service contracts demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of high-grade alloy castings and hydraulic seal inventories prevails among premium OEMs, whereas just-in-time procurement dominates mid-tier assemblers dependent on outsourced components. Component sourcing concentrates in Germany, Japan, and China, with precision gearboxes drawing from German and Japanese suppliers and structural frames feeding from Chinese manufacturing clusters. Raw material dependencies span high-grade steel alloys, synthetic hydraulic fluids, and lithium-iron-phosphate cells for electric platforms. Single-source vulnerability in precision transmission supply exposes spreader OEMs to 6-12 month lead time extensions. Distribution runs through manufacturer-direct channels for large fleet sales and specialized equipment distributors serving regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete spreader market operates as a defensive-moat industry where regulatory entrenchment—EPA Tier 4 Final, EU Stage V, OSHA silica limits—creates certification barriers that protect incumbent positions while raising capital requirements for new entrants.
For Market Incumbents: Shield market position by deepening captive supply of precision gearboxes through backward integration into German or Japanese transmission specialists, insulating against supplier-concentration risk. Accelerate ISO 16001 certification documentation to compress product launch timelines and capture replacement cycles driven by EU Green Deal subsidies. Prioritize R&D in regenerative hydraulic systems to defend premium positioning against battery-electric substitution pressure. For New Entrants and Emerging Players: EPA Tier 4 Final certification fast-track partnerships with established engine suppliers offer the most viable entry path for electric platform specialists lacking hydraulic legacy. White-space concentrates in India's Smart Cities Mission corridors, where trailer-mounted spreader demand outpaces local assembly capacity. Target municipal infrastructure contractors in Maharashtra and Gujarat with medium-size adjustable-width configurations. Go-to-market angle: equipment-as-a-service contracting bundles that match balance-sheet constraints of mid-tier regional pavers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified industrial conglomerates with construction machinery divisions over pure-play road equipment fabricators, given electrification capex requirements and software-integrated control system development. Long-term viability across the projection horizon hinges on telematics platform ownership and recurring software revenue streams. Acquisition target archetype: specialized slipform paving equipment fabricators with integrated highway workflow expertise. Signal to watch: battery-electric spreader runtime parity announcements in high-torque cold-start conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Development | EPA Tier 4 Final compliance costs and EU Green Deal subsidies accelerate battery-electric R&D prioritization. |
| Precision Gearbox Backward Integration | German and Japanese transmission supplier concentration creates acquisition rationale for captive supply security. |
| Telematics Platform Integration | State transportation department density-logging mandates compress warranty liability onto OEMs with connectivity layers. |
| Local Assembly Joint Ventures | India's Smart Cities Mission and PLI scheme incentives reward first-mover trailer-mounted spreader assembly capacity. |
| Equipment-as-a-Service Contracting | Contractor balance sheet constraints meet investor-backed fleet financing vehicles in the United States market. |
Research Methodology
A standing panel of highway paving contractors, fleet maintenance directors, OEM procurement managers, and telematics platform engineers provided ongoing calibration across the study period. Primary interviews with slipform paving specialists and regional equipment distributors were cross-validated against secondary sources including EPA engine certification databases, EU Stage V compliance filings, and state transportation department procurement records. Bottom-up unit demand modeling was triangulated with top-down infrastructure spending allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled demand by product type (hydraulic, electric, trailer-mounted, manual), end user (construction companies, contractors, manufacturers), size class (large, heavy-duty, medium, small), and feature configuration (adjustable width, durable materials, high capacity, lightweight design). CAGRs were derived from infrastructure spending trajectories, emissions regulation phase-in schedules, and battery energy density improvement curves. Industry-specific inputs included FAA runway resurfacing cycle timing and EU Green Deal subsidy uptake rates.
Underlying assumptions cover highway modernization program continuity, battery runtime parity achievement, and precision gearbox supply stability, with deviation risk concentrated in electric platform torque performance in cold-start conditions and alloy price volatility. Forecasts reflect these documented assumptions with explicit sensitivity ranges. Revision becomes warranted when battery-electric spreader cold-start performance crosses hydraulic parity thresholds or when precision gearbox lead times exceed 18 months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Press Fit Machines Market